
 Specialty Nitrile Butadiene Rubber (NBR) Market | 2026-2036
Specialty Nitrile Butadiene Rubber (NBR) Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Nitrile Butadiene Rubber (NBR) Market Analytics
Southeast Asia's petrochemical expansion is reshaping raw material availability for specialty NBR producers. ARLANXEO leverages its integrated butadiene supply chain to secure feedstock cost advantages across European and Asian plants. ZEON Corporation dominates high-purity grades for semiconductor seals, while JSR Corporation specializes in hydrogenated variants for extreme temperature applications. Kumho Petrochemical anchors Korean domestic supply for automotive hose compounds.
Specialty Nitrile Butadiene Rubber is a synthetic copolymer of butadiene and acrylonitrile, typically containing 18-50% acrylonitrile by weight, produced through emulsion or solution polymerization to deliver tailored oil resistance, elasticity, and thermal stability for precision industrial components. Oil-Resistant NBR commands the largest volume share as automotive and oilfield applications require proven hydrocarbon barrier performance, while Medical Grade NBR latex generates premium pricing as glove manufacturers pursue ASTM D6319 and ISO 11193 compliance for surgical and examination products. The Seals application segment leads value capture due to criticality in hydraulic and pneumatic systems where failure carries high consequential cost.
FDA regulations govern Medical Grade NBR biocompatibility for healthcare applications, while EPA standards restrict residual nitrosamine levels in consumer-contact formulations, and REACH registration requirements control monomer purity thresholds for European market access. These overlapping compliance frameworks elevate barriers for uncertified compounders and concentrate procurement among validated suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated processing aids face substitution pressure that could redirect formulation R&D investment toward silicone-NBR hybrid systems.
Market Dynamics
REACH and RoHS frameworks in Europe are tightening permissible extractable limits, forcing compounders to abandon legacy formulations and recertify entire product lines for medical-grade compliance.
Growth Catalysts
- Fuel system compatibility mandates:OEMs specify higher acrylonitrile content grades for automotive sealing applications, pulling volume toward precision-engineered compounds.
- REACH registration thresholds:Monomer purity requirements for European market access concentrate procurement among validated suppliers with established compliance infrastructure.
- Semiconductor fabrication expansion:Cleanroom seal demand from chip manufacturing clusters in East Asia drives consumption of ultra-high-purity NBR grades.
Market Restraints
- Butadiene feedstock volatility:Crude-linked pricing for this essential monomer creates margin compression for non-integrated compounders without captive supply.
- Fluorinated processing aid restrictions:Per- and polyfluoroalkyl substance limitations under evolving EPA frameworks threaten existing formulation portfolios.
- Hydrogenated NBR substitution:HNBR's superior thermal stability captures extreme-temperature applications previously served by specialty acrylonitrile grades.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's tightening medical device standards create first-mover advantage for ASTM D6319-certified latex suppliers.
- Silicone-NBR hybrid R&D:Fluorinated aid substitution pressure redirects formulation investment toward novel polymer blends with combined chemical resistance and elasticity.
- Direct compounder-to-OEM contracting:Tier supplier consolidation around Germany's automotive corridor enables bypass of traditional distribution layers.
Industry Challenges
- ISO 11193 certification timelines:Medical glove manufacturers face 18-24 month validation cycles that delay market entry and tie up working capital.
- Legacy hydraulic system integration:Seals manufacturers must maintain backward compatibility with decades-old equipment specifications while advancing material performance.
- Specialized polymerization expertise scarcity:Emulsion and solution process engineers command premium compensation, constraining capacity expansion at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Nitrile Butadiene Rubber (NBR) Market |
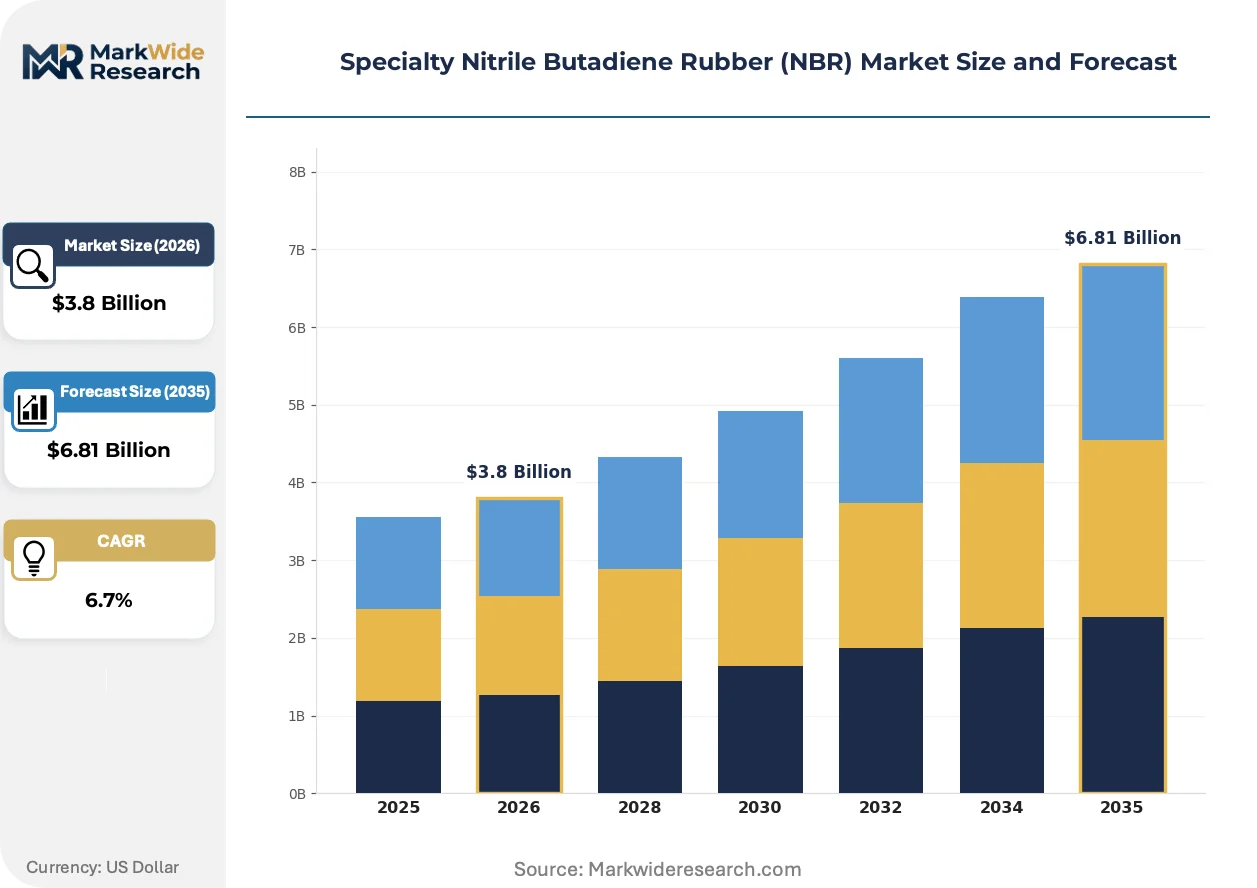
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Resistant NBR, Foam NBR, NBR Latex, NBR Blends End User: Automotive, Healthcare, Consumer Goods, Adhesives Application: Seals, Gaskets, Hoses, Coatings Grade: Standard Grade, High Performance Grade, Medical Grade, Specialty Grade |
| Companies Covered | ARLANXEO, China Petrochemical Corporation, ZEON Corporation, Synthos S.A., LG Chem, LANXESS AG, Kumho Petrochemical, American Rubber Products, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Nitrile Butadiene Rubber (NBR) Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance benchmarks across automotive, medical, and industrial sealing applications.
Solution polymerization methods producing ultra-low extractable grades are rendering obsolete conventional emulsion processes for semiconductor and pharmaceutical applications. Cleanroom equipment manufacturers in Japan and South Korea now specify these materials exclusively, compressing demand for legacy high-ash-content compounds and forcing European compounders to retool production lines.
REACH Annex XVII amendments targeting nitrosamine residuals in consumer-contact formulations are triggering wholesale formulation reviews across European compounding facilities. The industrial consequence is accelerated phase-out of certain vulcanization accelerators, with medical-grade latex producers investing in alternative cure systems to maintain ASTM D6319 compliance for surgical glove exports.
Specification-driven procurement now dominates automotive sealing contracts, with OEM technical teams mandating certified compound lots rather than accepting standard commercial grades. This behavior shift disintermediates traditional distributors in Germany's industrial corridor, as BMW and Volkswagen purchasing departments engage ARLANXEO and LANXESS directly for fuel system components.
Specialty Nitrile Butadiene Rubber (NBR) Market Segmentation
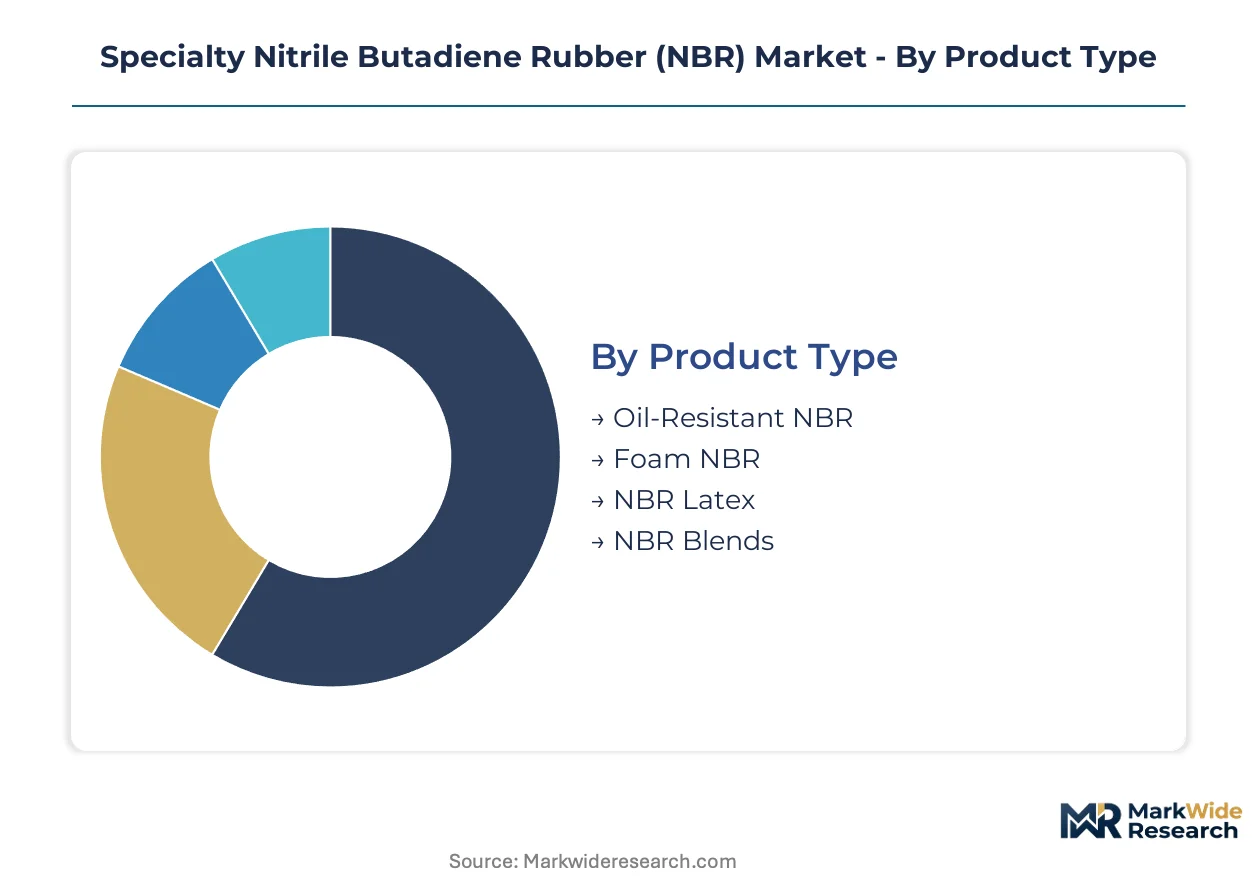
Specialty NBR purchasing decisions cascade through multiple intersecting dimensions. Compounders must navigate specification requirements from OEMs, regulatory thresholds from FDA and REACH, and performance demands from end-use environments simultaneously.
Product Type:
Cost tier differentiation separates commodity formulations from certified grades commanding material premiums.
- Oil-Resistant NBR:Formulations with 18-50% acrylonitrile content deliver proven hydrocarbon barrier performance. Automotive fuel system seals and oilfield packers in Germany's industrial corridor specify these grades exclusively, with OEM technical teams mandating certified compound lots rather than standard commercial grades.
- NBR Latex:Emulsion-polymerized dispersions enable dipped goods manufacturing with controlled particle size distribution. Glove producers pursuing ASTM D6319 and ISO 11193 compliance for surgical and examination products concentrate procurement among validated suppliers with established medical-grade certification infrastructure.
- Foam NBR:Cellular structures provide cushioning and insulation with closed-cell morphology for moisture resistance.
- NBR Blends:Compounded with PVC or other polymers to balance cost and performance in industrial applications.
Oil-Resistant NBR commands the established base. The steepest expansion runs through NBR Latex.
End User:
Application criticality determines certification burden and pricing power across customer verticals.
- Automotive:Fuel system compatibility mandates specify higher acrylonitrile content grades for sealing applications. BMW and Volkswagen purchasing departments engage compounders directly for precision-engineered components, disintermediating traditional distribution layers in Germany's automotive corridor.
- Healthcare:Medical device manufacturers face 18-24 month ISO 11193 validation cycles that delay market entry and tie up working capital. CDSCO's tightening standards in India create first-mover advantage for ASTM D6319-certified latex suppliers.
- Consumer Goods:REACH Annex XVII amendments targeting nitrosamine residuals trigger wholesale formulation reviews across European compounding facilities.
- Adhesives:Pressure-sensitive and structural bonding applications leverage NBR's tack and flexibility.
Automotive anchors volume demand. Healthcare generates the steepest margin expansion.
Application:
Functional performance requirements dictate polymer architecture and certification pathways.
- Seals:Criticality in hydraulic and pneumatic systems where failure carries high consequential cost drives value capture. Cleanroom equipment manufacturers in Japan and South Korea now specify ultra-low extractable grades exclusively, compressing demand for legacy high-ash-content compounds.
- Hoses:Automotive and industrial fluid transfer applications require dynamic flex resistance and chemical compatibility. Kumho Petrochemical anchors Korean domestic supply for automotive hose compounds.
- Gaskets:Static sealing applications span flange connections and equipment enclosures across industrial sectors.
- Coatings:Protective films and barrier layers leverage NBR's solvent resistance and adhesion properties.
Seals concentrate the highest value per kilogram. Hoses deliver the steepest volume trajectory.
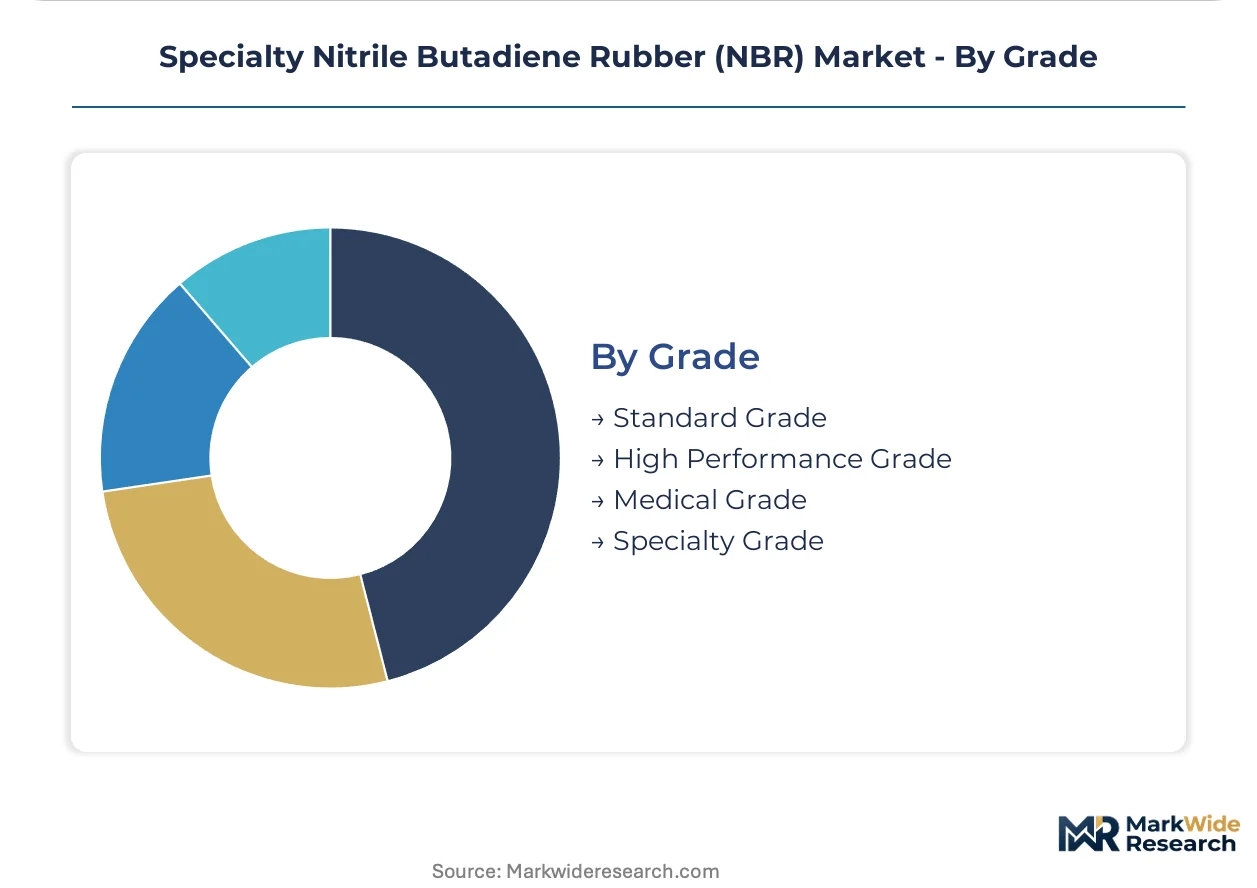
Grade:
Certification tier separates validated suppliers from commodity compounders in procurement decisions.
- Medical Grade:Biocompatibility requirements under FDA regulations govern healthcare applications, with EPA standards restricting residual nitrosamine levels in consumer-contact formulations. Alternative cure system investments maintain compliance as certain vulcanization accelerators face phase-out.
- High Performance Grade:Hydrogenated variants and ultra-pure formulations capture extreme-temperature applications and semiconductor fabrication demand. ZEON Corporation dominates high-purity grades for semiconductor seals in East Asian chip manufacturing clusters.
- Specialty Grade:Custom formulations address specific OEM specifications with dedicated compound development.
- Standard Grade:General-purpose formulations serve industrial applications without stringent certification requirements.
Medical Grade commands pricing premiums. High Performance Grade climbs the fastest on semiconductor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites Northwest Europe's feedstock security for specialty NBR production. This infrastructure anchors the continent's chemical processing density and enables just-in-time monomer delivery to compounders serving automotive OEMs.
Germany
Fuel system seal demand from BMW and Volkswagen technical teams specifies higher acrylonitrile content grades exclusively. REACH Annex XVII amendments on nitrosamine residuals force compounders toward alternative cure systems. The Stuttgart-Munich industrial corridor concentrates tier supplier facilities around major automaker headquarters.
United States
Semiconductor fabrication expansion in Arizona and Texas drives consumption of ultra-high-purity grades for cleanroom seals. EPA restrictions on per- and polyfluoroalkyl substances threaten existing formulation portfolios. Houston's petrochemical complex anchors butadiene supply security for non-integrated compounders.
China
Domestic automotive hose production scales require proven hydrocarbon barrier performance from oil-resistant formulations. MIIT standards on monomer purity concentrate procurement among validated suppliers with established certification infrastructure. The Yangtze River Delta clustering of chip manufacturing facilities pulls demand for semiconductor-grade materials.
Japan
Cleanroom equipment manufacturers in Osaka and Nagoya specify solution-polymerized ultra-low extractable grades exclusively. METI guidance on industrial material standards compresses demand for legacy high-ash-content compounds. The Chubu region hosts ZEON Corporation's high-purity production facilities serving East Asian chip clusters.
India
Pharmaceutical manufacturing expansion creates first-mover advantage for ASTM D6319-certified latex suppliers to surgical glove producers. CDSCO's tightening medical device standards impose 18-24 month validation cycles that delay market entry. Maharashtra's industrial belt concentrates domestic compounding capacity for healthcare applications.
Specialty Nitrile Butadiene Rubber (NBR) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation expertise and certification infrastructure. The vendor base organizes around three archetypes: integrated petrochemical conglomerates with captive butadiene supply, precision polymer specialists focused on high-purity grades, and regional compounders serving automotive tier networks. Dominant competitive moves include backward integration into monomer production and direct OEM contracting that bypasses traditional distribution layers.
Within the integrated petrochemical tier, ARLANXEO and LANXESS AG exemplify European-based players with established compliance infrastructure for REACH-regulated markets. ZEON Corporation occupies a position among precision polymer specialists, representing the Japanese archetype for ultra-high-purity grades. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning across certification-intensive segments.
| Leading Market Players |
|---|
| ARLANXEO |
| China Petrochemical Corporation |
| ZEON Corporation |
| Synthos S.A. |
| LG Chem |
| LANXESS AG |
| Kumho Petrochemical |
| American Rubber Products |
| JSR Corporation |
| Others |
Value Network & Pricing Analysis
ARLANXEO's integrated butadiene supply chain across Germany and the Netherlands anchors feedstock security for European compounders, concentrating margin capture upstream with petrochemical conglomerates while independent compounders face persistent cost compression from crude-linked monomer volatility.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the Specialty NBR market, with three-tier pricing stratifying across medical-grade certified, high-performance industrial, and standard commercial formulations. Price differentiation rests on certification grade and acrylonitrile content, with ASTM D6319-validated latex commanding substantial premiums over uncertified alternatives. Pricing pressure stems from hydrogenated NBR substitution in extreme-temperature applications, eroding margins for legacy acrylonitrile grades. Tier suppliers in Germany's automotive corridor exhibit lowest price sensitivity due to specification-locked contracts, while commodity industrial buyers demonstrate acute responsiveness to feedstock fluctuations.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Germany and Japan strain working capital for mid-scale compounders, forcing reliance on supply-chain finance facilities. Geographic supply concentration centers on Germany, Japan, and South Korea, with Rotterdam-Antwerp pipeline infrastructure feeding Northwest European production. Raw material dependencies draw from butadiene monomer, acrylonitrile, and specialized vulcanization accelerators facing REACH-driven phase-outs. Single-source vulnerability runs through ZEON Corporation's dominance of semiconductor-grade materials. Distribution runs through direct compounder-to-OEM contracting that disintermediates traditional distributor layers in precision applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty NBR incumbents must navigate hydrogenated NBR substitution that captures thermal-extreme applications previously served by high-acrylonitrile grades, requiring defensive repositioning around certification-locked medical and semiconductor segments.
For Market Incumbents: Pre-empt HNBR displacement by accelerating R&D investment in silicone-NBR hybrid systems that combine chemical resistance with elasticity, while securing backward integration into butadiene supply to defend margin position against feedstock volatility. Direct contracting with BMW and Volkswagen procurement teams in Stuttgart-Munich bypasses distributor layers and locks in specification-driven volume.
For New Entrants and Emerging Players: Pursue CDSCO-validated medical-grade latex supply to India's pharmaceutical manufacturing expansion in Maharashtra, where ASTM D6319 certification creates 18-24 month barriers for established competitors. Target semiconductor cleanroom seal applications in Japan's Chubu region through solution-polymerized ultra-low extractable grades that legacy European compounders struggle to produce.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders in Southeast Asia lacking integrated feedstock but holding medical-grade certification infrastructure. Long-term viability hinges on regulatory compliance durability rather than commodity scale. Watch EPA per- and polyfluoroalkyl substance restrictions as the inflection signal that redirects formulation R&D spend toward alternative cure systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene | Captive monomer supply insulates ARLANXEO and LANXESS from crude-linked volatility. |
| Medical-Grade Certification Investment | ASTM D6319 validation opens surgical glove procurement from India's CDSCO-regulated manufacturers. |
| Silicone-NBR Hybrid R&D | Fluorinated processing aid substitution redirects formulation investment toward novel polymer blends. |
| Direct OEM Contracting | BMW and Volkswagen technical teams now mandate certified compound lots exclusively. |
| Solution Polymerization Retooling | Ultra-low extractable grades displace emulsion processes for semiconductor fabrication demand. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across the Specialty NBR market. Plant managers at European compounding facilities, procurement leads at German automotive Tier 1 suppliers, distribution channel partners serving industrial seal manufacturers, and technical R&D directors at Japanese precision polymer specialists provided operational perspective. Secondary sources include ECHA REACH registration databases, FDA 510(k) filings for medical-grade materials, SEC 10-K disclosures from listed petrochemical conglomerates, and customs trade data for butadiene derivative flows. Bottom-up volume builds from application-level consumption models triangulate against top-down petrochemical capacity assessments.
Calibration against historical price realizations and certification timeline data validates the projection framework across the analysis window. Segmentation dimensions span product grade tier, end-use industry vertical, application functional category, and regional production hub cluster. CAGRs derive from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific inputs include semiconductor fabrication capacity buildouts in East Asia and automotive fuel system seal specification shifts from German OEM technical teams.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories and European regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding REACH Annex XVII implementation timelines and substitution elasticity between specialty NBR and hydrogenated variants. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EPDM Market
Rubber
Rubber Accelerators Market
Rubber
Global Crumb Rubber Market
Rubber
Rubber Valve Stem Market
Rubber
Silica for S-SBR Market
Rubber
Europe Neoprene Market
Rubber
Nitrile Elastomers Market
Rubber
Synthetic Rubber Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Rubber Ropes Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Rubber Flooring Market
Rubber
Industrial Rubber Products Market
Rubber
Liquid Polybutadiene Market