
 Niobium Market | 2026-2036
Niobium Market Size, Share, and Industry Trends Forecast 2026-2036
Niobium Market Intelligence
ASTM B393 qualification for reactor-grade niobium is collapsing the supplier base to a handful of certified producers. CBMM dominates raw material supply from its Araxá complex in Brazil, leveraging captive pyrochlore reserves and integrated refining. NioCorp Developments Ltd. positions its Elk Creek project as a North American alternative, navigating permitting complexity to establish domestic superalloy feedstock capacity.
Niobium is a refractory transition metal with atomic number 41, melting point 2,477°C, and exceptional corrosion resistance in acidic environments, primarily deployed as ferroniobium micro-additions to strengthen low-alloy steels and as pure metal in superconducting applications. Steel Production anchors volume demand through ferroniobium consumption in pipeline and automotive high-strength steels, while Aerospace represents the fastest-growing value segment as single-crystal turbine blade alloys require higher-purity niobium metal. Niobium Alloys command premium margins where nickel-based superalloys for jet engines specify tight tantalum and tungsten co-content limits.
REACH registration requirements in Europe restrict unqualified niobium compound imports, while China's GB/T 3629 standard for niobium and niobium alloy sheets shapes domestic procurement specifications for chemical processing equipment. The US Department of Commerce maintains niobium on its critical minerals list, influencing federal stockpile policy and loan guarantee eligibility for domestic mine development. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost structure of Brazilian-sourced ferroniobium against emerging North American and African supply alternatives.
Market Dynamics
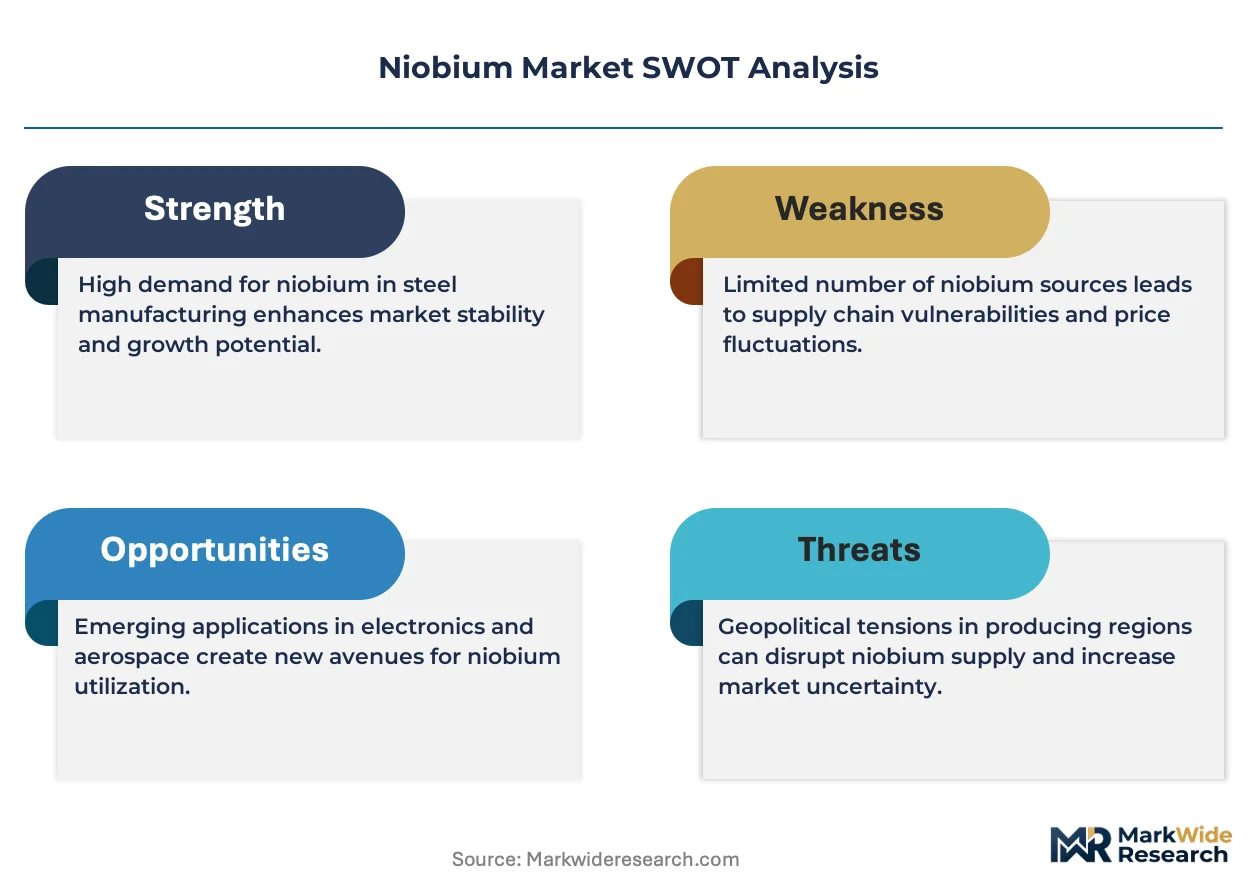
CBMM's captive pyrochlore reserves at Araxá concentrate upstream supply, while ASTM B393 reactor-grade certification collapses the qualified supplier base and China's GB standards tighten steel micro-addition specifications.
Growth Catalysts
- Single-crystal turbine blade alloys:Aerospace manufacturers specify higher-purity niobium metal for nickel-based superalloys, tightening tantalum and tungsten co-content limits. Jet engine OEMs drive value-segment expansion.
- Dual carbon goals:China's MEE mandates reduce steel sector emissions, accelerating ferroniobium consumption in high-strength low-alloy steels for lighter automotive and pipeline applications.
- Critical minerals designation:The US Department of Commerce listing triggers federal stockpile policy and loan guarantee eligibility for domestic mine development, redirecting capital toward North American supply alternatives.
Market Restraints
- Pyrochlore deposit concentration:Brazil's Minas Gerais state hosts the world's mineable reserves, creating single-source vulnerability for ferroniobium feedstock.
- REACH registration friction:ECHA requirements restrict unqualified niobium compound imports into Europe, raising compliance costs for traders and processors.
- Tantalum substitution in capacitors:Electronics manufacturers pivot to niobium oxide capacitors only where supply agreements stabilize, limiting metal penetration in passive components.
Strategic Opportunities
- Elk Creek carbonatite development:Nebraska's untapped niobium-scandium-titanium resource offers North American superalloy feedstock independence from Brazilian supply chains.
- Superconducting RF cavity fabrication:Particle accelerator projects in Japan and South Korea specify high-purity niobium sheet for next-generation collider infrastructure.
- Carbon border adjustment mechanisms:EU CBAM redefines landed cost structures for Brazilian-sourced ferroniobium, creating margin headroom for lower-carbon African and North American alternatives.
Industry Challenges
- ASTM B393 certification timelines:Reactor-grade qualification requires 18-24 months of traceability documentation and third-party audit cycles, constraining new market entrants.
- Pyrometallurgical refining capex:Ferroniobium production demands aluminum thermic reduction facilities with captive power and slag handling infrastructure, raising capital intensity for greenfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niobium Market |
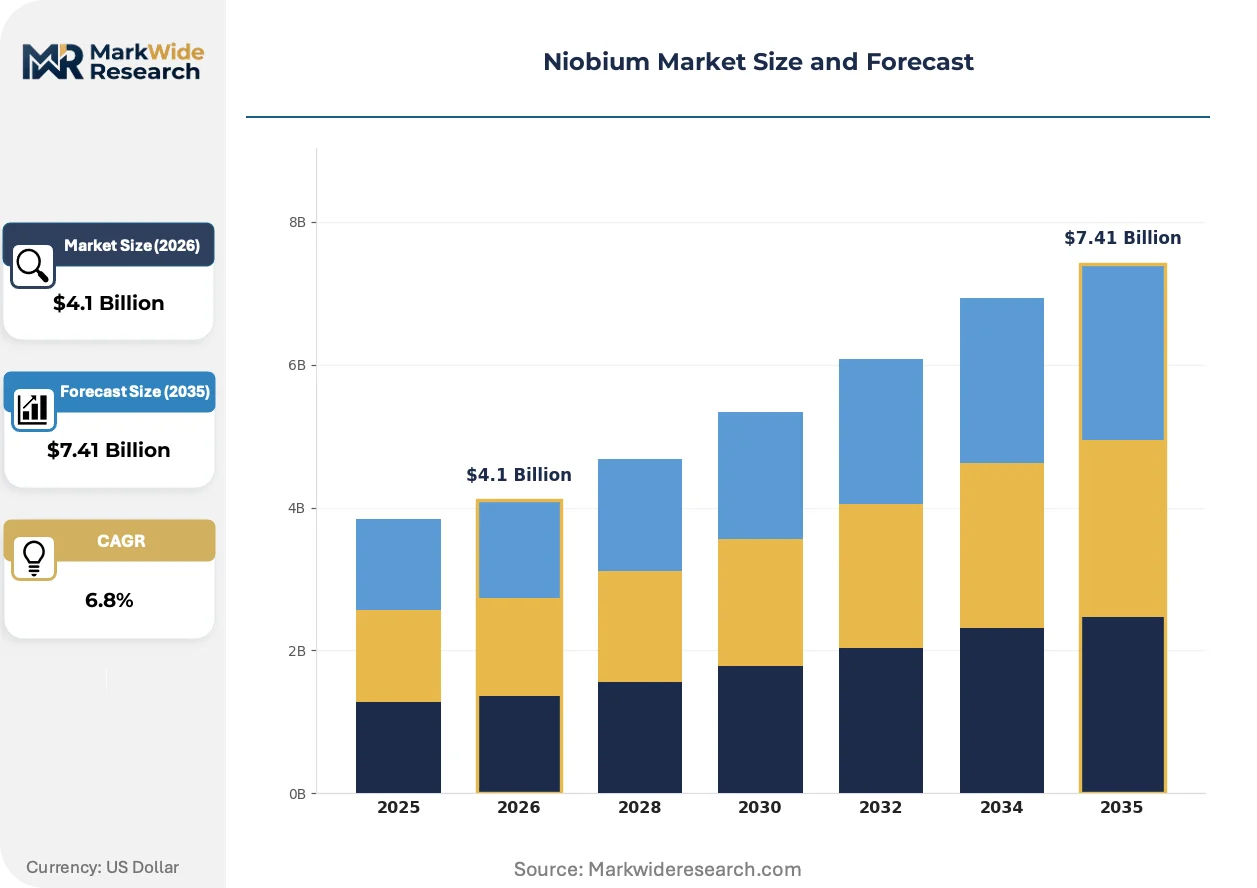
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Niobium Oxide, Niobium Metal, Niobium Alloys, Niobium Carbide Application: Aerospace, Electronics, Automotive, Steel Production End User: Manufacturers, Suppliers, Fabricators, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | NioCorp Developments Ltd., Nippon Steel Corporation, CBMM (Companhia Brasileira de Metalurgia e Mineração), Shin-Etsu Chemical Co., Ltd., JFE Steel Corporation, CMOC (China Molybdenum Co., Ltd.), Anglo American, Taseko Mines Limited, Magris Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niobium Market Strategic Shifts & Innovations
Electron beam melting purification is reshaping high-value niobium metal supply, while regulatory fragmentation around critical minerals and carbon accounting redefines competitive positioning across extraction and refining stages.
Electron beam melting of niobium ingots is supplanting traditional vacuum arc remelting for superconducting applications. Research institutions and MRI magnet fabricators in Germany and Japan adopt the technology for residual gas elimination. The process enables tantalum separation below 50 ppm, unlocking premium pricing in medical imaging and particle accelerator contracts.
REACH authorization requirements for niobium pentoxide are tightening import documentation and downstream user communication obligations. European chemical processors must demonstrate safe use scenarios across catalyst and optical coating applications. Specialty alloy foundries in Germany and France are consolidating suppliers to reduce registration cost duplication.
Long-term offtake contracting is displacing spot market purchasing among aerospace superalloy producers. Tier-one jet engine OEMs in the US and UK now secure five-year niobium metal supply agreements with fixed-volume, indexed-price structures. The shift concentrates procurement leverage with ASTM B393-certified producers and marginalizes trading house intermediaries.
Niobium Market Segmentation
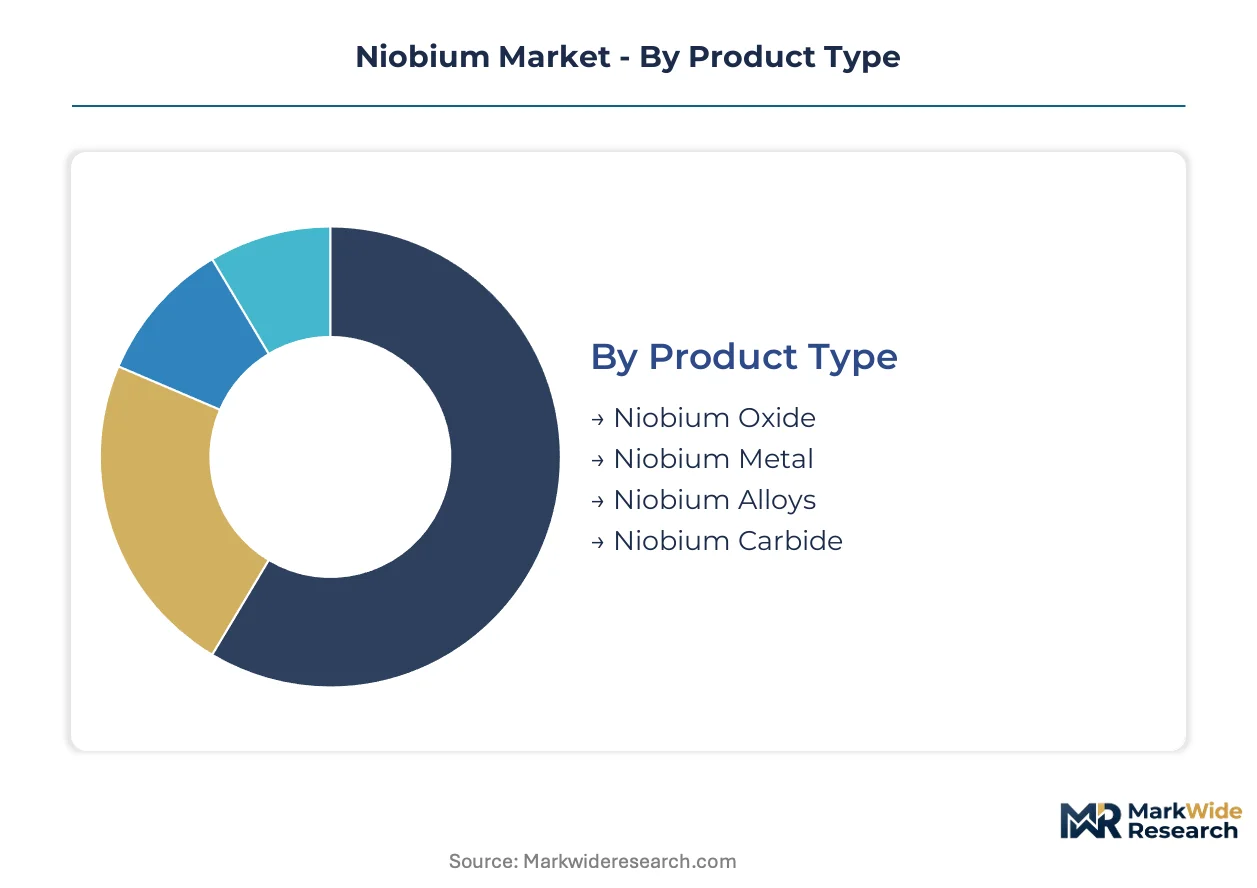
Niobium's commercial pathways diverge sharply between bulk ferroniobium flowing through steel mill direct contracts and high-purity metal moving through qualified supplier channels. Channel selection dictates margin capture, certification burden, and customer concentration risk across each segment.
Product Type:
Direct sales channels dominate ferroniobium volumes to integrated steel mills, while specialty distributors handle high-purity metal and alloys requiring ASTM B393 documentation.
- Niobium Metal:Vacuum-grade ingots and electron-beam-refined sheet command premium positioning in superconducting RF cavities and single-crystal turbine blade feedstock. Demand concentrates at General Electric Aviation and Pratt & Whitney superalloy foundries in the US and UK, where five-year offtake agreements now displace spot purchasing.
- Niobium Alloys:Nickel-based superalloys with tight tantalum and tungsten co-content limits serve jet engine OEM specifications. Procurement flows through qualified Tier-1 aerospace suppliers in Connecticut and Derbyshire, with CBMM and limited ASTM-certified producers capturing contract leverage.
- Niobium Oxide:Dielectric material for electronics capacitors moves through chemical distributors serving Asian contract manufacturers.
- Niobium Carbide:Hardmetal cutting tool applications source through specialized carbide powder distributors in Germany and Japan.
Niobium Metal dominates installed base value. Niobium Alloys is where expansion concentrates.
Application:
Cost tier separation runs deepest here, with commodity steel micro-additions at volume-driven margins and aerospace alloys at specification-driven premiums.
- Steel Production:Ferroniobium micro-additions strengthen high-strength low-alloy steels for automotive lightweighting and pipeline construction. China's MEE mandates accelerate consumption as mills substitute niobium for carbon-intensive alloying alternatives, with procurement flowing through CBMM's captive logistics network from Araxá.
- Aerospace:Single-crystal turbine blade alloys specify higher-purity metal with tantalum below 50 ppm. Jet engine OEMs in Cincinnati and Derby concentrate demand, driving the steepest expansion trajectory across all applications.
- Electronics:Niobium oxide capacitors serve niche applications where tantalum supply agreements prove unstable.
- Automotive:Direct ferroniobium consumption in chassis and powertrain components bypasses steel mill intermediation for select Tier-1 suppliers.
Steel Production anchors volume throughput. Aerospace captures margin expansion.
End User:
Customer type determines contract structure, with integrated manufacturers demanding captive supply and fabricators accepting distributor intermediation.
- Manufacturers:Steel mills and superalloy foundries source through long-term contracts with volume commitments and indexed pricing. China's Baowu and US-based Carpenter Technology exemplify procurement concentration at this tier.
- Fabricators:Superconducting wire and RF cavity fabricators in Germany and Japan require documented traceability and electron-beam purification certificates.
- Suppliers:Trading houses and chemical distributors handle niobium pentoxide and intermediate compounds.
- Research Institutions:CERN, KEK, and Brookhaven National Laboratory procure high-purity sheet for particle accelerator projects through specialized scientific supply channels.
Manufacturers dominate contract value. Fabricators drive technical specification advancement.
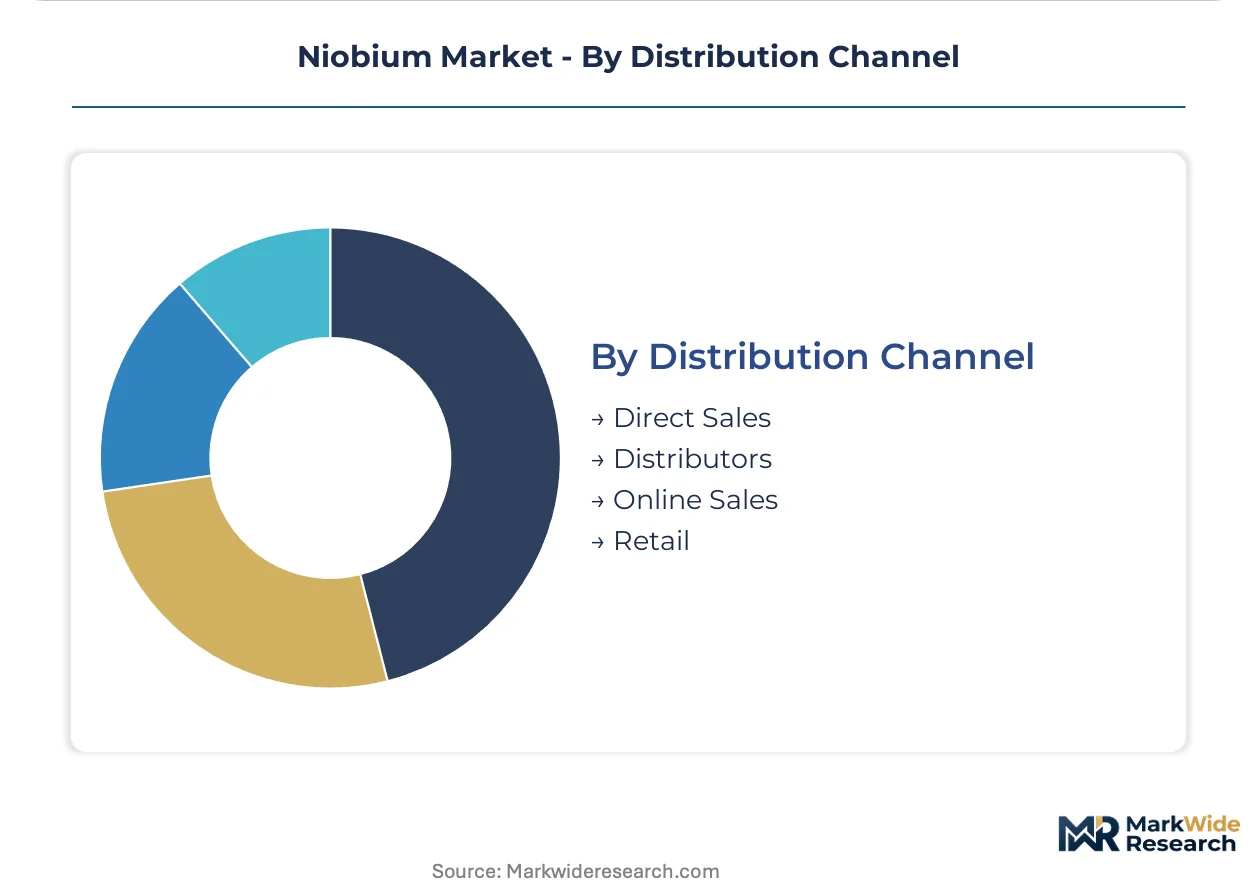
Distribution Channel:
Supply concentration in Brazilian pyrochlore deposits shapes channel economics, with direct sales capturing integrated value and distributors serving fragmented demand.
- Direct Sales:CBMM's mine-to-metal integration delivers ferroniobium directly to steel mills and superalloy producers, eliminating intermediation margin. This channel captures the majority of global niobium value.
- Distributors:Specialty chemical and alloy distributors serve European REACH-registered processors and smaller aerospace Tier-2 suppliers lacking direct qualification.
- Online Sales:Limited to laboratory reagent grades and small-batch niobium compounds for research applications.
- Retail:Negligible presence; no meaningful consumer-facing niobium products exist.
Direct Sales commands volume concentration. Distributors serve regulatory-complexity niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal loan guarantees and critical minerals stockpile policies are redirecting capital toward domestic niobium development across multiple jurisdictions. China's GB standards and MEE emissions mandates reshape steel micro-addition specifications. Brazil's captive pyrochlore reserves maintain upstream concentration despite geographic diversification efforts.
United States
Jet engine OEMs in Cincinnati and Connecticut concentrate aerospace superalloy demand with five-year offtake agreements. The Department of Commerce critical minerals listing triggers federal stockpile policy and loan guarantee eligibility. Nebraska's Elk Creek carbonatite project advances permitting to establish North American superalloy feedstock capacity independent of Brazilian supply chains.
China
Baowu Steel and regional mills accelerate ferroniobium consumption for high-strength low-alloy steels under MEE emissions reduction mandates. GB/T 3629 standards for niobium and niobium alloy sheets shape domestic procurement specifications for chemical processing equipment. Yangtze River Delta steel clusters integrate niobium micro-additions for automotive lightweighting applications.
Brazil
CBMM's Araxá complex feeds integrated mine-to-metal supply chains from captive Minas Gerais pyrochlore reserves. ANVISA and environmental licensing frameworks govern expansion at the world's largest mineable niobium deposit. The integrated refining infrastructure delivers ferroniobium directly to steel mills across Asia, Europe, and North America.
Germany
Specialty alloy foundries in North Rhine-Westphalia consolidate suppliers to reduce REACH registration cost duplication for niobium pentoxide. ECHA authorization requirements tighten import documentation and downstream user communication obligations. Research institutions and MRI magnet fabricators adopt electron beam melting for residual gas elimination in superconducting applications.
Japan
KEK and particle accelerator projects specify high-purity niobium sheet for next-generation collider infrastructure. METI industrial policy supports superconducting RF cavity fabrication for domestic and export contracts. Osaka and Nagoya superconducting wire fabricators require documented traceability and electron-beam purification certificates from qualified suppliers.
Niobium Market Key Industry Players
Player mix skews toward vertically integrated mining conglomerates with captive pyrochlore reserves and captive refining infrastructure. Two strategic archetypes dominate: Brazilian mine-to-metal integrators controlling upstream concentrate supply, and project developers positioning North American carbonatite resources as supply chain alternatives. Competitive moves concentrate on long-term offtake contracting with aerospace OEMs and regulatory qualification timelines for reactor-grade certification.
Within the integrated mining tier, CBMM exemplifies upstream concentration through its Araxá complex operations. NioCorp Developments Ltd. occupies a position among North American project developers navigating permitting complexity. Among steel and chemical conglomerates, Nippon Steel Corporation and JFE Steel Corporation represent downstream integration into ferroniobium-consuming applications. Shin-Etsu Chemical Co., Ltd. sits within the specialty materials fabricator archetype serving electronics and superconducting segments.
| Leading Market Players |
|---|
| NioCorp Developments Ltd. |
| Nippon Steel Corporation |
| CBMM (Companhia Brasileira de Metalurgia e Mineração) |
| Shin-Etsu Chemical Co., Ltd. |
| JFE Steel Corporation |
| CMOC (China Molybdenum Co., Ltd.) |
| Anglo American |
| Taseko Mines Limited |
| Magris Resources |
| Others |
Cost & Logistics Intelligence
Ferroniobium substitution for carbon-intensive alloying alternatives simultaneously reshapes supply geography toward Brazilian pyrochlore dominance and pricing economics toward long-term contract premiums. China's MEE emissions mandates accelerate this displacement dynamic, concentrating procurement leverage with integrated mine-to-metal producers while compressing spot market liquidity.
Pricing Analysis
Certification level creates the primary spread, with ASTM B393 reactor-grade niobium commanding substantial premiums over standard ferroniobium micro-additions. Long-term offtake contracting now dominates aerospace procurement, displacing spot purchasing and anchoring price floors through volume-indexed structures. Cost compression in standard-grade ferroniobium intensifies as Brazilian supply concentration limits buyer leverage. Steel mills exhibit highest price sensitivity due to commoditized micro-addition specifications, while superalloy foundries prioritize qualification security over unit economics.
Supply Chain Analysis
Inventory cycles extend 18-24 months for reactor-grade qualification documentation, constraining responsive capacity scaling. Brazilian pyrochlore reserves at Minas Gerais feed integrated refining infrastructure, while North American carbonatite development and African exploration projects diversify geographic sourcing. Raw material dependencies center on aluminum reductant quality, captive power availability, and slag handling chemistry. Single-source vulnerability pervades upstream concentrate supply. Distribution runs through direct sales channels for integrated steel mills and qualified superalloy producers, with specialty distributors serving REACH-registered European processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron beam melting purification and carbon border adjustment mechanisms constitute dual technological-regulatory inflections accelerating market disruption. Stakeholders must recalibrate positioning against qualification timelines and geographic supply alternatives.
For Market Incumbents: Shield qualification moats through accelerated ASTM B393 certification investments and captive pyrochlore reserve expansion. Deepen backward integration into electron beam melting capacity to capture superconducting application premiums. Defensive consolidation of long-term offtake agreements with Cincinnati and Derby jet engine OEMs neutralizes emerging North American supply threats.
For New Entrants and Emerging Players: Lead with Nebraska carbonatite development targeting superalloy feedstock independence from Brazilian supply chains. White-space concentration sits with North American aerospace Tier-2 suppliers lacking direct CBMM qualification. Penetrate through documented traceability partnerships with German and Japanese superconducting wire fabricators seeking supply diversification.
For Investors and Strategic Acquirers: Critical minerals designation by the US Department of Commerce reshapes the acquisition landscape toward domestic mine development eligibility. Long-term viability frames around federal loan guarantee access and stockpile policy alignment. Target project developers with advanced permitting progress and offtake memoranda with aerospace OEMs. Monitor EU CBAM implementation velocity as inflection indicator for Brazilian-sourced ferroniobium margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year offtake contracts with Pratt & Whitney and General Electric Aviation concentrate procurement leverage. |
| Backward Integration | Captive pyrochlore reserve control at Araxá secures upstream concentrate supply against African project competition. |
| Capacity Expansion | Electron beam melting facility investment in Germany serves CERN and KEK superconducting RF cavity specifications. |
| Regulatory Qualification | ASTM B393 certification investment opens reactor-grade niobium access to medical imaging and particle accelerator contracts. |
| Geographic Expansion | Elk Creek permitting advancement establishes North American superalloy feedstock capacity independent of Brazilian logistics. |
Research Approach
Desk research of customs trade databases, SEC mining company filings, and ECHA REACH registration records preceded structured interviews with superalloy foundry procurement directors, steel mill technical buyers, and electron beam melting equipment specialists. Primary fieldwork with CBMM logistics coordinators and NioCorp project development officers validated supply concentration assumptions. Secondary triangulation drew from ASTM certification documentation, ANVISA environmental licensing records, and GB/T 3629 standard technical committees. Bottom-up volume modeling across ferroniobium micro-addition tiers reconciled with top-down critical minerals policy impact assessment.
Variance decomposition across product type, application, and end-user segments structured the analytical framework over the projection horizon. Modeled dimensions encompassed purity grade tier, steel versus aerospace end-use, and direct sales versus distributor channel. CAGRs derived from segment-level volume trajectories weighted by value-per-ton differentials. Industry-specific inputs incorporated MEE emissions mandate compliance timelines and EU CBAM carbon intensity benchmarking.
The analysis sits within stated boundaries; outcomes outside sustained aerospace superalloy demand growth or accelerated North American mine development would require recalibration. Forecasts reflect assumptions regarding electron beam melting adoption velocity and REACH authorization friction persistence. Commodity price volatility in aluminum reductant markets and Brazilian logistics disruption represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Copper Cathode Market
Metals
North America Aluminium Powder Market
Metals
Europe Welding Consumables Market
Metals
Global Aluminium Wire Rod Market
Metals
Metal Finishing Market
Metals
Liquid Metal Thermal Pad Market
Metals
North America Metal Casting Market
Metals
Crude Steel Market
Metals
Iron Casting Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
India Special Steel Market
Metals
Metal Coil Lamination Market
Metals
Molybdenum Market
Metals
Global Aluminum Market
Metals
Aluminum Slugs Market
Metals
Merchant Bar Quality (MBQ) Steel Market