
 Seaweed Derived Minerals Market | 2026-2036
Seaweed Derived Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Derived Minerals Market Analytics
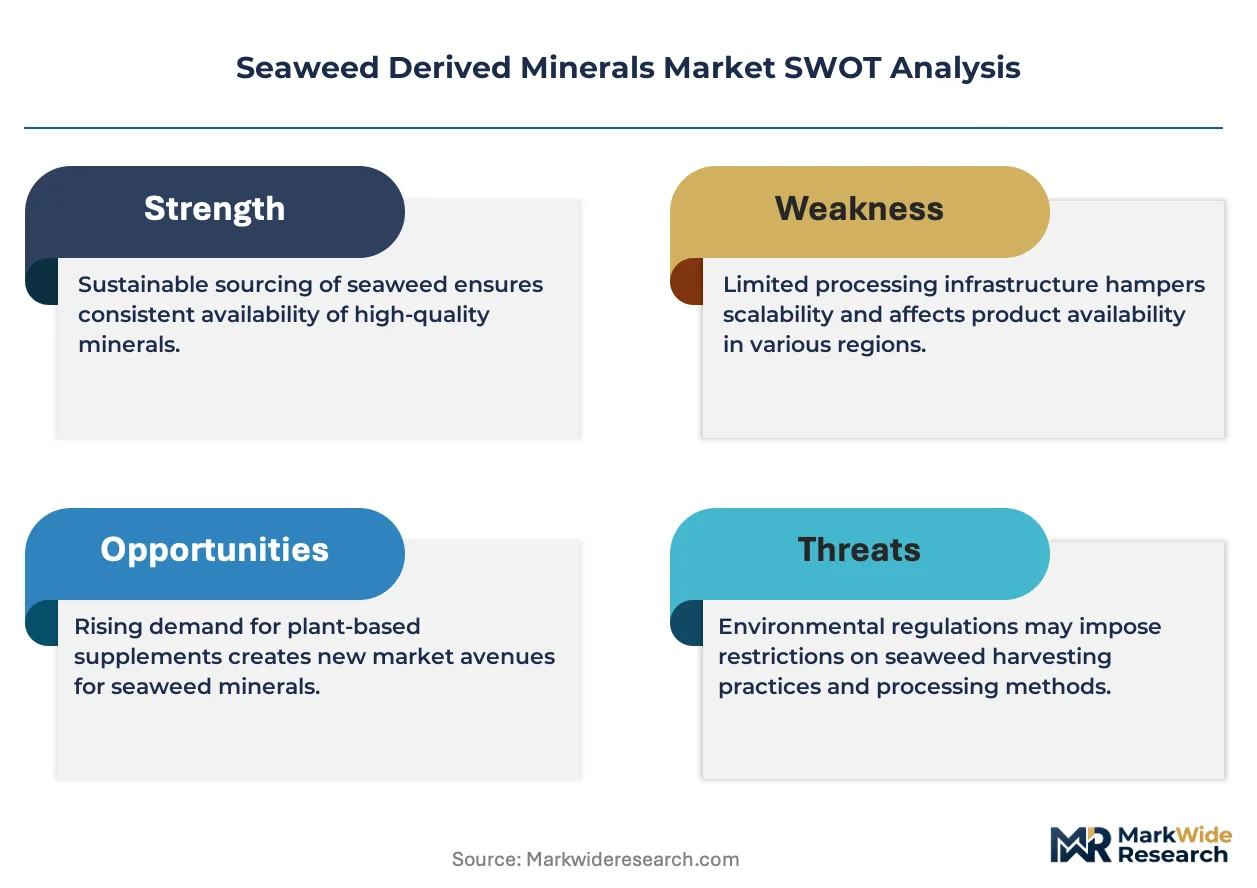
REACH registration requirements is hardening the cost-of-entry calculus for European suppliers, forcing new entrants to front-load compliance spending before securing commercial traction. Cargill leverages its integrated supply chain from Chilean kelp beds to European food manufacturers, sustaining margin control across extraction and distribution stages. DuPont competes through R&D intensity in alginate modification chemistry, while Acadian Seaplants anchors its position in North Atlantic Ascophyllum nodosum harvesting with proprietary cold-extraction protocols.
Seaweed derived minerals comprise ionically complexed macro- and micro-elements extracted from brown, red, and green marine algae through aqueous or acid leaching, with sodium alginate typically containing 15-20% bioavailable calcium and magnesium by dry weight. These minerals serve primarily as functional food fortificants, biodegradable thickeners, and slow-release agricultural biostimulants. Carrageenan and agar dominate food additive applications through established gel-strength specifications, while nutraceutical-grade potassium alginate captures expanding margin pools in pharmaceutical capsule formulations. Powder and liquid forms split demand across industrial-scale food processing and precision agriculture fertigation systems respectively.
The EU Green Deal and REACH frameworks enforce traceability from harvest waters to final ingredient, while FDA GRAS notifications govern US food additive approvals and MFDS regulates South Korean nutraceutical claims. These overlapping compliance layers shape product development roadmaps, with dual-certified extraction facilities commanding procurement preference from multinational food manufacturers. Stakeholders must monitor evolving maximum residue limits for heavy metals in marine biomass, as tightening standards in major import jurisdictions will determine which extraction geographies retain supply relevance.
Market Dynamics
Clean-label ingredient mandates from the EU Green Deal are forcing food manufacturers to replace synthetic mineral fortifiers with traceable marine alternatives, compressing formulation timelines and rewiring supplier qualification protocols across European processing chains.
Growth Catalysts
- MFDS nutraceutical approvals:South Korea's streamlined certification pathway for potassium alginate capsules accelerates product launches in functional food categories, drawing concentrated procurement investment toward established domestic extraction facilities.
- FDA GRAS notifications:US food additive clearance for carrageenan and agar derivatives sustains penetration into dairy alternatives and plant-based meat analogues, locking in long-term supply contracts with reformulating CPG brands.
- Cold-extraction protocols:Proprietary low-temperature processing of Ascophyllum nodosum preserves bioavailable calcium-magnesium ratios, enabling premium positioning in pharmaceutical-grade sodium alginate markets.
Market Restraints
- Heavy metal residue limits:Tightening EFSA maximum thresholds for arsenic and cadmium in marine biomass disqualify harvest zones in industrial coastal waters, constraining viable sourcing geography.
- Chilean kelp bed concentration:Over-reliance on narrow South Pacific harvesting corridors exposes processors to El Niño-driven biomass variability and port logistics disruption.
- Synthetic mineral pricing:Low-cost inorganic calcium carbonate and magnesium oxide from limestone and brine operations undercut marine-derived alternatives in commodity food fortification applications.
Strategic Opportunities
- Precision agriculture fertigation:Liquid seaweed mineral concentrates penetrate high-value greenhouse vegetable operations in the Netherlands, displacing synthetic NPK formulations through biostimulant efficacy claims.
- EU Green Deal sustainability mandates:Carbon footprint disclosure requirements for food ingredients create procurement preference for marine-sourced minerals with verified low-carbon extraction credentials.
- Alginate-hydrogel convergence:Cross-linking sodium alginate with biomedical polymers opens controlled-release drug delivery applications, expanding addressable market beyond traditional food and agriculture verticals.
Industry Challenges
- Dual-certification facility scarcity:Simultaneous EU organic and MFDS nutraceutical compliance requires specialized equipment configurations that extend facility commissioning timelines by 18-24 months.
- Marine biochemistry expertise gaps:Shortage of phycologists and extraction chemists with brown algae-specific knowledge limits R&D throughput for novel mineral complexation methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Derived Minerals Market |
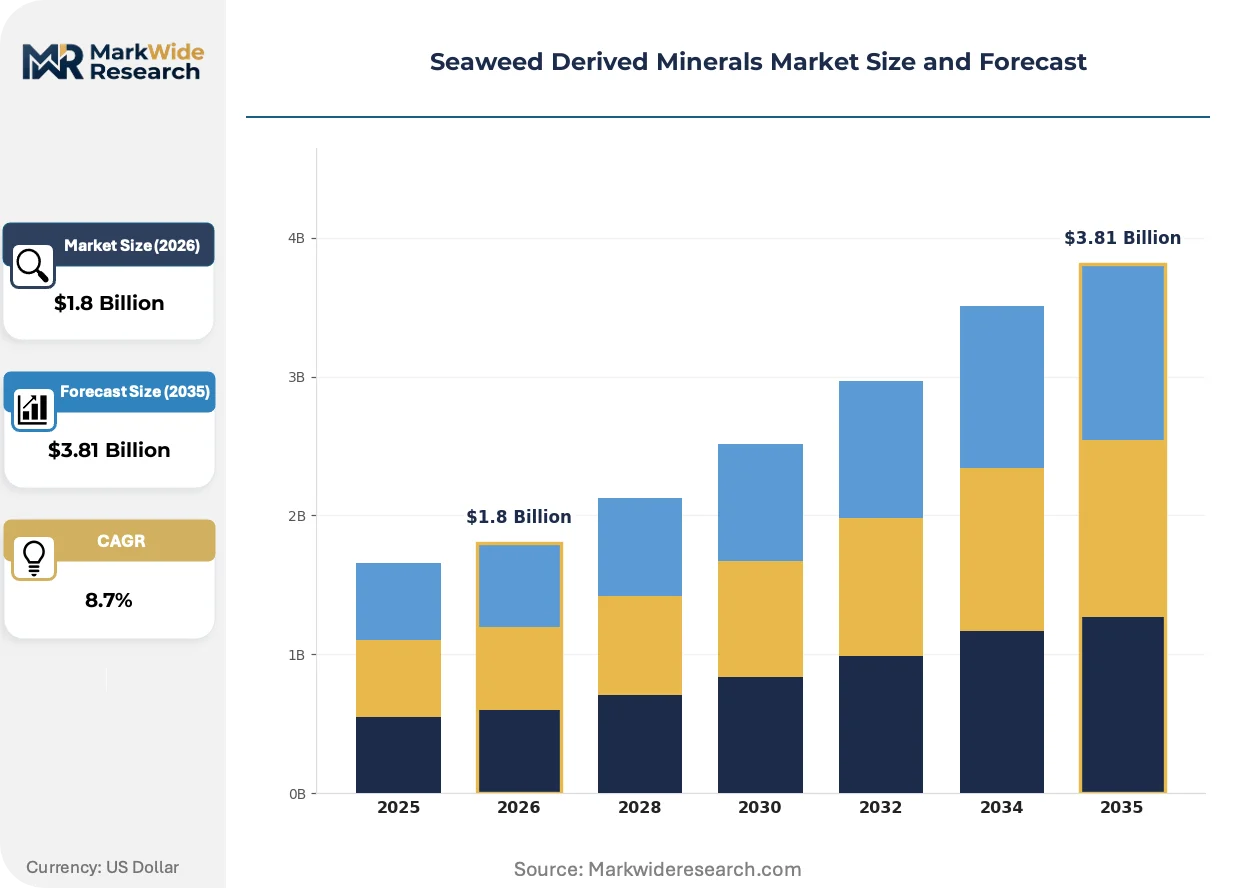
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Potassium Alginate, Carrageenan, Agar End Use Industry: Food & Beverage, Cosmetics, Agriculture, Pharmaceuticals Application: Food Additive, Thickening Agent, Gel Agent, Nutraceutical Form: Powder, Granule, Liquid, Flakes |
| Companies Covered | Cargill, Inc., DuPont, CP Kelco, Algaia SA, Gelymar SA, Qingdao Gather Great Ocean Algae Industry Group, Acadian Seaplants Limited, W Hydrocolloids, Inc., Seasol International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Derived Minerals Market Evolving Landscape
Extraction technology advancement and regulatory traceability mandates are converging to reshape competitive differentiation, with mineral bioavailability claims now requiring substantiation through standardized clinical validation protocols rather than traditional compositional analysis alone.
Enzymatic pre-treatment of kelp biomass is absorbing capital allocation from conventional acid-leaching operations, reducing extraction energy intensity while preserving polysaccharide integrity. European alginate processors retrofitting existing facilities report 30% yield improvements in magnesium recovery rates. This technology is absorbing market share from thermal processing methods that degrade functional gel-strength properties.
REACH registration deadlines for imported marine extracts harden documentation requirements for heavy metal provenance and harvest water quality testing. European compounders now demand batch-level certificates of analysis linking specific kelp beds to final ingredient lots. German and French food manufacturers are consolidating supplier panels to favor extraction facilities with in-house analytical laboratories capable of real-time contaminant screening.
Direct contracting between seaweed harvest cooperatives and end-use formulators is compressing traditional trader-mediated supply chains. Irish and Norwegian processors establish captive relationships with Ascophyllum nodosum collectors, securing multi-year biomass commitments that lock out spot-market competitors. This restructuring concentrates procurement leverage among vertically integrated processors with dedicated fleet and drying infrastructure.
Seaweed Derived Minerals Market Segmentation
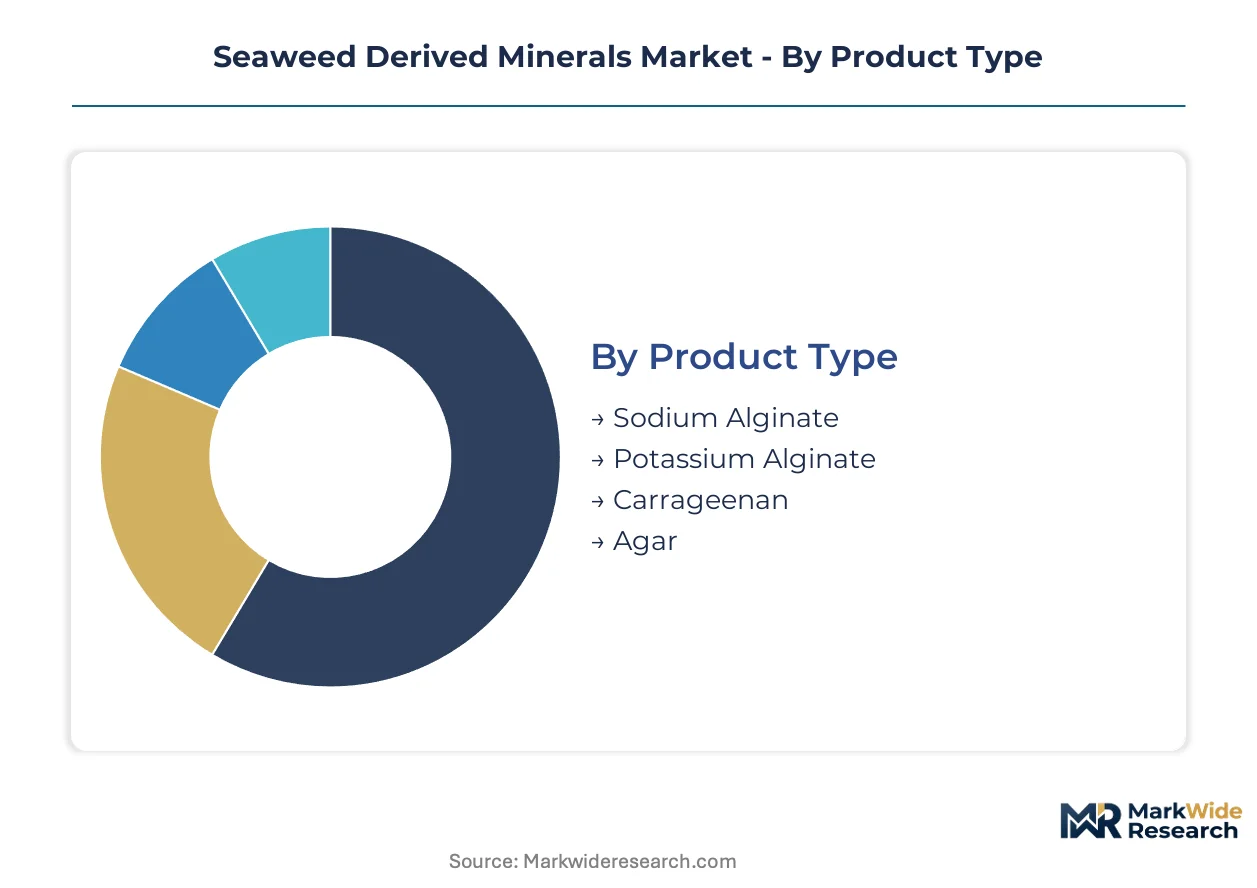
Seaweed derived minerals fragment across four intersecting dimensions that determine extraction protocols, certification requirements, and margin capture. Buyers select segments based on bioavailability specifications, regulatory pathway complexity, and end-use performance thresholds rather than commodity pricing alone.
Product Type:
Cost tier differentiation separates pharmaceutical-grade alginate buyers from commodity food additive purchasers, with extraction method and heavy metal testing intensity driving price spreads.
- Sodium Alginate:Brown algae extracts containing 15-20% bioavailable calcium and magnesium by dry weight serve as biodegradable thickeners and controlled-release matrices. Pharmaceutical capsule manufacturers in South Korea prioritize MFDS-certified sodium alginate for nutraceutical applications, paying premiums for cold-extracted batches with verified polysaccharide integrity.
- Potassium Alginate:Ionically complexed potassium salts enable slow-release agricultural biostimulant formulations with superior foliar adhesion properties. Dutch greenhouse operators specify liquid potassium alginate concentrates for precision fertigation systems, displacing synthetic NPK inputs through carbon footprint verification under EU Green Deal procurement rules.
- Carrageenan:Sulfated galactan polysaccharides from red algae deliver standardized gel-strength performance in dairy alternative formulations.
- Agar:Low-acid gelation properties support plant-based meat analogue texture engineering with FDA GRAS clearance.
Sodium alginate leads volumes today; potassium alginate is gaining share fastest.
End Use Industry:
Application maturity determines whether buyers demand established food-grade certifications or navigate emerging regulatory frameworks for novel uses.
- Food & Beverage:Clean-label reformulation mandates from EU Green Deal sustainability frameworks compress supplier qualification timelines for traceable marine mineral fortifiers. European dairy and meat analogue manufacturers lock in multi-year carrageenan and agar supply contracts to secure GRAS-compliant ingredient pipelines.
- Pharmaceuticals:Alginate-hydrogel convergence for controlled-release drug delivery requires EMA-quality documentation and batch-level heavy metal provenance. German and French formulators consolidate procurement panels to favor extraction facilities with in-house analytical laboratories capable of real-time contaminant screening per REACH registration deadlines.
- Agriculture:Biostimulant efficacy claims in high-value greenhouse vegetable operations drive liquid concentrate adoption.
- Cosmetics:Marine mineral complexes penetrate premium skincare through bioavailability marketing and sustainable sourcing narratives.
Food and beverage leads volumes today; pharmaceuticals is expanding most quickly.
Application:
Functional performance specifications separate commodity buyers from premium segment purchasers willing to fund specialized extraction infrastructure.
- Food Additive:Carrageenan and agar derivatives dominate dairy alternative and plant-based meat texture engineering through established FDA GRAS notification pathways. US CPG brands reformulating clean-label product lines sustain long-term supply commitments with processors maintaining dual EU organic and US organic certification.
- Nutraceutical:Potassium alginate capsules capture expanding margin pools through MFDS streamlined approval pathways in South Korea. Domestic extraction facilities with proprietary cold-processing protocols command procurement preference from functional food brands seeking rapid product launch timelines.
- Thickening Agent:Sodium alginate viscosity grades serve industrial-scale food processing with standardized hydration curves.
- Gel Agent:Agar low-temperature gelation properties enable precision culinary and laboratory applications.
Food additive leads volumes today; nutraceutical is climbing the fastest.
Form:
Logistics intensity and handling equipment requirements split demand between industrial-scale processors and precision agriculture operators.
- Powder:Spray-dried sodium alginate with controlled particle size distribution serves high-throughput food manufacturing lines requiring rapid hydration. European compounders specify powder forms for automated dosing systems in bakery and confectionery operations, with REACH-mandated batch traceability linking specific Chilean kelp beds to final ingredient lots.
- Liquid:Concentrated seaweed mineral suspensions integrate directly into greenhouse fertigation infrastructure without dissolution stages. Dutch and Belgian vegetable producers specify liquid potassium alginate for drip irrigation systems, validating biostimulant efficacy through yield monitoring against synthetic fertilizer benchmarks.
- Granule:Low-dust handling properties support agricultural broadcast applications and slow-release soil amendments.
- Flakes:Traditional agar presentation serves laboratory culture media and specialty culinary segments with established quality grades.
Powder leads volumes today; liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phycologists and marine extraction chemists concentrate in coastal research clusters across South Korea, Chile, and the North Atlantic rim. Their expertise anchors commercial-scale processing infrastructure near established seaweed harvesting corridors. Regional differentiation stems from regulatory pathway efficiency and biomass sourcing reliability rather than labor cost arbitrage.
South Korea
MFDS nutraceutical approvals for potassium alginate capsules accelerate functional food product launches. Domestic extraction facilities with proprietary cold-processing protocols command procurement preference from brands seeking rapid certification timelines. Busan-Ulsan processing corridors concentrate multi-year biomass commitments from regional harvest cooperatives.
Chile
El Niño-driven biomass variability exposes narrow South Pacific harvesting corridors to supply disruption. National regulators enforce harvest water quality documentation aligned with EU import requirements. Puerto Montt and Chiloé Island kelp bed operations sustain Cargill's integrated supply chain into European food manufacturers.
Germany
EMA-quality documentation requirements for alginate-hydrogel drug delivery applications consolidate procurement panels. REACH registration deadlines for imported marine extracts mandate batch-level heavy metal provenance. Hamburg and Bremen harbor zones host compounders retrofitting facilities with in-house analytical laboratories for real-time contaminant screening.
Netherlands
Greenhouse vegetable operators specify liquid potassium alginate concentrates for precision fertigation systems. EU Green Deal carbon footprint disclosure requirements create procurement preference for verified low-carbon extraction credentials. Westland and Noord-Brabant horticulture clusters validate biostimulant efficacy through yield monitoring against synthetic fertilizer benchmarks.
Norway
Direct contracting between Ascophyllum nodosum harvest cooperatives and end-use formulators compresses traditional trader-mediated supply chains. Proprietary cold-extraction protocols preserve bioavailable calcium-magnesium ratios for pharmaceutical-grade markets. Trøndelag and Nordland coastal zones concentrate captive relationships with multi-year biomass commitments.
Seaweed Derived Minerals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction and formulation stages. The vendor base stratifies into three tiers: integrated agribusinesses with captive biomass sourcing, regional processors with proprietary extraction protocols, and commodity traders lacking certification infrastructure. Dominant competitive moves include backward integration into harvest cooperative relationships and capacity expansion of dual-certified extraction facilities.
Among North American integrated agribusinesses, Cargill anchors the tier with Chilean kelp bed supply chain control. DuPont occupies a position within the R&D-intensive specialty chemicals segment. Acadian Seaplants exemplifies the focused pure-play archetype with North Atlantic harvesting specialization. These three entities represent distinct strategic postures rather than direct positional competition.
| Leading Market Players |
|---|
| Cargill, Inc. |
| DuPont |
| CP Kelco |
| Algaia SA |
| Gelymar SA |
| Qingdao Gather Great Ocean Algae Industry Group |
| Acadian Seaplants Limited |
| W Hydrocolloids, Inc. |
| Seasol International |
| Others |
Value Network & Pricing Analysis
Chilean kelp bed harvesting costs cascade through three distinct pricing tiers as biomass moves from coastal collection cooperatives to European food compounders, with cold-extraction certification premiums widening spreads between pharmaceutical-grade sodium alginate and commodity carrageenan feedstock.
Pricing Analysis
Unbundled extraction services and bundled certification-inclusive supply contracts split buyer procurement strategies across the market. Three-tier pricing structure across premium, standard, and economy levels reflects MFDS nutraceutical approval status, REACH registration completeness, and volume commitment scale. Cost compression in standard-grade carrageenan intensifies because synthetic mineral pricing from limestone operations undercuts marine alternatives in commodity food fortification. Commodity food additive purchasers exhibit highest price sensitivity; pharmaceutical capsule manufacturers demonstrate lowest.
Supply Chain Analysis
Freight cost exposure from Chilean kelp beds to European processing hubs absorbs margin at processors lacking dedicated fleet infrastructure. Supply concentrates in Chile, South Korea, and Norway, with brown algae biomass drawing from Ascophyllum nodosum beds in the North Atlantic and Macrocystis pyrifera corridors in the South Pacific. Single-source vulnerability around El Niño-driven biomass variability threatens processors dependent on narrow South Pacific harvesting windows. Distribution runs through vertically integrated agribusinesses with captive harvest cooperative relationships and regional pure-play specialists with proprietary extraction protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between South Korea's streamlined MFDS certification pathways and Europe's REACH-registered extraction infrastructure, with regulatory compliance cost differentials exceeding raw material input spreads.
For Market Incumbents: Cement backward integration into Ascophyllum nodosum harvest cooperatives in Norway and Ireland to lock out spot-market competitors. Expand dual-certified extraction capacity to capture procurement preference from multinational food manufacturers consolidating supplier panels under EU Green Deal traceability mandates. Cold-extraction protocol R&D investment defends margin position against enzymatic pre-treatment technology shifts absorbing capital allocation. For New Entrants and Emerging Players: Enter via precision agriculture liquid concentrate formulations in Dutch and Belgian greenhouse corridors, where biostimulant efficacy claims displace synthetic NPK inputs. Target pharmaceutical-grade potassium alginate capsules in South Korea through MFDS streamlined approval pathways, leveraging domestic extraction facility partnerships to compress certification timelines. Direct contracting with harvest cooperatives bypasses trader-mediated supply chain layers. For Investors and Strategic Acquirers: Roll-up economics work for regional processors with proprietary cold-extraction protocols because certification infrastructure scarcity extends facility commissioning timelines by 18-24 months, creating captive supply value. Long-term viability hinges on alginate-hydrogel convergence for controlled-release drug delivery beyond traditional food and agriculture verticals. Watch enzymatic pre-treatment yield improvements as inflection indicator for technology obsolescence risk in thermal processing methods.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvest Cooperatives | Cargill's Chilean kelp bed control secures biomass commitment priority over spot-market competitors. |
| Dual-Certification Facility Expansion | Simultaneous EU organic and MFDS nutraceutical compliance commands procurement preference from reformulating CPG brands. |
| Enzymatic Pre-Treatment Technology Adoption | European retrofitting facilities report 30% magnesium recovery yield improvements over thermal processing methods. |
| Direct Harvest-to-Formulator Contracting | Irish and Norwegian processors compress trader-mediated supply chains through captive cooperative relationships. |
| Alginate-Hydrogel Convergence R&D | Cross-linking sodium alginate with biomedical polymers expands addressable market into controlled-release drug delivery. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with extraction facility operators, phycologists, food manufacturer procurement leads, pharmaceutical formulators, and agricultural biostimulant distributors with secondary validation from EFSA maximum residue limit documentation, MFDS nutraceutical approval filings, REACH registration databases, and customs trade records for marine extract imports.
Input-output matrices map sodium alginate, potassium alginate, carrageenan, and agar production flows across food additive, nutraceutical, thickening agent, and gel agent applications, with powder, liquid, granule, and flake form factors modeled separately. CAGRs derive from segment-level demand elasticity analysis against synthetic mineral substitute pricing and regulatory pathway efficiency differentials across South Korea, Chile, Germany, Netherlands, and Norway.
The model holds under stable EFSA heavy metal threshold enforcement and MFDS approval timeline continuity; deviation in El Niño frequency or EU Green Deal carbon footprint disclosure stringency would shift supply geography viability. Forecasts reflect documented assumptions about biomass yield consistency and certification infrastructure commissioning rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Global Feed Minerals Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Gluconate Mineral Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Industrial Diamond Market
Industrial Minerals
Limestone Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Industrial Sodium Chloride Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Unexpanded Perlite Market
Industrial Minerals
North America Limestone Market