
 Global Aluminum Market | 2026-2036
Global Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Market Intelligence
Spot contract channels between European automotive OEMs and Gulf smelters is narrowing as long-term offtake agreements replace quarterly pricing. UC RUSAL leverages its Siberian hydro-powered smelters to sustain low-carbon aluminum premiums in European specialty contracts. Emirates Global Aluminium anchors its position through captive bauxite mining in Guinea and integrated alumina refining at Al Taweelah. Norsk Hydro ASA differentiates via its proprietary HAL4e and HAL4e Ultra cell technology, which reduces energy intensity per tonne.
Aluminum is a lightweight, corrosion-resistant metallic element derived from bauxite ore through the Bayer process and electrolytic reduction, typically alloyed with copper, magnesium, silicon, or zinc to achieve tensile strengths from 70 to 700 MPa depending on temper and composition. Its primary industrial purpose centers on weight reduction in transportation structures, thermal management in electrical systems, and barrier protection in packaging formats. Rolled products command the largest value pool from beverage can stock and automotive sheet, while extruded products represent the fastest-growing product category driven by solar panel frame demand and electric vehicle battery enclosure applications. The recycling process segment is capturing expanding margin pools as post-consumer scrap collection infrastructure matures in North America and Europe.
The European Commission's Carbon Border Adjustment Mechanism and the EU Green Deal's emissions benchmarks are forcing non-EU smelters to certify carbon intensity or face tariff-adjusted access penalties. China's Ministry of Ecology and Environment enforces dual carbon goals that cap smelter capacity in Inner Mongolia and Xinjiang while permitting expansion in hydro-rich Yunnan and Guangxi. The US Environmental Protection Agency and Securities and Exchange Commission climate disclosure rules are tightening scope-three reporting requirements for aluminum purchasers. Stakeholders must monitor how carbon border instruments and power sourcing disclosures reshape contract eligibility and supplier qualification timelines.
Market Dynamics
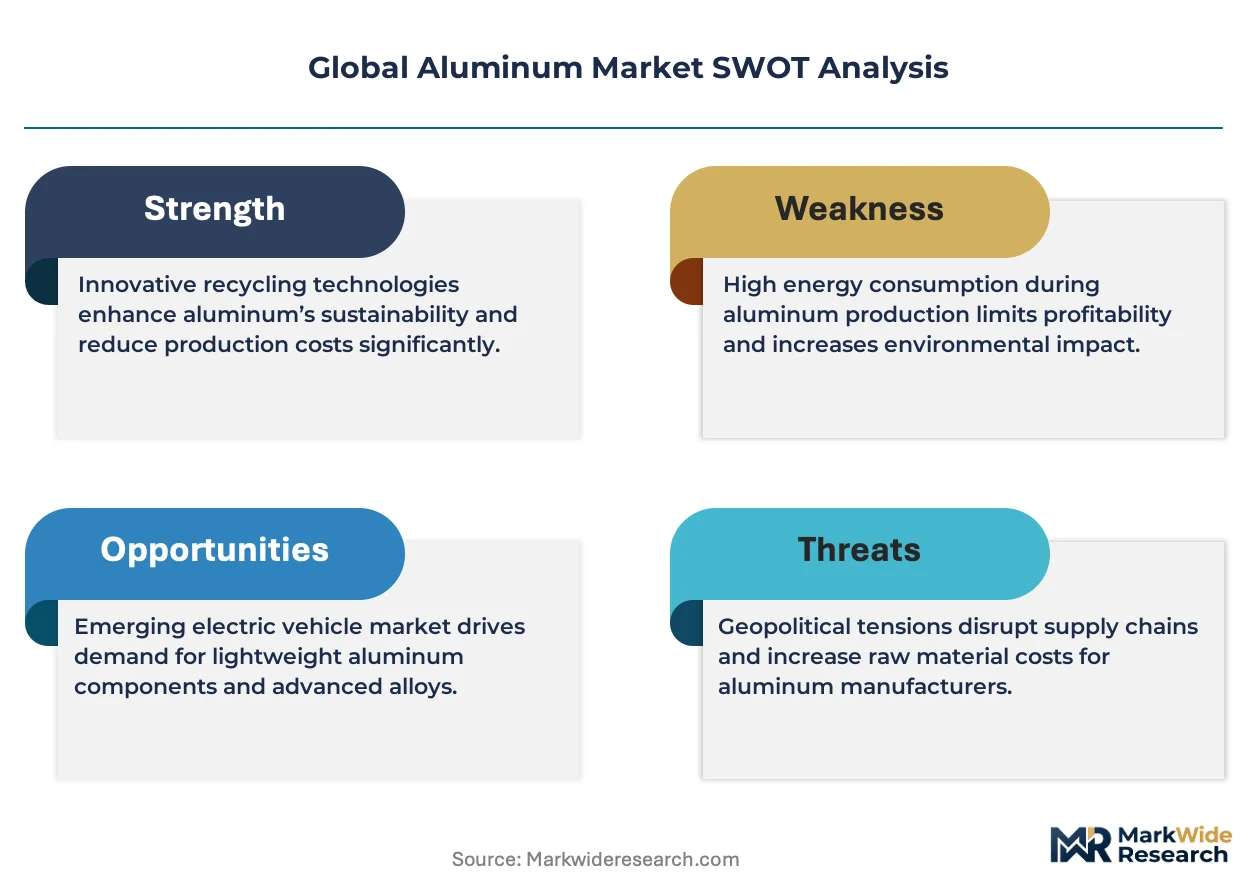
The EU Carbon Border Adjustment Mechanism is forcing non-EU smelters to certify carbon intensity or face tariff-adjusted access penalties, reshaping supplier qualification timelines and contract eligibility across automotive and packaging value chains.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Non-EU smelters must document emissions intensity to maintain European market access, accelerating investment in low-carbon smelting capacity.
- Electric vehicle battery enclosures:Extruded aluminum profiles are displacing steel in EV battery housings as manufacturers pursue weight reduction targets.
- Yunnan and Guangxi smelter expansion:China's hydro-rich southwestern provinces are adding low-carbon primary capacity while coal-dependent regions face capacity caps.
Market Restraints
- Alumina input cost volatility:Bauxite supply concentration in Guinea and Australia exposes smelters to freight and geopolitical risk premiums.
- Chinese smelter dominance:Over half of global primary production concentrates in China, creating single-source vulnerability for European and North American fabricators.
- Carbon fiber substitution in aerospace:Advanced composites are capturing wing and fuselage applications where aluminum alloys previously dominated.
Strategic Opportunities
- India post-consumer scrap infrastructure:Underdeveloped collection networks present first-mover advantages for integrated recycling investments.
- Solar panel frame demand:Extruded aluminum channels are the default mounting solution for utility-scale photovoltaic installations.
- US Inflation Reduction Act clean energy incentives:Domestic content requirements for renewable energy projects favor North American aluminum sourcing.
Industry Challenges
- HAL4e Ultra cell engineering talent scarcity:Norsk Hydro's proprietary electrolytic technology requires specialized metallurgists and process engineers in short supply.
- Scope-three emissions verification:Automotive OEMs demand audited carbon intensity data from tier-three bauxite miners, extending certification timelines.
- Legacy smelter retrofit capex:Converting Soderberg cells to prebake technology demands capital commitments that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Market |
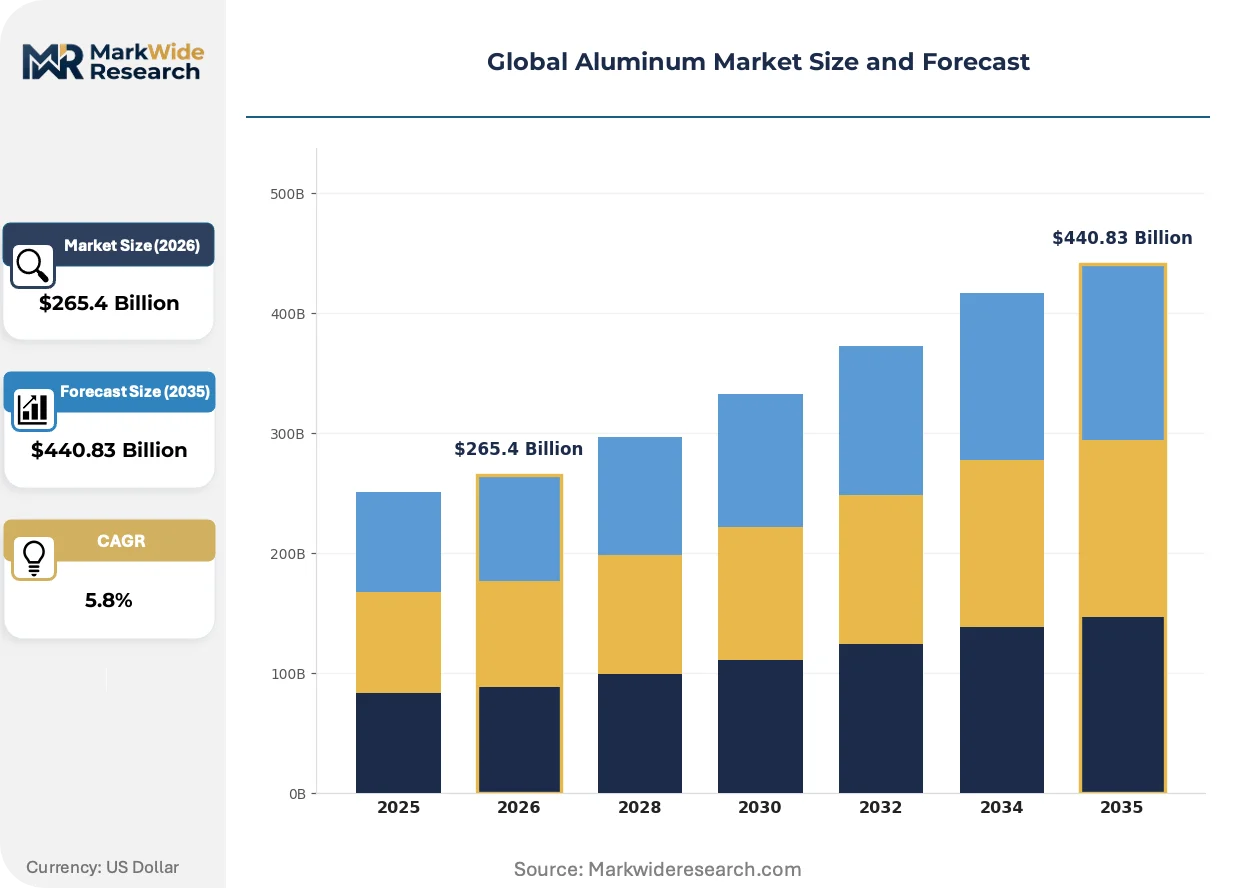
| Market Size in 2026 | $265.4 Billion |
| Market Size in 2035 | $440.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Aluminum, Rolled Products, Extruded Products, Aluminum Alloys Application: Packaging, Transportation, Construction, Electrical, Consumer Goods End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Shipbuilding, Aerospace Manufacturers Production Technology: Hall-Héroult Process, Recycling Process, Secondary Smelting, Continuous Casting |
| Companies Covered | China Hongqiao Group, Aluminum Corporation of China Limited (CHALCO), UC RUSAL, Rio Tinto, Alcoa Corporation, Emirates Global Aluminium (EGA), Norsk Hydro ASA, Xinfa Group, Vedanta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Market Strategic Shifts & Innovations
Electrification of transport and energy infrastructure is compressing product development cycles while carbon accounting tools are embedding into procurement workflows. Three forces are restructuring competitive advantage.
Inert anode technology is collapsing the carbon footprint of primary smelting by eliminating CO2 emissions from conventional carbon anode consumption. Rio Tinto and Alcoa pilot installations in Quebec and Iceland are validating commercial scalability. This innovation is collapsing the premium gap between primary and recycled aluminum in European specialty contracts.
China's Ministry of Ecology and Environment dual carbon goals are capping smelter capacity in Inner Mongolia and Xinjiang while permitting expansion in hydro-rich southwestern provinces. This geographic rebalancing is fragmenting Chinese supply chains and forcing European traders to diversify origin documentation. Fabricators in Germany and France are now qualifying Yunnan-sourced metal separately from Xinjiang material.
Automotive OEMs are consolidating aluminum procurement through direct long-term offtake agreements with Gulf smelters, bypassing traditional merchant traders and LME warehouse financing structures. BMW and Mercedes-Benz now contract directly with Emirates Global Aluminium for body-in-white sheet supply. This disintermediation is most advanced in Germany, where just-in-sequence manufacturing demands volume certainty and carbon traceability.
Global Aluminum Market Segmentation
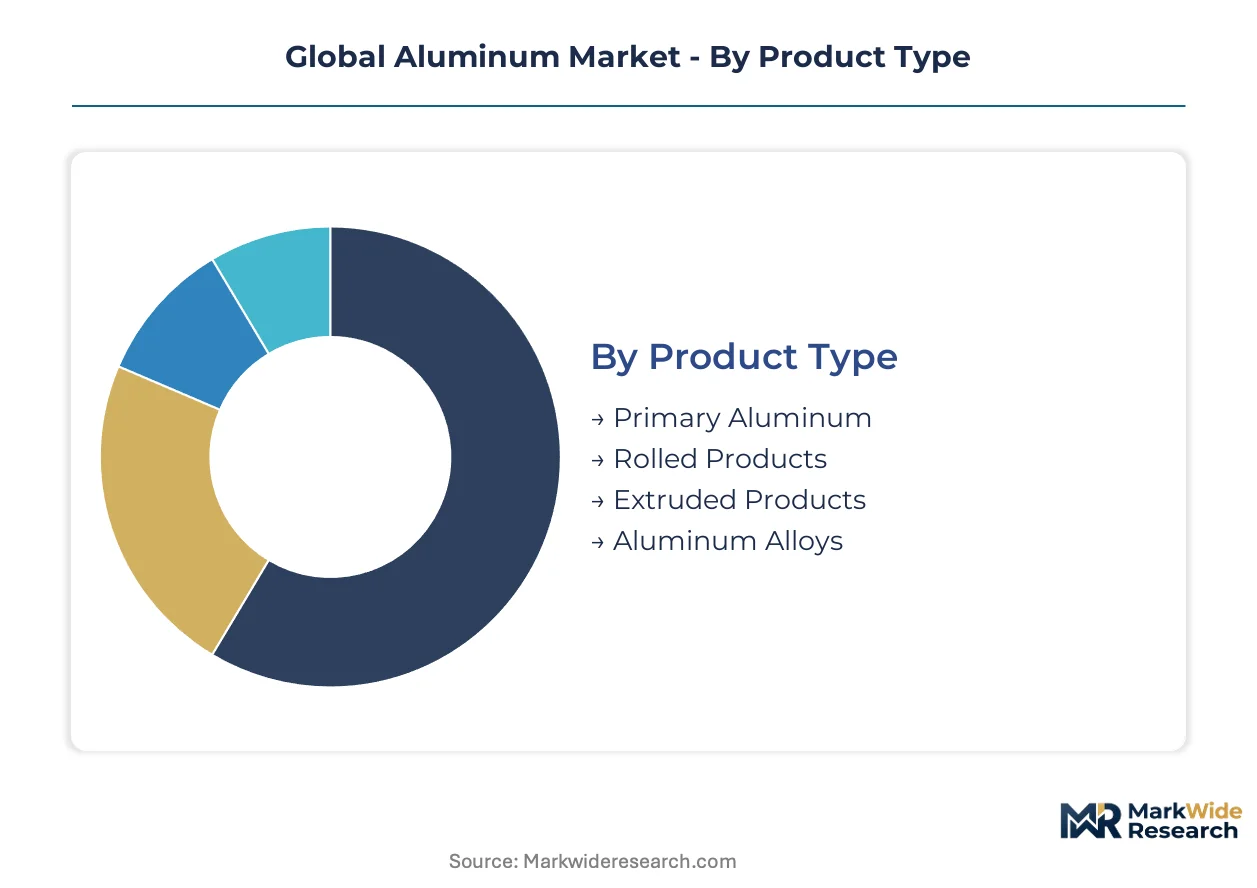
Aluminum market segmentation reveals how material specifications, carbon intensity credentials, and fabrication methods determine contract eligibility across automotive, packaging, and energy infrastructure value chains. Distinct buyer requirements for body-in-white sheet versus solar frame extrusions create non-overlapping supplier qualification pathways.
Product Type:
Cost tier differentiation separates commodity-grade primary metal from value-added fabricated products commanding carbon premiums and technical specifications.
- Primary Aluminum:Electrolytically reduced metal from alumina feedstock, with carbon intensity varying from 4-20 tonnes CO2 per tonne of aluminum depending on power source. Demand concentrates in China as domestic smelters relocate capacity to hydro-rich Yunnan and Guangxi provinces to meet EU Carbon Border Adjustment Mechanism thresholds.
- Rolled Products:Continuously cast and hot-rolled sheet and foil, including beverage can stock and automotive body panels requiring surface quality and gauge precision. European automotive OEMs source directly from Gulf smelters through long-term offtake agreements that bypass traditional merchant trading structures.
- Extruded Products:Profile shapes formed by forcing heated billet through hardened steel dies, serving solar panel frames and EV battery enclosures.
- Aluminum Alloys:Engineered compositions with copper, magnesium, silicon, or zinc additions achieving tensile strengths from 70 to 700 MPa.
Rolled products command the established base. The steepest expansion runs through extruded products.
Application:
End-use application determines alloy selection, surface treatment requirements, and carbon traceability documentation intensity.
- Packaging:Thin-gauge foil and rigid container sheet prioritizing barrier properties and formability. European beverage can makers now require mass-balance certified low-carbon aluminum to meet EU Green Deal emissions benchmarks.
- Transportation:Structural and closure panels for light-duty vehicles, heavy trucks, and rail rolling stock where weight reduction directly improves energy efficiency. Extruded aluminum profiles displace steel in EV battery housings as manufacturers pursue aggressive weight targets.
- Construction:Curtain wall systems, roofing, and structural framing requiring corrosion resistance and architectural finish durability.
- Electrical:Conductor cable, busbar, and transformer winding applications exploiting aluminum's conductivity-to-weight ratio.
- Consumer Goods:Appliances, electronics enclosures, and furniture where aesthetic finish and cost efficiency dominate specification.
Transportation absorbs the largest volume share. Packaging is gaining share fastest on carbon-labeling requirements.
End User:
Customer type dictates procurement scale, technical service intensity, and scope-three emissions audit depth.
- OEMs:Original equipment manufacturers in automotive and appliance sectors with direct smelter contracting power and dedicated metallurgical engineering staff. BMW and Mercedes-Benz now bypass traders to contract directly with Emirates Global Aluminium for body-in-white supply.
- Tier-1 Suppliers:Component fabricators and sub-assembly houses serving OEMs with just-in-sequence delivery requirements.
- Vehicle Assemblers:Final production facilities integrating aluminum-intensive platforms with mixed-material structures.
- Shipbuilding:Naval and commercial vessel constructors specifying marine-grade alloys with saltwater corrosion resistance.
- Aerospace Manufacturers:Airframe and engine component producers requiring aerospace-grade alloys with full lot traceability and NADCAP-certified processing.
OEMs dominate procurement volume. Tier-1 suppliers are expanding most quickly on outsourcing trends.
Production Technology:
Process maturity and capital intensity separate established electrolytic methods from emerging low-carbon alternatives.
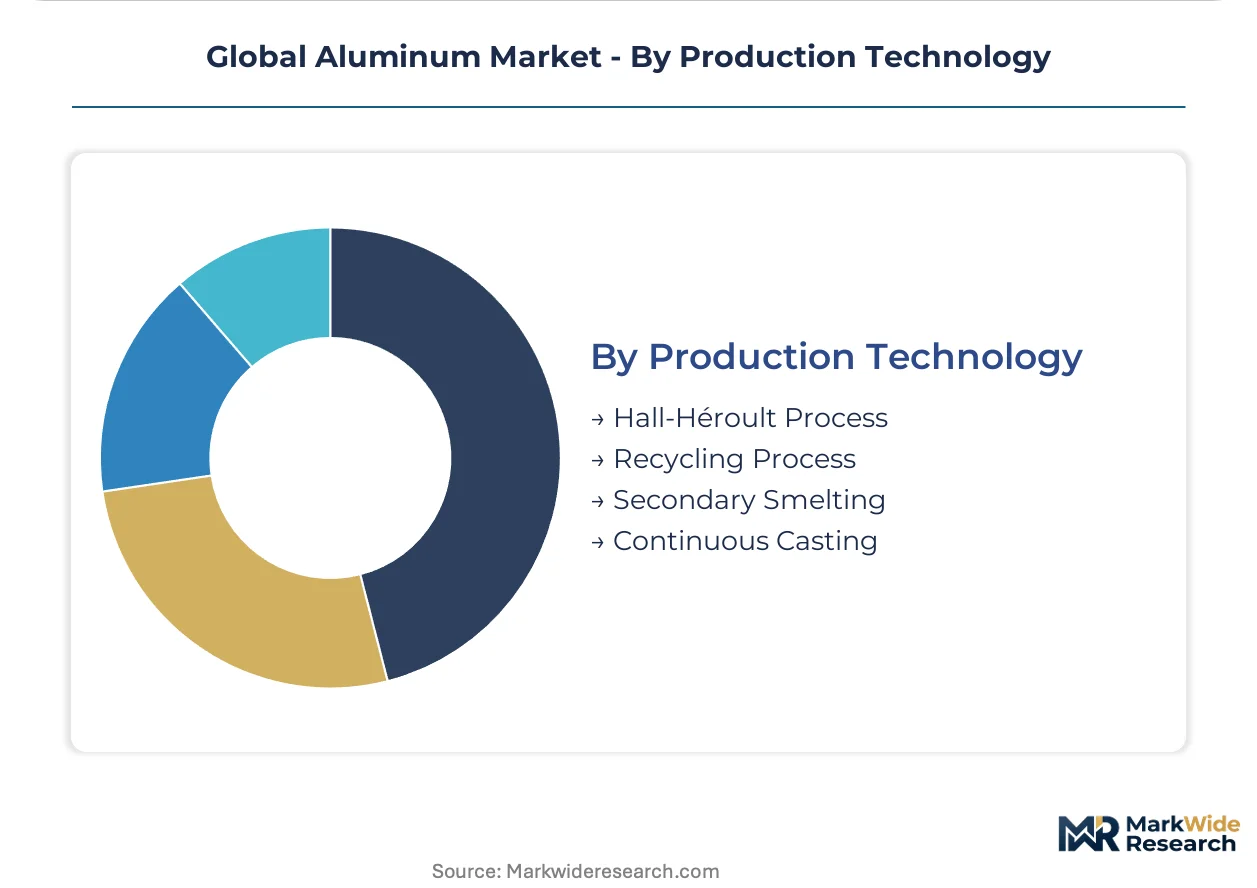
- Hall-Héroult Process:Conventional electrolytic reduction using carbon anodes, accounting for the majority of primary production. Rio Tinto and Alcoa pilot inert anode installations in Quebec and Iceland are validating commercial scalability without CO2 emissions from anode consumption.
- Recycling Process:Remelting of post-consumer and industrial scrap with 95% energy reduction versus primary production. North American and European post-consumer scrap collection infrastructure is capturing expanding margin pools as circular economy regulations tighten.
- Secondary Smelting:Reprocessing of aluminum dross and process skimmings to recover metallic content.
- Continuous Casting:Direct solidification of molten metal into semi-finished forms without intermediate ingot remelting.
Hall-Héroult Process retains the installed base. The recycling process is climbing the fastest on energy cost arbitrage and regulatory preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Carbon Border Adjustment Mechanism and the US Inflation Reduction Act are redirecting investment toward low-carbon smelting capacity in hydro-rich geographies. Production economics now hinge on power sourcing verification and emissions certification protocols. Fabricators in Germany, the United States, and China are requalifying supplier networks to meet divergent regulatory thresholds.
China
Electric vehicle battery enclosure demand and solar panel frame production are absorbing record volumes of extruded aluminum profiles. The Ministry of Ecology and Environment enforces dual carbon goals that cap smelter capacity in Inner Mongolia while permitting expansion in hydro-rich Yunnan and Guangxi. Smelter clusters in Yunnan's Wenshan and Guangxi's Baise are adding low-carbon primary capacity to meet EU Carbon Border Adjustment Mechanism thresholds.
Germany
BMW and Mercedes-Benz are contracting directly with Gulf smelters for body-in-white sheet supply, bypassing traditional merchant traders. The EU Green Deal's emissions benchmarks and Carbon Border Adjustment Mechanism force fabricators to certify carbon intensity across tier-three supply chains. Automotive aluminum processing concentrates in Baden-Württemberg's Stuttgart region and Bavaria's Ingolstadt corridor, where just-in-sequence manufacturing demands volume certainty.
United States
The Inflation Reduction Act's domestic content requirements for renewable energy projects favor North American aluminum sourcing for solar and wind infrastructure. The Environmental Protection Agency and Securities and Exchange Commission climate disclosure rules tighten scope-three reporting requirements for aluminum purchasers. Primary and recycled metal processing clusters in the Pacific Northwest and Ohio River Valley are capturing expanding margin pools from post-consumer scrap collection infrastructure.
United Arab Emirates
Emirates Global Aluminium anchors supply security through captive bauxite mining in Guinea and integrated alumina refining at Al Taweelah. The country's national industrial regulator enforces emissions benchmarks aligned with EU import requirements. Smelting and downstream fabrication concentrate in Abu Dhabi's Khalifa Industrial Zone, where long-term offtake agreements with European automotive OEMs are replacing quarterly spot pricing.
Iceland
Rio Tinto and Alcoa pilot inert anode installations are validating commercial scalability of zero-CO2 primary smelting technology. The country's renewable energy authority certifies geothermal and hydro power sourcing for carbon-intensity documentation. Smelter operations in the Reykjanes Peninsula and eastern fjords are supplying specialty low-carbon aluminum premiums to European packaging and automotive contracts.
Global Aluminum Market Key Industry Players
On the supply side, the industry is consolidating around integrated producers with captive bauxite access and verified low-carbon power sourcing. Smelters without emissions certification face exclusion from EU and North American automotive qualification pathways. Three archetypes dominate: state-backed Chinese conglomerates with domestic market priority, Gulf-based integrated miners with African bauxite control, and Nordic hydro-powered specialists with proprietary cell technology. Capacity relocation toward hydro-rich geographies and direct OEM offtake contracting are the dominant competitive moves reshaping market access.
Among Chinese state-linked producers, China Hongqiao Group and Aluminum Corporation of China Limited exemplify the scale-driven archetype with integrated alumina-to-smelter operations. UC RUSAL occupies a position representing the low-carbon hydro-powered tier through Siberian smelter assets. Emirates Global Aluminium anchors the Gulf-based integrated model with captive Guinean bauxite supply. These three producers represent divergent strategic pathways—domestic market depth, carbon-premium European access, and upstream resource control—each shaping contract eligibility in distinct regional markets.
| Leading Market Players |
|---|
| China Hongqiao Group |
| Aluminum Corporation of China Limited (CHALCO) |
| UC RUSAL |
| Rio Tinto |
| Alcoa Corporation |
| Emirates Global Aluminium (EGA) |
| Norsk Hydro ASA |
| Xinfa Group |
| Vedanta |
| Others |
Cost & Logistics Intelligence
Yunnan's Wenshan smelter cluster is adding low-carbon primary capacity that strengthens Chinese producers' pricing power in European specialty contracts subject to EU Carbon Border Adjustment Mechanism thresholds. Gulf smelters with captive Guinean bauxite supply now command premium positioning against merchant traders in long-term automotive offtake negotiations.
Pricing Analysis
Certification level creates the primary spread between commodity-grade primary metal and low-carbon premiums validated for EU Green Deal compliance. Contract-based long-term offtake agreements dominate automotive and packaging procurement, displacing quarterly spot pricing as OEMs seek volume certainty. Price differentiation rests on carbon intensity documentation and hydro-powered smelter origin, with Inner Mongolia coal-based metal facing the steepest discount pressure. Tier-1 automotive fabricators show lowest price sensitivity due to just-in-sequence manufacturing requirements, while merchant traders face margin compression from disintermediation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as competitive tools for Gulf integrated producers securing European automotive qualification. Bauxite supply concentrates in Guinea and Australia, exposing smelters to freight cost volatility and geopolitical risk premiums. Raw material dependencies include alumina refining capacity, metallurgical coke for Soderberg cells, and caustic soda for Bayer process operations. Single-source vulnerability runs through Chinese smelter dominance exceeding half of global primary production. Distribution runs through direct smelter-to-OEM contracting that bypasses traditional LME warehouse financing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global aluminum demand sits in early-cycle expansion as electric vehicle battery enclosure adoption accelerates weight-reduction mandates across automotive platforms. Penetration of extruded profiles in solar panel frames and renewable energy infrastructure is creating new volume anchors beyond traditional transportation and packaging.
For Market Incumbents: Harden carbon traceability systems to defend EU and North American contract eligibility against emerging hydro-powered competitors in Iceland and Quebec. Invest in captive bauxite access or backward integration into alumina refining to offset Guinea supply concentration risk. Prioritize HAL4e Ultra cell technology licensing to capture engineering talent scarcity premiums. For New Entrants and Emerging Players: Pursue India post-consumer scrap infrastructure as the most penetrable recycling market with underdeveloped collection networks and tightening circular economy regulations. Target solar panel frame extrusion contracts for utility-scale photovoltaic developers qualifying for US Inflation Reduction Act domestic content incentives. Position around regional scrap processing hubs with proximity to automotive manufacturing corridors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with verified low-carbon power sourcing and direct OEM offtake relationships. Long-term viability over the next decade hinges on emissions certification depth and geographic diversification beyond coal-dependent Chinese supply. Monitor inert anode commercialization timelines at Rio Tinto and Alcoa pilot installations as the critical inflection signal for primary smelting cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Relocation to Hydro-Rich Geographies | Yunnan and Guangxi smelter expansion meets EU Carbon Border Adjustment Mechanism thresholds for European market access. |
| Direct OEM Long-Term Offtake Agreements | BMW and Mercedes-Benz contracts with Emirates Global Aluminium disintermediate traditional merchant trading structures. |
| Inert Anode Technology Commercialization | Rio Tinto and Alcoa pilot installations in Quebec and Iceland validate zero-CO2 primary smelting scalability. |
| Post-Consumer Scrap Infrastructure Investment | North American and European circular economy regulations tighten, expanding recycling margin pools. |
| Captive Bauxite Mining Integration | Emirates Global Aluminium's Guinean mining assets anchor supply security against alumina input cost volatility. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with smelter operations managers, automotive OEM procurement directors, Tier-1 fabricator metallurgical engineers, renewable energy project developers, and commodity trading risk officers. Secondary validation drew from customs and trade flow databases, International Aluminium Institute production statistics, SEC filings from listed producers, EU Carbon Border Adjustment Mechanism regulatory texts, and power grid disclosure reports from hydro-rich provinces. Bottom-up capacity and consumption modeling was triangulated against top-down macroeconomic drivers.
Calibration against historical capacity utilization rates and contract pricing disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, carbon intensity tier, end-use application, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity commissioning timelines. Industry-specific forecast inputs incorporated electric vehicle platform aluminum content trajectories and solar panel installation growth curves.
Sensitivities concentrate around EU Carbon Border Adjustment Mechanism implementation timelines, Chinese dual carbon goal enforcement intensity, and inert anode technology commercialization pace. Forecasts reflect assumptions regarding power sourcing verification protocols and scope-three emissions audit standardization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Duplex Stainless Steel Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Ferrochrome Market
Metals
Palladium Market
Metals
Aluminum Extrusion Market
Metals
Global Brass Rods Market
Metals
US Metal Fabrication Market
Metals
Recycled Metal Market
Metals
Platinum Group Metals Market
Metals
Europe Aluminium Cans Market
Metals
Anodized Titanium Market
Metals
Ruthenium Market
Metals
Rolled Steel Motor Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Battery Metals Market
Metals
Aluminium Collars Market