
 India Thermic Fluid Market | 2026-2036
India Thermic Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
India Thermic Fluid Market Foresight
A capital-intensity divergence between integrated refiners and specialty blenders is rotating competitive dynamics across the India thermic fluid landscape. Shell plc leverages its global synthetic base stock supply chain to sustain premium positioning in high-temperature chemical applications. Bharat Petroleum Corporation Limited anchors its presence through backward integration into refinery streams, while Savita Oil Technologies Limited specializes in niche mineral oil formulations for mid-temperature industrial heating.
Thermic fluids are heat transfer media engineered to operate continuously between minus fifty degrees Celsius and four hundred degrees Celsius, typically formulated from refined petroleum distillates, synthetic aromatic compounds, or bio-based esters to convey thermal energy in closed-loop systems. Mineral oils retain volume leadership across India's installed base due to lower first-cost economics, though synthetic fluids command expanding share in pharmaceutical and specialty chemical operations where thermal stability beyond three hundred degrees Celsius prevents fluid degradation. Chemical processing and industrial heating applications together absorb the majority of domestic offtake, with food processing emerging as a specification-sensitive growth pocket driven by FSSAI-mandated thermal fluid safety protocols.
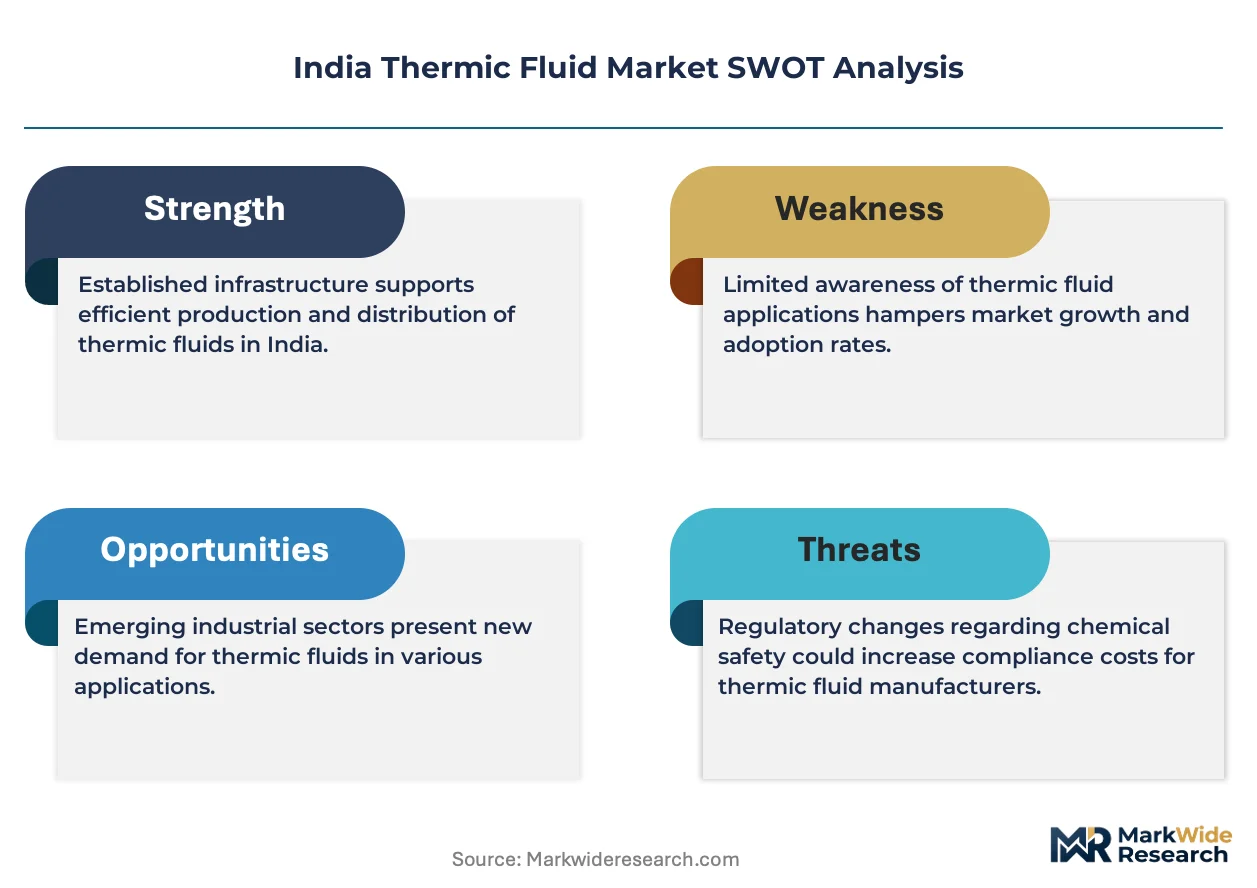
BIS fluid certification standards, CDSCO pharmaceutical manufacturing guidelines, and state-level factory inspectorate rules under the Factories Act collectively shape product compliance requirements and channel access across Indian states. The central government's PLI scheme for chemical manufacturing is inducing capacity additions that will require concurrent thermic fluid procurement at scale. Stakeholders must monitor how state pollution control board enforcement of spent fluid disposal norms reshapes total cost-of-ownership calculations for end users.
Market Dynamics
India's thermic fluid sector confronts a structural pivot as BIS certification tightening forces product reformulation across Gujarat and Maharashtra's chemical processing clusters, compressing margins for non-compliant blenders while elevating quality barriers to market entry.
Growth Catalysts
- PLI Scheme Induction:The central government's production-linked incentive scheme for chemical manufacturing is triggering capacity additions across western India, requiring concurrent thermic fluid procurement at scale for new reactor trains and distillation systems.
- FSSAI Thermal Safety Mandates:Food processing sector adoption accelerates as India's food safety regulator mandates dedicated heat transfer fluid protocols, creating specification-sensitive demand for food-grade formulations in dairy and edible oil refining.
- Petrochemical Corridor Expansion:Chemical processing plants stretching from Vadodara to Mumbai are expanding high-temperature operations, driving replacement cycles and greenfield fluid installations across Maharashtra and Gujarat.
Market Restraints
- Base Oil Import Dependency:Formulators remain exposed to Group II and III base stock price volatility, with over half of domestic mineral oil feedstock sourced through Middle Eastern and Southeast Asian supply chains.
- Spent Fluid Disposal Friction:State pollution control boards under the Factories Act are enforcing stricter spent thermic fluid handling norms, elevating total cost-of-ownership calculations for end users in Tamil Nadu and Karnataka.
- Synthetic Fluid Cost Premium:Aromatic and polyalphaolefin formulations carry three to four times the first-cost burden of mineral oils, constraining penetration beyond pharmaceutical and specialty chemical niches.
Strategic Opportunities
- Bio-Based Ester Formulations:Renewable-sourced heat transfer fluids present white space for domestic blenders targeting carbon-conscious chemical processors seeking Scope 3 emissions reduction pathways.
- Southern India Industrial Heating:Underpenetrated markets in Tamil Nadu's textile processing and Karnataka's food manufacturing clusters offer expansion terrain beyond the western petrochemical corridor.
- Closed-Loop Service Contracts:Fluid lifecycle management bundling supply, monitoring, and reclamation services creates recurring revenue models distinct from commodity gallonage sales.
Industry Challenges
- Thermal Stability Testing Capacity:BIS certification requires accelerated aging protocols and degradation analysis that few domestic laboratories can execute, elongating product approval timelines for new entrants.
- Legacy System Compatibility:Synthetic fluid conversion in existing mineral oil installations demands seal replacement, system flushing, and metallurgical verification, complicating upgrade economics for mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Thermic Fluid Market |
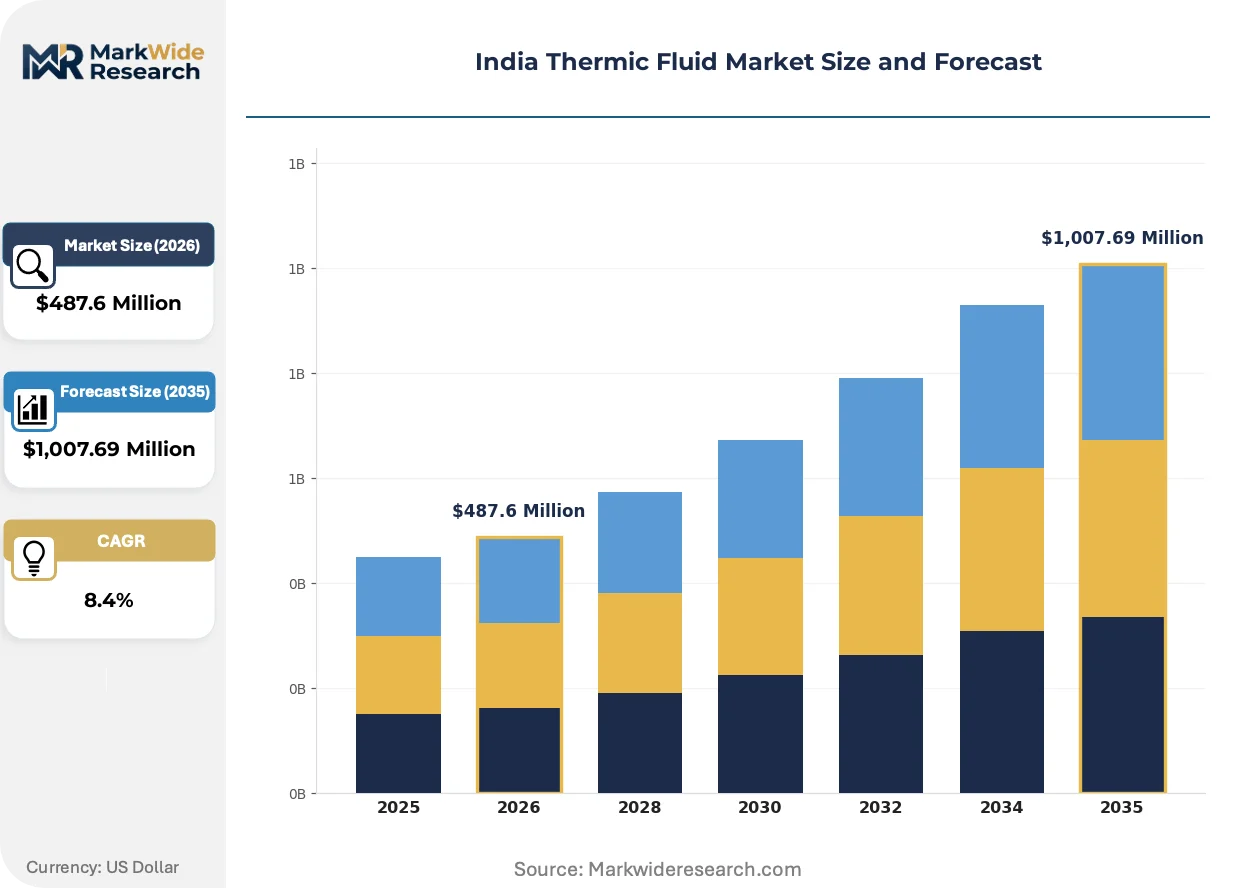
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oils, Synthetic Fluids, Biodegradable Fluids, Heat Transfer Fluids Application: Industrial Heating, Solar Heating, Food Processing, Chemical Processing End User: Manufacturing, Oil & Gas, Pharmaceuticals, Automotive Distribution Channel: Online Sales, Direct Sales, Distributors, Retailers |
| Companies Covered | Shell plc, HP Lubricants, Bharat Petroleum Corporation Limited, Eastman Chemical Company, Exxon Mobil Corporation, Hindustan Petroleum Corporation Limited, Hitech Solution (Generation Four Engitech Ltd), Savita Oil Technologies Limited, Indian Oil Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Thermic Fluid Market Shifts & Advancements
Formulation chemistry and regulatory compliance protocols are converging to reshape competitive positioning across India's thermic fluid landscape, with thermal stability thresholds and disposal accountability emerging as decisive purchase criteria.
Synthetic aromatic heat transfer fluids are displacing mineral oil formulations in chemical processing applications above three hundred degrees Celsius, with pharmaceutical manufacturers in Hyderabad and Visakhapatnam leading adoption due to CDSCO-mandated process validation requirements, compressing the addressable market for conventional petroleum-based products.
BIS fluid certification standards are tightening product quality specifications through revised testing protocols for thermal degradation resistance and oxidation stability, forcing domestic blenders to invest in laboratory infrastructure or exit the certified segment, with Maharashtra and Gujarat-based chemical processors most affected due to concentrated regulatory inspection intensity.
Buyers are consolidating fluid procurement under annual framework agreements with technical service bundling, displacing spot purchasing through distributor networks, a pattern most visible among integrated refiners and large specialty chemical houses in the Vadodara-Mumbai industrial corridor seeking predictive maintenance integration and inventory liability transfer.
India Thermic Fluid Market Segmentation
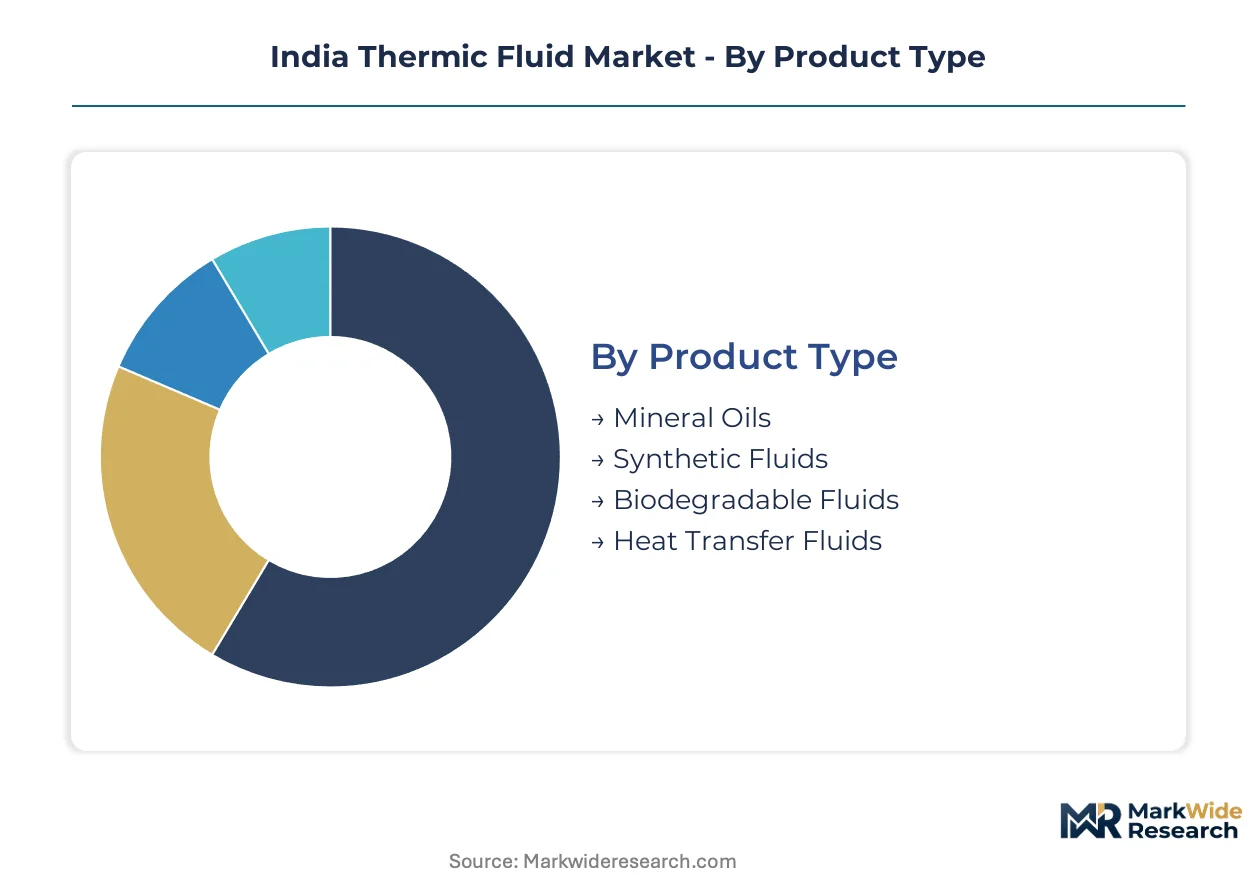
Thermic fluid procurement patterns in India diverge sharply across product chemistry, application temperature requirements, and end-user compliance obligations. Understanding these segment boundaries reveals where specification premiums command pricing power versus commodity gallonage competition.
Product Type:
Margin pools concentrate in synthetic and biodegradable formulations where technical barriers limit blender participation, while mineral oils compete on feedstock sourcing efficiency and scale economics.
- Mineral Oils:Refined petroleum distillates formulated from Group II and III base stocks dominate India's installed base through lower first-cost positioning. Demand clusters in Gujarat and Maharashtra's mid-temperature chemical processing operations where thermal stability requirements stay below three hundred degrees Celsius and BIS certification pressures remain manageable for domestic blenders.
- Synthetic Fluids:Aromatic compounds and polyalphaolefin formulations engineered for thermal stability beyond three hundred degrees Celsius command substantial specification premiums. Pharmaceutical manufacturers in Hyderabad and Visakhapatnam drive procurement volumes as CDSCO-mandated process validation requirements displace mineral oil alternatives in high-temperature reactor applications.
- Biodegradable Fluids:Bio-based ester formulations derived from renewable feedstocks target carbon-conscious processors seeking Scope 3 emissions reduction pathways.
- Heat Transfer Fluids:Broad category encompassing engineered thermal media for closed-loop energy conveyance across diverse industrial heating architectures.
Mineral oils hold installed capacity. Synthetic fluids are rotating up the share rankings.
Application:
Volume concentration tracks India's industrial geography, with chemical processing corridors generating recurrent replacement demand and food processing emerging as a compliance-driven growth vector.
- Chemical Processing:High-temperature distillation, reactor heating, and exothermic process management across Gujarat and Maharashtra's petrochemical belt absorb substantial thermic fluid volumes. Plants stretching from Vadodara to Mumbai are expanding operations and driving replacement cycles as BIS certification tightening forces fluid reformulation.
- Food Processing:Dairy pasteurization, edible oil refining, and thermal treatment operations require FSSAI-mandated food-grade formulations with dedicated safety protocols. This specification-sensitive segment accelerates adoption as India's food safety regulator enforces heat transfer fluid compliance standards.
- Industrial Heating:General manufacturing process heating across textiles, rubber, and metalworking applications constitutes a price-competitive volume segment.
- Solar Heating:Concentrated solar power and thermal storage systems represent an emerging application with specialized high-temperature stability requirements.
Chemical processing anchors current procurement volumes. Food processing is climbing the fastest as regulatory mandates reshape buyer specifications.
End User:
Customer sophistication varies dramatically, with pharmaceutical and oil & gas operators demanding technical service bundling while manufacturing procurement remains transactionally driven.
- Oil & Gas:Refinery process heating and upstream thermal management operations require thermic fluids with proven degradation resistance under continuous high-temperature exposure. Integrated refiners leverage backward integration into captive base stock supplies to control formulation costs.
- Pharmaceuticals:CDSCO-mandated process validation and batch consistency requirements drive specification-intensive procurement from validated suppliers with documented thermal stability testing capabilities.
- Manufacturing:Diverse industrial heating needs across metal fabrication, plastics, and general process industries compete primarily on total cost-of-ownership calculations.
- Automotive:Paint curing, component heat treatment, and manufacturing process heating constitute a cyclical demand segment tied to vehicle production volumes.
Manufacturing holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Distribution Channel:
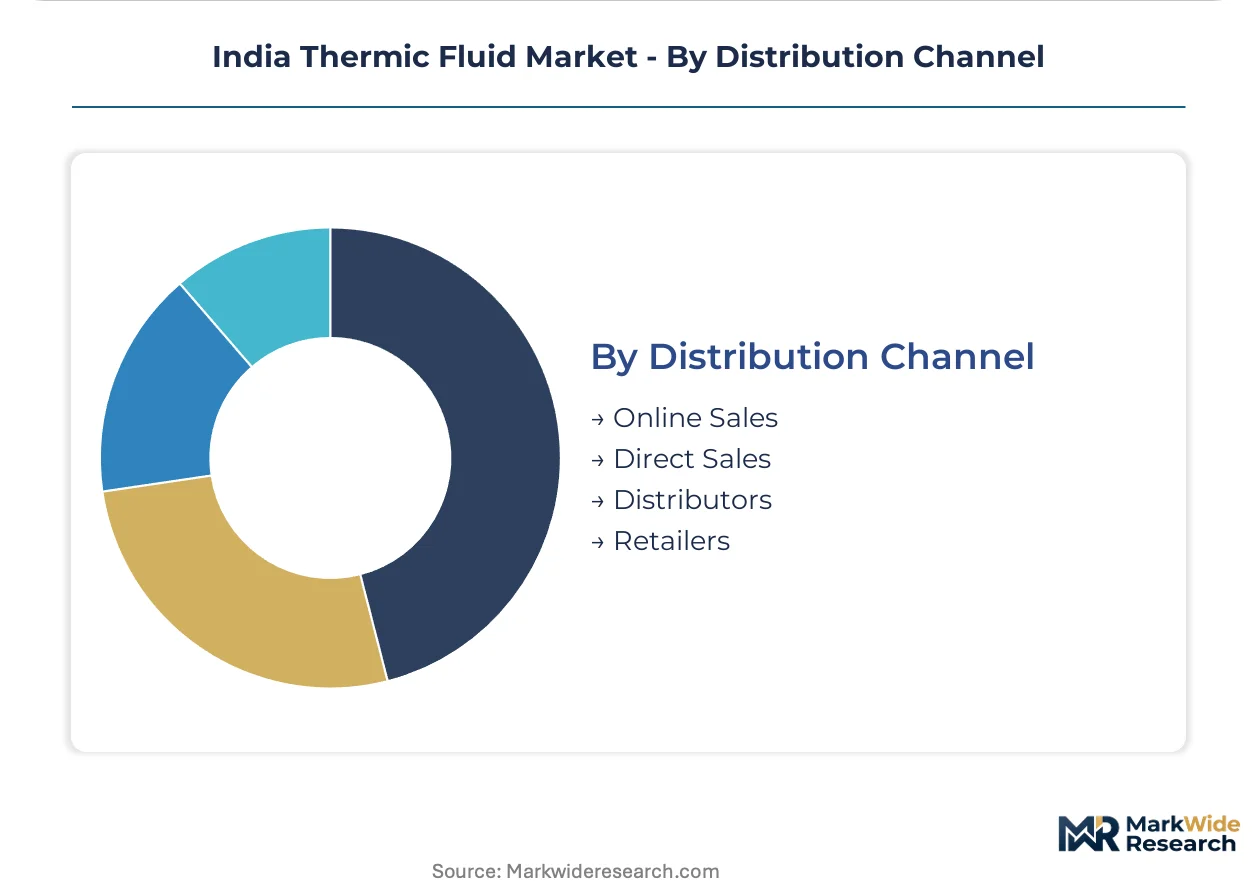
Channel economics reflect buyer scale and technical complexity, with large consumers consolidating procurement under framework agreements while smaller operators rely on distributor networks.
- Direct Sales:Integrated refiners and large specialty chemical houses in the Vadodara-Mumbai corridor negotiate annual framework agreements with technical service bundling. These arrangements transfer inventory liability and integrate predictive maintenance capabilities.
- Distributors:Regional stocking points serve mid-sized processors requiring responsive delivery and technical support without direct manufacturer relationships.
- Online Sales:Digital procurement platforms gain traction for standardized mineral oil formulations where specification complexity remains low.
- Retailers:Local supply points address emergency replenishment and small-volume maintenance requirements.
Distributors hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India's petrochemical corridor consumes thermic fluids at markedly higher temperatures than eastern manufacturing belts, where mid-temperature mineral oil formulations still dominate textile and food processing applications. Gujarat and Maharashtra together account for the majority of high-temperature synthetic fluid demand, while southern states remain underpenetrated in premium formulations.
Maharashtra
Refinery expansion at Mumbai and Ratnagiri drives synthetic fluid procurement for catalytic cracking and distillation units. The state's factory inspectorate enforces strict spent fluid disposal audits under the Factories Act, elevating compliance costs for chemical processors. The Mumbai-Pune industrial belt hosts concentrated demand from pharmaceutical manufacturers seeking CDSCO-validated heat transfer systems.
Gujarat
Dahej and Vadodara chemical complexes require continuous thermic fluid replacement for high-temperature reactor operations. BIS certification tightening forces domestic blenders to reformulate products or exit the certified segment entirely. The state's pollution control board monitors spent fluid handling at Ankleshwar and Vapi industrial estates.
Tamil Nadu
Textile processing clusters around Tiruppur and Coimbatore generate steady mineral oil demand for dyeing and finishing operations. State-level enforcement of spent fluid disposal norms lags western India, keeping total cost-of-ownership calculations lower. The region's food processing sector remains nascent in FSSAI-mandated thermal fluid adoption.
Karnataka
Edible oil refineries and dairy processors in Bengaluru and Mysuru corridors accelerate food-grade thermic fluid procurement under FSSAI safety protocols. The state's emerging pharmaceutical manufacturing base in Bengaluru Bio Corridor creates specification-sensitive demand. Karnataka pollution control board inspections are intensifying at industrial fluid handling facilities.
Telangana
Hyderabad's pharmaceutical formulation industry drives premium synthetic fluid adoption for CDSCO-mandated process validation. Genome Valley biotech clusters require thermic fluids with documented thermal stability testing. The state's industrial policy incentives attract chemical manufacturing capacity that will require concurrent heat transfer fluid procurement.
India Thermic Fluid Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in India's thermic fluid structure. National oil companies leverage captive refinery streams to control base stock costs, while international majors deploy global synthetic formulation expertise. Three archetypes dominate: integrated refiners with backward integration into base oil production, global specialists commanding premium positioning through technical service bundling, and domestic blenders competing on mineral oil volume. Competitive moves concentrate on BIS certification compliance investments and closed-loop service contract expansion.
Among international majors operating in India, Shell plc exemplifies the premium synthetic tier through its global base stock supply chain. Bharat Petroleum Corporation Limited anchors the integrated refiner archetype with captive access to Group II and III streams. Savita Oil Technologies Limited occupies a specialist position in niche mineral oil formulations for mid-temperature industrial heating applications.
| Leading Market Players |
|---|
| Shell plc |
| HP Lubricants |
| Bharat Petroleum Corporation Limited |
| Eastman Chemical Company |
| Exxon Mobil Corporation |
| Hindustan Petroleum Corporation Limited |
| Hitech Solution (Generation Four Engitech Ltd) |
| Savita Oil Technologies Limited |
| Indian Oil Corporation Ltd |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between integrated refiners and Gujarat-Maharashtra chemical processors lock in both Group II and III base stock supply access and price visibility, insulating large consumers from Middle Eastern import volatility while compressing spot-market liquidity for mid-sized blenders.
Pricing Analysis
Contract-based long-term offtake dominates procurement across the Vadodara-Mumbai corridor, with annual framework agreements bundling fluid supply and technical service. Price differentiation rests on BIS certification grade and volume scale, with certified synthetic formulations commanding substantial premiums over non-certified mineral oils. Cost compression in mid-tier mineral oils is intensifying because domestic blenders face feedstock volatility from Middle Eastern supply chains. Small textile processors in Tamil Nadu exhibit highest price sensitivity, while pharmaceutical manufacturers in Hyderabad prioritize thermal stability validation over unit economics.
Supply Chain Analysis
Inventory cycles stretch longer for synthetic aromatic formulations due to complex polyalphaolefin feedstock procurement from South Korea and Singapore. Base oil supply draws from Saudi Arabia, Kuwait, and United Arab Emirates for Group II and III mineral stocks, while synthetic precursors feed from East Asian specialty chemical producers. Single-source vulnerability concentrates in polyalphaolefin imports for high-temperature pharmaceutical applications. Distribution runs through direct sales to integrated refiners and regional distributor networks serving mid-sized processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's thermic fluid sector represents an early-cycle expansion story, with FSSAI-mandated food-grade adoption and PLI-scheme chemical capacity additions driving penetration beyond legacy mineral oil installations.
For Market Incumbents: Fortify BIS certification compliance through laboratory infrastructure investment in Maharashtra and Gujarat, where regulatory inspection intensity is compressing non-compliant blenders. Deepen backward integration into captive refinery streams to offset Middle Eastern base oil import volatility. Prioritize closed-loop service contract expansion to displace spot gallonage competition from distributor networks.
For New Entrants and Emerging Players: Lead with bio-based ester formulations targeting carbon-conscious chemical processors in Karnataka's emerging food processing corridor, where FSSAI safety protocols are reshaping procurement specifications. Exploit underpenetrated solar heating applications requiring specialized high-temperature stability. Deploy technical service bundling as primary go-to-market mechanism to differentiate from commodity mineral oil distributors.
For Investors and Strategic Acquirers: Domestic blenders with validated BIS testing capabilities and established relationships with western India chemical processors present attractive consolidation targets. Long-term viability hinges on regulatory compliance moats rather than feedstock scale economics. Monitor state pollution control board enforcement intensity as inflection indicator for total cost-of-ownership dynamics affecting end-user switching behavior.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Quality barriers are forcing laboratory infrastructure spending across Gujarat and Maharashtra blenders. |
| Backward Integration into Base Stocks | Captive refinery streams insulate Bharat Petroleum and Indian Oil from Middle Eastern import volatility. |
| Closed-Loop Service Contracts | Predictive maintenance bundling transfers inventory liability from pharmaceutical manufacturers in Hyderabad. |
| Bio-Based Ester Development | Renewable feedstock formulations target Scope 3 emissions reduction for carbon-conscious processors. |
| Southern India Geographic Expansion | Tamil Nadu textile clusters and Karnataka food processing offer underpenetrated mineral oil conversion opportunities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS certification registries, and state pollution control board enforcement records across Indian industrial clusters. Plant managers at Gujarat and Maharashtra chemical processors, procurement leads at pharmaceutical manufacturers in Hyderabad and Visakhapatnam, and distribution channel partners in Tamil Nadu textile belts provided operational perspective. Bottom-up installation base enumeration triangulates against top-down refinery output and import parity calculations for Group II and III base stocks.
Segmentation dimensions modeled span product chemistry tier, application temperature requirement, end-user compliance obligation, and regional regulatory enforcement intensity across the analysis window. CAGRs derive from elasticity-adjusted replacement cycle projections and greenfield capacity addition schedules tied to PLI scheme disbursements. Forecast inputs incorporate BIS certification timeline elongation and state-level spent fluid disposal cost trajectories.
Underlying assumptions cover sustained PLI scheme chemical manufacturing incentives and FSSAI enforcement continuity, with deviation risk concentrated in Middle Eastern base oil supply disruptions and unanticipated BIS testing protocol revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Decahydronaphthalene (Decalin) Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Slimicides Market