
 Aluminum Slugs Market | 2026-2036
Aluminum Slugs Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Slugs Market Analysis
Beverage and cosmetics packaging is shifting toward aluminum slugs as brand owners abandon multi-layer plastic laminates. Novelis leverages closed-loop recycling systems to secure feedstock for high-purity slug production. Hydro Aluminum anchors Nordic supply through hydropower-smelting integration that lowers carbon intensity per ton. Constellium competes on specialized alloy formulations for pressurized aerosol applications.
Aluminum slugs are cylindrical or shaped blanks punched from rolled aluminum sheet, typically in 1070 or 1050 alloy grades with thickness tolerances of ±0.05 mm, intended for impact extrusion into collapsible tubes, aerosol cans, and technical containers. Round slugs dominate volume due to standardized tooling across impact extrusion lines, while custom shapes capture margin pools from pharmaceutical and luxury cosmetics buyers requiring proprietary container geometries. Secondary manufacturing stages are expanding fastest as toll processors add precision edging and annealing services to capture value beyond raw slug supply.
EPA regulations on volatile organic compounds from aerosol propellants and REACH substance restrictions on certain alloy additives shape product formulation and surface treatment choices across North American and European supply chains. FDA food-contact material standards and EU Packaging and Packaging Waste Directive recycling targets further constrain alloy selection and post-consumer content claims. Stakeholders must monitor evolving carbon-border adjustment mechanisms and verify scope-three emissions data from primary aluminum suppliers to maintain contract eligibility with multinational packaging buyers.
Market Dynamics
Carbon-border adjustment mechanisms are forcing aluminum slug producers to restructure supplier relationships and verify scope-three emissions data to retain multinational packaging contracts.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Packaging converters in Germany accelerate sourcing from low-carbon primary aluminum to preempt tariff exposure on imported feedstock.
- Beverage industry:Brand owners abandon multi-layer plastic laminates for aluminum aerosol and tube components, expanding slug orders from cosmetics and pharmaceutical packaging producers.
- Hydropower-smelting integration:Nordic producers leverage renewable energy to lower carbon intensity per ton, securing preferred supplier status with sustainability-mandated buyers.
Market Restraints
- Primary aluminum price volatility:Energy cost fluctuations in smelting regions transmit directly to slug feedstock economics, compressing processor margins.
- REACH substance restrictions:ECHA limitations on certain alloy additives constrain surface treatment chemistry options for European manufacturers.
- Steel aerosol substitution:Tinplate alternatives retain cost advantage in price-sensitive personal care segments, capping aluminum penetration.
Strategic Opportunities
- Secondary manufacturing services:Toll processors capture margin expansion by adding precision edging and annealing services beyond raw slug supply.
- Pharmaceutical packaging:Custom-shaped slugs for proprietary container geometries command premium pricing from luxury cosmetics and medical device buyers.
- Closed-loop recycling systems:Integrated scrap recovery programs align with EU Packaging and Packaging Waste Directive recycling targets, securing long-term supply agreements.
Industry Challenges
- Scope-three emissions verification:Procurement teams lack standardized tools to audit primary aluminum supplier carbon data, delaying contract renewals.
- Impact extrusion tooling reconfiguration:Converters face capex burdens when shifting between round and custom-shaped slug formats to serve fragmented end-use demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Slugs Market |
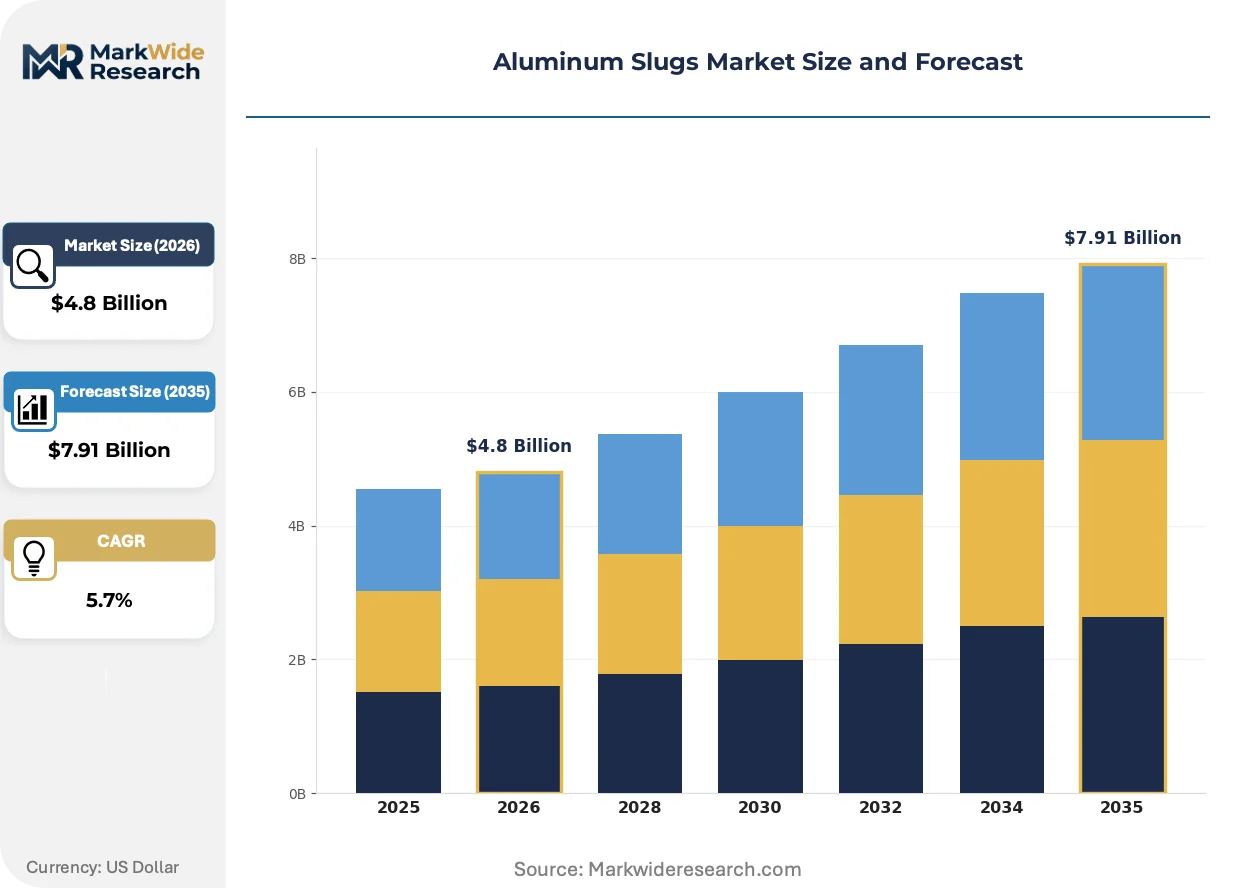
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Slugs, Rectangular Slugs, Custom Shapes, Stamped Parts End User: Packaging, Automotive, Electronics, Consumer Goods Manufacturing Stage: Primary, Secondary, Tertiary, Value-Added Processes Feature: High Purity, Lightweight, Corrosion Resistance, Custom Dimensions |
| Companies Covered | Alcoa, Novelis, Hydro Aluminum, Constellium, Talum, Impol, Neuman Aluminium, Rheinfelden, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Slugs Market Emerging Trajectories
Digital traceability systems and alloy formulation advances are compressing quality assurance timelines while expanding the addressable market for high-performance container applications.
Continuous casting technology for 1070 and 1050 alloy grades is absorbing tolerance requirements that previously demanded multiple rolling and annealing stages. Aerosol and tube manufacturers in Germany adopt these streamlined inputs to reduce in-process inventory. The technology is absorbing capital that would otherwise flow to conventional hot-rolling capacity expansions.
REACH substance restrictions on specific alloy additives are compelling reformulation of surface treatment chemistries across European supply chains. ECHA enforcement timelines pressure processors to qualify alternative passivation coatings before renewal deadlines. Cosmetic packaging converters face the tightest compliance windows due to direct skin-contact regulatory exposure.
Direct mill relationships are displacing distributor intermediaries for volume slug procurement by large impact extrusion houses. German and Austrian converters consolidate purchasing through long-term offtake agreements with Novelis and Hydro Aluminum. This concentration is most pronounced in beverage and pharmaceutical packaging segments where lot traceability requirements exceed distributor capabilities.
Aluminum Slugs Market Segmentation
Aluminum slugs serve distinct performance requirements across impact extrusion, deep drawing, and precision stamping workflows. Segmentation reveals where volume economies clash with premium customization, and which manufacturing stages capture margin expansion.
Product Type:
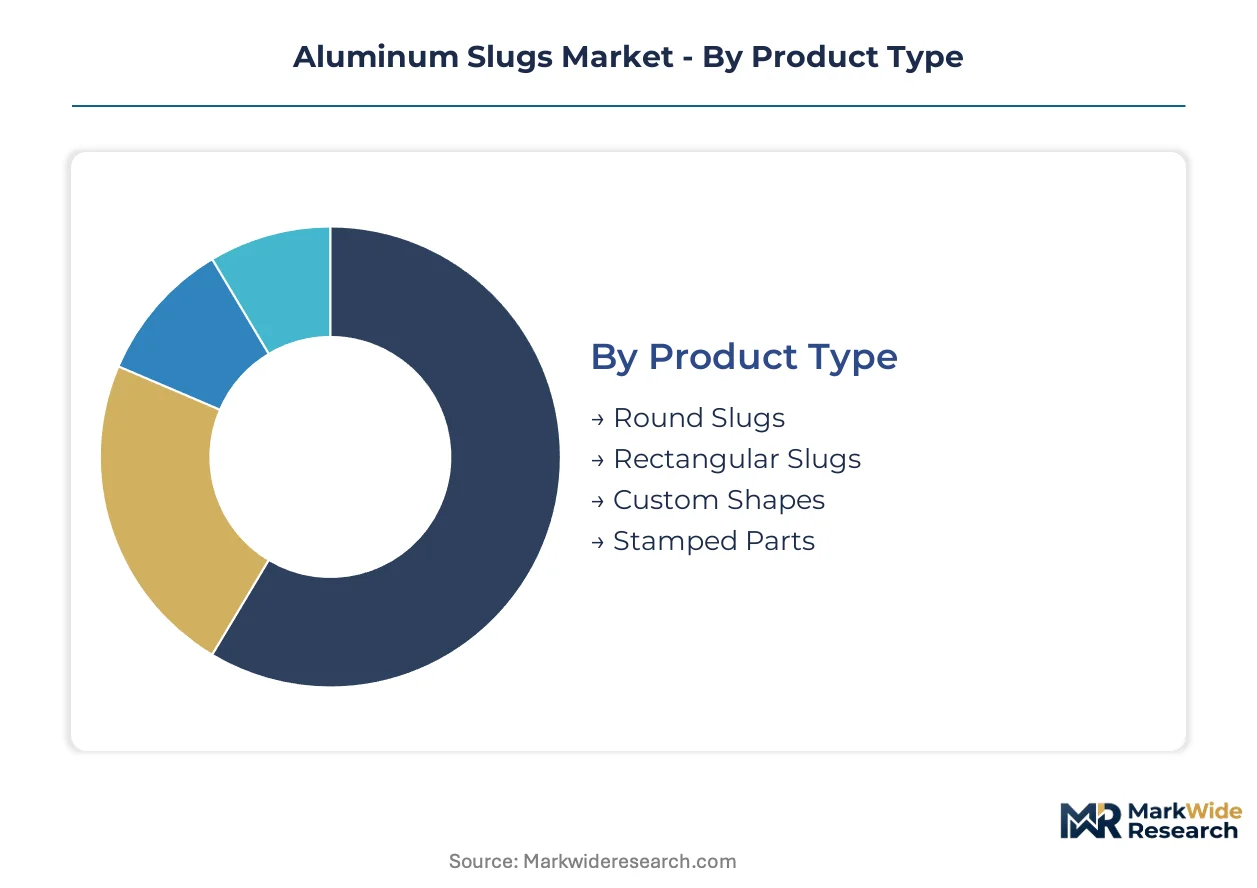
Round slugs dominate tonnage while custom shapes extract margin premiums from specialized buyers.
- Round Slugs:Cylindrical blanks in 1070 and 1050 alloy grades with ±0.05 mm thickness tolerances, punched from rolled sheet for standardized impact extrusion tooling. Beverage aerosol and tube manufacturers in Germany concentrate procurement here due to interchangeable die configurations across high-speed production lines.
- Custom Shapes:Proprietary geometries engineered for pharmaceutical and luxury cosmetics containers requiring unique grip profiles or branding embossments. These configurations command pricing premiums from medical device and prestige beauty buyers who specify lot-traceable alloy certification.
- Rectangular Slugs:Blanked profiles for technical container applications and specialized closure systems.
- Stamped Parts:Pre-formed components for assembly-integrated packaging solutions.
Today's leader: Round Slugs. Tomorrow's challenger: Custom Shapes.
End User:
Packaging converters drive volume while automotive applications test alloy performance limits.
- Packaging:Collapsible tubes, aerosol cans, and technical containers for cosmetics, pharmaceuticals, and food products. REACH substance restrictions and EU Green Deal carbon-border adjustments are tightening material traceability requirements across European supply chains.
- Automotive:Lightweight structural components and thermal management parts where 1070 alloy purity standards intersect with crashworthiness specifications.
- Electronics:EMI shielding housings and heat sink precursors requiring precise dimensional stability.
- Consumer Goods:Premium appliance trim and recreational equipment components.
Packaging absorbs the highest slug tonnage. Automotive applications are climbing fastest as electrification intensifies lightweighting mandates.
Manufacturing Stage:
Secondary and tertiary services are capturing value that raw slug producers previously relinquished.
- Secondary:Precision edging, annealing, and surface conditioning performed by toll processors. These services expand margin pools as German and Austrian converters outsource preparation steps to qualify for multinational packaging contracts.
- Value-Added Processes:Integrated scrap recovery, lot-traceable certification, and direct mill relationships that displace distributor intermediaries.
- Primary:Basic slug punching from rolled aluminum sheet without subsequent treatment.
- Tertiary:Final finishing and packaging for just-in-time delivery to impact extrusion houses.
Secondary services currently command the steepest margin expansion. Value-Added Processes are gaining share fastest as carbon-border mechanisms force scope-three emissions verification.
Feature:
High purity and corrosion resistance separate specification-grade from commodity supply.
- High Purity:1070 and 1050 alloy grades with controlled iron and silicon content for food-contact and pharmaceutical compliance. FDA standards and EU Packaging and Packaging Waste Directive recycling targets constrain alloy selection and post-consumer content claims.
- Corrosion Resistance:Passivation coatings and surface treatments reformulated to meet ECHA enforcement timelines on restricted alloy additives.
- Lightweight:Thickness-optimized profiles for transportation cost reduction.
- Custom Dimensions:Tolerance-specified blanks for proprietary tooling configurations.
High Purity dominates contract eligibility. Corrosion Resistance specifications are expanding most quickly as cosmetic packaging converters face direct skin-contact regulatory exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping aluminum slug production geography as producers migrate toward jurisdictions with lower carbon-compliance costs and renewable energy access. The EU Green Deal carbon-border adjustment mechanism creates a cost-of-compliance gap that favors Nordic hydropower regions and penalizes coal-intensive primary aluminum imports.
Germany
Cosmetics and pharmaceutical packaging converters in the Cologne-Düsseldorf corridor drive concentrated slug demand for aerosol and tube applications. ECHA enforcement of REACH substance restrictions on alloy additives compels surface treatment reformulation across Baden-Württemberg processing clusters. Bavaria's dense network of impact extrusion houses anchors procurement through direct mill relationships with Novelis and Hydro Aluminum.
United States
EPA regulations on volatile organic compounds from aerosol propellants shape formulation choices for personal care and household product packaging. The Southeast's growing beverage packaging manufacturing base expands orders for lightweight aluminum components. Ohio and Pennsylvania host legacy metalworking infrastructure that toll processors leverage for precision edging and annealing services.
China
Dual carbon goals and MEE emissions standards are tightening smelter operations in Shandong and Henan provinces. The Yangtze River Delta's packaging machinery ecosystem generates sustained demand for standardized round slugs. Zhengzhou-based fabricators supply domestic impact extrusion lines serving cosmetics export manufacturing.
Norway
Hydropower-smelting integration delivers carbon intensity advantages that secure preferred supplier status with sustainability-mandated European buyers. Novelis and Hydro Aluminum operations near Årdal and Sunndal feed high-purity feedstock into German and Austrian converter supply chains. Nordic producers capture margin premiums through scope-three emissions verification that satisfies EU Green Deal contract eligibility.
India
BIS standards and FSSAI food-contact regulations constrain alloy selection for pharmaceutical and cosmetics packaging applications. Maharashtra's Mumbai-Pune industrial corridor concentrates demand from domestic personal care brand owners shifting from plastic laminates. Gujarat's chemical processing infrastructure supports surface treatment capabilities for export-oriented slug finishing.
Aluminum Slugs Market Vendor Landscape
Capacity expansion dominates the current landscape as producers add precision edging and annealing services to capture value beyond raw slug supply. The vendor base organizes around three strategic archetypes: integrated primary aluminum producers with captive slug operations, specialized toll processors offering secondary manufacturing services, and regional fabricators serving fragmented local demand. M&A activity concentrates among European toll processors seeking geographic coverage, while technology licensing agreements spread continuous casting capabilities across Asian supply chains.
Among integrated primary aluminum producers, Novelis and Hydro Aluminum exemplify the scale-driven archetype through closed-loop recycling systems and hydropower-smelting integration. Constellium occupies a position within the specialized alloy formulation tier, serving pressurized aerosol applications requiring material performance verification. These three anchors demonstrate how carbon-border compliance capabilities and direct mill relationships are displacing distributor intermediaries for volume procurement by multinational packaging converters.
| Leading Market Players |
|---|
| Alcoa |
| Novelis |
| Hydro Aluminum |
| Constellium |
| Talum |
| Impol |
| Neuman Aluminium |
| Rheinfelden |
| Ball Corporation |
| Others |
Supply Flow & Price Mechanics
LME aluminum cash contract volatility cascades through slug feedstock economics, compressing processor margins when energy costs spike in smelting regions and forcing tiered contract structures that separate carbon-certified premiums from commodity spot exposure.
Pricing Analysis
Distributor margin compression is accelerating direct mill relationships as German and Austrian converters consolidate purchasing through long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates lot-traceable pharmaceutical grades from commodity beverage packaging supply. Cost compression in standard-grade round slugs is intensifying because primary aluminum price volatility transmits immediately to toll processor economics. Beverage aerosol manufacturers exhibit highest price sensitivity due to thin converter margins, while luxury cosmetics buyers absorb premiums for custom-shaped proprietary geometries.
Supply Chain Analysis
REACH substance restrictions and EU Green Deal carbon-border adjustments are gating supplier qualification through scope-three emissions verification protocols. Raw material flows draw from Norwegian hydropower-smelting operations, German rolling mill clusters, and Chinese continuous casting facilities. Primary aluminum ingot, precision rolling capacity, and surface treatment chemistry constitute critical input dependencies. Single-source vulnerability concentrates in Nordic high-purity feedstock channels serving pharmaceutical compliance tiers. Distribution runs through direct mill relationships displacing distributor intermediaries for volume procurement by multinational packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory arbitrage play where EU Green Deal carbon-border adjustments force scope-three emissions verification, converting compliance capability into pricing power and contract eligibility.
For Market Incumbents: Deploy closed-loop recycling systems to secure feedstock insulation from primary aluminum volatility while capturing EU Packaging and Packaging Waste Directive recycling targets. Add precision edging and annealing services through toll processing acquisitions to defend against margin erosion in raw slug commoditization. Steel aerosol substitution in price-sensitive personal care segments threatens volume retention in standard-grade round slugs.
For New Entrants and Emerging Players: Enter via secondary manufacturing services in Ohio and Pennsylvania where legacy metalworking infrastructure supports precision edging and annealing capacity expansion. Target pharmaceutical packaging converters in the Cologne-Düsseldorf corridor requiring custom-shaped slugs with lot-traceable alloy certification. Position through hydropower-smelting feedstock partnerships that satisfy sustainability-mandated buyer procurement criteria.
For Investors and Strategic Acquirers: Asymmetric upside sits with European toll processors possessing geographic coverage across German and Austrian converter clusters and verified scope-three emissions data. Long-term viability hinges on carbon-border compliance infrastructure rather than commodity scale. Watch for ECHA enforcement timeline acceleration on restricted alloy additives as inflection indicator for surface treatment reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captures carbon-intensity advantages through Norwegian hydropower-smelting feedstock securing preferred supplier status. |
| Precision Edging and Annealing Capacity Expansion | Toll processors capture margin pools beyond raw slug supply serving German pharmaceutical packaging converters. |
| Closed-Loop Recycling System Deployment | Aligns with EU Packaging and Packaging Waste Directive targets securing long-term multinational contracts. |
| Continuous Casting Technology Licensing | Absorbs tolerance requirements previously demanding multiple rolling stages reducing in-process inventory. |
| Direct Mill Relationship Consolidation | Displaces distributor intermediaries for volume procurement where lot traceability exceeds distributor capabilities. |
Methodological Framework
Multiple input streams — primary interviews with impact extrusion plant managers, procurement leads at packaging converters, toll processor operations directors, and regulatory affairs specialists; secondary validation through customs and trade data, SEC filings of integrated aluminum producers, ECHA substance restriction databases, and EU carbon-border adjustment mechanism documentation; plus continuous casting technology patent filings — were reconciled through bottom-up demand modeling and top-down supply capacity triangulation.
Data-stream reconciliation across the projection horizon applied product type, end-use industry, manufacturing stage, and regional regulatory cluster segmentation dimensions. CAGRs were derived from growth driver elasticity modeling against aluminum price volatility scenarios and carbon-border compliance cost trajectories. Forecast inputs incorporated REACH substance restriction enforcement timelines and hydropower-smelting capacity expansion announcements.
Inputs from packaging converter procurement databases and primary aluminum producer sustainability disclosures were available through the study window; gaps in real-time scope-three emissions verification tooling introduce uncertainty bands around carbon-border adjustment impact assessments. A model refresh is warranted upon material change in EU Green Deal carbon-border adjustment implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Oxygen-Free Copper Market
Metals
Aluminum Extrusion Market
Metals
Tantalum and Niobium Material Market
Metals
Silver Sulphate Market
Metals
Zinc Ingots Market
Metals
Global Bronze Market
Metals
Tin Chloride Market
Metals
Tungsten Metal Powder Market
Metals
Copper Powder Market
Metals
Iron Ore Market
Metals
Steel Salvage Drums Market
Metals
Steel Ingots Market
Metals
India Metal Fabrication Market
Metals
Global Copper Market
Metals
Crude Steel Market
Metals
Metallurgical Silicon Market