
 India Special Steel Market | 2026-2036
India Special Steel Market Size, Share, and Industry Trends Forecast 2026-2036
India Special Steel Market Insights
Skilled metallurgist availability in India is collapsing as vocational training pipelines fail to match Electric Arc Furnace complexity. Tata Steel Limited leverages captive iron ore reserves to sustain cost leadership in alloy grades. JSW Steel Limited anchors western India demand through its Dolvi complex. Jindal Stainless Limited specializes in austenitic and ferritic output for precision engineering buyers.
Special steel denotes iron-carbon alloys engineered with deliberate chromium, nickel, molybdenum, or vanadium additions to achieve tensile strengths exceeding 540 MPa, corrosion resistance, or elevated temperature stability for critical load-bearing applications. Stainless steel commands the dominant value share due to nuclear and chemical processing specifications, while tool steel competes on die-life metrics for automotive stamping. Blast Furnace routes still occupy volume leadership, though Electric Arc Furnace configurations are gaining traction in merchant special steel for their scrap-flexibility and lower carbon intensity per tonne.
BIS certification mandates, the Ministry of Steel's PLI scheme, and CEA power-quality standards collectively shape domestic special steel demand by enforcing grade-specific testing and incentivizing capacity expansion in value-added segments. CDSCO medical-device grade requirements and DGFT export obligation frameworks further filter market access for specialty producers. Stakeholders must monitor alloy surcharge volatility and scrap import duty adjustments as decisive variables for margin sustainability.
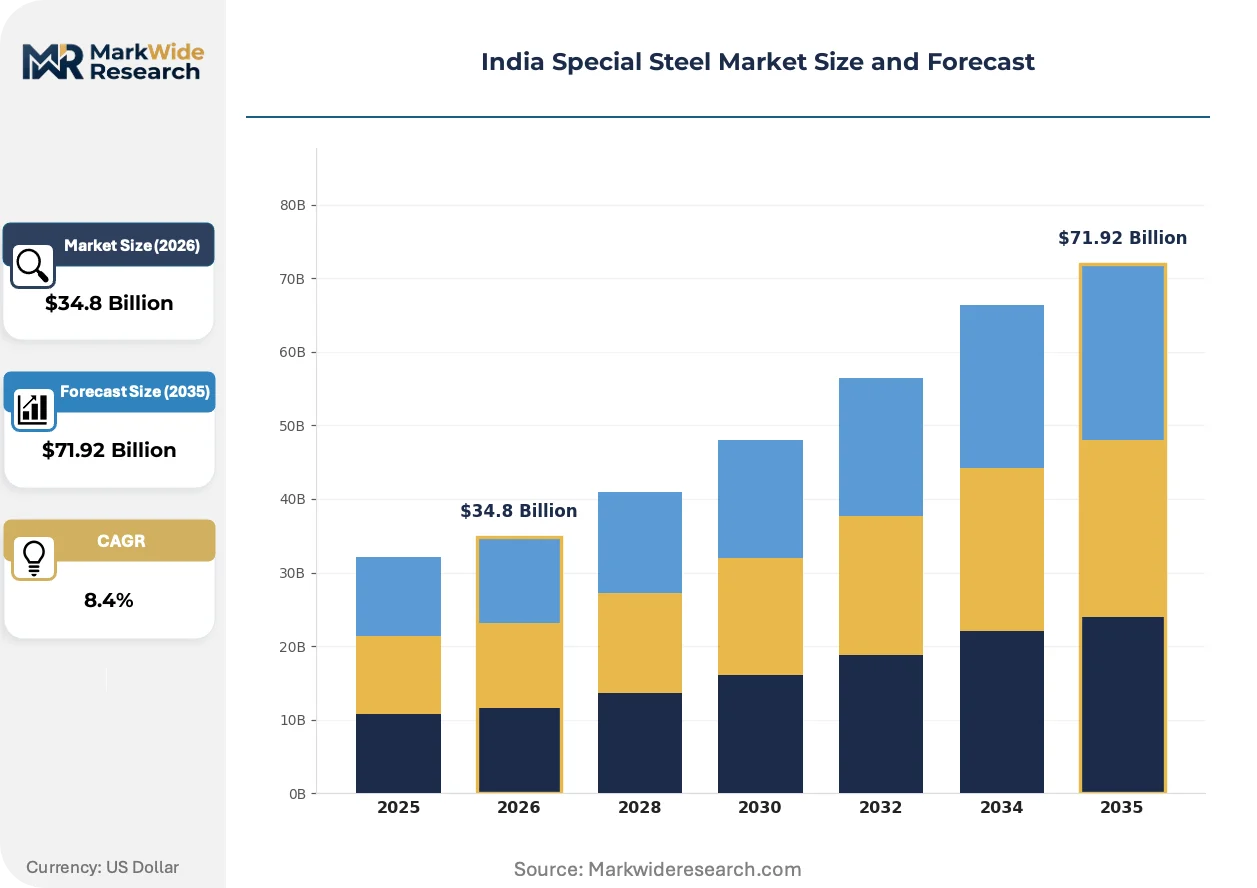
Market Dynamics
The Ministry of Steel's PLI scheme is concentrating alloy steel capacity expansion in Tamil Nadu and Maharashtra, pulling procurement volumes toward automotive OEMs demanding high-strength grades above 540 MPa tensile strength.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Pune and Chennai are specifying advanced high-strength steel for chassis components, creating pull-through demand for quenched and tempered grades.
- BIS certification enforcement:Mandatory grade-specific testing under BIS IS 6911 and IS 6529 is filtering out substandard imports and securing domestic volume for certified mills.
- Nuclear power expansion:CEA specifications for reactor-grade stainless steel are opening dedicated procurement channels for austenitic grades with elevated chromium content.
Market Restraints
- Scrap import duty volatility:DGFT adjustments to shredded scrap tariffs are compressing Electric Arc Furnace margins and discouraging merchant capacity expansion.
- Skilled metallurgist scarcity:Vocational training pipelines in Odisha and Jharkhand are failing to match Electric Arc Furnace operational complexity, constraining output quality consistency.
- Alloy surcharge instability:Molybdenum and nickel price swings are disrupting long-term contract pricing for tool steel and die-grade deliveries.
Strategic Opportunities
- Medical-device grade penetration:CDSCO requirements for surgical instrument steel are creating white space for domestic producers of 316LVM and 420-modified grades.
- Defense indigenization:Ministry of Defence offset mandates are channeling armor plate and ballistics-grade alloy demand toward domestic special steel mills.
- Hydrogen infrastructure specification:Emerging demand for hydrogen-compatible pipeline steel and pressure vessel grades is opening new application segments for ferritic-martensitic alloys.
Industry Challenges
- Electric Arc Furnace commissioning delays:Complex electrode management and slag chemistry control are extending ramp-up timelines for new merchant capacity beyond projected schedules.
- Multi-grade certification backlog:BIS laboratory capacity constraints are stretching approval timelines for new alloy formulations, delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Special Steel Market |
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $71.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Steel, Stainless Steel, Tool Steel, Spring Steel End User: Automotive, Construction, Aerospace, Energy Production Process: Electric Arc Furnace, Blast Furnace, Ladle Refining, Continuous Casting Application: Machinery, Infrastructure, Transportation, Defense |
| Companies Covered | AM/NS India (ArcelorMittal Nippon Steel India), Vedanta Limited (ESL Steel), Tata Steel Limited, Rashtriya Ispat Nigam Limited (RINL), Jindal Stainless Limited, JSW Steel Limited, Jindal Steel and Power Limited, Godawari Power and Ispat Limited, Steel Authority of India Limited (SAIL), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Special Steel Market Trends and Innovations
Process metallurgy and regulatory specification are reshaping competitive positioning in Indian special steel, with technology adoption patterns diverging between integrated blast furnace routes and emerging scrap-based configurations.
Direct reduced iron-electric arc furnace hybrid configurations are decomposing the traditional blast furnace cost advantage in alloy steel production. Automotive tier-one suppliers in Gujarat are piloting these routes for medium-carbon grades. The technology is decomposing integrated mill dominance in merchant bar and rod segments.
CEA power-quality standards for grid-connected steel melting are tightening harmonic emission limits for induction furnace operators. Smaller rerollers in Raipur and Mandi Gobindgarh face retrofit costs or exit pressures. Special steel producers with in-house captive power are absorbing compliance costs more efficiently than merchant induction units.
Specification-driven procurement is consolidating buyer power among automotive OEMs and nuclear project contractors. Long-term offtake agreements with penalty clauses for deviation from declared chemistry are displacing spot market purchasing for critical grades. This pattern is most visible in Tamil Nadu's automotive cluster and Gujarat's nuclear equipment fabrication zone.
India Special Steel Market Segmentation
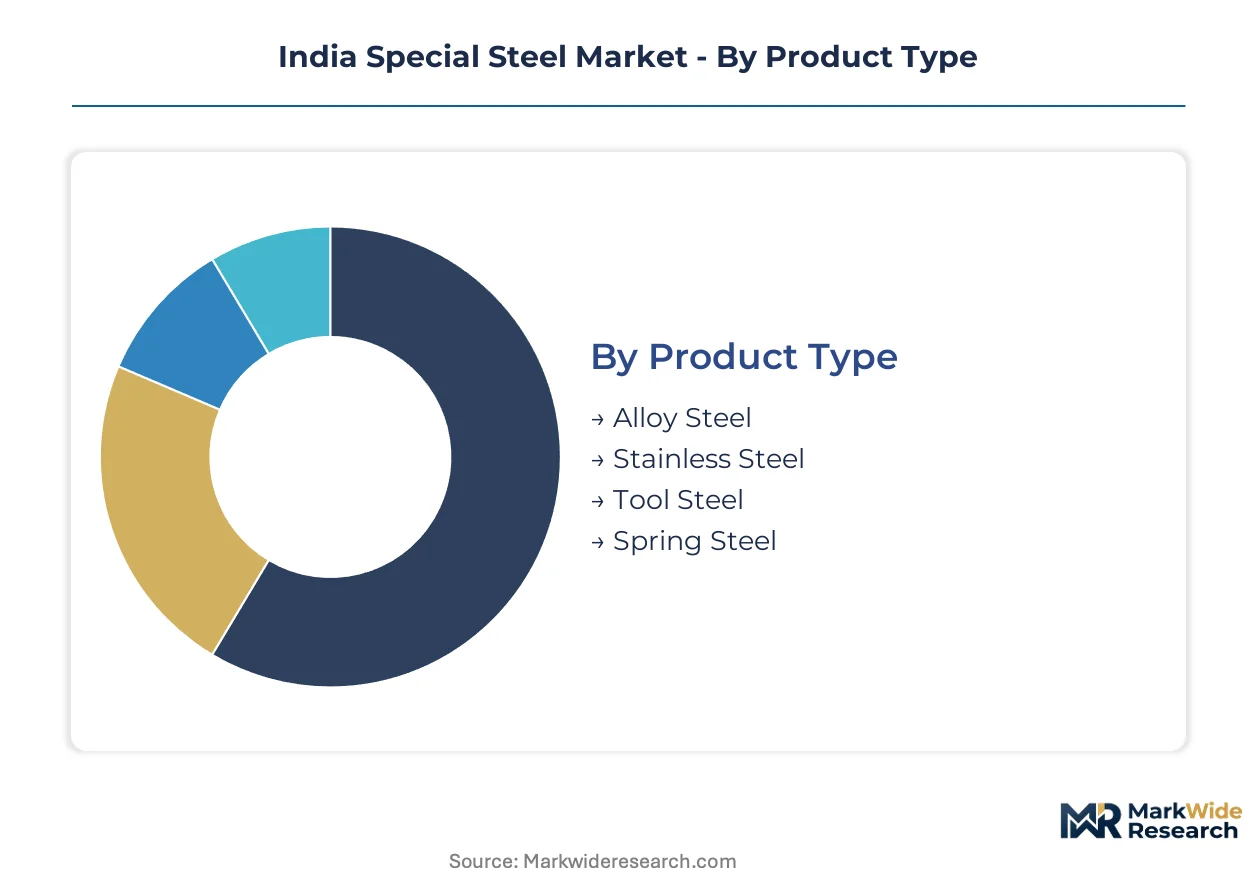
Special steel procurement in India fragments across specification-driven buyer clusters, with automotive and nuclear contractors imposing distinct chemistry and certification requirements. Segment boundaries blur where dual-grade specifications serve overlapping end-uses, forcing mills to maintain flexible alloy portfolios rather than single-product dominance.
Product Type:
Domestic consumption concentrates in grades serving BIS-mandated infrastructure and automotive specifications, while export-oriented production targets precision engineering buyers in Southeast Asia and the Middle East.
- Alloy Steel:Iron-carbon matrices with deliberate chromium, nickel, or molybdenum additions achieve tensile strengths exceeding 540 MPa for chassis and transmission components. Demand clusters in Tamil Nadu and Maharashtra automotive corridors, where OEMs enforce long-term chemistry lock-in contracts.
- Stainless Steel:Austenitic and ferritic grades with elevated chromium content deliver corrosion resistance for chemical processing and nuclear applications. CEA reactor-grade specifications channel procurement toward domestic mills with dedicated vacuum arc remelting capability.
- Tool Steel:High-carbon formulations with tungsten or vanadium optimize die life for automotive stamping operations. CDSCO surgical instrument specifications are opening niche demand for 420-modified grades.
- Spring Steel:Silicon-manganese alloys provide fatigue resistance for suspension and railway applications. Railway Board procurement specifications dominate volume allocation.
Stainless steel commands the established base. The steepest expansion runs through alloy steel grades serving automotive lightweighting mandates.
End User:
Customer concentration varies sharply by certification burden, with nuclear and medical-device buyers imposing multi-stage approval protocols that exclude merchant rerollers.
- Automotive:Pune and Chennai OEM clusters specify quenched and tempered grades for chassis lightweighting, creating pull-through demand exceeding 540 MPa tensile thresholds. Long-term offtake agreements with chemistry penalty clauses displace spot purchasing.
- Construction:Infrastructure projects in Gujarat and Maharashtra consume rebar and structural sections with BIS IS 1786 certification. Metro rail expansions in Bengaluru and Hyderabad are concentrating high-strength bar demand.
- Aerospace:Defense indigenization programs under Ministry of Defence offset mandates channel specialty alloy demand toward domestic producers. Stringent vacuum induction melting requirements limit qualified supplier pools.
- Energy:Nuclear power expansion drives reactor-grade stainless procurement under CEA specifications. Hydrogen infrastructure pilots are emerging demand sources for ferritic-martensitic pressure vessel grades.
Automotive offtake anchors current volume. Aerospace and energy applications are climbing the fastest as indigenization mandates deepen.
Production Process:
Technology choice determines carbon intensity and scrap flexibility, with merchant operators favoring Electric Arc Furnace configurations despite electrode management complexity.
- Electric Arc Furnace:Scrap-based melting enables rapid alloy adjustment for small-batch specialty grades. DGFT scrap import duty volatility compresses margins and discourages greenfield merchant capacity.
- Blast Furnace:Integrated routes sustain cost leadership in high-volume alloy grades through captive iron ore integration. Tata Steel's Jharkhand and Odisha operations exemplify this configuration.
- Ladle Refining:Secondary metallurgy stations enable precise chemistry control for vacuum degassed grades. Essential for automotive and nuclear specifications requiring hydrogen content below 2 ppm.
- Continuous Casting:Near-net-shape solidification reduces downstream processing for billet and bloom segments. Billet quality consistency determines eligibility for seamless tube and forging applications.
Blast furnace routes retain volume leadership. Electric Arc Furnace configurations are gaining share fastest on scrap flexibility and carbon intensity advantages.
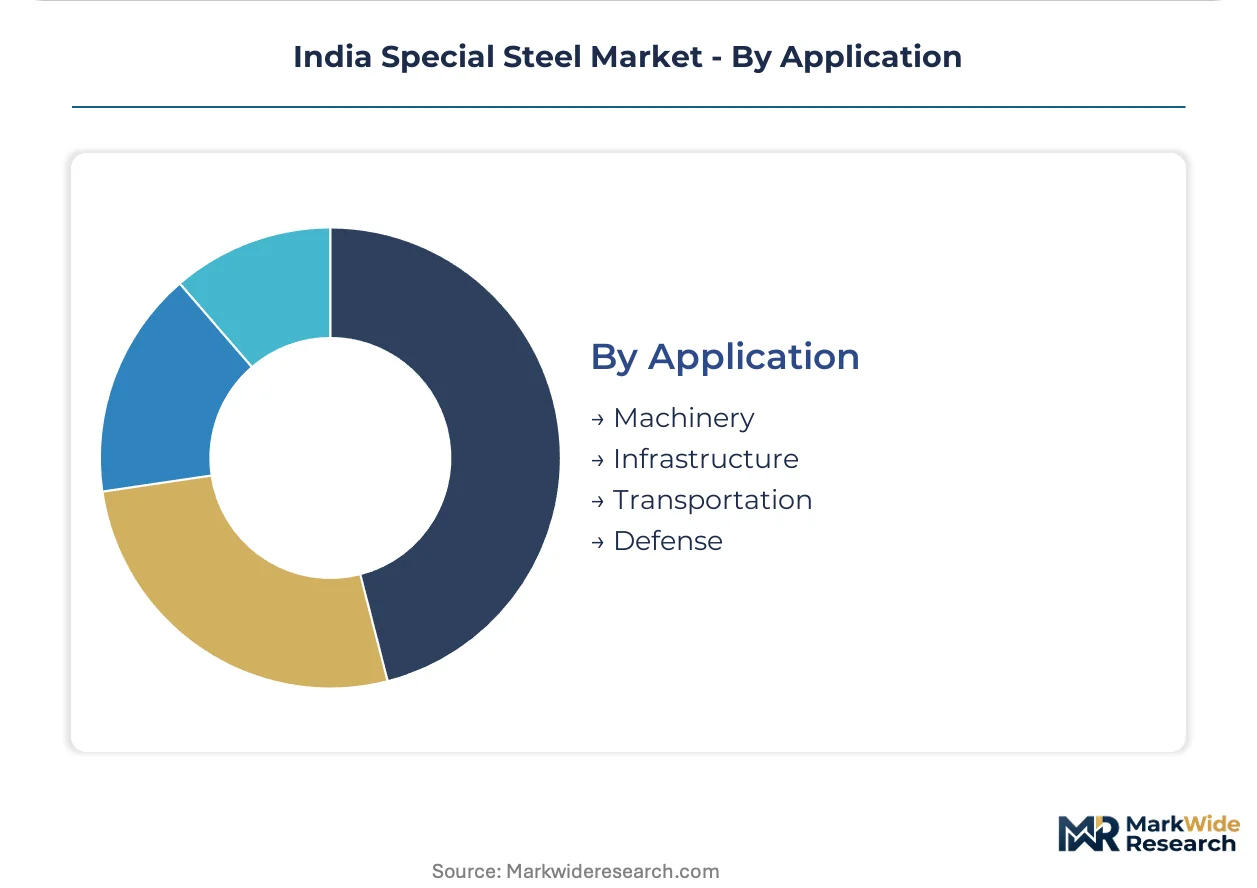
Application:
Application boundaries shift as grade specifications migrate across traditional sector definitions, with defense and hydrogen infrastructure creating overlapping demand profiles.
- Machinery:Tool steel and bearing grades serve capital goods manufacturers in Coimbatore and Ludhiana clusters. Die life metrics dominate supplier selection for automotive tier-one stampers.
- Infrastructure:High-strength rebar and structural sections support metro rail, bridges, and industrial construction. BIS IS 1786 and IS 2062 certifications filter substandard imports.
- Transportation:Railway rolling stock and automotive chassis consume the majority of quenched and tempered alloy production. Indian Railways' dedicated freight corridors are expanding rail-grade demand.
- Defense:Armor plate and ballistics-grade alloys serve Ministry of Defence indigenization mandates. Offset requirements are channeling specialty melting investment toward domestic capacity.
Infrastructure applications anchor established demand. Defense and hydrogen-compatible transportation grades are expanding most quickly as procurement specifications evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special steel consumption in India fragments sharply across regional industrial bases, with western and southern states driving high-specification automotive demand while eastern states anchor integrated production capacity.
Maharashtra
Pune's automotive OEM cluster specifies quenched and tempered grades exceeding 540 MPa for chassis lightweighting programs. The state's PLI scheme allocations for alloy steel capacity are accelerating greenfield investments near Dolvi. Mumbai-Pune industrial corridor buyers enforce long-term chemistry lock-in contracts that displace spot purchasing.
Tamil Nadu
Chennai's automotive belt generates concentrated demand for high-strength transmission and suspension components. BIS certification enforcement through regional laboratories filters substandard imports from Southeast Asian suppliers. Sriperumbudur and Oragadam industrial zones host tier-one stampers sourcing tool steel under die-life metric contracts.
Gujarat
Hazira's integrated steel complex and Mundra port infrastructure enable export-oriented stainless production for Middle Eastern chemical processors. CEA power-quality standards for grid-connected melting are tightening harmonic emission limits for induction furnace operators in Ahmedabad's reroller cluster. Dahej's petroleum refinery expansion is opening procurement channels for hydrogen-compatible pressure vessel grades.
Jharkhand
Jamshedpur's captive iron ore integration sustains cost leadership in blast furnace-based alloy grades. Vocational training pipeline failures in Odisha-Jharkhand border regions are constraining Electric Arc Furnace operator availability for emerging merchant capacity. Bokaro's Steel Authority of India Limited facility anchors Railway Board spring steel procurement for dedicated freight corridors.
Karnataka
Bengaluru's metro rail expansion and Hyderabad's infrastructure corridor are concentrating high-strength rebar demand with BIS IS 1786 certification requirements. Ballari-Hospet's iron ore belt feeds southern integrated mills, though scrap-based Electric Arc Furnace configurations are gaining share in nearby Raichur for merchant bar segments.
India Special Steel Market Competitive Landscape
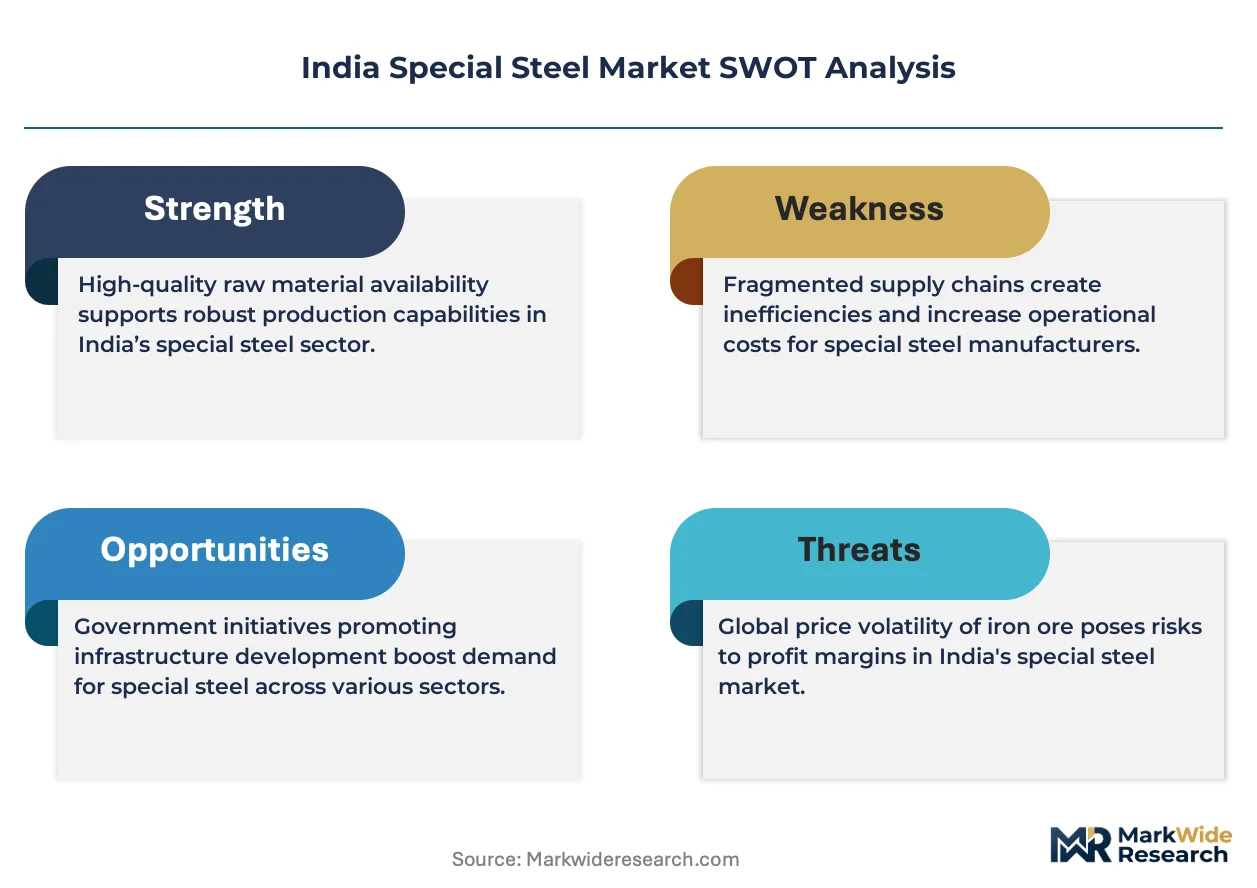
A small set of integrated leaders sits above a broader specialist tier, with captive resource control separating cost-competitive alloy producers from margin-pressed merchant operators. The structure concentrates high-volume alloy and stainless grades among ore-integrated players while tool steel and precision grades fragment across smaller electric furnace configurations. Two strategic archetypes dominate: integrated blast furnace operators leveraging captive raw materials, and scrap-based specialists serving small-batch specification orders. Capacity expansion and backward integration into ferroalloy production represent the prevailing competitive moves.
Within the integrated tier, Tata Steel Limited and JSW Steel Limited exemplify ore-backed scale positions, with the former anchoring eastern India production and the latter commanding western corridor demand through coastal complex advantages. Jindal Stainless Limited occupies a specialist position in austenitic and ferritic grades for corrosion-resistant applications.
| Leading Market Players |
|---|
| AM/NS India (ArcelorMittal Nippon Steel India) |
| Vedanta Limited (ESL Steel) |
| Tata Steel Limited |
| Rashtriya Ispat Nigam Limited (RINL) |
| Jindal Stainless Limited |
| JSW Steel Limited |
| Jindal Steel and Power Limited |
| Godawari Power and Ispat Limited |
| Steel Authority of India Limited (SAIL) |
| Others |
Pricing and Supply Chain Analysis
Blast furnace scale economies at Tata Steel's Jharkhand and Odisha complexes establish cost floors that scrap-based Electric Arc Furnace operators cannot match without captive iron ore integration. This scale concentration compresses merchant mill margins while amplifying pricing power for integrated producers serving automotive OEMs under long-term chemistry lock-in contracts.
Pricing Analysis
Long-term offtake agreements with penalty clauses for chemistry deviation dominate procurement between Tamil Nadu automotive OEMs and certified mills, displacing spot purchasing for critical grades. Price differentiation rests on BIS certification tier and captive raw material integration, with ore-backed producers commanding premiums over merchant induction units. Cost compression in Electric Arc Furnace grades is intensifying because DGFT scrap import duty volatility erodes margin buffers. Merchant rerollers in Raipur and Mandi Gobindgarh exhibit highest price sensitivity, while nuclear contractors under CEA specifications show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
India anchors integrated alloy steel production through Jharkhand and Odisha blast furnace corridors, while China and Indonesia feed ferrochrome and nickel inputs for stainless grades. Domestic supply draws from captive iron ore belts in Ballari-Hospet and Odisha, yet molybdenum and vanadium alloys rest on import channels. Single-source vulnerability concentrates in electrode and high-grade scrap supply for Electric Arc Furnace configurations. Distribution runs through direct mill-OEM contracts for automotive grades and Steel Authority of India Limited channels for Railway Board spring steel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ministry of Steel's PLI scheme is accelerating domestic alloy steel capacity expansion, creating a high-growth disruption as Electric Arc Furnace technology matures against traditional blast furnace dominance.
For Market Incumbents: Compound captive resource advantage through backward integration into ferroalloy production, securing molybdenum and nickel supply chains against import volatility. Defend position by expanding vacuum arc remelting capability for CEA reactor-grade specifications, creating certification moats that exclude merchant rerollers from nuclear procurement channels.
For New Entrants and Emerging Players: Anchor in medical-device grade white space created by CDSCO 316LVM and 420-modified specifications, where incumbent stainless producers lack dedicated surgical instrument focus. Target hydrogen-compatible pressure vessel grades for Dahej petroleum refinery expansion, leveraging ferritic-martensitic alloy expertise as a differentiated entry wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors scrap-flexible Electric Arc Furnace specialists with ladle refining capability, as carbon intensity regulations tighten across the analysis window. Acquisition candidates should demonstrate qualified BIS laboratory relationships to circumvent multi-grade certification backlogs. The signal to watch is Ministry of Defence offset mandate acceleration, which would inflect armor plate and ballistics-grade alloy demand toward domestic capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Production | Captive molybdenum and nickel supply insulates margins against DGFT import duty volatility. |
| Vacuum Arc Remelting Capability Expansion | CEA reactor-grade specifications channel nuclear procurement toward qualified domestic mills exclusively. |
| Medical-Device Grade Certification Investment | CDSCO 316LVM requirements create defensible niche demand with premium pricing power. |
| Hydrogen-Compatible Alloy Development | Dahej refinery expansion and pipeline pilots open new application segments for early movers. |
| Long-Term Automotive Offtake Structuring | Chemistry lock-in contracts with Pune and Chennai OEMs displace spot purchasing and stabilize utilization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with BIS certification laboratory directors, Ministry of Steel policy officials, automotive tier-one procurement heads, and Electric Arc Furnace plant managers. Secondary validation drew from DGFT trade data, CEA power-quality filings, BIS IS standard documentation, and Steel Authority of India Limited annual disclosures. Bottom-up alloy grade consumption estimates were triangulated against top-down capacity utilization data from integrated mill complexes.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-use industry, production process technology, and regional state cluster. CAGRs were derived from fitted growth curves against historical alloy steel shipment trajectories, with explicit modeling of PLI scheme capacity addition timelines and scrap import duty scenario variations. Forecast inputs incorporated automotive lightweighting mandate intensity and nuclear power expansion procurement schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained PLI scheme funding and stable BIS certification enforcement timelines; material deviation in either would warrant model refresh. Specific risks that could revise projections include sudden DGFT scrap duty spikes, Electric Arc Furnace commissioning delays beyond projected schedules, or multi-grade certification backlog resolution. Recalibration cycles align with material shifts in Ministry of Steel policy announcements and CEA specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Ingots Market
Metals
Global Tin Market
Metals
Medical Metal Tubing Market
Metals
Magnesium Metal Market
Metals
Silver-Platinum Paste Market
Metals
Aluminum Casting Market
Metals
China Copper Market
Metals
North America Aluminum Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Ferro Vanadium Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
North America Iron Casting Market
Metals
316 Stainless Steel Container Market
Metals
Aluminum Scrap Recycling Market
Metals
Stainless Steel Panels Market
Metals
Gold Smelting Market