
 Molybdenum Market | 2026-2036
Molybdenum Market Size, Share, and Industry Trends Forecast 2026-2036
Molybdenum Market Intelligence
The unbundling of molybdenum ore sales from specialized, application-specific ferromolybdenum products is hardening supply chain relationships. Freeport-McMoRan Inc. leverages its significant mining output to secure long-term contracts for raw materials. In contrast, Jinduicheng Molybdenum Co., Ltd. specializes in a diverse portfolio of refined products, including high-purity powders and alloys. Anglo American competes through its integrated copper-molybdenum mining operations, offering cost advantages.
Molybdenum is a refractory transition metal, atomic number 42, with an extremely high melting point of 2,623°C. Its primary function is as an alloying element to improve the properties of steel and other metals. The ferromolybdenum product segment commands the largest share, directly feeding into steel alloy applications. While steel production accounts for most consumption, the catalyst sector offers higher value for specialized molybdenum compounds.
Environmental regulations from bodies like the U.S. EPA and China's MEE govern mining waste and processing emissions. Concurrently, the EU's REACH framework controls the registration and use of molybdenum compounds in industrial applications. The key decision for producers involves balancing investment in cleaner extraction technologies against meeting the stringent purity requirements of downstream electronics and chemical markets.
Market Dynamics
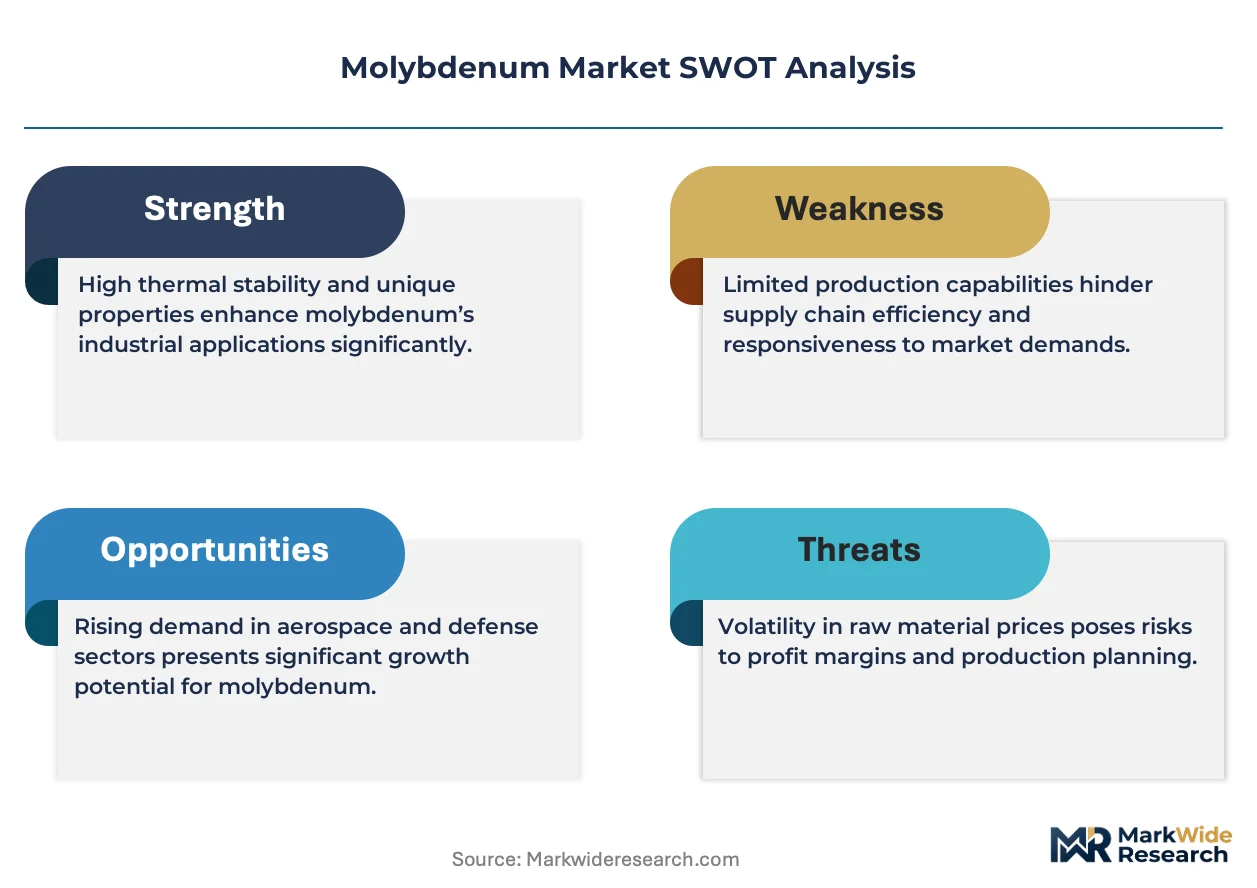
The market's structure is defined by a fundamental split between high-volume demand for steel alloying and the exacting purity requirements of high-value electronics and chemical sectors. This division influences investment, supply chain configuration, and technology development.
Growth Catalysts
- Infrastructure Expansion:High-strength steel alloys containing molybdenum are critical for large-scale construction and energy projects, particularly under China's infrastructure-focused economic plans.
- Aerospace Superalloys:The high melting point of molybdenum makes it essential for nickel-based superalloys used in jet engine turbines and other high-temperature aerospace components.
- Petroleum Refining:Molybdenum-based catalysts are indispensable for hydrodesulfurization processes in oil refineries, helping to produce cleaner-burning fuels that meet environmental standards.
Market Restraints
- By-product Supply Dependency:A significant portion of molybdenum supply is tied to copper mining, making its availability dependent on copper market dynamics rather than direct molybdenum demand signals.
- Intensive Energy Consumption:The roasting and smelting processes required to refine molybdenum ore are highly energy-intensive, exposing producers to volatile electricity and natural gas prices.
- Alloying Substitution:In certain grades of steel, other elements like vanadium and niobium can offer similar strengthening properties, creating a substitution threat that can cap molybdenum prices.
Strategic Opportunities
- Electronics Materials:Growth in the display market creates opportunities for high-purity molybdenum sputtering targets used in thin-film transistor (TFT) manufacturing for screens.
- Green Hydrogen Catalysis:Research into molybdenum sulfides as efficient, non-precious-metal catalysts for hydrogen evolution reactions presents a potential long-term demand source from the hydrogen economy.
- Circular Economy Development:Establishing dedicated infrastructure for collecting and recycling molybdenum-bearing scrap from specialty alloys and catalysts offers a sustainable secondary supply stream.
Industry Challenges
- Ultra-High Purity Demands:Meeting the parts-per-billion impurity levels required by the semiconductor and electronics industries necessitates substantial investment in advanced refining and cleanroom handling facilities.
- Waste Stream Compliance:Adhering to increasingly strict environmental regulations from bodies like the U.S. EPA and China's MEE for managing mine tailings and processing emissions adds significant operational cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molybdenum Market |
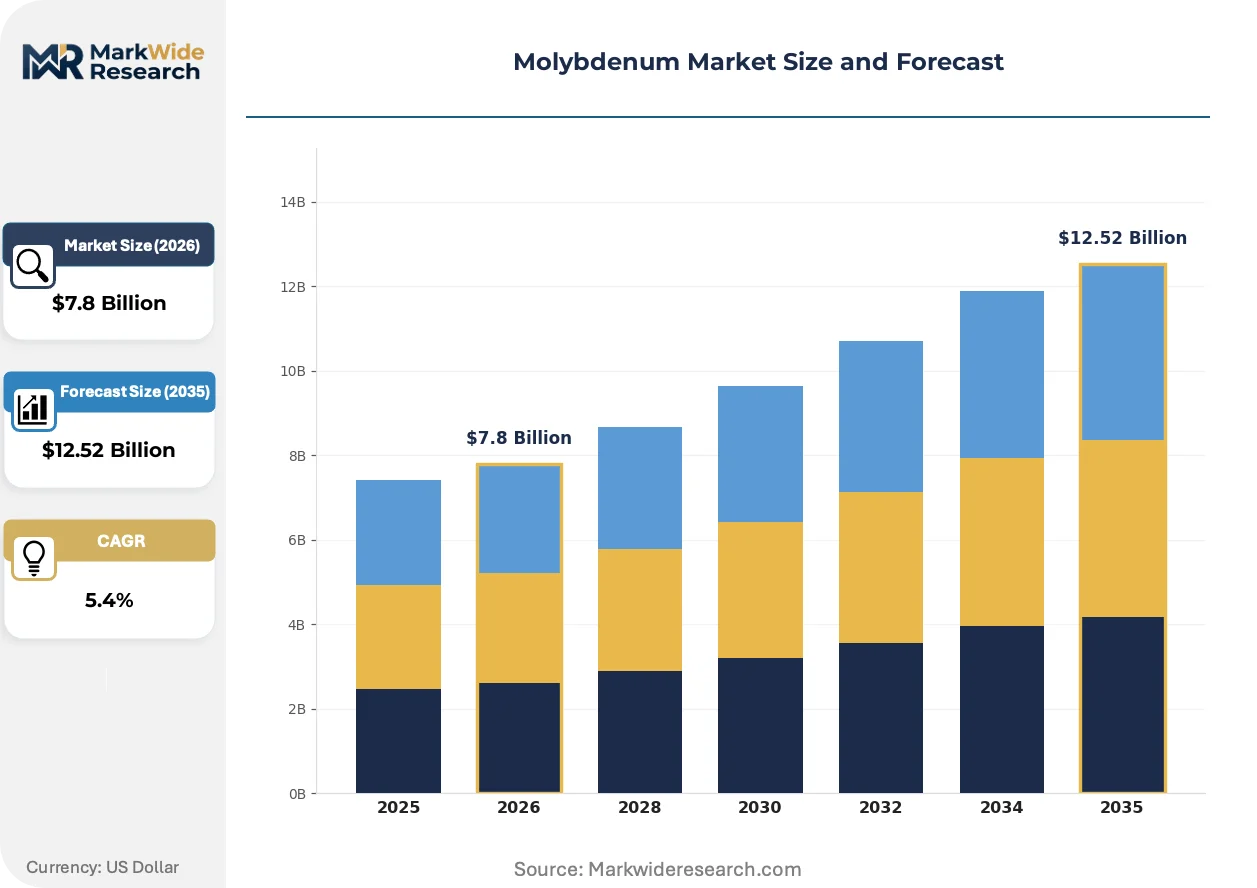
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molybdenum Ore, Ferromolybdenum, Technical Grade Powder, Molybdenum Disulfide Application: Steel Alloys, Catalysts, Electronics, Lubricants, Pigments End User Industry: Construction, Chemical Manufacturers, Electronics Fabricators, Paint Producers Form: Powder, Rods, Plates, Sheets, Pellets |
| Companies Covered | Southern Copper Corporation, Anglo American, Jinduicheng Molybdenum Co., Ltd., Glencore PLC, Antofagasta PLC, Freeport-McMoRan Inc., BHP Billiton Group, Teck Resources Limited, China Molybdenum Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molybdenum Market Strategic Shifts & Innovations
Technological advancements and regulatory pressures are creating a distinct bifurcation in the molybdenum value chain. One path leads toward commoditized, high-volume alloys, while the other focuses on highly specialized, application-specific compounds with stringent purity qualifications.
High-purity molybdenum sputtering targets provide uniform thin films for advanced electronics. Semiconductor and flat-panel display manufacturers are adopting these materials for next-generation circuits. This specialized product category is overtaking lower-grade molybdenum materials in the high-value electronics manufacturing supply chain.
The EU's REACH framework mandates extensive data submission for the registration of molybdenum compounds sold within Europe. This regulation increases compliance costs for producers, requiring detailed toxicological and environmental impact assessments. The chemical and catalyst segments are most affected, often consolidating their European supply through fewer, fully-registered suppliers.
A shift in buying behavior separates raw material procurement from the purchase of finished alloys. Large steel producers are securing unrefined molybdenum ore through long-term contracts to ensure supply stability. This pattern is most pronounced in China's industrial hubs, where steel mills prioritize raw input security over sourcing finished ferromolybdenum.
Molybdenum Market Segmentation
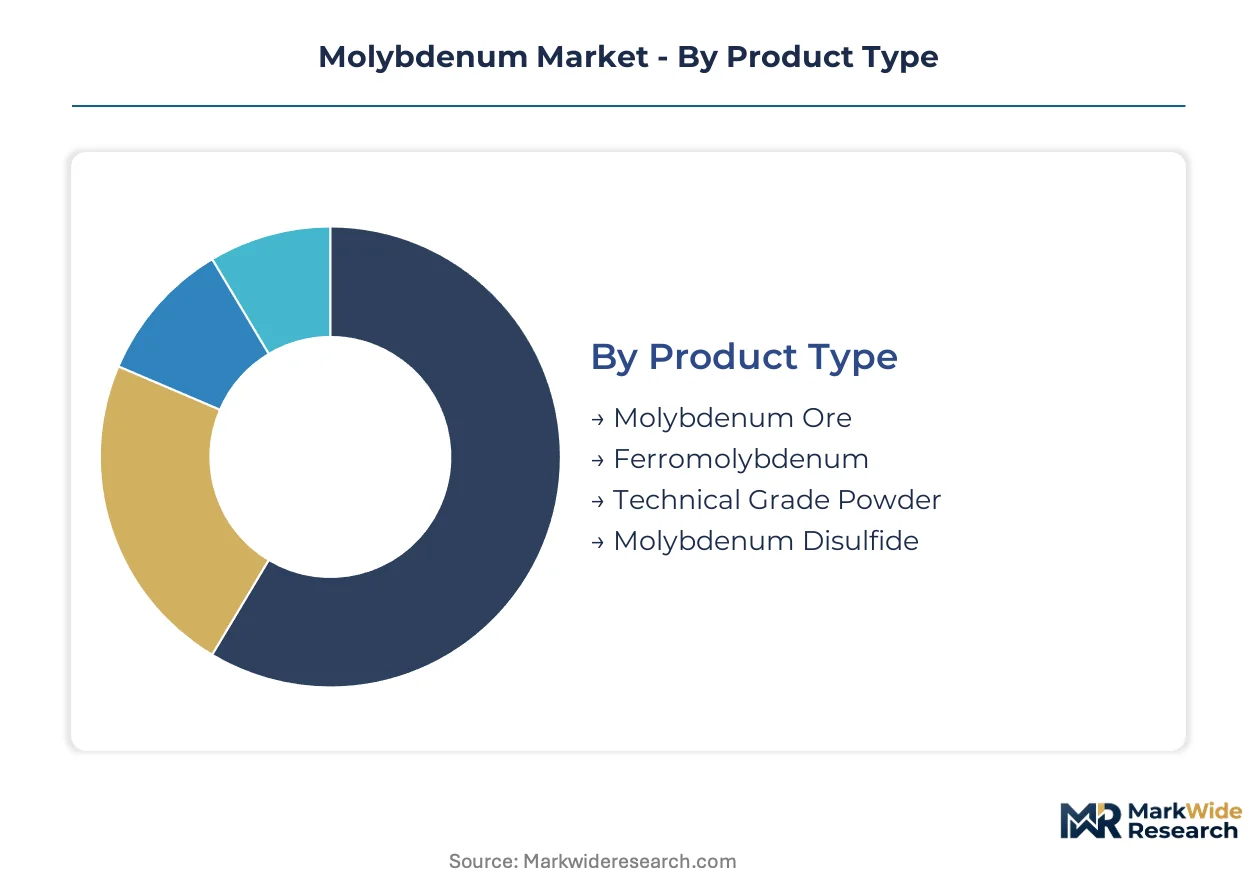
The Molybdenum Market's segmentation reveals the diverse forms and applications driving its value chain. Understanding these distinct segments is crucial for producers to align their investment strategies with specific industrial requirements. This granular view highlights where demand is concentrating and where specialized product development offers higher returns.
Product Type:
Buyer decisions regarding molybdenum product types are primarily driven by the required purity levels and the specific metallurgical or chemical processes involved.
- Ferromolybdenum:This alloy of iron and molybdenum typically contains 60-75% molybdenum, enhancing steel's strength and corrosion resistance. Demand concentrates heavily in Chinese industrial hubs for high-strength steel alloy production, driven by infrastructure expansion.
- Molybdenum Ore:Raw molybdenum ore, primarily molybdenite, is the foundational input for all downstream products, requiring extensive processing. Procurement is shifting towards long-term contracts by large steel producers to ensure supply stability for their operations.
- Technical Grade Powder:This refined molybdenum powder is used in various industrial applications requiring specific particle sizes, including thermal spray coatings and certain chemical processes.
- Molybdenum Disulfide:Molybdenum disulfide functions as a solid lubricant due to its layered crystalline structure, finding application in high-temperature and high-pressure environments.
Volume sits with Molybdenum Ore; growth tilts toward Ferromolybdenum.
Application:
The diverse applications of molybdenum dictate distinct performance requirements, influencing material specifications and processing technologies.
- Steel Alloys:Molybdenum significantly improves the hardenability, strength, and corrosion resistance of steel, particularly in high-temperature environments. This application dominates consumption, with a strong focus on infrastructure projects in China and other developing economies.
- Catalysts:Molybdenum-based compounds are critical in petroleum refining for hydrodesulfurization, removing sulfur from fuels to meet environmental standards. The catalyst sector offers higher value for specialized molybdenum compounds, particularly in cleaner fuel production.
- Electronics:Molybdenum is utilized in the electronics sector for sputtering targets, creating thin films for advanced display technologies and semiconductors.
- Lubricants:Molybdenum compounds, especially molybdenum disulfide, provide excellent lubrication under extreme pressure and temperature conditions in industrial machinery.
- Pigments:Molybdenum-based pigments offer vibrant colors and corrosion resistance, finding use in specialized paints and coatings.
Steel Alloys represent the largest volume segment; Catalysts exhibit a higher value growth trajectory.
End User Industry:
Supply chain configuration for molybdenum is heavily influenced by the specific needs and procurement patterns of distinct end-user industries.
- Construction:This industry demands molybdenum primarily for high-strength steel alloys used in bridges, buildings, and other large-scale infrastructure projects. China's infrastructure-focused economic plans are a significant driver of molybdenum consumption in this sector.
- Chemical Manufacturers:Chemical manufacturers utilize molybdenum compounds as catalysts for various reactions, particularly in petroleum refining and petrochemical production. The exacting purity requirements for these applications necessitate specialized molybdenum compounds and strict quality control.
- Electronics Fabricators:These manufacturers use high-purity molybdenum sputtering targets to create critical components for advanced displays and semiconductor devices.
- Paint Producers:Paint producers incorporate molybdenum pigments for their color stability and corrosion-inhibiting properties in industrial and automotive coatings.
Demand for molybdenum is strongest from the Construction and Chemical Manufacturers sectors, reflecting their material requirements.
Form:
The cost tier for molybdenum forms varies significantly, driven by the complexity of processing and the required material properties for specific applications.
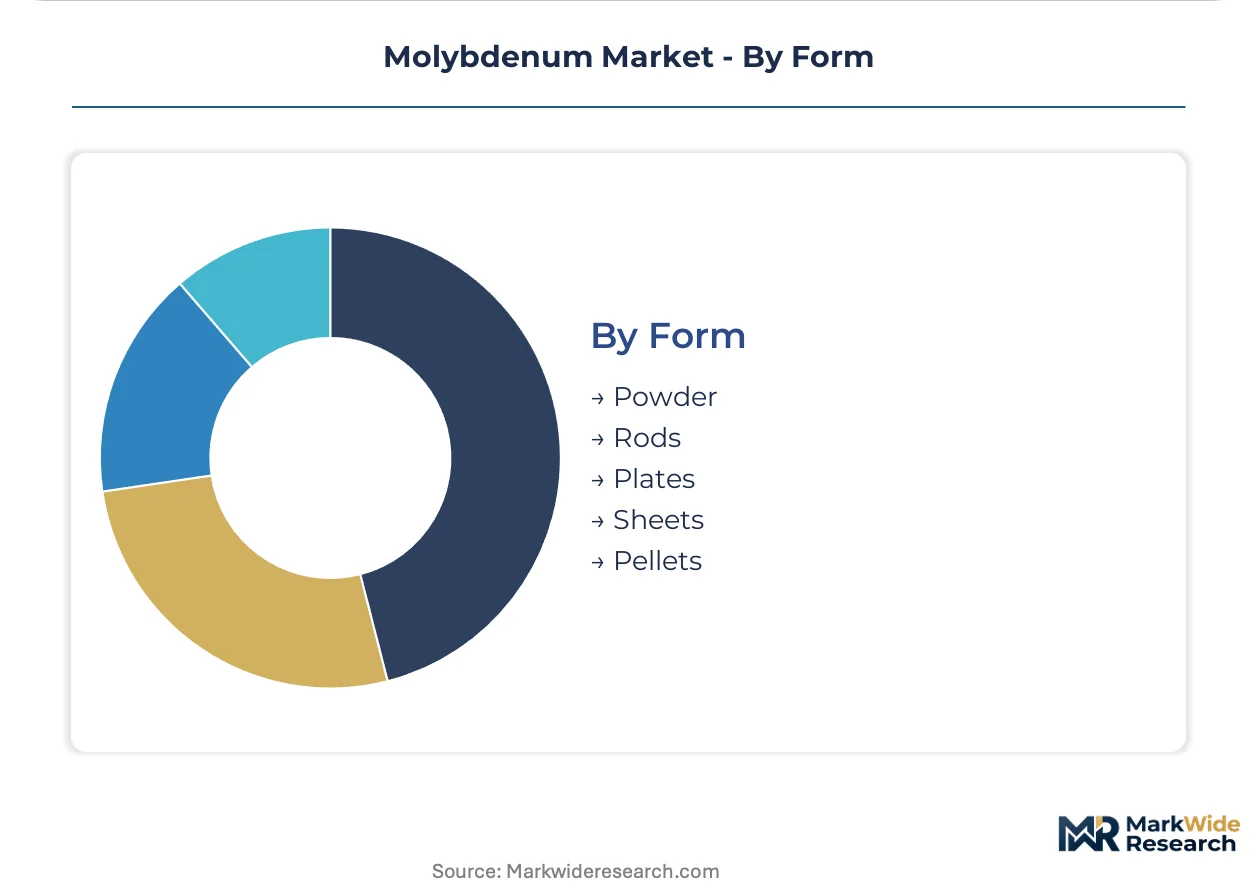
- Powder:Molybdenum powder, often in various grades of purity, serves as a crucial intermediate for alloying, thermal spraying, and high-purity electronics applications. Ultra-high purity demands from the semiconductor industry necessitate substantial investment in advanced refining processes for this form.
- Pellets:Molybdenum pellets are a common form for adding molybdenum to steel and superalloys during the melting process, offering precise alloying control. These pellets facilitate efficient and consistent incorporation of molybdenum into molten metal batches.
- Rods:Molybdenum rods are used in high-temperature furnace components, electrodes, and other applications requiring structural integrity at extreme heat.
- Plates:Molybdenum plates find application in high-temperature vacuum furnaces, heat shields, and specialized electronic components due to their thermal properties.
- Sheets:Molybdenum sheets are employed in electronics, aerospace, and medical industries for their high melting point and excellent strength-to-weight ratio.
Specialization in Powder forms addresses high-purity electronics markets, while Pellets serve bulk alloying needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molybdenum market dynamics show a production-consumption divide. Raw material supply often originates from specific mining regions, while demand centers around industrial manufacturing hubs. This geographic separation influences global trade flows and pricing structures for molybdenum products.
China
China's significant infrastructure expansion drives demand for high-strength steel alloys. The country's MEE governs processing emissions, aligning with dual carbon goals influencing production techniques. Industrial hubs within the Yangtze River Delta concentrate demand for molybdenum as an alloying agent.
United States
The United States market demands molybdenum for petroleum refining catalysts and aerospace superalloys. U.S. EPA regulations influence mining waste management and processing standards for domestic operations. Gulf Coast refineries drive catalyst consumption, while semiconductor clusters require high-purity sputtering targets.
Germany
German industries require molybdenum for high-performance steel, chemical catalysts, and advanced components. The EU's REACH framework controls the registration and use of molybdenum compounds within the country. Industrial regions such as North Rhine-Westphalia utilize molybdenum in specialized alloys and chemical production.
Chile
Chile functions as a primary global supplier of raw molybdenum ore, often as a copper by-product. Environmental regulations from the Chilean Ministry of Environment impact mining operations and waste management. Major mining regions in the Atacama Desert are primary sources for copper-molybdenum output.
Molybdenum Market Key Industry Players
The competitive structure tilts toward integrated mining operations providing raw materials. This market features a blend of large-scale commodity producers and specialized refiners. Strategic archetypes include diversified mining conglomerates, dedicated molybdenum specialists, and downstream product manufacturers. Key competitive moves involve securing long-term raw material contracts, diversifying product portfolios, and investing in cleaner extraction technologies to meet environmental standards.
Integrated mining giants such as Freeport-McMoRan Inc. and Anglo American exemplify the upstream control over raw material supply. These entities leverage their significant copper-molybdenum mining output to secure market position and ensure supply stability for industrial consumers. In contrast, specialists in diverse refined products like Jinduicheng Molybdenum Co., Ltd. occupy a distinct position, focusing on high-purity powders and alloys for specialized applications in electronics and chemical sectors, catering to exacting purity requirements.
| Leading Market Players |
|---|
| Southern Copper Corporation |
| Anglo American |
| Jinduicheng Molybdenum Co., Ltd. |
| Glencore PLC |
| Antofagasta PLC |
| Freeport-McMoRan Inc. |
| BHP Billiton Group |
| Teck Resources Limited |
| China Molybdenum Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Highly specialized metallurgists and chemical engineers concentrated in advanced processing hubs contribute to labor-cost differentials, which in turn influence pricing-tier spreads between high-purity molybdenum compounds and commodity-grade products.
Pricing Analysis
Cost-down pressure on high-volume ferromolybdenum alloys intensifies due to consistent byproduct supply from copper mining operations. The market operates on a hybrid pricing model, combining long-term contract-based offtake for raw ore with value-based pricing for specialized molybdenum compounds. Price differentiation stems from purity levels, processing complexity, and application-specific formulations. Steel alloy producers, requiring large volumes, exhibit the highest price sensitivity, while electronics and catalyst manufacturers prioritize performance over cost for their critical applications.
Supply Chain Analysis
Rigorous qualification processes for high-purity molybdenum compounds gate access to sensitive downstream electronics and chemical markets. Geographic supply concentrates in Chile for raw ore, China for processing and demand, and the United States for specialized product manufacturing. The supply chain relies heavily on copper mining as a primary source, creating a structural risk from copper market dynamics. Distribution for bulk materials occurs through direct long-term contracts with large industrial consumers, while specialized high-purity forms utilize niche distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a cost-of-compliance story, where the EU's REACH framework creates a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents: Acquire upstream mining assets to secure long-term molybdenum ore supply stability against geopolitical risks. Invest in cleaner extraction technologies to meet increasingly stringent environmental regulations from bodies like the U.S. EPA and China's MEE. Diversify product portfolios beyond commodity ferromolybdenum into high-value, application-specific compounds to mitigate alloying substitution threats.
For New Entrants and Emerging Players: Specialized distributors serving the electronics and chemical sectors offer a pathway for new entrants focusing on high-purity molybdenum sputtering targets. Target niche high-value applications, such as green hydrogen catalysis, where existing supply chains are less entrenched. Initiate R&D collaborations with electronics fabricators to co-develop next-generation molybdenum materials.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated specialists given their control over advanced processing technologies and intellectual property in high-purity materials. Long-term viability is anchored in the growing demand for advanced materials in green technologies and high-performance electronics. A key signal to watch is the adoption rate of molybdenum-based catalysts in commercial green hydrogen production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Purity Processing | Addresses ultra-high purity demands from semiconductor industries for advanced displays. |
| Long-term Supply Agreements for Raw Ore | Ensures supply stability for large-scale steel producers in China's industrial hubs. |
| Investment in Green Hydrogen Catalysis R&D | Positions for future demand from the emerging hydrogen economy and clean energy. |
| Circular Economy Infrastructure Development | Creates sustainable secondary supply streams for specialty alloys and catalysts. |
| Strategic Partnership with Electronics Fabricators | Accelerates adoption of molybdenum sputtering targets in next-generation circuits. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational market view. This was triangulated with primary interviews conducted with mining executives, steel mill procurement heads, chemical R&D directors, and electronics supply chain managers. The analysis integrated both bottom-up and top-down approaches for comprehensive validation.
Market volume and value were modeled at granular levels across product type, application, and regional demand patterns throughout the forecast period. Segmentation dimensions included end-user industry, form, and specific purity grades to capture market nuances. Compound Annual Growth Rates were derived from historical trends, projected demand, and anticipated infrastructure spending forecasts.
Caveats apply where geopolitical stability shifts or unforeseen technological breakthroughs could materially alter the outlook. Forecasts reflect assumptions documented regarding economic growth trajectories and clean energy transition policies. A model refresh is warranted upon material change in global commodity prices or regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
China Copper Market
Metals
Global Precious Metal Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Electrolytic Manganese Metal Market
Metals
Global Titanium Metal Market
Metals
Monel Alloy Market
Metals
Copper and Copper Alloy Powder Market
Metals
Global Oxygen-Free Copper Market
Metals
Welding Materials Market
Metals
Metal Finishing Market
Metals
Prebaked Anodes for Aluminum Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Asia-Pacific Metal Finishing Market
Metals
Copper Powder Market
Metals
Bismuth Market
Metals
TMCP Steel Market