
 Metal Coil Lamination Market | 2026-2036
Metal Coil Lamination Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Coil Lamination Market Analysis
The split between premium grain-oriented electrical steel and commodity non-oriented grades is shifting coil lamination procurement patterns across end-use sectors. ArcelorMittal leverages integrated steelmaking and coating capabilities to dominate high-efficiency transformer laminations in European markets. Tata Steel anchors its position through deep R&D partnerships with automotive OEMs developing next-generation motor cores. Nippon Steel Corporation differentiates via ultra-thin gauge expertise that reduces eddy current losses in high-frequency applications.
Metal coil lamination applies insulating coatings—typically phosphate, chromate, or organic resin systems ranging from 0.5 to 5 micrometers—to silicon-alloyed steel strips, then slits and stamps them into stacked cores for electromagnetic devices. Galvanized steel laminations sustain the largest volume pool through mature transformer and motor manufacturing chains, while cold rolled products capture expanding share in precision electronics where tighter dimensional tolerances matter. Traditional laminating technology still occupies the bulk of installed capacity, though laser cutting is displacing mechanical methods in prototype and short-run production for aerospace inductor applications.
REACH compliance in Europe and EPA hazardous air pollutant standards in the United States are forcing reformulation of coating chemistries away from hexavalent chromium systems. China's GB standards and MEE enforcement on volatile organic compound emissions further constrain process choices for suppliers serving export markets. Stakeholders must monitor how evolving efficiency mandates from IEC and national energy agencies redirect specifications toward thinner, higher-silicon grades that challenge existing lamination line configurations.
Market Dynamics
Coating chemistry reformulation under REACH and EPA hazardous air pollutant standards is restructuring supplier capabilities across the metal coil lamination value chain, forcing capital redeployment toward phosphate and organic resin systems while decommissioning legacy hexavalent chromium lines.
Growth Catalysts
- EU Green Deal carbon intensity benchmarks:Automotive OEMs in Germany and France are accelerating procurement of high-grade laminated electrical steel for EV motor cores to meet tightening vehicle production standards.
- High-frequency electronics demand:Ultra-thin gauge lamination expertise is reducing eddy current losses in precision inductor applications for aerospace and telecommunications equipment.
- Transformer efficiency mandates:IEC specifications and national energy agency directives in Japan and South Korea are redirecting procurement toward thinner, higher-silicon steel grades for distribution and power transformer cores.
Market Restraints
- Silicon steel input cost volatility:Raw material price swings for grain-oriented and non-oriented electrical steel grades compress lamination coating margins during contract renegotiations with transformer manufacturers.
- Coating line reconfiguration capex:Conversion from chromate to phosphate or organic resin systems requires multi-million dollar furnace and application equipment upgrades with extended commissioning timelines.
- Regional supply concentration:Integrated steelmaking and coating capabilities cluster heavily in Western Europe and East Asia, exposing buyers in Southeast Asia and Latin America to logistics cost inflation and currency fluctuation risks.
Strategic Opportunities
- India automotive motorization:Domestic OEM partnerships with PLI scheme beneficiaries are creating localized lamination coating capacity for two-wheeler and passenger EV traction motor cores.
- Laser cutting technology convergence:Integration of fiber laser systems with traditional mechanical slitting lines is enabling prototype and short-run production for aerospace inductor manufacturers demanding tighter dimensional tolerances.
- China dual carbon policy tailwind:MEE enforcement on volatile organic compound emissions and GB standard upgrades are accelerating consolidation among coating specialists serving export-oriented transformer OEMs.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for phosphate and organic resin systems that match hexavalent chromium performance in salt spray and thermal cycling tests remains concentrated among retiring specialists in European supplier ecosystems.
- Multi-jurisdiction certification timelines:Simultaneous REACH compliance in Europe, EPA hazardous air pollutant permitting in the United States, and China GB standard testing creates 18-24 month product qualification cycles that delay revenue recognition.
- Legacy mechanical slitting integration:Laser cutting adoption for high-frequency laminations requires retrofitting or bypassing existing stamping press workflows optimized for mechanical die clearance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Coil Lamination Market |
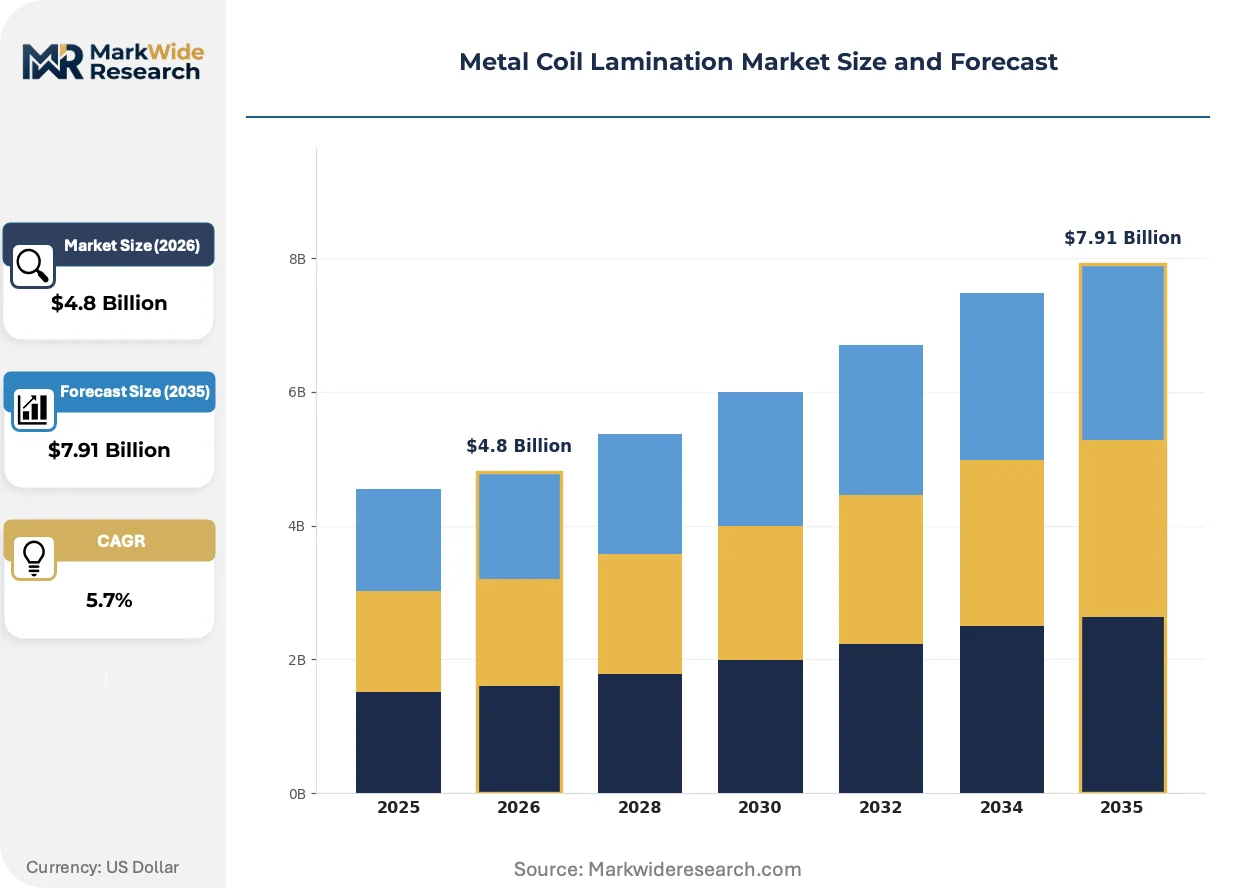
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Rolled, Hot Rolled, Galvanized Steel, Stainless Steel End User: Aerospace, Automotive, Electronics, Home Appliances Application: Transformers, Motors, Inductors, Chokes Technology: Traditional Laminating, Laser Cutting, Die Cutting, CNC Machining |
| Companies Covered | Polytech America, LLC, Nippon Steel Corporation, American Nickeloid Company, Tata Steel, ArcelorMittal, Berlin Metals, Toyo Kohan Co., Ltd., Mitsubishi Chemical Corporation, Lienchy Laminated Metal Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Coil Lamination Market Emerging Trajectories
Process technology and regulatory chemistry are converging to redefine competitive positioning in metal coil lamination, with coating application methods and compliance frameworks evolving faster than installed capacity can adapt.
Laser cutting systems for electrical steel laminations are expanding into high-frequency inductor and precision motor core applications where mechanical die wear produces unacceptable edge burr and dimensional drift. Aerospace suppliers in France and Germany are piloting fiber laser slitting lines for prototype runs of amorphous metal and nano-crystalline core materials. This technology is expanding into short-run production environments previously dominated by hardened tool steel dies, compressing setup times from days to hours and enabling lot sizes below 500 kilograms.
REACH authorization requirements for chromium trioxide in functional coatings are forcing reformulation of insulating layer chemistries across European lamination facilities. ECHA sunset date pressures have accelerated phosphate-based and sol-gel organic resin development programs at coating specialists serving transformer OEMs. German and Austrian suppliers are responding with integrated steelmaking-to-coating lines that capture chemistry control across the full silicon steel processing sequence, locking in thermal expansion matching between substrate and insulation.
Automotive OEMs are consolidating motor core lamination suppliers under single-source contracts with qualification requirements spanning 15-year vehicle platform lifecycles. Tier-1 suppliers in Japan and South Korea are displacing spot-market purchasing with captive coating capacity or exclusive tolling arrangements that guarantee silicon steel grade availability. This concentration is most visible in Germany, where BASF coating chemistry partnerships and Siemens motor design specifications have created closed-loop procurement ecosystems for premium EV traction applications.
Metal Coil Lamination Market Segmentation
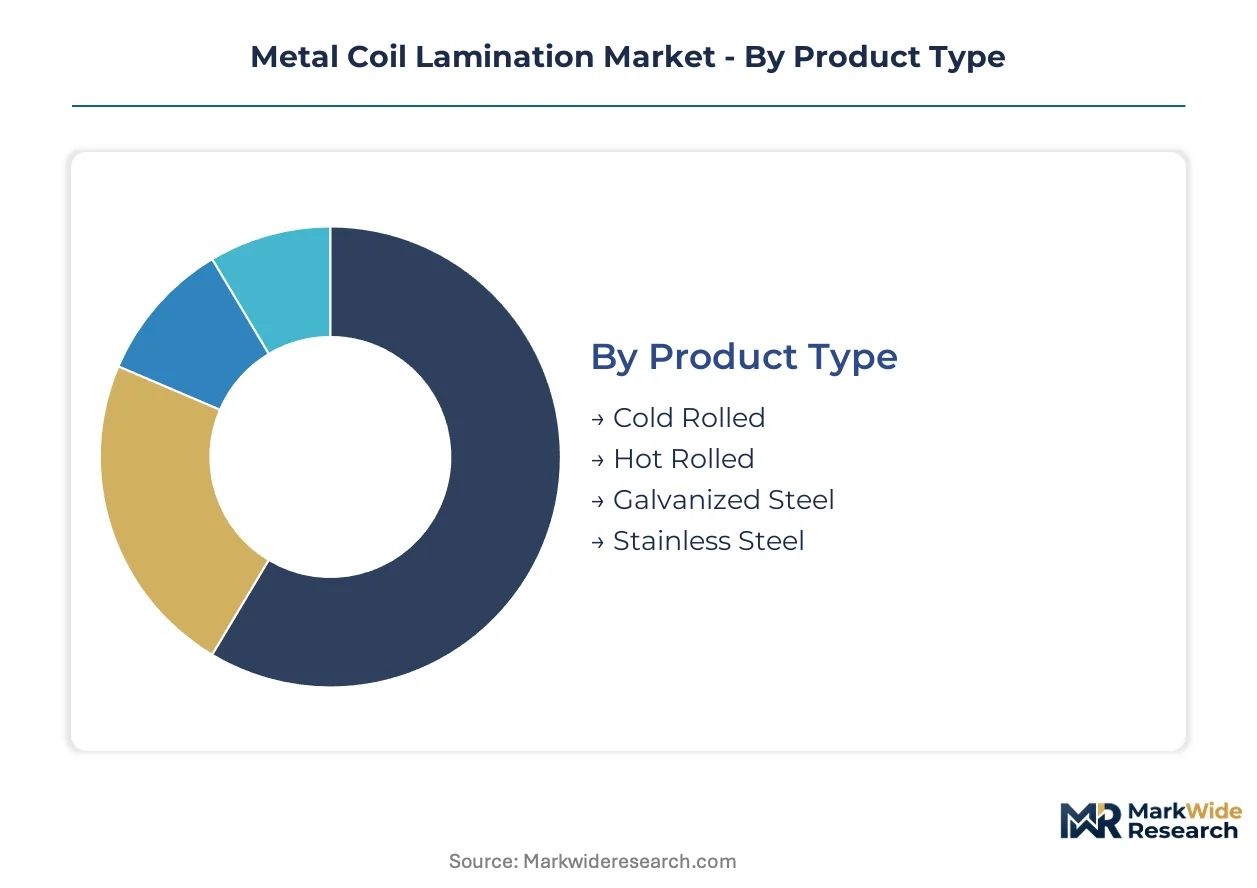
Metal coil lamination segmentation reveals how substrate metallurgy, end-use performance requirements, and processing technology interlock to create distinct competitive arenas. Understanding these splits exposes where coating specialists can defend margin pools against integrated steelmakers.
Product Type:
Galvanized steel commands the volume base while cold rolled products capture precision premiums in tight-tolerance applications.
- Galvanized Steel:Zinc-coated substrates dominate transformer and motor manufacturing chains where corrosion resistance during coil storage and stamping operations outweighs substrate cost premiums. Demand concentrates in Germany and Japan for distribution transformer cores subject to IEC efficiency mandates.
- Cold Rolled:Unoxidized, dimensionally precise strips enable sub-0.5mm gauge lamination for high-frequency inductor applications where eddy current losses scale with thickness squared. Electronics manufacturers in South Korea and Taiwan specify these grades for telecommunications power supplies.
- Hot Rolled:Thicker gauge, oxide-scaled products serve cost-sensitive motor applications where dimensional tolerance relaxation permits mechanical die stamping at higher throughput rates.
- Stainless Steel:Corrosion-immune austenitic and ferritic grades penetrate marine, chemical processing, and medical device inductor niches requiring sterile or salt-spray-resistant core assemblies.
Today's leader: Galvanized Steel. Tomorrow's challenger: Cold Rolled.
End User:
Automotive procurement consolidation contrasts with aerospace fragmentation, creating divergent supplier relationship models.
- Automotive:OEMs in Germany and France are locking in 15-year single-source contracts for EV traction motor laminations under EU Green Deal carbon intensity benchmarks. BASF coating chemistry partnerships with Siemens anchor closed-loop procurement ecosystems.
- Electronics:Telecommunications and computing equipment manufacturers in Japan and South Korea drive ultra-thin gauge demand for high-frequency power conversion. Nippon Steel's amorphous metal expertise targets this precision tier.
- Aerospace:French and German suppliers pilot fiber laser slitting for prototype runs of nano-crystalline core materials, compressing setup times from days to hours for lot sizes below 500 kilograms.
- Home Appliances:Compressor motor and induction heating applications in China sustain high-volume, price-competitive lamination demand subject to MEE volatile organic compound enforcement.
Automotive contracts concentrate supplier power. Electronics specifications fragment it.
Application:
Transformer efficiency regulations are redirecting specifications faster than motor core platforms can adapt.
- Transformers:IEC and national energy agency directives in Japan and South Korea mandate thinner, higher-silicon steel grades that challenge existing lamination line configurations and accelerate phosphate coating chemistry adoption.
- Motors:EV traction applications in Germany and France require thermal expansion matching between silicon steel substrate and insulating coating across extreme operating temperature cycles.
- Inductors:Aerospace and telecommunications equipment demands edge quality and dimensional precision that mechanical die wear compromises, opening entry paths for laser cutting technology.
- Chokes:Power supply filtering applications in consumer electronics tolerate wider tolerance bands, sustaining mechanical stamping volume despite efficiency disadvantages.
Transformers lead regulatory-driven specification change. Inductors enable process technology disruption.
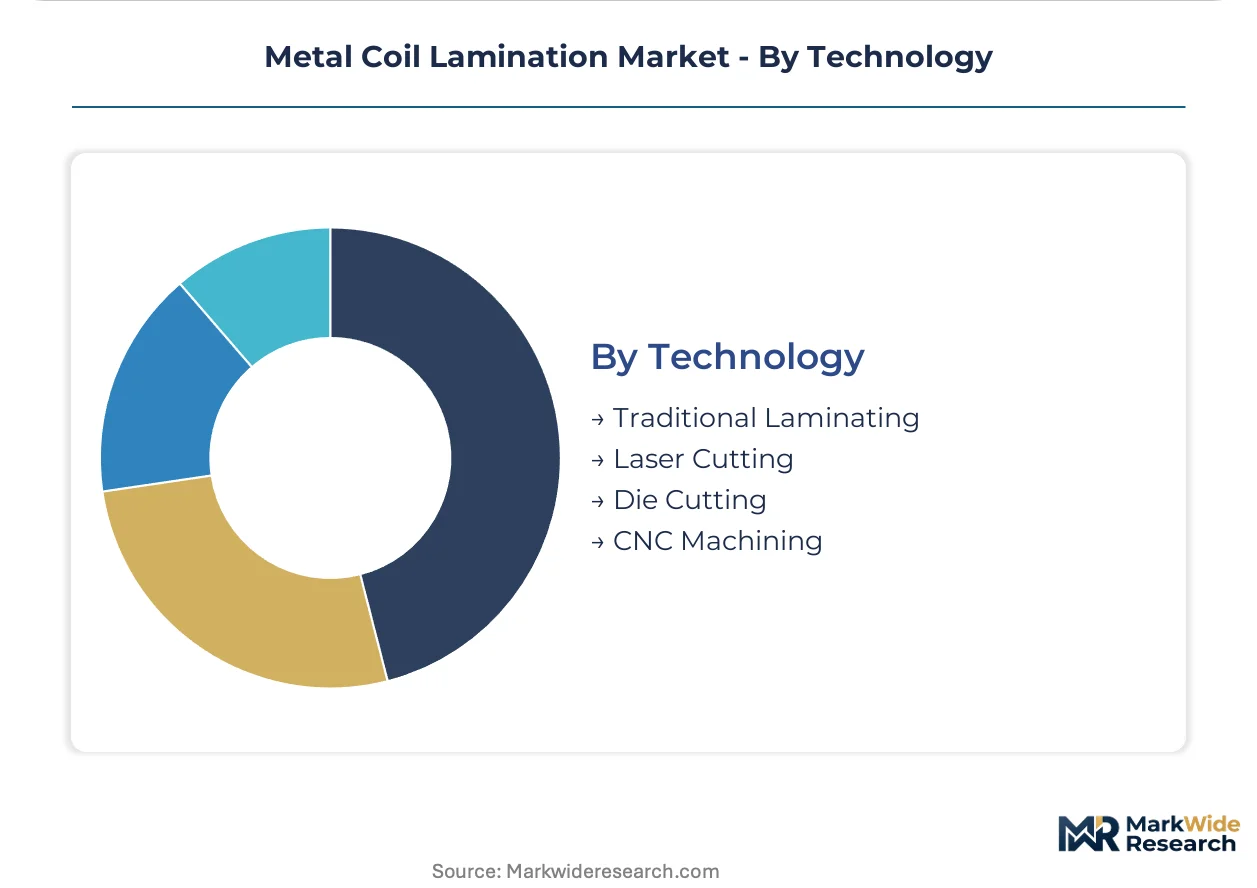
Technology:
Mechanical throughput advantages face precision erosion from thermal and edge-quality limitations.
- Traditional Laminating:Mechanical slitting and stamping lines retain bulk installed capacity for transformer and motor manufacturing, though die wear produces edge burr that elevates eddy current losses in high-frequency service.
- Laser Cutting:Fiber laser systems displace mechanical methods in prototype and short-run production for aerospace inductor applications, enabling lot sizes below 500 kilograms with setup times compressed from days to hours.
- Die Cutting:Hardened tool steel dies sustain high-volume home appliance and standard motor production where edge quality requirements permit 50-100 micron burr tolerances.
- CNC Machining:Subtractive milling processes serve specialty core geometries and repair operations where stamping die amortization proves uneconomic below 10,000-unit production runs.
Traditional Laminating holds volume dominance. Laser Cutting climbs the fastest on precision premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coating chemists and silicon steel metallurgists concentrate in Germany's Ruhr industrial corridor and Japan's Chubu region, anchoring technical capability clusters that serve transformer and motor core manufacturers worldwide.
Germany
EV traction motor procurement from BASF-Siemens partnerships drives laminated electrical steel demand as OEMs lock in 15-year supply contracts. REACH authorization deadlines for chromium trioxide accelerate phosphate coating chemistry transitions at facilities in Duisburg and Dortmund. The North Rhine-Westphalia steel-coating cluster captures thermal expansion matching expertise for extreme-temperature motor applications.
Japan
Ultra-thin gauge expertise for high-frequency inductor applications concentrates around Nagoya and Tokyo Bay manufacturing zones. METI efficiency mandates redirect transformer procurement toward thinner, higher-silicon steel grades that challenge legacy lamination configurations. Nippon Steel anchors amorphous metal development partnerships serving telecommunications power supply manufacturers in Aichi Prefecture.
China
Export-oriented transformer OEMs in Jiangsu and Zhejiang provinces face MEE volatile organic compound enforcement accelerating coating specialist consolidation. GB standard upgrades on insulating layer specifications constrain process choices for suppliers serving European and North American markets. The Yangtze River Delta cluster integrates silicon steel rolling with captive lamination coating for domestic EV motor programs.
United States
EPA hazardous air pollutant standards force reformulation of hexavalent chromium coating systems at facilities serving distribution transformer manufacturers. FERC grid modernization directives sustain procurement of high-efficiency core materials for utility-scale power infrastructure. Pittsburgh and Cleveland anchor legacy steelmaking regions adapting mechanical slitting lines for phosphate-based insulation chemistries.
India
PLI scheme beneficiaries in Maharashtra and Gujarat establish localized lamination coating partnerships for two-wheeler and passenger EV traction motor cores. BIS certification timelines for imported silicon steel grades delay qualification of thinner, higher-efficiency substrates. The Pune-Nashik industrial corridor concentrates automotive supplier ecosystems developing captive coating capacity under domestic OEM single-source contracts.
Metal Coil Lamination Market Vendor Landscape
Top-tier vendors anchor integrated steelmaking-to-coating capabilities, while regional specialists occupy toll-coating and chemistry formulation niches. Market structure reflects concentration among Asian and European producers with captive silicon steel supply, alongside fragmentation among North American coating service providers. Three archetypes dominate: integrated steelmakers controlling full processing chains, coating chemistry specialists licensing formulation IP, and toll laminators serving spot-market transformer manufacturers. Competitive moves center on backward integration into silicon steel rolling and strategic partnerships locking in automotive OEM qualification cycles.
Within the integrated producer tier, ArcelorMittal and Nippon Steel occupy positions spanning substrate metallurgy through insulation application. Tata Steel exemplifies the automotive-focused archetype through R&D partnerships with OEM motor core programs. Among coating chemistry specialists, Mitsubishi Chemical Corporation represents the formulation-driven segment developing phosphate and sol-gel organic resin systems. Toyo Kohan Co., Ltd. sits within the precision lamination tier serving electronics and telecommunications equipment manufacturers. These groupings illustrate how competitive positioning splits between scale-driven substrate control and specialization in high-frequency, tight-tolerance applications.
| Leading Market Players |
|---|
| Polytech America, LLC |
| Nippon Steel Corporation |
| American Nickeloid Company |
| Tata Steel |
| ArcelorMittal |
| Berlin Metals |
| Toyo Kohan Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Lienchy Laminated Metal Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between IEC-certified high-silicon transformer laminations and commodity motor-grade coatings manifests in divergent pricing power and supply chain configurations across Germany, Japan, and China. Premium tier suppliers capture thermal expansion matching premiums through captive silicon steel rolling, while spot-market toll coaters absorb raw material volatility without backward integration buffers.
Pricing Analysis
Bundled coating-and-substrate contracts dominate EV traction motor procurement, while unbundled toll-coating services sustain transformer manufacturers with volatile silicon steel positions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with automotive OEMs least price-sensitive due to 15-year platform lock-ins. Pricing pressure stems from REACH-driven chemistry reformulation capex, while home appliance manufacturers exhibit highest price sensitivity in mechanical stamping tiers.
Supply Chain Analysis
Reverse-logistics flows for coating line decommissioning and hexavalent chromium waste recovery concentrate in Germany's Ruhr corridor and Japan's Chubu region. Supply draws from integrated steelmaking clusters in Germany, Japan, and China, with silicon steel slab and phosphate chemical feedstocks as critical inputs. Single-source vulnerability permeates automotive motor core procurement, where BASF-Siemens partnerships control coating chemistry IP. Distribution runs through transformer OEM direct contracts and spot-market toll laminators serving fragmented motor manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU REACH compliance costs and China's MEE enforcement timelines, with coating chemistry specialists relocating formulation R&D to jurisdictions with extended sunset dates.
For Market Incumbents: Deepen thermal expansion matching capabilities for EV traction applications through captive silicon steel rolling investments in North Rhine-Westphalia, defending against emerging laser-cutting entrants in aerospace inductor niches. Prioritize phosphate coating chemistry certification ahead of ECHA authorization deadlines to lock in automotive OEM single-source renewals. For New Entrants and Emerging Players: The premium-economy price-point gap in cold rolled precision laminations for telecommunications power supplies offers white-space entry. Target South Korean and Taiwanese electronics manufacturers with fiber laser slitting capabilities for lot sizes below 500 kilograms, bypassing mechanical die amortization barriers that protect incumbent volume positions. For Investors and Strategic Acquirers: Consolidation pressure builds where coating chemistry expertise concentrates among retiring European specialists without succession pipelines. Five-to-ten year viability favors acquisition of phosphate formulation specialists with automotive qualification credentials, with ECHA sunset date adherence as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Steel Rolling | ArcelorMittal captures substrate cost control and thermal expansion matching precision for transformer efficiency mandates. |
| Phosphate Coating Chemistry Transition | German suppliers secure REACH compliance ahead of chromium trioxide sunset dates, locking in automotive OEM contracts. |
| Laser Cutting Technology Adoption | French aerospace suppliers compress prototype setup times from days to hours for nano-crystalline core materials. |
| Captive Coating Capacity in India | PLI scheme beneficiaries localize lamination supply for two-wheeler and passenger EV traction motor programs. |
| Long-term Supply Agreement with Transformer OEMs | Japanese producers guarantee silicon steel grade availability under METI efficiency directive procurement shifts. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with coating line engineers, transformer OEM procurement directors, automotive platform engineers, and phosphate chemistry R&D leads combine with secondary validation from IEC specification databases, ECHA authorization registries, SEC filings of integrated steelmakers, and customs trade data for silicon steel imports. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Historical trendline analysis of coating capacity utilization and silicon steel price indices informs projection frameworks across the analysis window. Segmentation dimensions include substrate metallurgy grade, end-use sector, application type, and technology platform, with CAGRs derived from elasticity modeling against EV motorization rates and transformer efficiency regulatory trajectories. Coating chemistry reformulation timelines and laser cutting adoption curves serve as industry-specific forecast inputs.
Caveats apply where ECHA sunset date extensions, MEE enforcement intensity variations, or automotive platform delays could materially shift the outlook. Forecasts reflect documented assumptions regarding silicon steel input cost stability and qualification cycle durations. Periodic stress-testing of base assumptions against regulatory announcement calendars and OEM contract award patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Drums Market
Metals
Ferrosilicon Magnesium Market
Metals
Silico Manganese Market
Metals
Global Tool Steel Market
Metals
Zinc Plating Market
Metals
Weathering Steel Market
Metals
Recycled Metal Market
Metals
Electrodeposited Copper Foil Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Platinum Compounds Market
Metals
China Copper Market
Metals
Aluminum Wire Market
Metals
Barium Market
Metals
Aluminum Sheet Market
Metals
Ferro Vanadium Market
Metals
Transition Metals Market