
 Europe Welding Consumables Market | 2026-2036
Europe Welding Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Welding Consumables Market Intelligence
The Europe welding consumables market is restructuring around a widening split between premium alloy wires for automated fabrication and commodity electrodes for manual repair work. Lincoln Electric Holdings Inc. leverages its automation integration expertise to dominate robotic MIG/MAG supply chains for German automotive Tier 1s. ESAB Corporation anchors its position through deep R&D intensity in submerged arc consumables for Baltic shipyards. voestalpine Böhler Welding differentiates via specialized nickel-based filler metals serving Austrian power generation and Czech pressure vessel fabricators.
Welding consumables encompass electrodes, filler metals, welding wires, and fluxes formulated with precise chemical compositions to metallurgically bond base materials under thermal arc conditions. Solid wires for MIG processes typically carry AWS ER70S-6 specifications with deoxidizing manganese and silicon levels engineered for CO2 or argon-rich shielding gases, while flux-cored variants embed slag-forming compounds within a tubular sheath to enable all-position welding without external gas protection. Welding wires for automotive manufacturing represent the fastest-expanding product category as OEMs convert structural assemblies to high-strength steel grades demanding exacting weld metal chemistry. Filler metals for shipbuilding sustain mature margin pools through long-term supply agreements with Polish and Romanian yards, though electrodes for manual stick applications face gradual displacement by flux-cored alternatives in fabrication shops.
CE marking under the EU Machinery Directive and REACH compliance through ECHA govern chemical composition disclosures and operator safety for welding consumables sold across member states, while the F-Gas Regulation progressively restricts fluorinated shielding gas blends that many TIG applications historically employed. Germany's KBA and France's ANSM coordinate with notified bodies to enforce welding procedure qualification standards for pressure equipment and transport structures, tightening market access for uncertified suppliers. Stakeholders must monitor how the EU AI Act and evolving CSRD disclosure requirements reshape liability frameworks for automated welding systems that embed consumable selection algorithms.
Market Dynamics
The European welding consumables sector is bifurcating between automated fabrication lines demanding precision-engineered alloy wires and legacy manual repair operations clinging to commodity electrodes. This structural tension is compressing margins at the mid-tier while concentrating value capture among suppliers with metallurgical R&D depth and automation integration capabilities.
Growth Catalysts
- EU Green Deal compliance mandates:The EU Green Deal and F-Gas Regulation are forcing reformulation of flux chemistries toward low-emission variants, creating replacement demand for certified consumable portfolios across German and Polish fabrication shops.
- Automotive lightweighting:German OEMs and Eastern European Tier 1s are expanding automated MIG/MAG lines for high-strength steel assemblies, pulling specialized filler metals with exacting manganese-silicon ratios.
- Baltic shipyard modernization:Polish and Romanian yards are renewing long-term supply agreements for submerged arc consumables as naval and commercial vessel orders accumulate.
Market Restraints
- Alloy raw material volatility:Nickel and molybdenum price swings destabilize cost structures for specialized filler metal producers serving Austrian power generation fabricators.
- REACH disclosure burdens:ECHA chemical composition reporting requirements impose compliance costs that disproportionately burden small electrode manufacturers without dedicated regulatory staff.
- Flux-cored wire substitution:Tubular wire technologies are displacing manual stick electrodes in Czech and Slovak fabrication shops, eroding volume pools for legacy product lines.
Strategic Opportunities
- Recyclable packaging mandates:The EU Green Deal's packaging waste directives create first-mover advantages for suppliers deploying biodegradable spool materials and closed-loop wire reclaim systems.
- AI-integrated consumable selection:The EU AI Act is reshaping liability frameworks for automated welding systems, opening consulting revenue streams around algorithm-validated filler metal specification.
- Romanian industrial catch-up:Underpenetrated fabrication capacity in Transylvanian automotive supplier parks offers volume expansion for flux-cored wire distributors with local stocking infrastructure.
Industry Challenges
- Welding procedure qualification bottlenecks:Germany's KBA and France's ANSM coordinate enforcement of pressure equipment standards, extending certification timelines for uncertified consumable entrants by 8-14 months.
- Automation technician scarcity:Robotic welding line deployment outpaces supply of operators capable of programming MIG/MAG parameter sets for high-strength steel chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Welding Consumables Market |
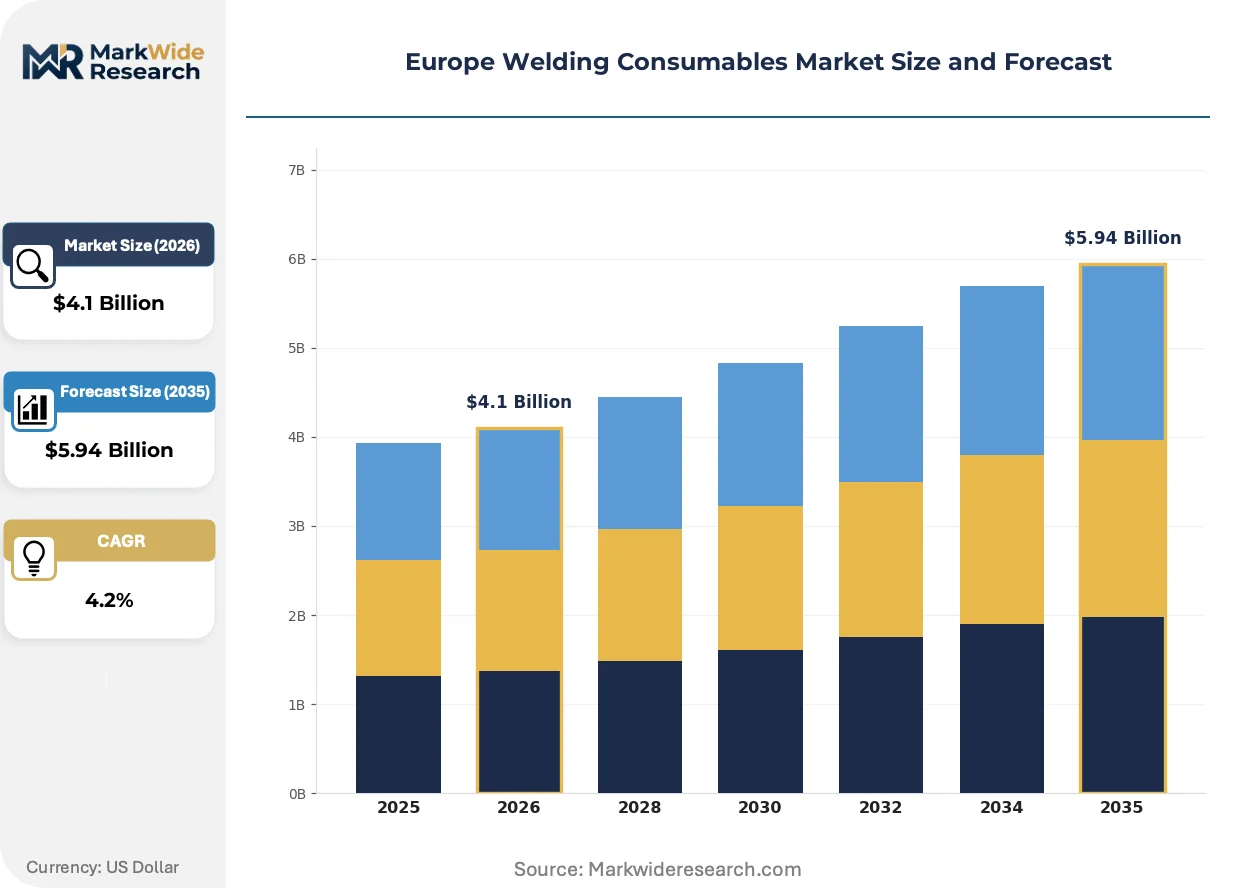
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Filler Metals, Welding Wires, Fluxes End User: Aerospace, Automotive, Construction, Shipbuilding Technology: MIG, TIG, Stick, Submerged Arc Application: Manufacturing, Repair, Maintenance, Fabrication |
| Companies Covered | Kemppi Oy, Carl Cloos Schweisstechnik GmbH, Lincoln Electric Holdings Inc., Hobart Welders, EWM AG, ESAB Corporation, voestalpine Böhler Welding, AMADA WELD TECH, Fronius International GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Welding Consumables Market Strategic Shifts & Innovations
European welding consumables are converging with digital manufacturing systems and circular economy mandates, reshaping how filler metals are specified, delivered, and recovered. Three forces dominate this transition.
Robotic wire feeding systems with real-time arc monitoring are automating parameter adjustment during automotive structural welding. German Tier 1 suppliers deploy these systems at scale across Saxony and Bavaria assembly plants. The technology is automating quality assurance steps that previously required manual weld inspection, compressing cycle times for high-strength steel joints.
The F-Gas Regulation is progressively restricting fluorinated shielding gas blends historically standard in TIG applications. Industrial gas distributors are reformulating argon-helium mixtures to maintain arc stability without prohibited compounds. Baltic and North Sea fabricators dependent on precision TIG work face the steepest reformulation costs and are accelerating qualification of alternative shielding chemistries.
Consolidated procurement through automotive OEM direct contracts is displacing distributor-mediated electrode purchases. Tier 1 metal fabricators in the Czech Republic and Hungary now negotiate annual wire volumes directly with consumable manufacturers, bypassing traditional wholesale channels. This concentration is most visible in Germany's industrial belt, where Volkswagen and BMW supplier parks enforce single-source consumable specifications.
Europe Welding Consumables Market Segmentation
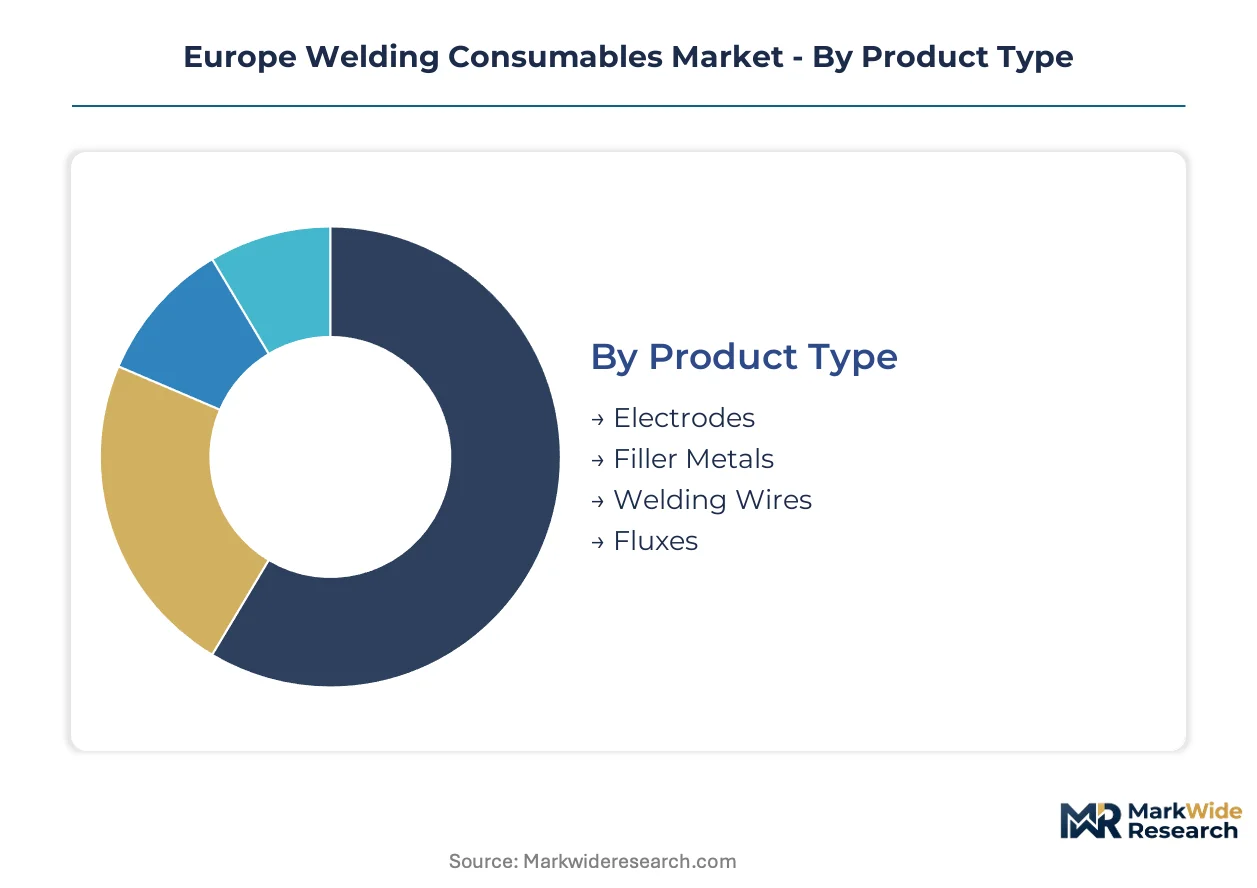
European welding consumables procurement splits sharply between automated fabrication lines demanding precision-engineered alloys and manual repair operations sourcing commodity electrodes. Understanding these segment boundaries clarifies where margin pools concentrate and which technologies are displacing legacy categories.
Product Type:
Replacement cycles vary dramatically across product categories, with automated wire systems refreshing every 18-24 months while manual electrode stocks turn over more slowly.
- Welding Wires:Solid and flux-cored formulations carry AWS ER70S-6 specifications with manganese-silicon deoxidizers calibrated for CO2 or argon-rich shielding. German automotive Tier 1s in Saxony and Bavaria anchor procurement volumes as OEMs convert structural assemblies to high-strength steel grades demanding exacting weld metal chemistry.
- Filler Metals:Nickel-based and specialized alloy formulations serve pressure vessel fabricators and power generation equipment manufacturers. Austrian fabricators and Czech boiler shops sustain mature margin pools through long-term supply agreements tied to CE marking under the EU Machinery Directive.
- Electrodes:Manual stick electrodes face gradual displacement by flux-cored alternatives in fabrication shops across Slovakia and the Czech Republic.
- Fluxes:Submerged arc and agglomerated formulations enable high-deposition welding in Baltic shipyards, with reformulation pressures mounting under EU Green Deal low-emission mandates.
Volume placements concentrate in welding wires; the faster expansion belongs to filler metals.
End User:
Cost tier differentiation separates premium alloy specifications serving automated OEM lines from commodity grades supplying maintenance contractors.
- Automotive:German OEMs and Eastern European Tier 1s operate the most demanding procurement specifications, requiring robotic MIG/MAG compatibility and lot-traceable chemistry certificates. Direct annual contracts with consumable manufacturers are displacing traditional distributor channels in Czech and Hungarian supplier parks.
- Shipbuilding:Polish and Romanian yards renew long-term agreements for submerged arc consumables as naval and commercial vessel orders accumulate. ECHA REACH compliance documentation adds procurement friction for uncertified suppliers.
- Construction:Infrastructure and commercial building contractors source commodity electrodes and flux-cored wires through wholesale distributors, with price sensitivity dominating supplier selection.
- Aerospace:Precision TIG applications in French and German aerostructures manufacturing require specialized filler metals qualified to stringent procedure standards enforced by France's ANSM and Germany's KBA.
Revenue concentration sits with automotive; the steepest expansion trajectory runs through shipbuilding.
Technology:
Application intensity determines technology selection, with high-volume production lines favoring continuous wire processes over intermittent stick methods.
- MIG:Metal inert gas processes dominate automated structural welding in German automotive plants, with real-time arc monitoring systems now automating parameter adjustment during high-strength steel joint assembly.
- Submerged Arc:High-deposition welding for thick plate sections anchors Baltic shipyard operations, with voestalpine Böhler Welding and ESAB Corporation competing on R&D intensity for naval contract specifications.
- TIG:Tungsten inert gas precision work faces reformulation pressure as the F-Gas Regulation restricts fluorinated shielding gas blends historically standard in aerospace and nuclear applications.
- Stick:Manual shielded metal arc welding clings to repair and maintenance operations where portability outweighs deposition efficiency, though flux-cored wire substitution accelerates in Czech fabrication shops.
Deployment density peaks with MIG; the technology gaining share fastest is submerged arc.
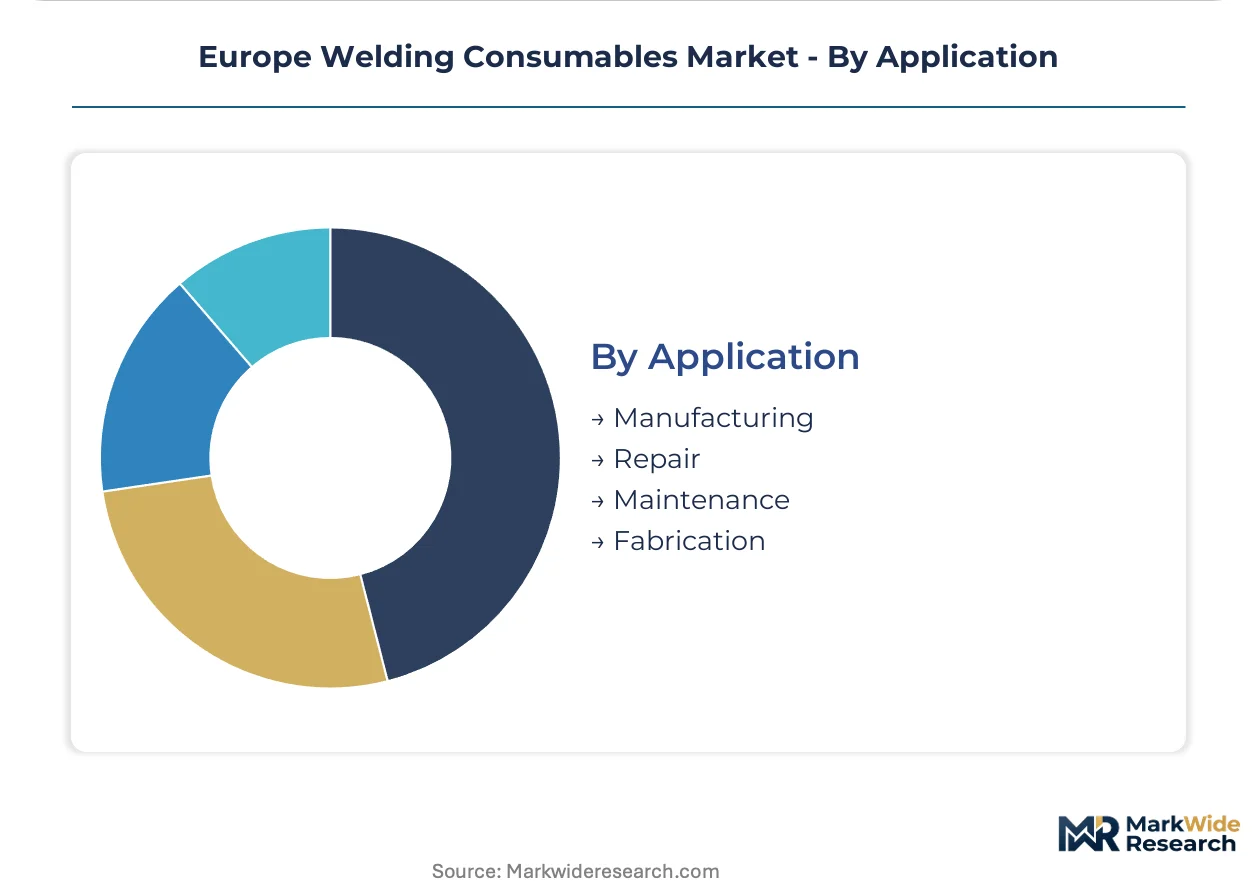
Application:
Customer type bifurcation separates OEM direct procurement from distributor-mediated maintenance purchasing.
- Manufacturing:Original equipment production lines in Germany's industrial belt enforce single-source consumable specifications, with Volkswagen and BMW supplier parks consolidating annual wire volumes under direct manufacturer contracts.
- Fabrication:Custom metalworking shops across Poland and Romania source flux-cored and solid wires through regional distributors, with CE marking compliance filtering supplier pools.
- Repair:Field maintenance operations rely on portable electrode supplies for on-site structural corrections, though this segment faces gradual erosion from flux-cored wire adoption.
- Maintenance:Scheduled upkeep contracts for industrial equipment and infrastructure sustain steady demand for commodity electrodes, with procurement centralized through facilities management providers.
Contract value concentrates in manufacturing; the application climbing fastest is fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial belt and Bavarian automotive corridors concentrate the continent's most demanding welding consumables procurement, with Polish shipyards and Czech fabrication clusters anchoring volume growth across Central Europe.
Germany
Automotive OEMs in Saxony and Bavaria operate automated MIG/MAG lines for high-strength steel assemblies, pulling specialized filler metals with exacting chemistry certificates. KBA enforcement of pressure equipment standards tightens market access for uncertified suppliers. Volkswagen and BMW supplier parks in Lower Saxony and Munich's industrial periphery enforce single-source consumable specifications under direct manufacturer contracts.
Poland
Naval and commercial vessel orders accumulate at Gdańsk and Szczecin shipyards, renewing long-term agreements for submerged arc consumables. ECHA REACH compliance documentation adds procurement friction for uncertified entrants. Silesian fabrication shops source flux-cored wires through regional distributors, with CE marking compliance filtering supplier pools.
Czech Republic
Boiler shops and pressure vessel fabricators sustain mature margin pools through long-term supply agreements tied to CE marking requirements. F-Gas Regulation restrictions on fluorinated shielding gases accelerate qualification of alternative chemistries. Ostrava's steelmaking heritage supports specialized nickel-based filler metal demand from power generation equipment manufacturers.
France
ANSM coordinates with notified bodies to enforce welding procedure qualification standards for aerospace and nuclear applications. Precision TIG work in Toulouse's aerostructures manufacturing requires specialized filler metals with stringent certification. Normandy shipyards and Lyon-area fabrication clusters diversify procurement across submerged arc and flux-cored wire categories.
Romania
Transylvanian automotive supplier parks offer volume expansion for flux-cored wire distributors building local stocking infrastructure. EU Green Deal packaging waste directives create first-mover advantages for suppliers deploying biodegradable spool materials. Constanța shipyard modernization and Bucharest-area metalworking shops concentrate emerging fabrication demand.
Europe Welding Consumables Market Key Industry Players
Premium-margin players sit above commodity-margin players across automation integration and metallurgical R&D depth, with the sector consolidating around three distinct tiers. Integrated welding equipment manufacturers capture value through robotic system bundling. Specialized alloy producers defend position via procedure qualification lock-in with pressure equipment fabricators. Regional distributors face compression as OEM direct procurement bypasses traditional wholesale channels. Dominant competitive moves include backward integration into wire drawing operations and geographic expansion through local stocking partnerships.
Among Nordic and Germanic fabricators, Kemppi Oy and Carl Cloos Schweisstechnik GmbH exemplify the automation-integrated archetype, while Lincoln Electric Holdings Inc. occupies a position spanning equipment and consumable supply. ESAB Corporation and voestalpine Böhler Welding represent the specialized alloy tier, with their respective emphases on submerged arc systems and nickel-based formulations. These five entities collectively illustrate how competitive positioning stratifies across robotic integration capability, metallurgical R&D intensity, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Kemppi Oy |
| Carl Cloos Schweisstechnik GmbH |
| Lincoln Electric Holdings Inc. |
| Hobart Welders |
| EWM AG |
| ESAB Corporation |
| voestalpine Böhler Welding |
| AMADA WELD TECH |
| Fronius International GmbH |
| Others |
Cost & Logistics Intelligence
Nickel and molybdenum alloy feedstock costs cascade through three distinct pricing tiers for European welding consumables, with German automotive OEMs absorbing premium-grade wire premiums while Polish fabrication shops negotiate spot-market electrodes. Raw material volatility concentrates margin pressure on specialized filler metal producers serving Austrian power generation fabricators, forcing mid-tier suppliers toward commodity positioning or vertical retreat.
Pricing Analysis
Throughput-linked pricing for robotic MIG/MAG wire systems anchors value capture for automation-integrated suppliers serving Saxony and Bavaria assembly plants. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked procedure-qualified alloys from uncertified commodity electrodes. Cost compression in manual stick electrode tiers is intensifying because flux-cored wire substitution accelerates in Czech and Slovak fabrication shops. Construction contractors sourcing through wholesale distributors exhibit highest price sensitivity; German automotive Tier 1s negotiating direct annual contracts show lowest.
Supply Chain Analysis
Inland freight and cross-border logistics costs from German wire drawing mills to Eastern European distributor warehouses shape procurement economics for Polish and Romanian fabrication clusters. Supply concentrates in Germany, Austria, and Italy for precision alloy formulations; nickel and manganese raw material sourcing draws from Scandinavian and Russian mining corridors. Single-source vulnerability runs through specialized submerged arc flux formulations qualified for Baltic shipyard contracts. Distribution runs through manufacturer-direct channels for automotive OEMs and regional wholesale networks for construction maintenance buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European welding consumables is consolidating into a two-tier structure where automation-integrated metallurgical specialists capture value and undifferentiated electrode manufacturers face displacement. REACH compliance burdens and F-Gas Regulation reformulation costs are forcing weaker players toward exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into wire drawing operations and captive supply of nickel-based alloy feedstocks. ESAB Corporation and voestalpine Böhler Welding demonstrate how procedure qualification lock-in with KBA and ANSM enforcement bodies defends margin pools against emerging low-cost entrants. Prioritize R&D intensity in low-emission flux formulations ahead of EU Green Deal packaging mandates. For New Entrants and Emerging Players: E-commerce and digital specification platforms offer route-to-market bypass for Romanian Transylvanian automotive supplier parks currently underserved by local stocking infrastructure. White-space concentration sits with flux-cored wire distribution in Bucharest-area metalworking clusters and biodegradable spool packaging for EU Green Deal first-mover positioning. Partner with regional fabrication cooperatives for CE marking compliance navigation. For Investors and Strategic Acquirers: Accelerated direct procurement contracting between Volkswagen and BMW supplier parks and consumable manufacturers is the leading indicator that distributor-mediated channel structures are structurally weakening. Five-to-ten year viability favors specialized alloy producers with KBA pressure equipment certification and automated welding system integration capabilities. Watch for ANSM enforcement tightening on TIG procedure qualification as signal for aerospace-grade filler metal consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Drawing | Captive supply of manganese-silicon alloy feedstock reduces exposure to nickel price volatility for German producers. |
| Low-Emission Flux Reformulation | EU Green Deal compliance creates replacement demand cycles across Polish and Czech fabrication shop networks. |
| Biodegradable Spool Packaging Deployment | Packaging waste directive first-mover positioning unlocks preferential procurement from sustainability-mandated OEMs. |
| AI-Integrated Consumable Selection Consulting | EU AI Act liability frameworks open algorithm-validation revenue streams for automation-integrated suppliers. |
| Local Stocking Partnership in Romania | Transylvanian automotive supplier park penetration captures volume expansion in underdistributed Eastern European clusters. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across welding consumable manufacturers, automotive Tier 1 procurement directors, Baltic shipyard supply chain managers, and ECHA compliance consultants. ECHA REACH substance databases, KBA pressure equipment certification registries, SEC 10-K filings from listed equipment manufacturers, and EU customs wire trade statistics provided validation layers. Bottom-up volume modeling from end-use application clusters and top-down value reconciliation from manufacturer revenue disclosures were cross-checked for consistency.
Data-stream reconciliation across shipment volumes, alloy pricing indices, and end-use procurement surveys shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, end-use industry, welding technology, and regional regulatory cluster. CAGRs were derived from trend extrapolation of automation penetration rates and alloy substitution patterns, calibrated against German automotive production forecasts and Baltic shipyard order backlogs.
Inputs from ECHA substance registration databases and KBA certification timelines were available through the study window; gaps in real-time nickel spot pricing granularity and private shipyard contract terms introduce uncertainty bands around specialized filler metal value projections. Stakeholders should weight assumptions against their own operating context and monitor F-Gas Regulation enforcement acceleration as potential forecast revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lithium Tungstate Market
Metals
Steel Wire Market
Metals
Platinum Market
Metals
Copper and Copper Alloy Foil Market
Metals
Silver Cyanide Market
Metals
Stainless Steel Sheet Market
Metals
Liquid Metal Thermal Pad Market
Metals
Electrolytic Manganese Metal Market
Metals
Metal Alloys Market
Metals
Tin Chloride Market
Metals
Metal Powder Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Aluminum Wire Market
Metals
Base Metals Market
Metals
North America Aluminum Market
Metals
Global Precious Metal Market