
 Energy Retrofits Market | 2026-2036
Energy Retrofits Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Retrofits Market Analysis
The EU Green Deal is pivoting commercial real estate toward deep energy renovations across aging building stock. Johnson Controls leverages its building automation expertise to capture large-scale retrofit contracts in metropolitan districts. Siemens sustains technology leadership through integrated energy management platforms that combine HVAC optimization with grid-responsive controls. Ameresco anchors its position through long-term energy savings performance contracts with municipal and federal clients.
Energy retrofits encompass the systematic upgrade of existing building systems—envelope insulation, mechanical equipment, lighting, and on-site generation—to reduce operational energy intensity and carbon emissions, typically targeting performance thresholds of 30-50% reduction in energy use intensity. The service type dimension segments into lighting upgrades, HVAC optimizations, insulation improvements, and renewable integrations, with HVAC optimizations commanding the largest share of contracted value due to equipment replacement cycles and refrigerant phase-down pressures. The end user dimension splits across commercial buildings, residential properties, industrial facilities, and government entities, where commercial buildings generate the steadiest project pipeline because lease restructuring and green certification requirements compress payback tolerance.
The EU Green Deal and national building performance standards shape product specifications and compliance pathways across member states, while the EPA and FERC influence equipment efficiency benchmarks and demand-response integration in the United States. Stakeholders must monitor how tightening embodied carbon regulations and grid-interactivity mandates reshape retrofit scope and technology selection.
Market Dynamics
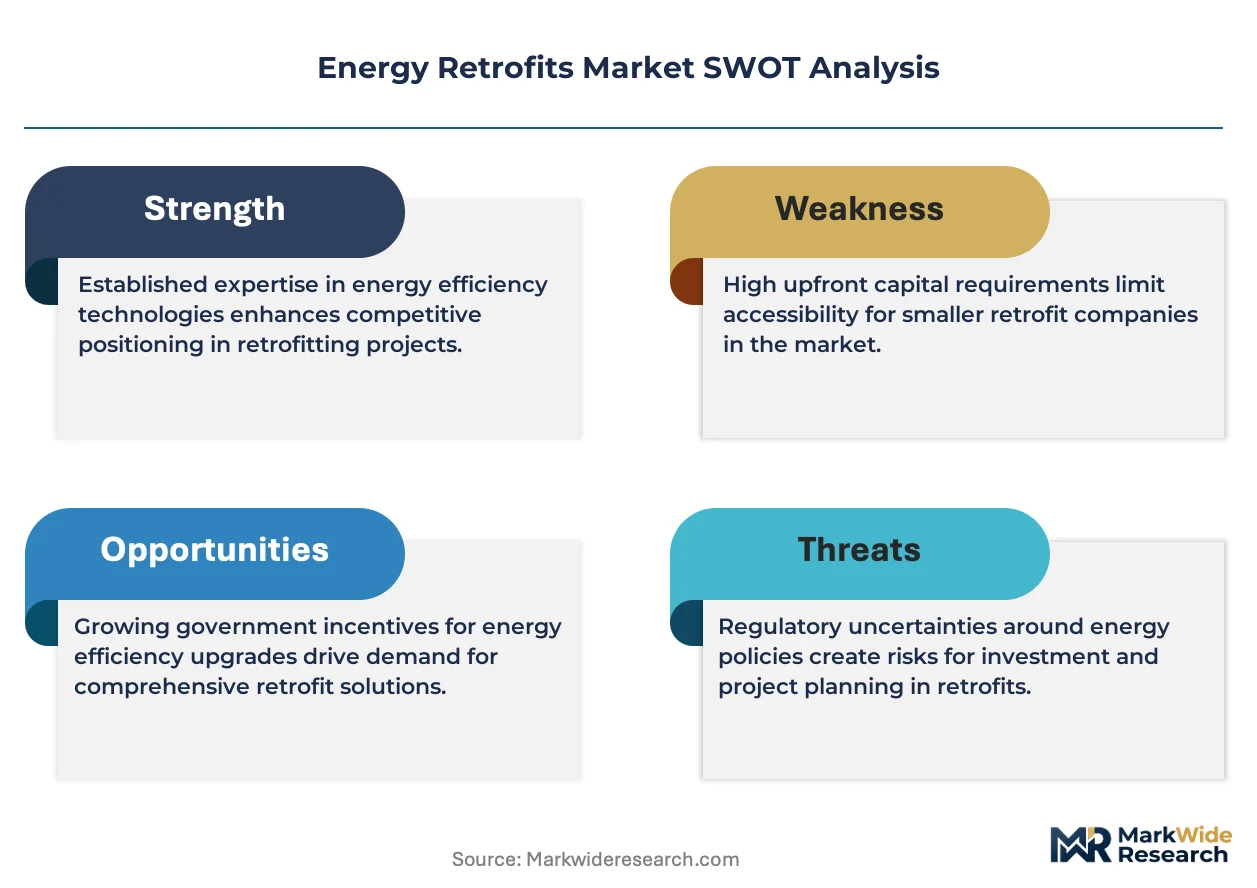
The Energy Retrofits Market pivots on tightening building performance standards that mandate deep renovation of existing commercial and residential stock, compressing payback tolerance and expanding contracted project scopes across metropolitan districts.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates accelerate HVAC equipment replacement cycles in commercial buildings across Germany, France, and the United Kingdom.
- Energy savings performance contracting:Municipal and federal clients lock in long-term retrofit partnerships that transfer technology risk to service providers.
- Grid-interactive building controls:Demand-response integration creates recurring revenue streams for retrofitters who bundle automation with envelope improvements.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings compress margins on HVAC and electrical upgrade contracts.
- Specialized contractor concentration:Deep renovation expertise clusters in Western European urban centers, creating capacity bottlenecks for rural and secondary city projects.
- Embodied carbon accounting gaps:Incomplete lifecycle data for insulation and glazing materials delays compliance pathways under emerging building codes.
Strategic Opportunities
- Poland and Romania building stock:Underpenetrated markets in Eastern Europe offer first-mover advantage as EU cohesion funds flow toward energy efficiency.
- Building-integrated photovoltaics:Convergence of envelope retrofitting with on-site generation opens integrated contracting models.
- France's MaPrimeRénov scheme:Subsidized renovation incentives lower homeowner capital barriers and expand residential addressable market.
Industry Challenges
- BIM-to-operations skill gaps:Shortage of technicians who bridge digital design tools with legacy mechanical systems integration.
- Multi-trade coordination complexity:Deep renovations require sequencing across insulation, HVAC, electrical, and controls specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Retrofits Market |
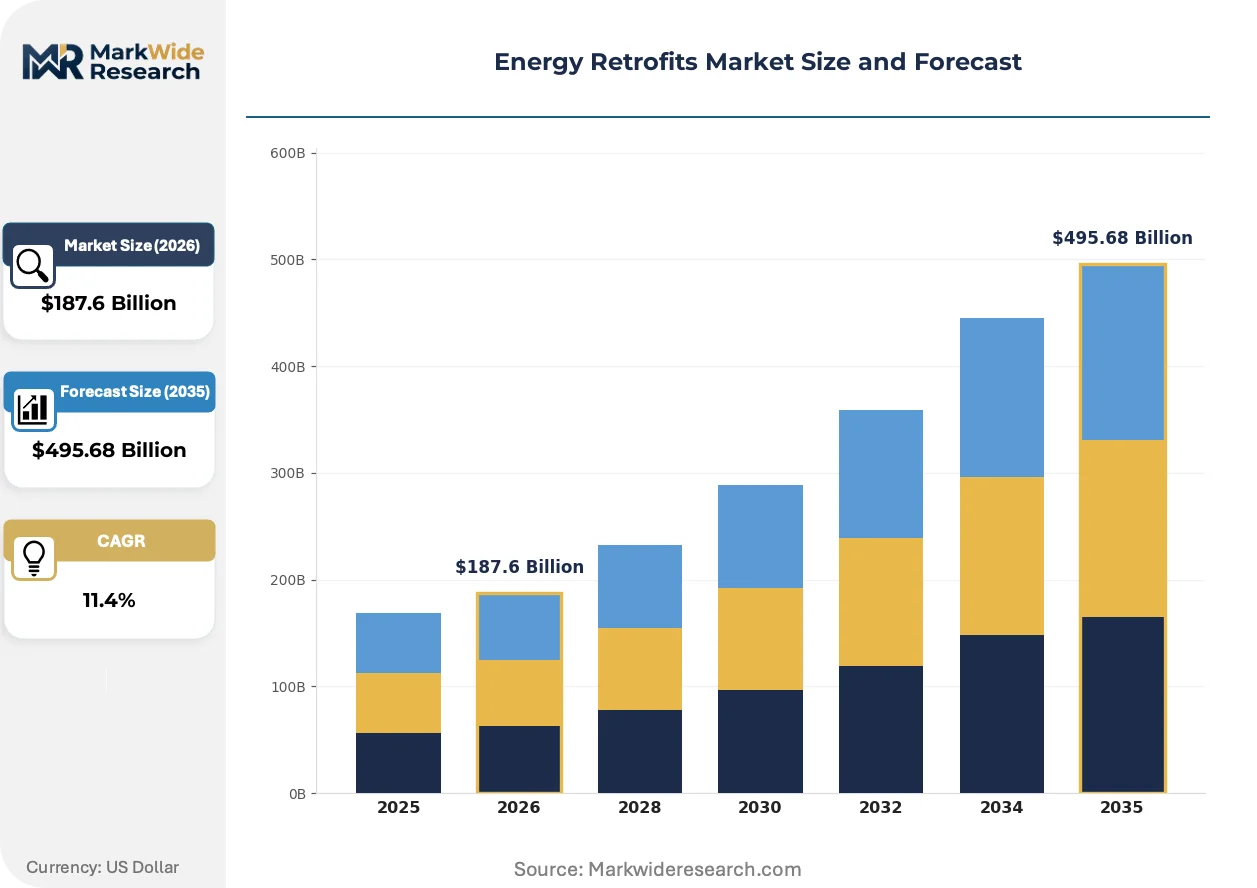
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lighting Upgrades, HVAC Optimizations, Insulation Improvements, Renewable Integrations End User: Commercial Buildings, Residential Properties, Industrial Facilities, Government Entities Technology: Solar Panels, Smart Thermostats, Energy Management Systems, Advanced Lighting Installation: On-site Retrofit, Turnkey Solutions, DIY Kits, Contractor Services |
| Companies Covered | Johnson Controls, Schneider Electric, Siemens, Ameresco, Trane Technologies, Daikin Industries, Eaton, AECOM, Orion Energy Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Retrofits Market Emerging Trajectories
Digital twin technology is absorbing capital allocation across the retrofit value chain, compressing design-to-commissioning timelines and enabling predictive maintenance contracts that extend project revenue horizons.
Heat pump technology is absorbing market share from gas-fired boilers in Northern European retrofits. Commercial landlords in the Netherlands and Denmark specify air-source and ground-source systems to meet district heating decarbonization targets. This shift is absorbing conventional boiler replacement revenue and redirecting it toward integrated thermal storage and smart controls.
The EU Green Deal's Renovation Wave strategy mandates minimum energy performance standards for existing buildings. Member states must transpose these requirements into national building codes by specified deadlines. Deep renovation clusters in Germany and France are responding by bundling envelope, mechanical, and renewable upgrades into single-contract procurement.
Asset owners now require outcome-guaranteed contracts rather than equipment-only procurement. Facility managers in the United Kingdom and Belgium select retrofit partners based on verified energy savings commitments. This behavior compresses traditional equipment vendor margins and elevates service-integrated providers who assume performance risk.
Energy Retrofits Market Segmentation
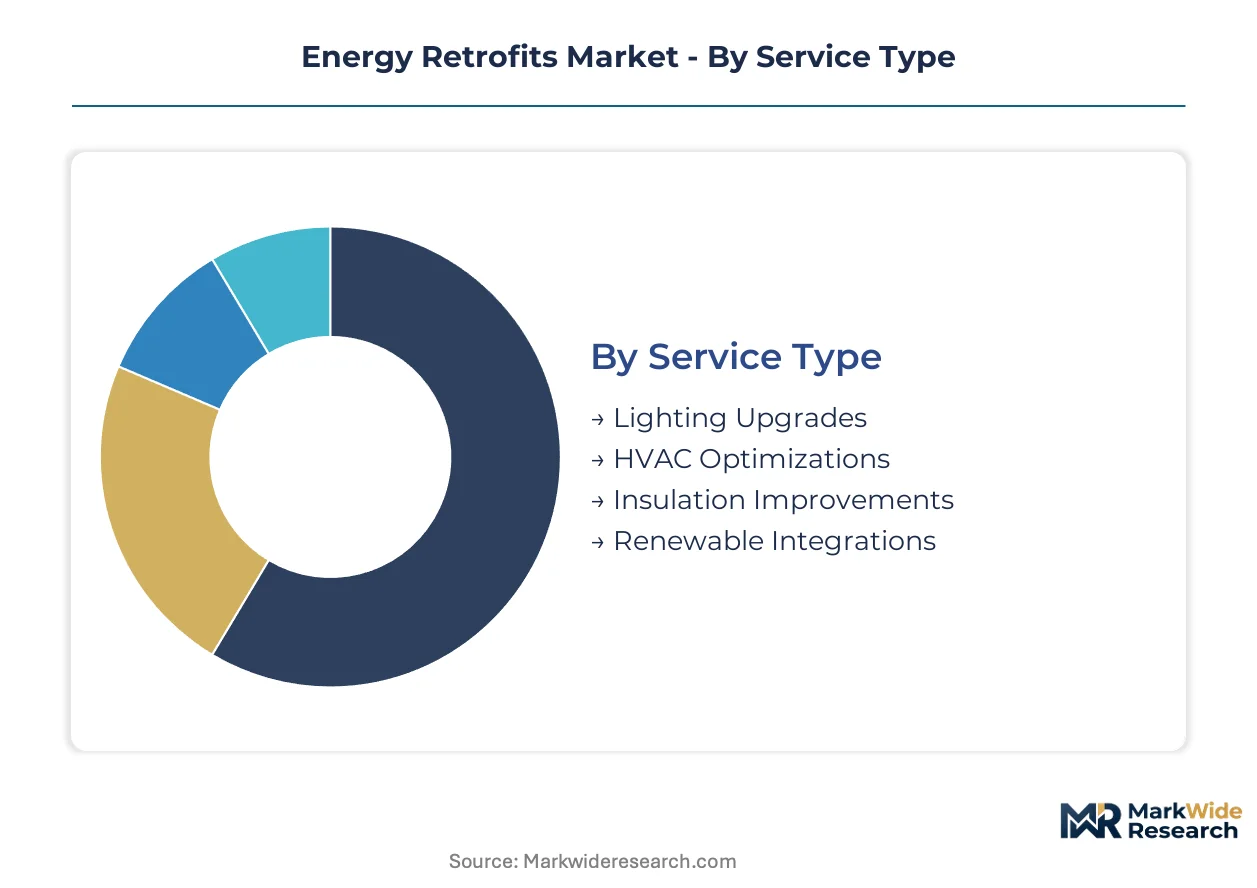
Retrofit procurement patterns diverge sharply between standardized equipment swaps and engineered system overhauls. Segment boundaries determine contractor qualification tiers, financing structures, and performance guarantee frameworks across building portfolios.
Service Type:
Standardization dominates lighting and insulation categories, while HVAC and renewable integrations demand bespoke engineering across building-specific load profiles.
- HVAC Optimizations:Equipment replacement cycles intersect with F-Gas refrigerant phase-down mandates, forcing premature retirement of R-410A systems. Demand concentrates in Germany and France where district heating decarbonization targets compress boiler-to-heat-pump conversion timelines. Long-term service contracts bundle thermal storage with predictive maintenance.
- Insulation Improvements:Envelope upgrades range from batt insulation retrofits to vacuum-insulated panel systems. Deep renovation clusters in the United Kingdom and Belgium prioritize whole-building thermal bridging remediation. Embodied carbon accounting gaps delay material specification under emerging codes.
- Lighting Upgrades:LED retrofits with daylight harvesting controls dominate commercial corridors.
- Renewable Integrations:On-site generation couples with battery storage in net-zero retrofit specifications.
Most installed capacity flows through HVAC Optimizations. Expansion is steepest in Renewable Integrations.
End User:
Payback tolerance and procurement sophistication create distinct customer tiers, from risk-averse municipal buyers to yield-focused commercial landlords.
- Commercial Buildings:Lease restructuring and green certification requirements compress payback thresholds to 5-7 years. Portfolio owners in the Netherlands and Denmark mandate BREEAM Outstanding or equivalent for Class A assets. Energy savings performance contracting transfers technology risk to service providers.
- Government Entities:Federal and municipal clients lock in decade-long retrofit partnerships with guaranteed savings clauses. Procurement favors incumbent contractors with GSA schedule or framework agreement status. Budget certainty outweighs first-cost optimization.
- Residential Properties:France's MaPrimeRénov subsidies lower homeowner capital barriers.
- Industrial Facilities:Process heat electrification drives custom thermal system redesigns.
Contracted value concentrates in Commercial Buildings. Residential Properties are gaining share fastest as subsidy programs mature.
Technology:
Integration complexity separates point solutions from platform-based systems requiring interoperability across legacy building infrastructure.
- Energy Management Systems:Centralized platforms aggregate HVAC, lighting, and on-site generation data for automated demand-response participation. Grid-interactive building controls create recurring revenue streams for retrofitters who bundle software subscriptions with hardware upgrades. Cybersecurity certification increasingly gates utility incentive eligibility.
- Smart Thermostats:Occupancy-based climate zoning reduces heating degree-hour intensity in mixed-use commercial assets. Installation scales through contractor networks rather than direct consumer channels. Utility rebate programs drive volume in deregulated markets.
- Solar Panels:Building-integrated photovoltaics merge envelope replacement with generation capacity.
- Advanced Lighting:Human-centric circadian systems penetrate healthcare and education retrofits.
Platform deployments favor Energy Management Systems. Smart Thermostats show the steepest volume ramp from residential program expansion.
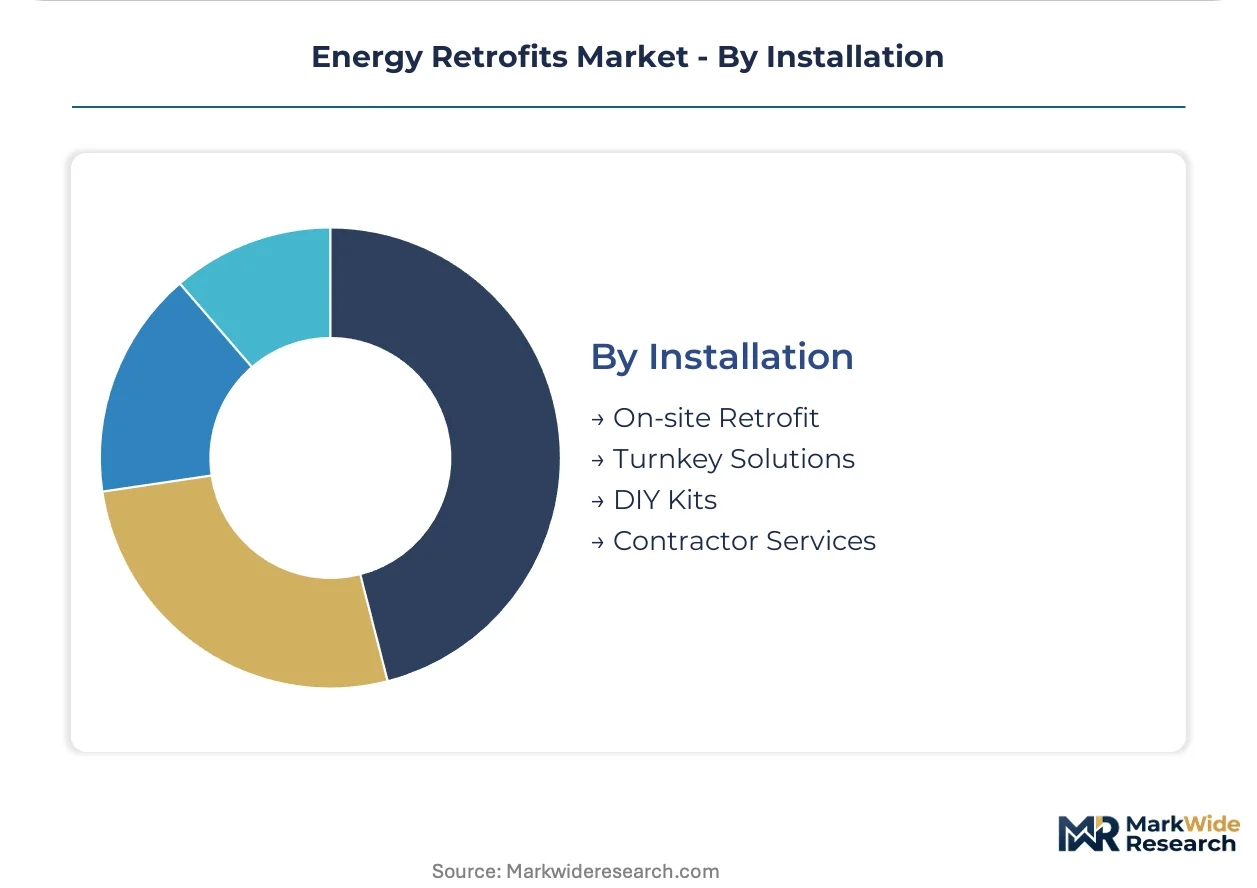
Installation:
Execution risk allocation distinguishes self-managed projects from performance-guaranteed delivery models.
- Turnkey Solutions:Single-contract procurement bundles design, equipment, installation, and commissioning with savings guarantees. Municipal and federal clients mandate this structure for technology risk transfer. Providers carry liquidated damages exposure for underperformance.
- Contractor Services:Specialized trades execute envelope, mechanical, and electrical scopes under owner-managed coordination. Deep renovation expertise clusters in Western European urban centers. Multi-trade sequencing complexity elevates project management overhead.
- On-site Retrofit:Phased execution minimizes tenant disruption in occupied commercial assets.
- DIY Kits:Consumer-direct sales target residential lighting and thermostat replacements.
Institutional capital flows through Turnkey Solutions. Contractor Services capture volume in fragmented secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep energy renovation practices crystallized in Northern Europe during the 1970s oil crises, establishing Denmark and Sweden as early laboratories for building envelope standards that later diffused across the continent through EU directive harmonization.
Germany
Building Energy Act mandates heat pump installation in new and replacement heating systems, accelerating equipment turnover in multi-family housing stock. The Federal Office for Economic Affairs and Export Control administers subsidy programs through BAFA that cover up to 70 percent of renovation costs for efficiency measures. Deep renovation clusters concentrate in the Rhine-Ruhr metropolitan region, where municipal housing associations bundle envelope and mechanical upgrades into single-procurement frameworks.
France
MaPrimeRénov subsidies have unlocked residential retrofit demand among owner-occupiers previously priced out of deep renovation markets. The Ministry of Ecological Transition enforces RE2020 environmental regulations that tighten operational and embodied carbon thresholds for building renovations. Lyon and Grenoble anchor commercial retrofit activity in the Auvergne-Rhône-Alpes region, where district heating operators mandate building-level efficiency pre-qualification for network connection.
United Kingdom
Minimum Energy Efficiency Standards prohibit landlords from leasing commercial properties below EPC rating E, forcing portfolio-wide upgrade programs. The Department for Energy Security and Net Zero oversees the Social Housing Decarbonisation Fund that targets 2.8 million social homes for retrofit by 2030. Manchester and Birmingham concentrate contractor capacity for deep renovation, with metropolitan combined authorities coordinating street-by-street retrofit delivery to minimize disruption.
Netherlands
Natural gas phase-out mandates in district heating zones accelerate heat pump adoption across residential and commercial building stock. The Ministry of Economic Affairs and Climate Policy implements the National Heat Transition Program that coordinates municipal heat planning with building renovation timelines. Rotterdam and Utrecht pilot integrated energy districts where envelope retrofits synchronize with grid-interactive thermal storage deployment.
Poland
EU cohesion fund allocations are channeling renovation finance into multi-family housing estates constructed during the communist period. The National Fund for Environmental Protection and Water Management administers thermomodernization programs that cover insulation, window replacement, and heating system upgrades. Warsaw and Kraków concentrate emerging contractor capacity as Western European firms establish joint ventures to access first-mover positions in underpenetrated markets.
Energy Retrofits Market Vendor Landscape
Capital-heavy engineering conglomerates compete with asset-light energy service companies for retrofit contract flow, creating a bifurcated structure where equipment manufacturers and turnkey integrators occupy distinct competitive spaces. The market organizes around three strategic archetypes: building automation specialists who capture metropolitan district contracts, energy service companies who assume long-term performance risk through savings guarantees, and diversified industrial conglomerates who bundle HVAC equipment with digital controls. Consolidation pressure operates through vertical integration moves by equipment manufacturers acquiring installation capabilities, and through geographic expansion by Western European contractors into Eastern European markets.
Among building automation specialists, Johnson Controls and Siemens exemplify the integrated platform approach, anchoring positions through metropolitan-scale retrofit contracts that combine envelope, mechanical, and controls upgrades. Within the energy service company tier, Ameresco represents the performance-contracting model, assuming technology and savings risk through decade-long municipal and federal partnerships. Trane Technologies occupies the equipment-centric position, leveraging HVAC manufacturing scale to capture replacement cycle demand accelerated by refrigerant phase-down regulations.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Siemens |
| Ameresco |
| Trane Technologies |
| Daikin Industries |
| Eaton |
| AECOM |
| Orion Energy Systems |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's Renovation Wave gates qualified supply and premium-tier pricing access, as contractors must demonstrate certified deep-renovation competency to bid on municipal frameworks in Germany and France. This environmental mandate compresses margins for uncertified installers while elevating performance-guaranteed providers who can command 15-25 percent price premiums.
Pricing Analysis
Project-based contracting with outcome guarantees dominates commercial retrofit procurement, separating integrated service providers from equipment-only vendors. Price differentiation hinges on BREEAM certification tier and after-sales thermal performance monitoring. Cost compression in standard insulation packages is intensifying because aluminum and copper volatility squeezes HVAC margins. Municipal clients show lowest price sensitivity due to decade-long budget certainty, while residential owner-occupiers in subsidy-dependent markets exhibit highest sensitivity to capital outlay.
Supply Chain Analysis
Heat pump supply rests on German and Japanese compressor manufacturers, with vacuum-insulated panel production concentrated in Germany and South Korea. Copper tubing, aluminum heat exchangers, and synthetic refrigerants constitute critical input dependencies. Single-source vulnerability in inverter drive electronics creates procurement risk for contractors scaling heat pump deployment. Distribution runs through authorized dealer networks rather than open wholesale channels, locking regional installers into manufacturer-controlled pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Energy Retrofits Market represents a late-cycle quality story as asset owners shift procurement toward outcome-guaranteed contracts that bundle envelope, mechanical, and controls upgrades. Premium specifications now mandate verified energy savings commitments rather than equipment-only delivery.
For Market Incumbents: Cement metropolitan district relationships through long-term energy savings performance contracts that transfer technology risk. Expand backward integration into thermal storage manufacturing to capture margin from heat pump conversions. Deepen certification investment in BIM-to-operations competency to defend against specialized contractor entrants.
For New Entrants and Emerging Players: Municipal housing associations in Poland and Romania offer white-space entry points as EU cohesion funds flow toward thermomodernization. Target residential retrofit aggregators in France's MaPrimeRénov subsidy channel. Partner with district heating operators seeking building-level efficiency pre-qualification capabilities.
For Investors and Strategic Acquirers: Roll-up economics work for regional energy service companies because deep renovation expertise clusters geographically and municipal framework agreements create sticky revenue. The five-to-ten year viability window favors contractors with GSA schedule or national framework status. Watch F-Gas refrigerant phase-down acceleration as inflection signal for HVAC replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance Contracting Expansion | Long-term municipal partnerships in Germany transfer technology risk and lock recurring revenue streams. |
| Backward Integration into Thermal Storage | In-house production of heat pump-integrated storage captures margin from district heating decarbonization mandates. |
| BIM-to-Operations Certification Investment | Bridging digital design tools with legacy mechanical systems addresses critical technician scarcity in deep renovations. |
| Eastern European Geographic Expansion | Joint ventures in Poland and Romania access EU cohesion fund flows before Western European incumbent saturation. |
| Building-Integrated Photovoltaics Development | Envelope retrofitting merged with on-site generation opens integrated contracting models beyond equipment-only procurement. |
Methodological Framework
Coverage spans Western Europe, Eastern Europe, and North America, with primary inputs from each region combined with secondary validation. Interviews with municipal housing officers, energy service company project developers, HVAC contractor network managers, and district heating operators informed demand-side assumptions. Secondary sources include EU building performance directive transposition documents, BAFA subsidy disbursement records, FERC demand-response filings, and national building code regulatory texts. Bottom-up project pipeline analysis triangulates with top-down construction spending forecasts.
Rate-of-change decomposition separates equipment replacement cycle effects from regulatory mandate acceleration across the modeling period. Segmentation dimensions include service type, end user, technology platform, and installation delivery model, with regional regulatory framework as cross-cutting variable. CAGRs derive from installed base turnover analysis and policy implementation timeline phasing. Forecast inputs incorporate F-Gas phase-down schedules and national building performance standard enforcement calendars.
Revisions become necessary when copper and aluminum price volatility exceeds historical bands or when EU member states delay directive transposition deadlines. Forecasts reflect assumptions about subsidy program continuity and contractor capacity expansion rates. A small set of named triggers warrants ongoing watch: refrigerant supply disruption, embodied carbon accounting standard finalization, and grid-interactivity mandate enforcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Heat Pump Water Heater Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market