
 India Liquified Petroleum Gas (LPG) Market | 2026-2036
India Liquified Petroleum Gas (LPG) Market Size, Share, and Industry Trends Forecast 2026-2036
India Liquified Petroleum Gas (LPG) Market Foresight
Composite cylinder technology is fragmenting traditional steel-dominated supply chains across India's LPG infrastructure. Indian Oil Corporation leverages its nationwide bottling network to sustain last-mile delivery dominance in rural districts. Bharat Petroleum Corporation Limited anchors its position through dedicated industrial supply contracts with manufacturing clusters. Hindustan Petroleum Corporation Limited competes on cylinder exchange density in urban coastal markets.
Liquified Petroleum Gas comprises propane and butane hydrocarbons stored under moderate pressure, typically delivered as a liquid that vaporizes for combustion in cooking burners, industrial furnaces, and vehicle engines. The fuel serves as a portable, cleaner-burning alternative to coal, kerosene, and biomass in residential and commercial settings where pipeline natural gas remains unavailable. Residential cooking applications occupy the largest volume share, though industrial heating segments command superior per-unit margins through bulk tanker deliveries. Composite cylinders represent the fastest-growing container category, driven by weight reduction benefits and extended corrosion resistance in humid coastal states.
The Petroleum and Natural Gas Regulatory Board enforces cylinder safety standards and transportation protocols that raise compliance costs for smaller distributors. BIS certification mandates for valve and hose assemblies filter out substandard equipment imports from neighboring markets. The PLI scheme for domestic manufacturing of specialty steel and composite materials redirects procurement toward local supply chains. Stakeholders must monitor how state-level environment clearances for new bottling plants affect regional supply adequacy as urbanization accelerates.
Market Dynamics
Composite cylinder adoption is fragmenting steel-dominated supply chains across India's LPG infrastructure, forcing bottling networks to retool for lightweight corrosion-resistant containers while state-level environment clearances slow new plant approvals.
Growth Catalysts
- Pradhan Mantri Ujjwala Yojana:The central government's subsidized connection program extends LPG access to rural households previously dependent on biomass, expanding the residential consumer base into underserved districts.
- Petroleum and Natural Gas Regulatory Board safety mandates:Stricter cylinder and valve certification requirements under PNGRB protocols filter substandard imports and consolidate distribution around compliant domestic bottlers.
- Maharashtra-Gujarat industrial clustering:Chemical and textile manufacturing hubs in these states generate concentrated bulk demand for process heating applications, driving tanker-delivered commercial offtake.
Market Restraints
- Specialty steel input volatility:Cylinder manufacturing depends on chromium-molybdenum alloy grades subject to import price fluctuations, compressing margins for domestic fabricators.
- Bottling plant concentration:Over half of national filling capacity sits within 200 kilometers of Mumbai and Ahmedabad, creating supply vulnerability during monsoon logistics disruptions.
- Pipeline natural gas substitution:City gas distribution networks expanding under PNGRB authorization threaten LPG's cost position in premium urban cooking segments.
Strategic Opportunities
- Eastern coastal underpenetration:Odisha and West Bengal rural districts show connection rates below the national average, offering white-space expansion for distributor networks.
- Automotive LPG retrofits:Commercial fleet operators in Karnataka and Tamil Nadu are piloting dual-fuel conversions for diesel trucks, creating a nascent transport fuel segment.
- PLI scheme for composite materials:The production-linked incentive framework subsidizes domestic manufacturing of fiber-wrapped cylinders, redirecting procurement from imported steel shells.
Industry Challenges
- BIS certification timelines:Valve and hose assembly testing protocols create 4-6 month approval backlogs, delaying new product introductions and inventory turns.
- Last-mile distributor fragmentation:The mandated separation of bottling, transportation, and retail functions across thousands of small operators complicates quality control and safety audit enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Liquified Petroleum Gas (LPG) Market |
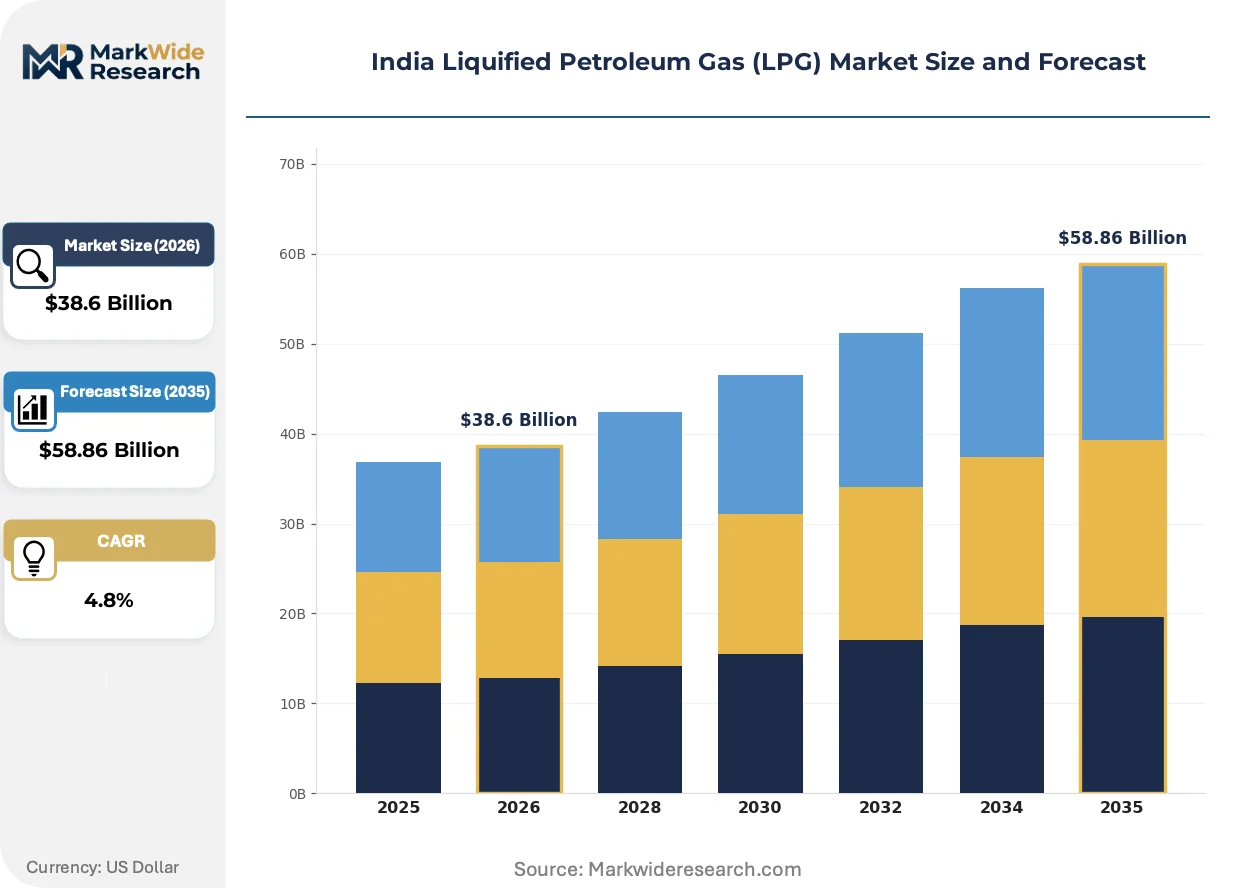
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential Cooking, Industrial Heating, Automotive Fuel, Commercial Cooking Distribution Channel: Retail Outlets, Direct Sales, Wholesalers, Online Sales Container Type: Steel Cylinders, Composite Cylinders, Bulk Tankers, Pipeline Systems End User: Households, Restaurants, Manufacturing Facilities, Hospitals |
| Companies Covered | Indian Oil Corporation, Bharat Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, GAIL India Limited, Reliance Industries, TotalEnergies India, Shell India Markets Private Limited, Adani Total Gas, Essar Oil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Liquified Petroleum Gas (LPG) Market Shifts & Advancements
Material substitution and regulatory tightening are compressing traditional supply chain configurations while procurement patterns shift toward certified lightweight containers. These forces are reconfiguring competitive positioning across bottling, distribution, and end-use segments.
Composite cylinder technology is migrating from coastal humidity-prone districts into interior markets. Food processing units in Kerala and Goa pioneered fiber-reinforced polymer adoption for corrosion resistance. Urban residential distributors in Chennai and Visakhapatnam now stock composite options as standard, compressing steel cylinder replacement cycles from fifteen years to eight.
The Petroleum and Natural Gas Regulatory Board's 2023 cylinder tracking mandate requires QR-coded digital records for every refill. Bottling plants must integrate serialization equipment and cloud-based inventory systems. Smaller distributors in Rajasthan and Madhya Pradesh face compliance cost burdens that favor consolidation toward integrated oil marketing company networks.
Buying patterns among institutional purchasers are compressing contract durations from annual to quarterly terms. Hospitality chains in Maharashtra and hotel cooperatives in Karnataka now negotiate spot-indexed pricing rather than fixed-rate agreements. This liquidity preference favors distributors with real-time inventory visibility and flexible tanker routing capabilities.
India Liquified Petroleum Gas (LPG) Market Segmentation
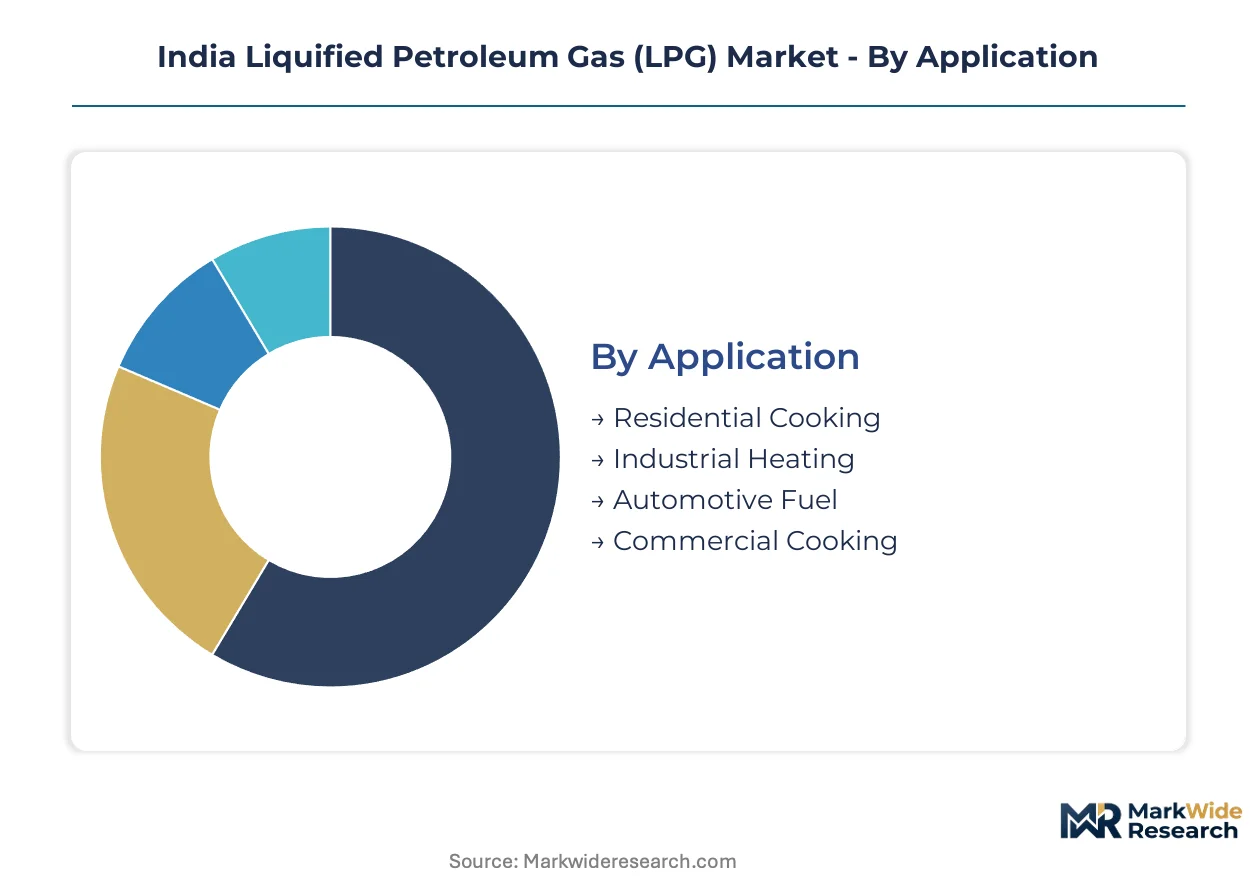
Segmentation in India's LPG market reveals divergent service intensity requirements across container technologies and delivery modes. Steel cylinders demand periodic hydrostatic testing and valve replacement programs, while composite alternatives reduce corrosion-related maintenance. Bulk tanker customers require dedicated technical support for vaporizer systems and pressure regulation equipment.
Application:
After-sales service intensity varies sharply across application segments, with industrial heating requiring continuous burner maintenance contracts and residential cooking depending on distributor exchange networks.
- Residential Cooking:Propane-butane blends delivered in 14.2kg cylinders dominate household consumption under subsidized pricing frameworks. Rural districts under Pradhan Mantri Ujjwala Yojana drive volume concentration, though subsidy phase-out schedules create pricing volatility for distributors managing working capital cycles.
- Industrial Heating:Bulk propane supplies process heat for textile dyeing operations in Surat and chemical reactors in Vadodara manufacturing clusters. These accounts command dedicated technical service teams for combustion system calibration, with annual maintenance contracts representing 8-12% of fuel spend.
- Automotive Fuel:Retrofit LPG kits for commercial fleets require certified installation and periodic emissions testing compliance.
- Commercial Cooking:Restaurant chains in Bengaluru and Hyderabad negotiate consolidated billing across multiple outlet locations.
By volume, residential cooking leads. By growth pace, industrial heating is ahead.
Distribution Channel:
Cost tier stratification separates capital-intensive direct sales infrastructure from asset-light online intermediaries, with working capital requirements determining distributor market entry feasibility.
- Retail Outlets:Indian Oil Corporation's Indane distributors operate 11,000+ physical booking centers with cylinder exchange and cash collection functions. These outlets require refrigerated storage for rubber hose inventory and maintain spare part stocks for regulator replacements, elevating fixed cost structures.
- Direct Sales:Bulk tanker deliveries to manufacturing facilities bypass cylinder handling entirely, with dedicated fleet assets and trained drivers handling pressure unloading protocols. Bharat Petroleum Corporation Limited anchors this channel through long-term supply agreements with Gujarat chemical parks.
- Wholesalers:Aggregators in secondary cities consolidate small lot purchases for hospitality sector buyers.
- Online Sales:Aggregator platforms now handle 12-15% of cylinder booking transactions in tier-1 cities.
Retail outlets capture the largest transaction count. Direct sales generate the highest revenue per customer.
Container Type:
Technology maturity curves separate established steel fabrication from emerging composite materials, with replacement cycles and corrosion resistance driving procurement decisions in coastal versus interior markets.
- Steel Cylinders:Chromium-molybdenum alloy shells manufactured at BIS-certified plants in Nagpur and Kanpur retain 85% of installed base despite weight disadvantages. Hydrostatic testing mandates every five years create recurring revenue streams for authorized testing stations, embedding steel deeply in distributor service infrastructure.
- Composite Cylinders:Fiber-wrapped polymer construction from PLI-supported domestic manufacturers reduces cylinder weight by 50% and eliminates rust in Kerala's humid coastal districts. Adoption accelerates in Chennai and Visakhapatnam urban markets where apartment dwellers prioritize portability.
- Bulk Tankers:Cryogenic road tankers serve manufacturing facilities with dedicated unloading bays.
- Pipeline Systems:Limited to integrated petrochemical complexes with captive LPG production.
Steel cylinders dominate installed base. Composite variants are expanding most quickly.
End User:
Customer type determines delivery frequency, safety protocol stringency, and payment terms, with institutional accounts demanding specialized handling procedures absent from household transactions.
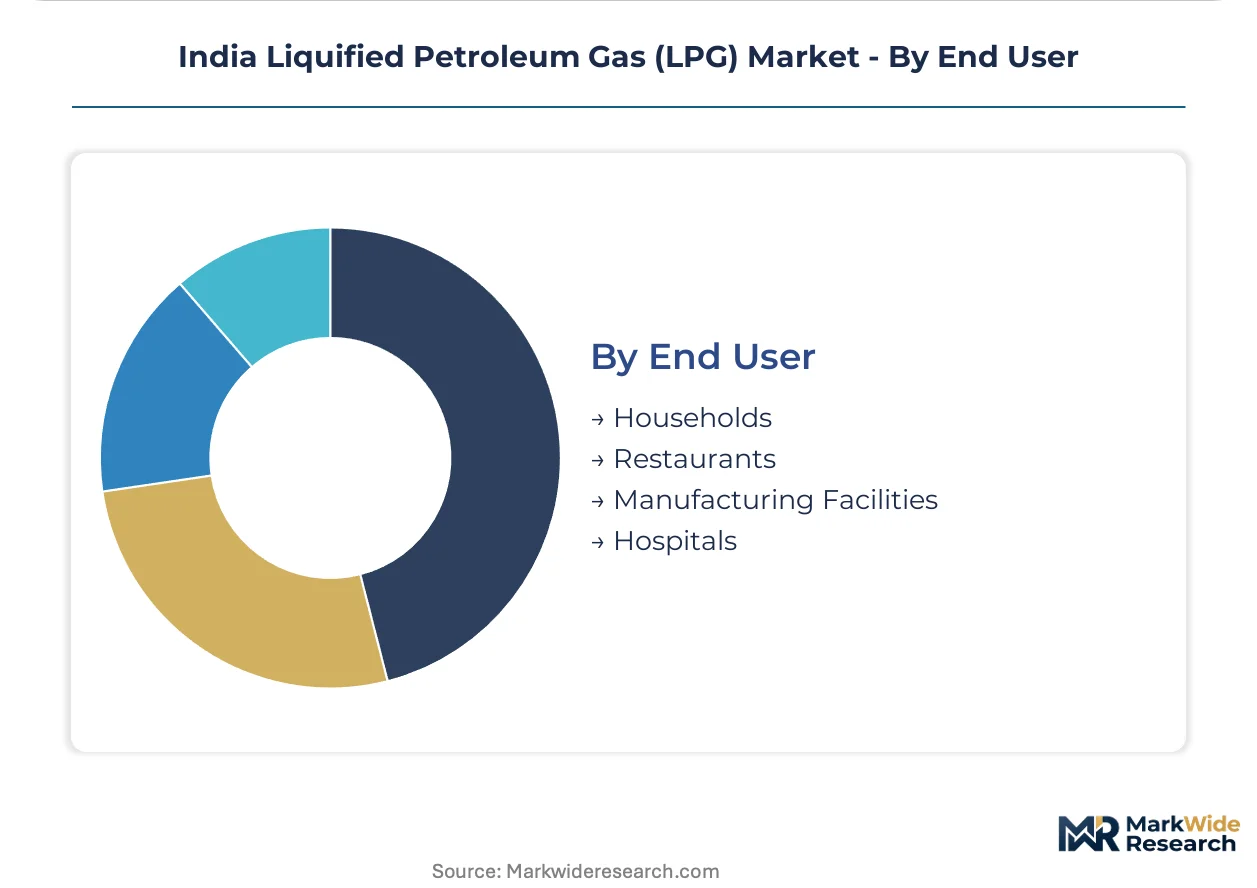
- Households:Individual consumers under Pradhan Mantri Ujjwala Yojana receive subsidized 14.2kg cylinders with KYC-linked direct benefit transfer mechanisms. Connection density varies from 95% in Kerala to 65% in rural Bihar, creating uneven distributor route economics.
- Restaurants:Commercial kitchen operators in Mumbai and Delhi purchase 19kg and 47.5kg cylinders with higher frequency exchange requirements. Food safety audits now include LPG hose certification checks, adding compliance layers to supplier relationships.
- Manufacturing Facilities:Process heating applications in Maharashtra chemical clusters require bulk vaporization systems.
- Hospitals:Medical gas installations for sterilization equipment demand 99.5% purity propane with dedicated supply chain segregation.
Households account for the largest cylinder count. Manufacturing facilities contribute the highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Middle Eastern exporters supply the majority of India's LPG import volumes through long-term supply contracts and spot market purchases. Qatar and Saudi Arabia dominate the trade corridor with dedicated very large gas carrier (VLGC) shipments to Indian ports. Domestic bottling infrastructure concentrates around western and southern coastal states with direct import terminal access.
Maharashtra
Mumbai and Pune metropolitan clusters drive residential cylinder demand from apartment complexes and urban households. The state environment department mandates coastal regulation zone clearances for new bottling plants near JNPT port facilities. Chemical manufacturing zones in Raigad and Thane districts absorb bulk propane for reactor heating and solvent recovery operations.
Gujarat
Dahej and Hazira LNG terminals enable direct LPG extraction and coastal distribution to inland bottling networks. The Gujarat Pollution Control Board enforces emission norms for captive power plants using LPG as backup fuel. Textile processing units in Surat and chemical complexes in Vadodara generate concentrated industrial offtake through dedicated tanker routes.
Karnataka
Bengaluru's commercial kitchen sector and hospitality chains purchase 19kg and 47.5kg cylinders at high exchange frequency. The Karnataka State Pollution Control Board mandates cleaner fuel transitions for brick kilns in peripheral districts. Food processing clusters in Mysuru and Mangaluru pilot composite cylinder adoption for humidity-resistant storage.
Tamil Nadu
Chennai's urban residential distributors stock composite cylinders as standard inventory for apartment dwellers prioritizing portability. The Tamil Nadu Industrial Development Corporation facilitates land allotment for bottling plants in Sriperumbudur industrial corridor. Automotive component manufacturers in Hosur evaluate LPG retrofit kits for captive generator sets and material handling equipment.
West Bengal
Kolkata's dense urban settlement pattern sustains high-frequency cylinder exchange routes through narrow street networks. The West Bengal Pollution Control Board restricts new LPG bottling approvals in the critically polluted Asansol-Raniganj belt. Tea processing estates in Darjeeling and Dooars regions convert wood-fired dryers to LPG burner systems under plantation modernization schemes.
India Liquified Petroleum Gas (LPG) Market Competitive Landscape
On the supply side, the industry is consolidated around three state-owned oil marketing companies controlling bottling infrastructure and last-mile distribution networks. Private sector participants concentrate in bulk industrial supply and import terminal operations. Two strategic archetypes dominate: integrated public sector undertakings with nationwide cylinder exchange networks, and specialized private operators with coastal import and bulk delivery capabilities. Competitive moves center on composite cylinder manufacturing partnerships under PLI scheme incentives and consolidation of fragmented distributor networks through franchisee acquisitions.
Among public sector anchors, Indian Oil Corporation exemplifies the integrated bottling network archetype with extensive rural penetration. Bharat Petroleum Corporation Limited occupies a position emphasizing industrial supply contracts and direct sales infrastructure. Hindustan Petroleum Corporation Limited represents the coastal market specialization vector with concentrated urban exchange density. These three entities collectively anchor competitive dynamics across container technology transitions and distribution channel reconfiguration.
| Leading Market Players |
|---|
| Indian Oil Corporation |
| Bharat Petroleum Corporation Limited |
| Hindustan Petroleum Corporation Limited |
| GAIL India Limited |
| Reliance Industries |
| TotalEnergies India |
| Shell India Markets Private Limited |
| Adani Total Gas |
| Essar Oil |
| Others |
Supply & Pricing Matrix
Middle Eastern VLGC operators supplying Dahej and Hazira terminals anchor upstream pricing power, concentrating margin pools with bottling networks that control cylinder serialization infrastructure and last-mile distributor franchises.
Pricing Analysis
Steel-to-composite technology-generation pricing gaps separate three distinct cost tiers: legacy chromium-molybdenum alloy cylinders, PLI-subsidized fiber-wrapped polymer alternatives, and bulk tanker-delivered propane bypassing container economics entirely. Price differentiation rests on BIS certification grade and geographic delivery cost to interior districts. Cost compression in standard steel tiers is intensifying because of specialty steel import volatility. Households under Ujjwala subsidy frameworks exhibit highest price sensitivity; bulk industrial accounts purchasing tanker volumes show lowest.
Supply Chain Analysis
Extended payment terms from Qatari and Saudi suppliers to Indian oil marketing companies compress working capital cycles for downstream distributors. Geographic supply concentrates in Qatar, Saudi Arabia, and the UAE. Raw material dependencies include propane-butane feedstock, chromium-molybdenum alloy steel, and fiber-reinforced polymer composites. Single-source vulnerability runs through the Hormuz Strait VLGC corridor. Distribution runs through state-owned bottling plants, fragmented retail distributors, and direct-sales tanker fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality chains and manufacturing clusters that negotiate quarterly spot-indexed contracts, fragmenting traditional annual offtake agreements that favored incumbent distributors.
For Market Incumbents: Entrench control over cylinder tracking infrastructure mandated by Petroleum and Natural Gas Regulatory Board serialization rules, locking out non-compliant regional distributors. Deepen backward integration into PLI-supported composite cylinder manufacturing to capture margin migrating from steel fabricators. Channel control through franchisee acquisition in eastern coastal districts counters pipeline natural gas substitution threats in premium urban segments. For New Entrants and Emerging Players: Odisha and West Bengal rural underpenetration offers white-space expansion where connection rates trail national benchmarks. Automotive LPG retrofit services for Karnataka and Tamil Nadu commercial fleets represent the most penetrable application segment. A go-to-market angle anchored through certified installation partnerships with vehicle service centers bypasses incumbent bottling network dependencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed composite materials manufacturers holding PLI scheme allocations and coastal bottling plant operators with environment clearance backlogs. Long-term viability over a decade-long horizon favors targets with integrated import terminal access and digital serialization compliance. The signal to watch is state-level environment clearance velocity for new bottling capacity as urbanization accelerates cylinder demand density.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Cylinder Manufacturing Scale-Up | PLI scheme subsidies redirect procurement from imported steel shells toward domestic fiber-wrapped production. |
| Backward Integration into Import Terminals | Dahej and Hazira terminal access secures direct LPG extraction bypassing Middle Eastern trader intermediaries. |
| Digital Serialization Infrastructure Deployment | Petroleum and Natural Gas Regulatory Board QR-code mandates favor bottlers with cloud-based inventory systems. |
| Eastern Coastal Distribution Network Expansion | Odisha and West Bengal underpenetration offers connection rate catch-up potential outside saturated western markets. |
| Automotive Retrofit Certification Investment | Karnataka and Tamil Nadu fleet conversions require certified installation capabilities creating technical barrier to entry. |
Research Methodology
A standing panel of bottling plant operations managers, Petroleum and Natural Gas Regulatory Board compliance officers, hospitality sector procurement heads, and rural distributor franchisees provided ongoing calibration against secondary validation from customs import records, PNGRB authorization databases, SEC filings by listed oil marketing companies, and state pollution control board clearance registers. Bottom-up cylinder volume estimates triangulated against top-down national consumption aggregates.
Scenario-bracketing framed demand projections across subsidized residential, unsubsidized commercial, and bulk industrial segments, with container type substitution curves modeled separately. CAGRs derived from weighted average of historical volume trajectories and policy-driven connection targets. Forecast inputs included PLI scheme allocation timelines and city gas distribution network rollout schedules.
The forecast holds incumbent behavior within observed patterns; aggressive composite cylinder capacity expansion by private entrants or accelerated pipeline natural gas substitution would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Liquefied Helium Tanks Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Gas to Liquid (GTL) Market
Fuels
North America Wood Pellet Market
Fuels
Gasoline As a Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Gas Pooling Mechanism Market
Fuels
Diesel Fuel Water Separator Market
Fuels
India Bunker Fuel Market
Fuels
Europe Coal Market
Fuels
Chafing Fuel Market
Fuels
China Bunker Fuel Market