
 Global Radial Artery Compression Devices Market | 2026-2036
Global Radial Artery Compression Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radial Artery Compression Devices Market Foresight
Ambulatory surgical centers is decoupling from traditional hospital-based procurement patterns as same-day discharge protocols expand across interventional cardiology. Terumo Corporation leverages its integrated transradial platform to anchor premium positioning in Japanese and North American cath labs. Abbott Laboratories sustains competitive density through broad vascular access portfolios that span hemostasis to closure. Merit Medical Systems specializes in disposable-centric designs that align with single-use deployment preferences in outpatient settings.
Radial artery compression devices are mechanical or pneumatic systems engineered to apply calibrated, localized pressure at the wrist puncture site following catheterization, typically incorporating pressure plates, adjustable straps, and inflation mechanisms rated for 20-40 mmHg operational ranges to achieve hemostasis without vascular occlusion. Their primary commercial purpose centers on reducing access-site complications, shortening bed-rest requirements, and enabling faster patient turnover in high-volume interventional suites. Pneumatic compression devices lead value contribution due to programmable pressure profiles that minimize nursing labor and standardize outcomes across operators. Digital compression devices represent the fastest-expanding category as integrated pressure sensors and wireless monitoring capabilities align with telemetry-enabled recovery protocols. Manual compression devices retain volume presence in cost-constrained emergency settings but face margin compression from labor intensity and outcome variability.
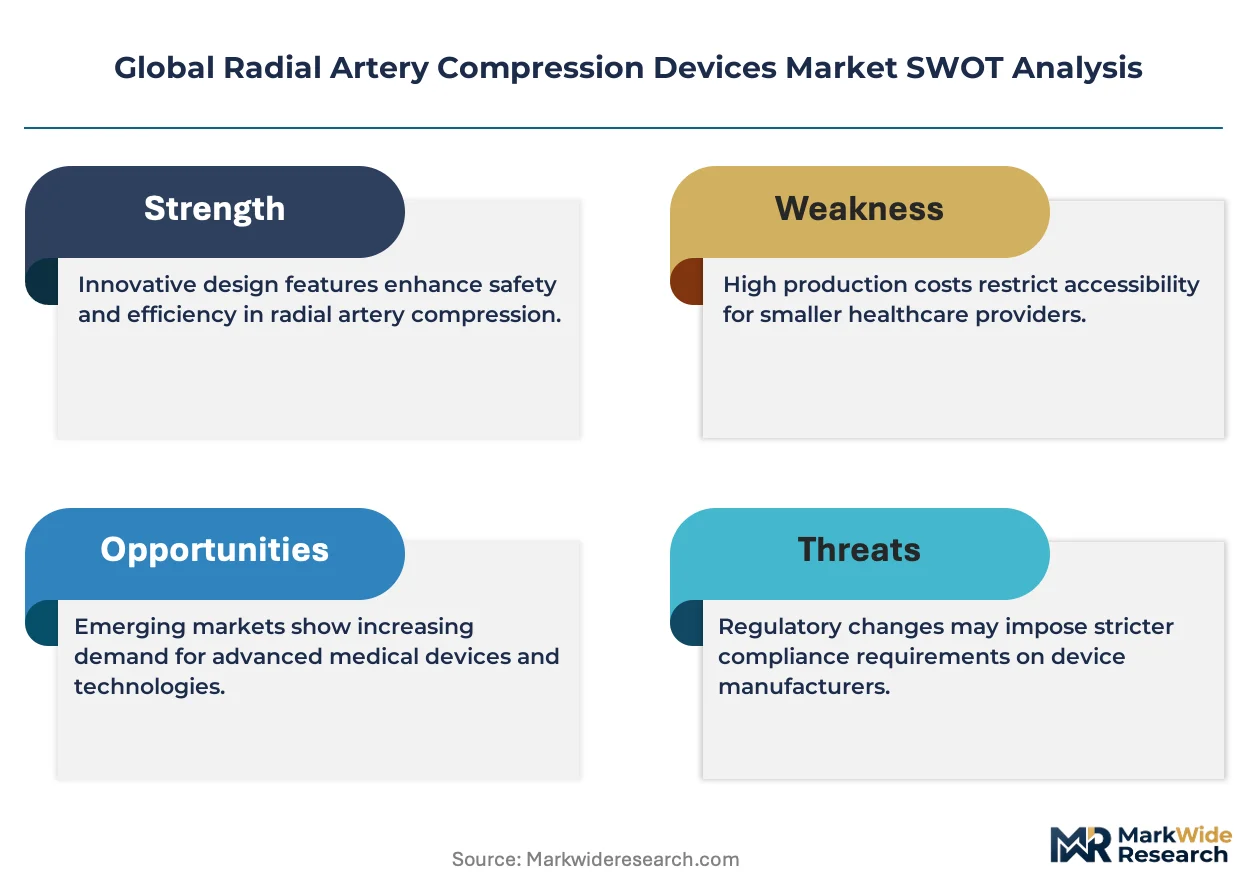
FDA 510(k) pathways and the EU MDR framework shape product development cycles by demanding expanded clinical validation for compression duration and complication-rate claims, while Japan's PMDA reinforces barrier-to-entry through localized efficacy studies. These regulatory architectures favor incumbents with established quality-management systems and constrain rapid market entry for novel mechanisms. Stakeholders must monitor reimbursement parity between transradial and transfemoral procedures as payer alignment determines institutional commitment to radial-first protocols and associated device procurement.
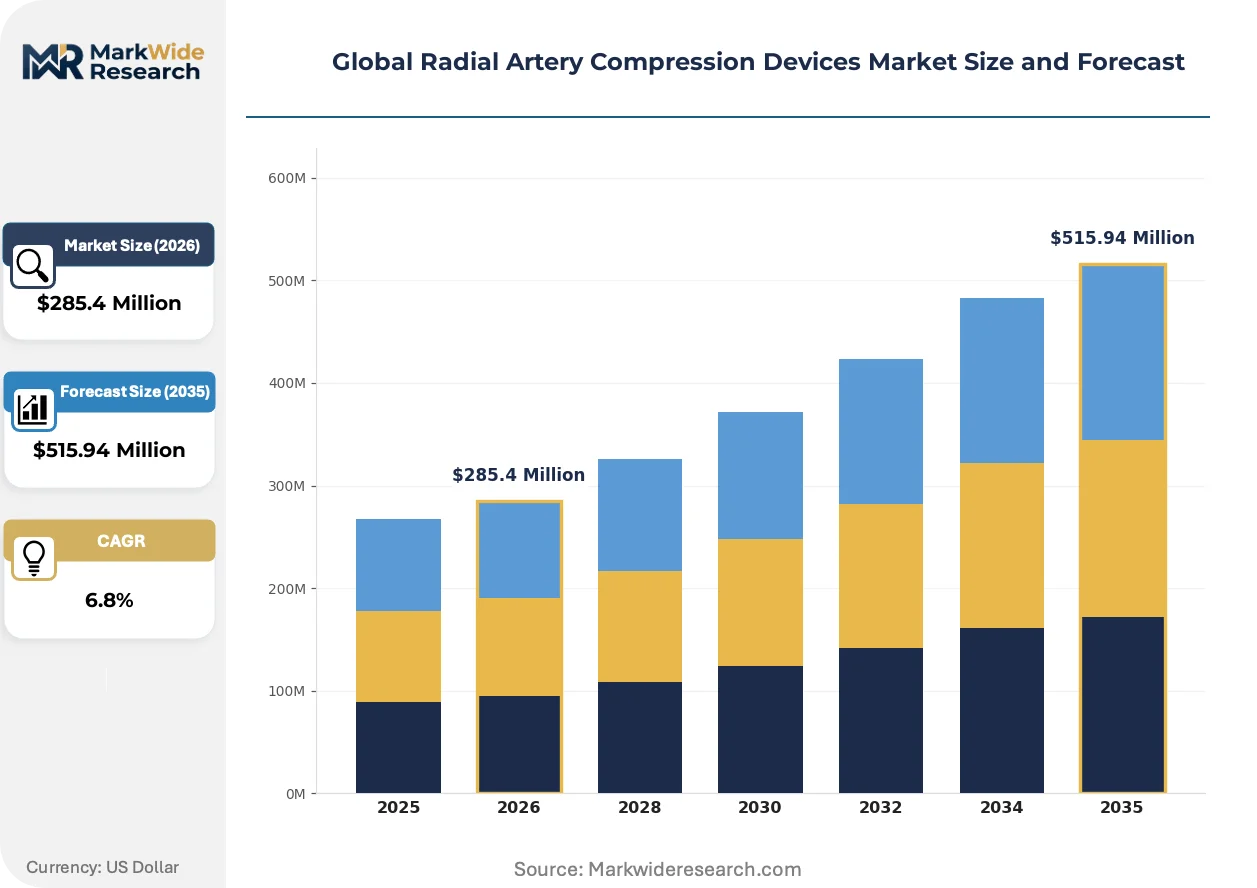
Market Dynamics
Transradial catheterization protocols are displacing femoral access across interventional cardiology, compressing bed-rest requirements and forcing cath labs to reconfigure post-procedural workflows around wrist-based hemostasis systems.
Growth Catalysts
- EU MDR framework:Tightened clinical validation requirements for hemostasis claims are filtering out marginal competitors and concentrating procurement among validated suppliers in German and French cath labs.
- Same-day discharge protocols:Ambulatory surgical centers across the United States are mandating rapid patient turnover that pneumatic compression devices enable through standardized pressure application.
- Japan's PMDA localization mandate:Efficacy studies conducted on Japanese patient populations create captive demand for devices with established domestic clinical footprints.
Market Restraints
- Silicone membrane supply concentration:Pneumatic bladder production depends on specialized medical-grade silicone suppliers concentrated in East Asian chemical processing corridors.
- FDA 510(k) documentation burden:Expanded predicate device comparisons and human factors testing extend clearance timelines for novel compression mechanisms.
- Manual compression substitute:Cost-constrained emergency departments retain trained nursing labor for digital pressure application, limiting device penetration in acute care entry points.
Strategic Opportunities
- Wireless telemetry integration:Bluetooth-enabled pressure sensors that stream to central monitoring stations are electrifying recovery protocols in high-volume Japanese and North American facilities.
- India's CDSCO fast-track pathway:Streamlined device registration for established predicate technologies opens procurement channels in Mumbai and Delhi cath lab networks.
- Single-use disposable pivot:Outpatient settings are abandoning reusable compression systems in favor of sterile, procedure-bundled disposables that reduce infection control overhead.
Industry Challenges
- Interventional cardiology nursing specialization:Transradial protocols require distinct competency in radial artery access site management that general cardiac units often lack.
- ISO 13485 quality system maintenance:Sustained certification demands consume operational bandwidth for mid-tier device manufacturers seeking multi-regional market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radial Artery Compression Devices Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Compression Devices, Pneumatic Compression Devices, Digital Compression Devices, Mechanical Compression Devices Application: Hemostasis Post-Cardiac Catheterization, Vascular Access Site Management, Bleeding Control in Trauma, Post-Interventional Radiology Procedures End User: Cardiology Clinics, Interventional Radiology Centers, Emergency Care Units, Ambulatory Surgical Centers Deployment Mode: Single-Use Devices, Reusable Devices, Semi-Disposable Devices, Portable Devices |
| Companies Covered | Terumo Corporation, Abbott Laboratories, Teleflex Incorporated, Merit Medical Systems, Medtronic, Boston Scientific Corporation, Lepu Medical Technology, TZ Medical, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radial Artery Compression Devices Market Shifts & Advancements
Device architecture is bifurcating between premium pneumatic systems with programmable profiles and stripped manual alternatives, while connectivity modules transform compression from isolated procedure into integrated recovery telemetry.
Sensor-embedded compression plates with real-time pressure feedback loops are electrifying hemostasis management in high-throughput cath labs. Interventional suites at major academic medical centers are adopting these systems to reduce nursing labor variability. The technology is compressing outcome variation between operators and enabling standardized discharge criteria across nursing shifts.
Japan's PMDA has tightened post-market surveillance requirements for vascular closure devices, mandating complication-rate reporting that extends beyond initial clearance documentation. Device manufacturers must now maintain active clinical follow-up infrastructure to retain marketing authorization. This regulatory architecture favors incumbents with established pharmacovigilance systems and raises capital barriers for new market entrants.
Hospital procurement committees are unbundling compression devices from catheterization procedure kits, creating direct purchasing relationships with specialized hemostasis suppliers. Group purchasing organizations in the United States are consolidating vendor lists to three approved suppliers per region. This concentration is most visible in Texas and California health systems where integrated delivery networks command substantial volume leverage.
Global Radial Artery Compression Devices Market Segmentation
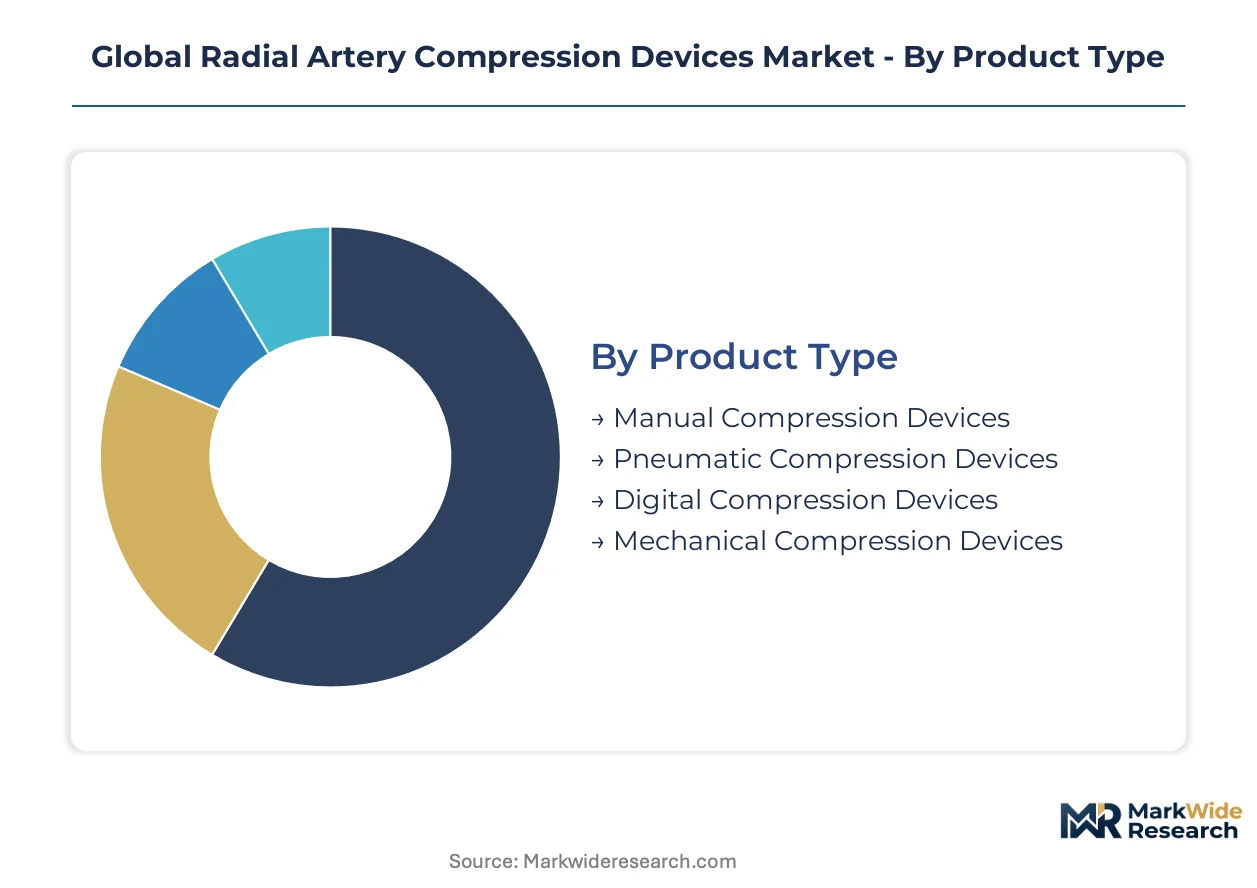
Compression device architectures diverge sharply across clinical settings, with pneumatic and digital systems commanding premium positioning in high-volume cath labs while manual alternatives retain footholds in cost-constrained emergency departments. Understanding these segment boundaries reveals where procurement budgets concentrate and which upgrade cycles drive replacement demand.
Product Type:
Upgrade cycles in this category accelerate where programmable pressure profiles reduce nursing labor variability and standardize hemostasis outcomes across operator skill levels.
- Pneumatic Compression Devices:These systems employ inflatable bladders and calibrated air pressure mechanisms rated for 20-40 mmHg operational ranges, enabling consistent compression without vascular occlusion. Demand concentrates in German and Japanese cath labs where transradial-first protocols dominate interventional cardiology volumes and nursing staff optimization drives capital procurement.
- Digital Compression Devices:Sensor-embedded plates with real-time pressure feedback loops and wireless telemetry capabilities transform hemostasis into integrated recovery monitoring. United States ambulatory surgical centers are standardizing on these systems to enable same-day discharge protocols and reduce inter-operator outcome variation.
- Manual Compression Devices:Simple strap-and-plate designs requiring trained nursing labor for pressure application and duration timing.
- Mechanical Compression Devices:Spring-loaded or screw-adjusted systems providing calibrated force without pneumatic infrastructure.
Pneumatic Compression Devices sits at the top of the volume ranking, with Digital Compression Devices climbing the fastest.
Application:
Application demand maps directly to procedure volume density, with cardiac catheterization hemostasis consuming the majority of device deployments and trauma bleeding control representing a marginal addressable market.
- Hemostasis Post-Cardiac Catheterization:Wrist-based compression following transradial access for coronary angiography or percutaneous coronary intervention, requiring 2-4 hours of maintained pressure. This application dominates procurement in United States, German, and Japanese facilities where cath lab throughput exceeds 3,000 procedures annually.
- Vascular Access Site Management:Standardized compression protocols for radial artery closure in interventional suites, incorporating pressure monitoring and complication documentation. Japanese PMDA post-market surveillance requirements mandate detailed outcome tracking for this application, favoring suppliers with established pharmacovigilance infrastructure.
- Bleeding Control in Trauma:Emergency department deployment for extremity hemorrhage management where device availability supplements manual pressure techniques.
- Post-Interventional Radiology Procedures:Radial access site management following diagnostic or therapeutic radiology interventions, a smaller volume segment with specialized pressure duration requirements.
Hemostasis Post-Cardiac Catheterization captures the dominant revenue share, while Vascular Access Site Management expands most quickly as standardization protocols spread.
End User:
End-user procurement patterns split between integrated hospital systems with capital equipment budgets and outpatient facilities prioritizing disposable-centric, single-procedure economics.
- Cardiology Clinics:High-volume interventional suites performing 2,000+ transradial procedures annually, investing in pneumatic and digital systems with wireless monitoring. German cardiology clinics lead European procurement as transradial access rates exceed 80% of diagnostic catheterizations.
- Ambulatory Surgical Centers:Same-day discharge facilities in Texas and California health systems mandating rapid patient turnover and sterile, procedure-bundled disposables. These centers are unbundling compression devices from catheterization kits to establish direct supplier relationships.
- Interventional Radiology Centers:Specialized facilities with lower radial access volumes and distinct pressure duration protocols compared to cardiac applications.
- Emergency Care Units:Acute care entry points retaining manual compression techniques due to cost constraints and unpredictable procedure volumes.
Cardiology Clinics anchor absolute demand volume, with Ambulatory Surgical Centers gaining share fastest as outpatient migration accelerates.
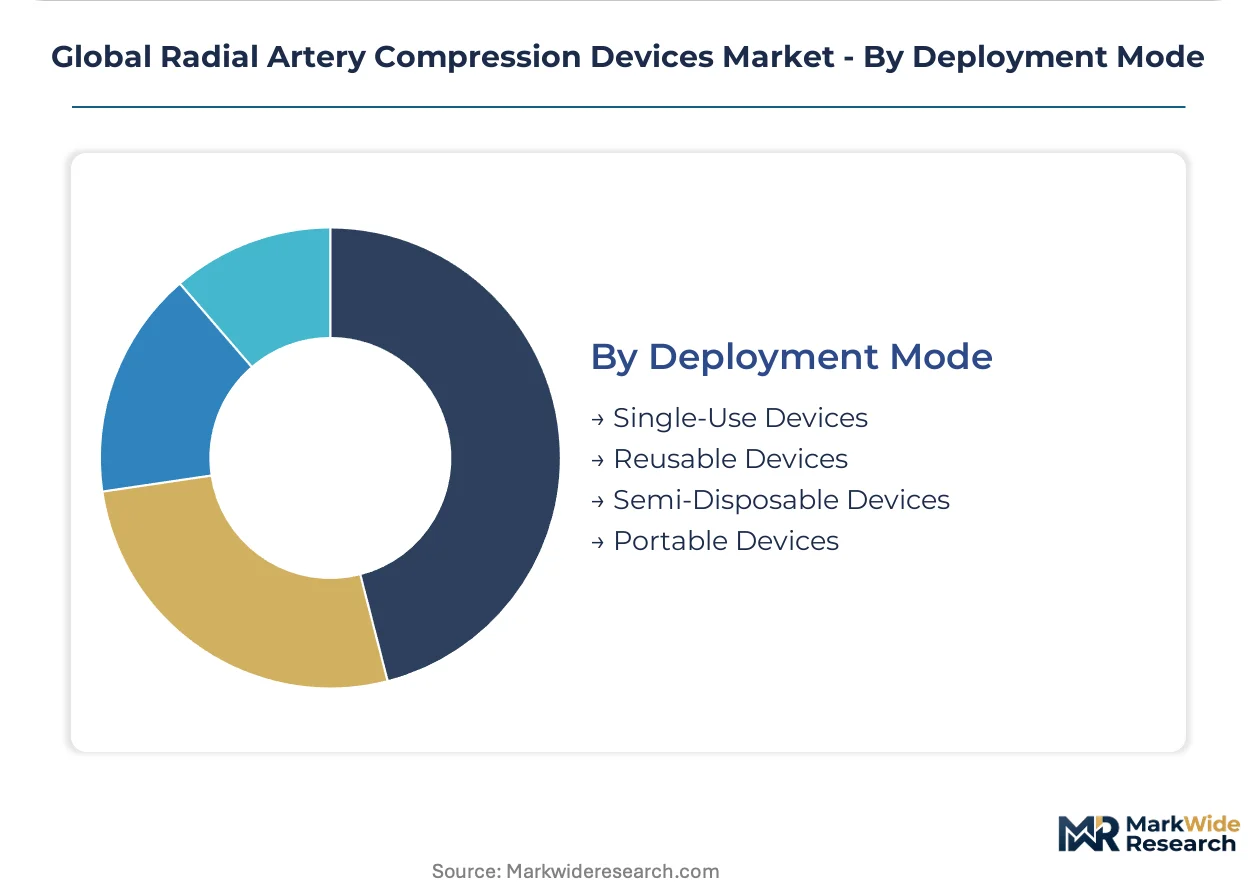
Deployment Mode:
Deployment economics hinge on infection control overhead versus capital amortization, with outpatient settings abandoning reusable systems despite higher per-unit disposable costs.
- Single-Use Devices:Sterile, procedure-bundled compression systems eliminating reprocessing labor and cross-contamination risk. United States ambulatory surgical centers and Japanese day-procedure facilities are mandating this deployment mode as group purchasing organizations consolidate approved vendor lists.
- Reusable Devices:Durable pneumatic or mechanical systems with replaceable contact surfaces, retained in German hospital cath labs with centralized sterilization infrastructure and high daily procedure throughput.
- Semi-Disposable Devices:Hybrid designs with reusable pressure mechanisms and single-use patient contact components.
- Portable Devices:Battery-powered or manual systems for inter-hospital transfer or field deployment scenarios.
Single-Use Devices command the steepest expansion trajectory, while Reusable Devices retain volume leadership in capital-intensive hospital systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Tokyo Area anchors transradial catheterization infrastructure, with Kanto region cath labs driving pneumatic compression device procurement as radial-first protocols displace femoral access across interventional cardiology suites.
United States
Texas and California health systems concentrate ambulatory surgical center expansion, with integrated delivery networks consolidating vendor lists to three approved suppliers per region. FDA 510(k) pathways demand expanded predicate device comparisons and human factors testing. The Southeast corridor from Florida to Georgia is standardizing on wireless telemetry-enabled systems for same-day discharge protocols.
Germany
Cardiology clinics in Bavaria and North Rhine-Westphalia exceed 80% transradial access rates for diagnostic catheterizations, creating sustained demand for reusable pneumatic systems with centralized sterilization infrastructure. The EU MDR framework filters out marginal competitors through tightened clinical validation requirements. The Frankfurt-Mainz corridor maintains premium positioning for programmable pressure profile devices.
Japan
Kanto region facilities around Tokyo deploy integrated transradial platforms with wireless monitoring capabilities, while Kansai cath labs in Osaka prioritize disposable-centric designs. PMDA localization mandates require efficacy studies on Japanese patient populations, creating captive demand for established domestic clinical footprints. Chubu region around Nagoya is adopting Bluetooth-enabled pressure sensors for telemetry-enabled recovery protocols.
India
Maharashtra and Delhi-NCR cath lab networks are opening procurement channels through CDSCO fast-track pathways for established predicate technologies. Mumbai facilities are migrating toward single-use sterile systems to reduce infection control overhead. The country's national pharmaceutical regulator is streamlining device registration for compression mechanisms with existing international clearances.
United Kingdom
London and Southeast England interventional suites are unbundling compression devices from catheterization procedure kits to establish direct purchasing relationships with specialized hemostasis suppliers. MHRA post-Brexit regulatory alignment maintains CE marking recognition for EU MDR-compliant devices. The Midlands corridor is consolidating around semi-disposable hybrid designs with reusable pressure mechanisms.
Global Radial Artery Compression Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent medical device conglomerates extend vascular access portfolios across hemostasis to closure systems. The vendor base concentrates around three strategic tiers: integrated multinational platforms with cath lab ecosystem control, mid-scale specialists in disposable-centric designs, and regional fabricators serving cost-constrained procurement channels. Tiered competitive positioning separates premium pneumatic systems with programmable profiles from stripped manual alternatives. M&A activity and technology licensing agreements represent the dominant competitive moves as firms seek wireless telemetry capabilities and regulatory clearance infrastructure.
Among integrated multinational platforms, Terumo Corporation and Abbott Laboratories exemplify divergent strategic archetypes. Terumo anchors premium positioning through integrated transradial platform control in Japanese and North American cath labs. Abbott occupies a position defined by broad vascular access portfolio density spanning hemostasis to closure. Merit Medical Systems sits within the disposable-centric specialist tier, aligning with single-use deployment preferences in United States outpatient settings. These three anchors represent how geographic footprint breadth, regulatory clearance depth, and product architecture philosophy stratify competitive positioning across procurement committees and group purchasing organizations.
| Leading Market Players |
|---|
| Terumo Corporation |
| Abbott Laboratories |
| Teleflex Incorporated |
| Merit Medical Systems |
| Medtronic |
| Boston Scientific Corporation |
| Lepu Medical Technology |
| TZ Medical |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Pneumatic bladder manufacturing migration toward automated silicone molding simultaneously compresses unit production costs and concentrates supplier leverage among East Asian chemical processors with captive medical-grade polymer capabilities. This dual shift reshapes procurement economics for device manufacturers navigating FDA 510(k) documentation burdens and EU MDR clinical validation requirements.
Pricing Analysis
Medical-grade silicone membrane costs pass through directly to pneumatic compression device pricing, with three-tier pricing structure across premium, standard, and economy levels stratifying by wireless telemetry integration and pressure sensor sophistication. Price differentiation hinges on FDA 510(k) clearance tier and ambulatory surgical center volume commitments. Pricing pressure stems from group purchasing organization vendor consolidation in Texas and California health systems. Emergency departments exhibit highest price sensitivity due to unpredictable procedure volumes and manual compression substitute availability.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German pneumatic component suppliers controlling precision valve and sensor calibration technologies. Manufacturing concentration clusters in Japan, Germany, and the United States for finished device assembly, while medical-grade silicone feedstock draws from South Korean and Chinese chemical processors. Tariff exposure on East Asian polymer imports presents structural risk to margin stability. Distribution runs through hospital procurement committees and group purchasing organizations consolidating to three approved suppliers per integrated delivery network region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Radial Artery Compression Devices Market functions as a stable compounder anchored by irreversible transradial protocol adoption in interventional cardiology suites across United States, German, and Japanese cath labs.
For Market Incumbents: To counter wireless telemetry integration demands from ambulatory surgical centers, deepen software companion development for Bluetooth-enabled pressure monitoring and secure CE marking pathway expansion under EU MDR tightened clinical validation requirements. Prioritize backward integration into medical-grade silicone membrane sourcing to defend margin position against East Asian polymer supply concentration. For New Entrants and Emerging Players: Begin with India's CDSCO fast-track pathway for established predicate technologies, targeting Maharashtra and Delhi-NCR cath lab networks migrating toward single-use sterile systems. Pursue disposable-centric designs aligned with outpatient infection control protocols as the most penetrable entry vector, leveraging streamlined device registration for compression mechanisms with existing FDA clearances. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier disposable specialists lacking wireless telemetry capabilities but possessing established GPO contracts and ISO 13485 quality systems. Long-term viability favors targets with pharmacovigilance infrastructure meeting Japan PMDA post-market surveillance mandates. Monitor reimbursement parity shifts between transradial and transfemoral procedures as the critical inflection signal for institutional procurement commitment to radial-first protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Telemetry Integration | Bluetooth-enabled pressure sensors transform hemostasis into integrated recovery monitoring for Japanese and North American facilities. |
| EU MDR Compliance Pathway | CE marking under tightened clinical validation requirements filters marginal competitors from German and French cath lab procurement. |
| Backward Integration into Silicone Sourcing | In-house production of medical-grade pneumatic bladders mitigates East Asian polymer supply concentration risk. |
| Hospital System Partnership | Direct purchasing relationships with Texas and California integrated delivery networks bypass catheterization kit bundling. |
| Reimbursement Strategy | Payer alignment on transradial procedure parity determines institutional commitment to radial-first protocol adoption. |
Research Methodology
Bottom-up cath lab procedure volume modeling reconciled against top-down device shipment tracking forms the analytical core of this study. Primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and Japanese PMDA post-market surveillance reports. Triangulation across these sources ensures segmentation integrity across pneumatic, digital, and manual compression device architectures.
Historical trendline analysis of transradial catheterization adoption rates and compression device replacement cycles informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and deployment mode, with CAGRs derived from procedure volume density correlations and upgrade cycle acceleration patterns. Forecast inputs incorporate EU MDR compliance timeline impacts and ambulatory surgical center expansion trajectories in United States health systems.
Caveats apply where reimbursement policy shifts or silicone supply disruptions could materially shift the outlook. Forecasts reflect assumptions about transradial protocol standardization and regulatory clearance pathway stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
GCC Organ Preservation Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Global Glucometer Market
Medical Devices
Global Retinoscopes Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Urodynamic Devices Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Nano Healthcare Technology Market