

ePTFE Vascular Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
ePTFE Vascular Prosthesis Market Insights
Hospital procurement committees is reorganizing purchasing criteria toward durable synthetic graft materials with proven patency rates. W. L. Gore & Associates leverages its proprietary expanded polytetrafluoroethylene manufacturing heritage to dominate premium bypass graft supply. Medtronic sustains broad therapy coverage across coronary and peripheral vascular segments through integrated device portfolios. B. Braun Melsungen anchors European hospital supply chains with specialized hemodialysis access solutions.
ePTFE vascular prosthesis denotes a microporous synthetic conduit fabricated from expanded polytetrafluoroethylene through mechanical stretching of PTFE paste extrudates, yielding a node-and-fibril microstructure with internodal distances of 10–30 microns that permits tissue ingrowth while resisting thrombosis. These implants serve primarily as blood vessel substitutes in bypass procedures, patch angioplasty, and hemodialysis access creation where autologous vein availability is limited. Bypass graft segments command the largest revenue pool given their use in femoropopliteal and aortoiliac reconstructions, while arteriovenous fistula applications for dialysis access represent the fastest-expanding category driven by rising end-stage renal disease prevalence. Endovascular stent grafts incorporating ePTFE membranes capture concentrated margins in aortic aneurysm repair despite smaller procedural volumes.
FDA 510(k) clearance pathways and CE marking under the EU MDR impose escalating clinical evidence requirements for long-term patency claims on ePTFE vascular implants. ISO 7198 standards for cardiovascular implants define minimum performance thresholds for synthetic vascular prostheses that manufacturers must validate through accelerated fatigue testing. Japan's PMDA maintains distinct biocompatibility assessment protocols that create incremental regulatory burden for market entry. Stakeholders must monitor evolving MDR transition timelines and predicate device selection strategies as notified body capacity constraints reshape European approval cadences.
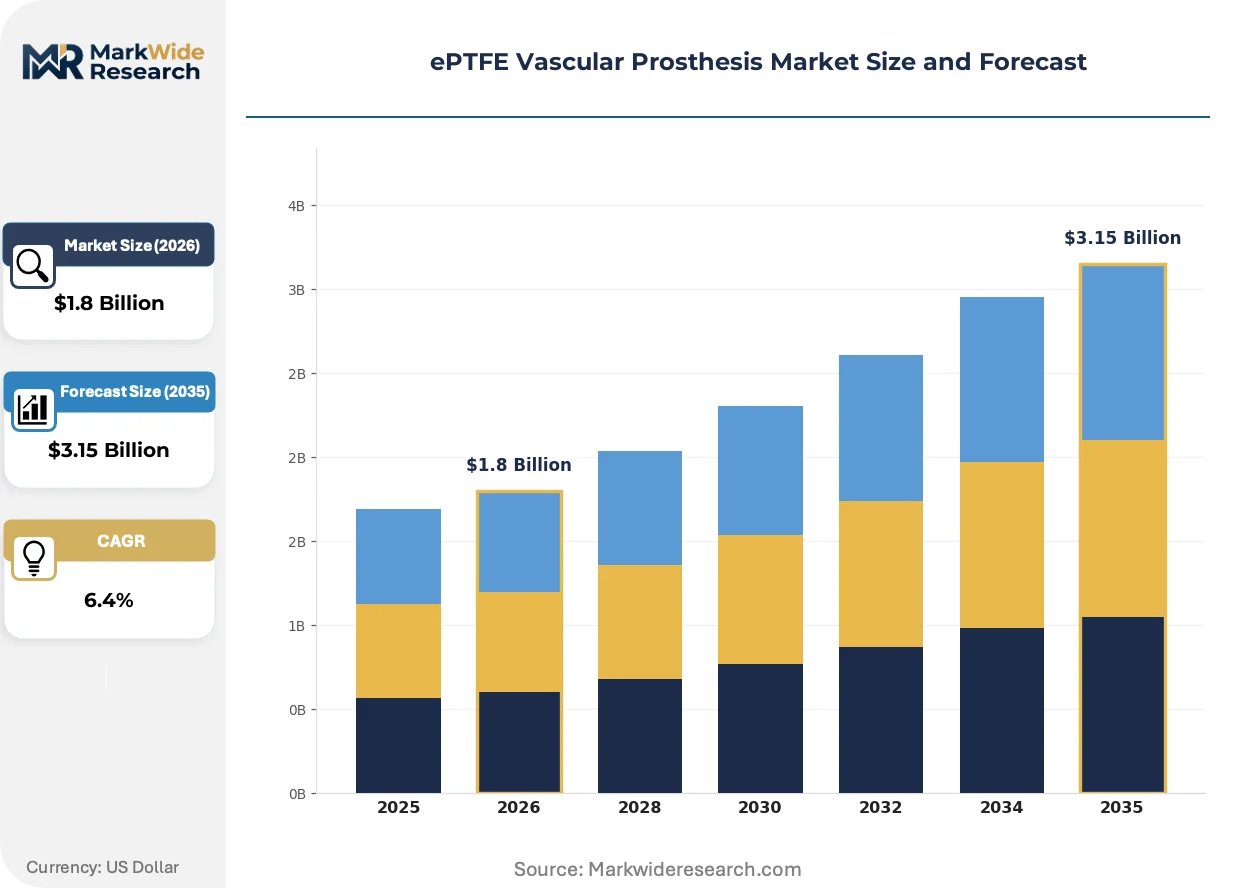
Market Dynamics
Hospital procurement committees are reorganizing purchasing criteria toward durable synthetic graft materials with proven patency rates, compressing margins for suppliers lacking longitudinal clinical data. This structural shift toward evidence-based sourcing is reshaping competitive positioning across the ePTFE vascular prosthesis landscape.
Growth Catalysts
- EU MDR Implementation:The Medical Device Regulation's heightened clinical evidence requirements for long-term patency claims is accelerating consolidation toward manufacturers with robust validation infrastructure. Premium graft suppliers with established predicate device histories capture disproportionate procurement share.
- Japan's Aging Demographics:PMDA biocompatibility assessment protocols, while stringent, create durable competitive moats for compliant suppliers. End-stage renal disease prevalence in Japanese metropolitan centers drives arteriovenous fistula procedure volumes.
- Surface Modification Chemistry:Heparin-bonded ePTFE technologies reduce thrombogenicity in small-diameter bypass applications. Cardiovascular clinics in Germany and the United States are expanding adoption for femoropopliteal reconstructions.
Market Restraints
- Raw Material Concentration:High-purity PTFE resin supply concentrates among specialized fluoropolymer chemical producers in Germany and Japan. Input cost volatility constrains margin flexibility for graft fabricators lacking backward integration.
- Biological Substitute Competition:Autologous vein harvesting and tissue-engineered vascular grafts threaten synthetic conduit demand in coronary bypass procedures. Saphenous vein patency advantages persist in distal revascularization cases.
- Notified Body Bottlenecks:EU MDR transition timelines and constrained notified body capacity extend CE marking timelines for novel ePTFE implant designs. European market entry delays compress revenue recognition windows.
Strategic Opportunities
- Indian Dialysis Access Expansion:CDSCO regulatory harmonization with ISO 7198 standards reduces technical barriers for established manufacturers. Hemodialysis infrastructure buildout in Maharashtra and Tamil Nadu creates graft demand acceleration.
- Endovascular Stent Graft Convergence:ePTFE membrane integration with nitinol stent platforms for aortic aneurysm repair commands concentrated margins. Device manufacturers with catheter delivery system expertise capture value chain expansion.
- Outcome-Based Procurement Models:United States hospital systems are piloting patency-guaranteed supply contracts. Suppliers with real-world evidence registries differentiate against commodity graft competitors.
Industry Challenges
- Polymer Processing Talent Scarcity:Expanded PTFE paste extrusion and mechanical stretching expertise concentrates among aging specialist workforces in Delaware and Bavaria. Knowledge transfer gaps threaten manufacturing consistency.
- Accelerated Fatigue Testing Infrastructure:ISO 7198 validation requirements demand capital-intensive pulsatile flow simulation equipment. Mid-scale manufacturers face capex barriers to predicate device portfolio expansion.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ePTFE Vascular Prosthesis Market Trends and Innovations
Surface engineering and manufacturing precision are converging to extend graft patency duration while regulatory frameworks tighten evidentiary standards for implantable vascular devices.
Carbon-impregnated ePTFE grafts with enhanced radiopacity are displacing conventional unmarked conduits in complex peripheral revascularization procedures. Interventional radiologists in German university hospitals are adopting these technologies for fluoroscopy-guided placement. The structural consequence is compressing demand for intraoperative angiography accessories and reducing revision procedure rates.
Japan's PMDA maintains distinct biocompatibility assessment protocols that create incremental regulatory burden for market entry. The industrial consequence is segmenting supplier bases between PMDA-validated incumbents and EU-US focused challengers. Endovascular stent graft manufacturers with Japan-specific dossier preparation capabilities capture concentrated margins in Tokyo and Osaka metropolitan procurement zones.
Hospital supply chain rationalization is consolidating vendor lists toward full-line vascular surgery suppliers. Independent graft specialists face displacement by integrated device portfolios covering stents, balloons, and closure systems. This consolidation is most visible in United States integrated delivery networks where procurement committees prioritize single-source contracting for cardiovascular service lines.
ePTFE Vascular Prosthesis Market Segmentation
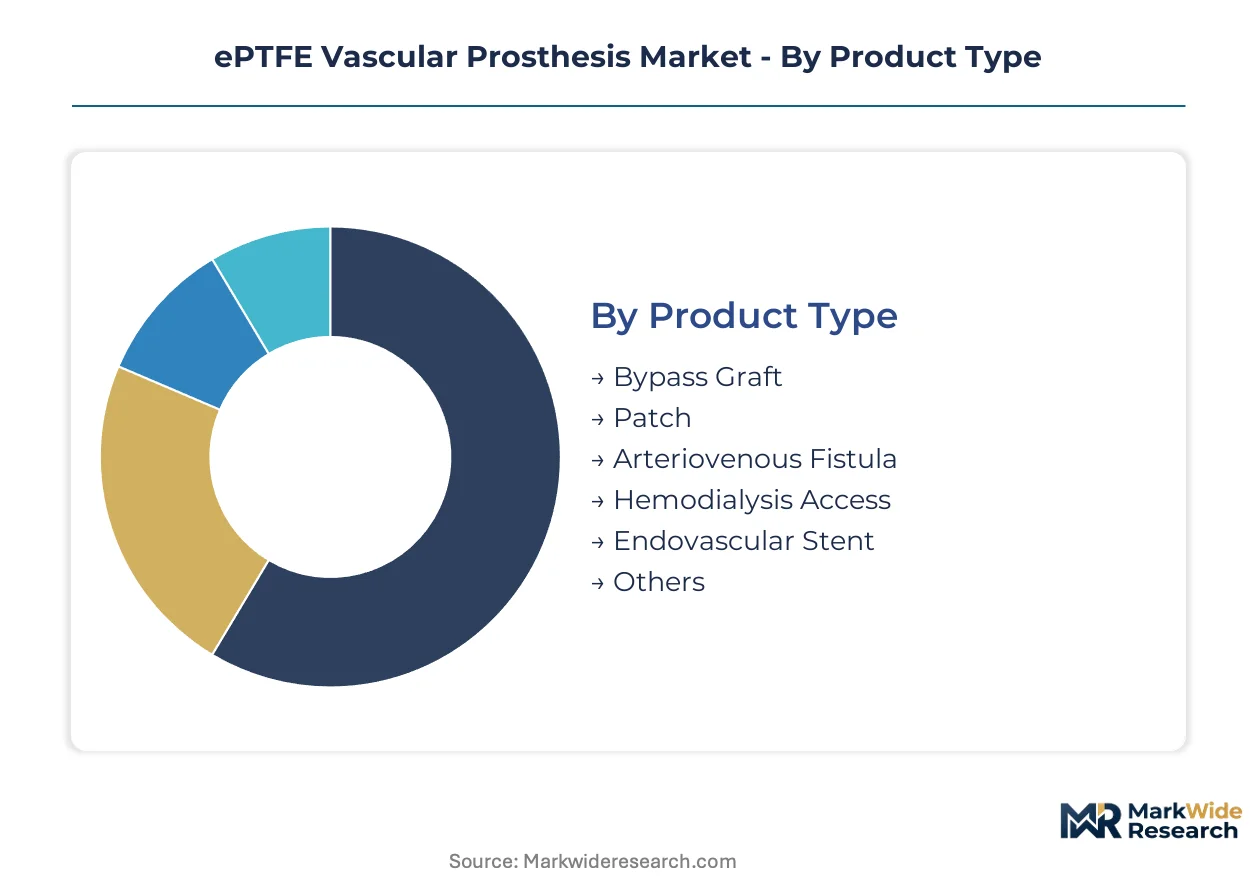
ePTFE vascular prosthesis segmentation reveals distinct procurement patterns across product architectures and clinical settings. Manufacturers align R&D investment with therapy-specific performance requirements rather than pursuing universal platform strategies.
Product Type:
Bypass graft procurement concentrates in United States and German cardiovascular service lines, while arteriovenous fistula demand accelerates in Japanese dialysis networks. Patch and stent graft categories show mixed geographic distribution.
- Bypass Graft:Fabricated as tubular conduits with 6-10mm diameters for femoropopliteal and aortoiliac reconstructions. German university hospitals and United States integrated delivery networks prioritize heparin-bonded variants for improved patency in small-diameter applications.
- Arteriovenous Fistula:Configured as tapered or straight grafts for dialysis access creation. Japanese metropolitan centers drive procedural volumes through PMDA-validated suppliers serving end-stage renal disease populations in Tokyo and Osaka.
- Patch:Planar ePTFE sheets for carotid endarterectomy and patch angioplasty closure.
- Hemodialysis Access:Specialized configurations for brachiocephalic and radiocephalic fistula creation.
- Endovascular Stent:ePTFE membranes bonded to nitinol frameworks for aortic aneurysm exclusion.
- Others:Custom geometries for congenital heart defect repair and trauma reconstruction.
Bypass graft commands the established base. The steepest expansion runs through arteriovenous fistula.
Therapy Area:
Peripheral artery disease interventions generate highest graft consumption volumes, while aortic aneurysm repair captures concentrated margins through endovascular approaches. Coronary applications face biological substitute competition.
- Peripheral Artery Disease:Femoropopliteal and infrapopliteal bypass procedures consume synthetic conduits where autologous vein is unavailable or unsuitable. German and United States vascular surgery departments specify carbon-impregnated radiopaque grafts for complex revascularization.
- Aortic Aneurysm:Thoracic and abdominal endovascular repair deploys ePTFE-lined stent grafts. Japanese and German centers favor manufacturers with catheter delivery system integration and longitudinal clinical registries.
- Coronary Artery Disease:Internal mammary artery and saphenous vein harvesting limits synthetic graft penetration.
- Renal Artery Stenosis:Patch angioplasty and bypass for renovascular hypertension.
- Carotid Artery Disease:Patch closure following endarterectomy in high-volume stroke centers.
Peripheral artery disease anchors volume procurement. Aortic aneurysm climbs the fastest on endovascular conversion.
End User:
Cardiovascular clinics dominate graft utilization through procedure concentration, while specialized surgery centers fragment procurement across narrower therapeutic focuses. Research institutes and diagnostic laboratories occupy peripheral positions.
- Cardiovascular Clinics:Dedicated vascular surgery units within hospital systems perform bulk of bypass and dialysis access procedures. United States and German clinics enforce vendor consolidation through single-source contracting.
- Specialized Surgery Centers:Ambulatory facilities focused on peripheral interventions.
- Research Institutes:Preclinical and clinical trial graft evaluation.
- Diagnostic Laboratories:Exploratory biocompatibility assessment and material characterization.
Cardiovascular clinics control the procurement base. Specialized surgery centers are gaining share fastest through outpatient migration.
Deployment Type:
Hospital-based deployment remains dominant for complex reconstructions, while ambulatory surgical centers expand into lower-acuity peripheral interventions. Specialty care facilities and outpatient clinics serve niche access roles.
- Hospitals:Inpatient surgical suites handle complex aortic and multivessel reconstructions requiring postoperative monitoring. Japanese and United States hospital systems negotiate enterprise pricing through procurement committee structures.
- Ambulatory Surgical Centers:Same-day discharge protocols for uncomplicated femoropopliteal bypass.
- Specialty Care Facilities:Dialysis centers with integrated surgical capabilities.
- Outpatient Clinics:Preoperative planning and postoperative surveillance.
Hospitals retain the procedure base. Ambulatory surgical centers show the steepest expansion trajectory on cost containment mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Newark-Air Cargo Complex underwrites United States distribution of implantable vascular devices, while Frankfurt Airport's pharmaceutical logistics hub anchors European graft procurement networks. These infrastructure assets compress transit times for temperature-sensitive medical implants.
United States
Integrated delivery networks in Texas and Florida drive bypass graft consumption through centralized cardiovascular service lines. FDA 510(k) clearance pathways enforce longitudinal patency data requirements that favor established predicate device portfolios. Newark-Elizabeth port facilities handle bulk resin imports for Delaware-based manufacturing clusters.
Germany
University hospitals in Bavaria and North Rhine-Westphalia specify carbon-impregnated radiopaque grafts for complex peripheral reconstructions. EU MDR notified body capacity constraints in Berlin and Munich extend CE marking timelines for novel designs. The Frankfurt-Rhine-Main logistics corridor distributes finished devices across Central European procurement zones.
Japan
Tokyo and Osaka metropolitan dialysis centers generate concentrated arteriovenous fistula demand from aging end-stage renal disease populations. PMDA biocompatibility assessment protocols create durable competitive moats for compliant suppliers. Kansai International Airport's cold-chain infrastructure supports just-in-time delivery to Osaka university hospitals.
India
Hemodialysis infrastructure buildout in Maharashtra and Tamil Nadu accelerates graft demand from private hospital chains. CDSCO regulatory harmonization with ISO 7198 standards reduces technical barriers for multinational manufacturers. Mumbai's pharmaceutical manufacturing corridor hosts contract fabrication facilities serving domestic and export markets.
United Kingdom
NHS England's specialized vascular surgery networks concentrate procurement through designated treatment centers in London and Manchester. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific approval pathways. Heathrow's pharmaceutical cargo terminals facilitate rapid restocking of London teaching hospital inventories.
ePTFE Vascular Prosthesis Market Competitive Landscape
Listed leaders compete with private specialists across predicate device validation capabilities, compressing margins for challengers lacking longitudinal clinical registries. The vendor base stratifies into three tiers: integrated cardiovascular device conglomerates with full therapy coverage, specialized graft fabricators with proprietary polymer processing expertise, and regional contract manufacturers serving price-sensitive procurement channels. Dominant competitive moves include backward integration into high-purity PTFE resin supply and strategic partnerships with catheter delivery system developers.
Within the integrated device tier, W. L. Gore & Associates and Medtronic exemplify divergent scale advantages. Gore's Delaware-based private structure permits sustained R&D commitment without quarterly earnings pressure. Medtronic's publicly traded Dublin-Minnesota operations leverage diversified cardiovascular portfolios to secure hospital single-source contracts. Among European specialists, B. Braun Melsungen's German GmbH structure anchors hemodialysis access supply chains through regional manufacturing proximity.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Medtronic |
| Cook Medical |
| Terumo Corporation |
| B. Braun Melsungen |
| Getinge |
| LeMaitre Vascular |
| Artivion |
| BD |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Delaware-based ePTFE manufacturing clusters shapes both supply concentration and price floors for vascular graft fabricators. German fluoropolymer resin producers leverage scale economies to anchor input pricing, while Japanese PMDA-validated suppliers command premiums through compliance moats.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between United States hospital systems and graft suppliers. Pricing stratifies across premium heparin-bonded variants, standard uncoated conduits, and economy-grade dialysis access grafts. Cost compression in the economy tier intensifies because Indian contract manufacturers absorb margin pressure to secure volume. Dialysis centers exhibit highest price sensitivity, while German university hospitals prioritize patency-proven premium tiers regardless of cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Newark-Air Cargo Complex fluctuate with container availability on trans-Pacific trade lanes serving Delaware manufacturing. High-purity PTFE resin supply concentrates in Germany and Japan, while mechanical stretching equipment draws from Bavarian and Delaware specialist fabricators. Single-source vulnerability runs through aged polymer processing workforces in both regions. Distribution runs through hospital GPO contracts and regional distributor networks serving cardiovascular service lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as outpatient migration to ambulatory surgical centers fragments procurement authority away from centralized hospital committees. Dialysis access expansion across Indian metropolitan markets creates additional niche entry points.
For Market Incumbents: Fortify predicate device portfolios through accelerated fatigue testing infrastructure investments to satisfy EU MDR clinical evidence requirements. Backward integration into high-purity PTFE resin supply hedges against German and Japanese chemical producer pricing power. Channel control through exclusive GPO contracts with United States integrated delivery networks defends against emerging contract manufacturers.
For New Entrants and Emerging Players: CDSCO harmonization with ISO 7198 standards offers a certification fast-track for established manufacturers seeking Indian market entry. Target Maharashtra and Tamil Nadu dialysis infrastructure buildout through distributor partnerships with private hospital chains. Hemodialysis access grafts represent the most penetrable segment given price sensitivity and volume acceleration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized graft fabricators with proprietary paste extrusion expertise over diversified device conglomerates. Long-term viability rests on surface modification chemistry capabilities extending patency duration. Watch PMDA validation timelines as inflection indicators for Japanese market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Predicate Device Expansion | Accelerated fatigue testing infrastructure satisfies notified body clinical evidence requirements for CE marking. |
| Heparin-Bonding Technology Licensing | Surface modification chemistry partnerships extend patency claims for small-diameter bypass applications. |
| Indian CDSCO Registration Pathway | ISO 7198 harmonization reduces technical barriers for dialysis access graft market entry. |
| Hospital GPO Contract Consolidation | Single-source cardiovascular service line agreements displace independent graft specialists. |
| Carbon-Impregnated Graft Launch | Radiopacity enhancements capture German university hospital procurement for complex reconstructions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with vascular surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CE marking databases under EU MDR, Japanese PMDA submission records, and hospital procurement databases. Bottom-up graft volume estimates triangulated against top-down therapy area expenditure models.
Across the analysis window, the forecasting framework modeled product type segmentation, therapy area demand patterns, end-user procurement channels, and deployment type migration trends. CAGRs were derived from procedure volume projections weighted by graft utilization rates and price tier mix assumptions. Surface modification technology adoption curves and regulatory approval cadences informed segment-specific growth trajectories.
Underlying assumptions cover stable EU MDR transition timelines and continued PMDA biocompatibility protocol consistency, with deviation risk concentrated in notified body capacity constraints and raw material supply volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.