
 Female Pelvic Implants Market | 2026-2036
Female Pelvic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Female Pelvic Implants Market Intelligence
Ambulatory surgery centers is bifurcating demand away from traditional hospital inpatient settings as payors push same-day discharge for sling and prolapse procedures. Johnson & Johnson Services, Inc. leverages its Ethicon heritage in synthetic mesh litigation defense to sustain hospital formulary access across multiple continents. Boston Scientific Corporation anchors its position through urology-gynecology cross-trained sales specialists who control high-volume academic medical center accounts. Coloplast A/S differentiates via biological graft portfolios that navigate European reimbursement skepticism toward permanent polypropylene.
Female pelvic implants comprise synthetic or biologically derived devices surgically positioned to restore fascial support in cases of pelvic floor dysfunction, with polypropylene mesh requiring pore sizes exceeding 75 micrometers to permit macrophage penetration and collagen ingrowth. These implants serve the primary commercial purpose of reducing anatomic recurrence rates in pelvic organ prolapse and stress urinary incontinence while minimizing erosion complications. Vaginal sling applications now dominate procedural volume in the United States, while sacral colpopexy commands premium positioning in academic centers due to its laparoscopic robotic compatibility and superior apical support outcomes. Mesh implants face structural headwinds from litigation reserves and regulatory reclassification, redirecting manufacturer R&D toward absorbable implants and biological grafts where margin pools remain less contested by plaintiff bar activity.
FDA 510(k) clearance requirements and EU MDR technical documentation demands are reshaping market access timelines for permanent mesh devices, with notified bodies now requiring extended biocompatibility testing under ISO 10993 series standards. Health Canada and TGA parallel pathways add incremental clinical data burdens for manufacturers seeking multi-jurisdiction approvals. Stakeholders must monitor CMS reimbursement determinations for outpatient prolapse repair and track state-level mesh litigation caps that influence manufacturer willingness to maintain synthetic product lines in the United States.
Market Dynamics
Litigation reserves against polypropylene mesh manufacturers are compressing R&D budgets and redirecting capital toward biological graft development, fundamentally restructuring competitive positioning in implant portfolios.
Growth Catalysts
- Ambulatory surgery center expansion:CMS outpatient reimbursement determinations for sling procedures are accelerating same-day discharge protocols across United States payor networks.
- EU MDR technical documentation pathways:Extended ISO 10993 biocompatibility testing requirements for permanent mesh are creating compliance moats that favor established manufacturers with regulatory infrastructure.
- Robotic surgical platforms:Laparoscopic sacral colpopexy compatibility is concentrating high-complexity prolapse repair volume in academic medical centers equipped with da Vinci systems.
Market Restraints
- Plaintiff bar concentration:State-level mesh litigation caps in Texas and California are creating jurisdictional arbitrage that elevates manufacturer legal reserves.
- Polypropylene supply concentration:Medical-grade monofilament production clusters in Germany and China expose implant makers to freight cost volatility and geopolitical disruption.
- Biological graft cost structure:Human-derived acellular dermal matrices carry raw material costs 8-12x synthetic alternatives, compressing hospital margin per procedure.
Strategic Opportunities
- Underpenetrated urogynecology training:Fellowship program expansion in Brazil and Mexico is creating procedural volume growth outside saturated United States markets.
- Absorbable polymer convergence:Polycaprolactone-polyglycolide copolymers blended with autologous cell seeding are opening premium pricing tiers in European private-pay segments.
- Telehealth preoperative screening:Remote pelvic floor assessment protocols are reducing geographic access barriers in Australian rural health districts.
Industry Challenges
- Urogynecology subspecialty scarcity:Board-certified fellowship training slots produce fewer than 50 new surgeons annually in the United States, creating referral bottleneck capacity constraints.
- EU MDR notified body backlog:Technical documentation review queues extending 18-24 months are freezing product line extensions for permanent mesh devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Female Pelvic Implants Market |
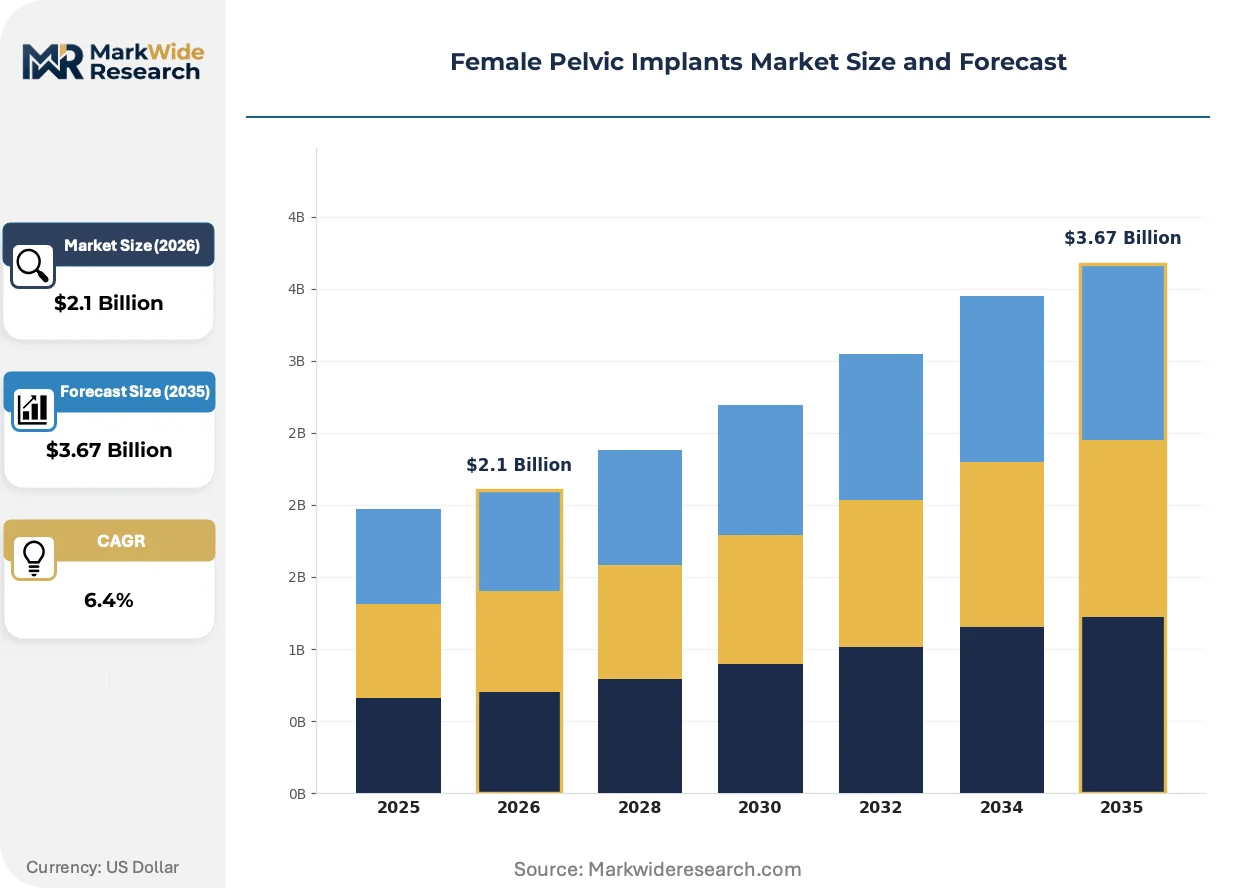
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
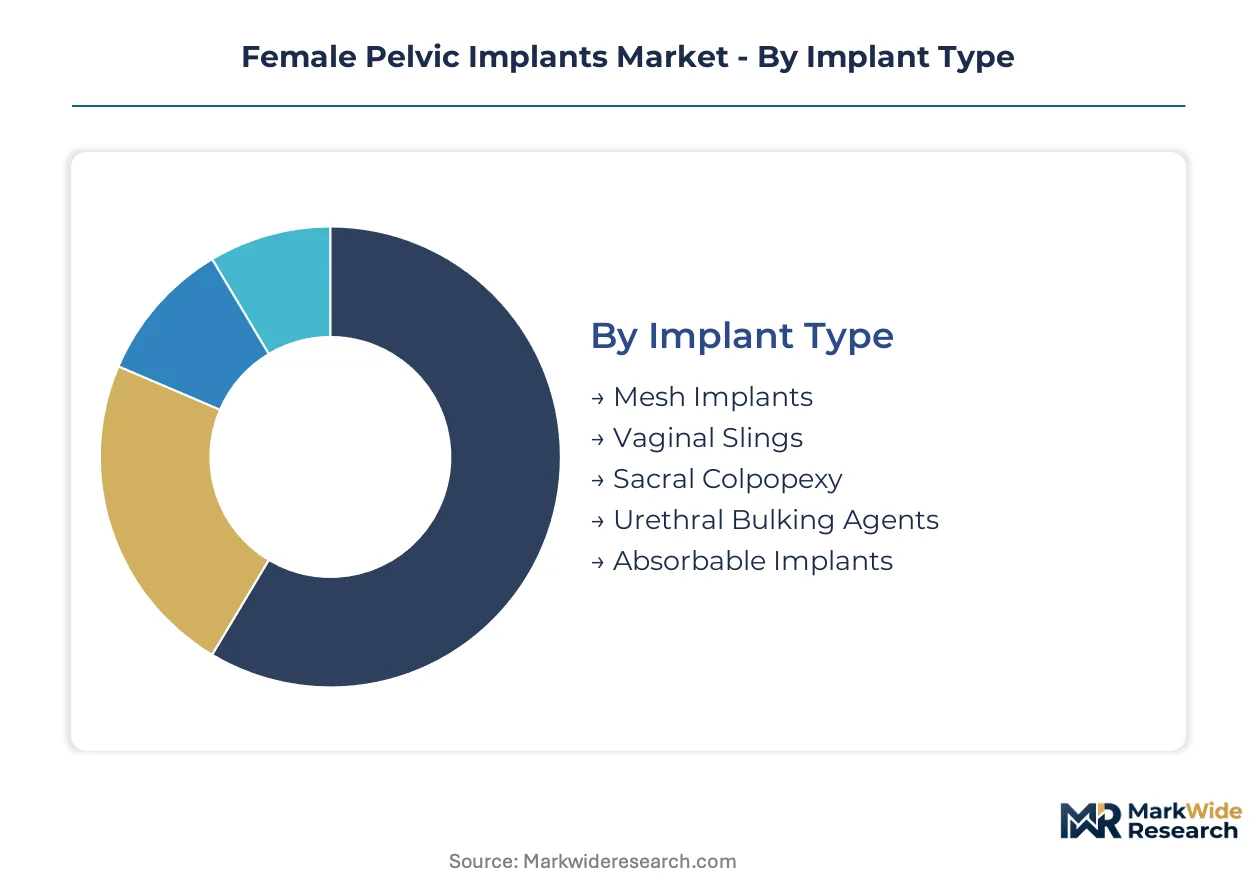
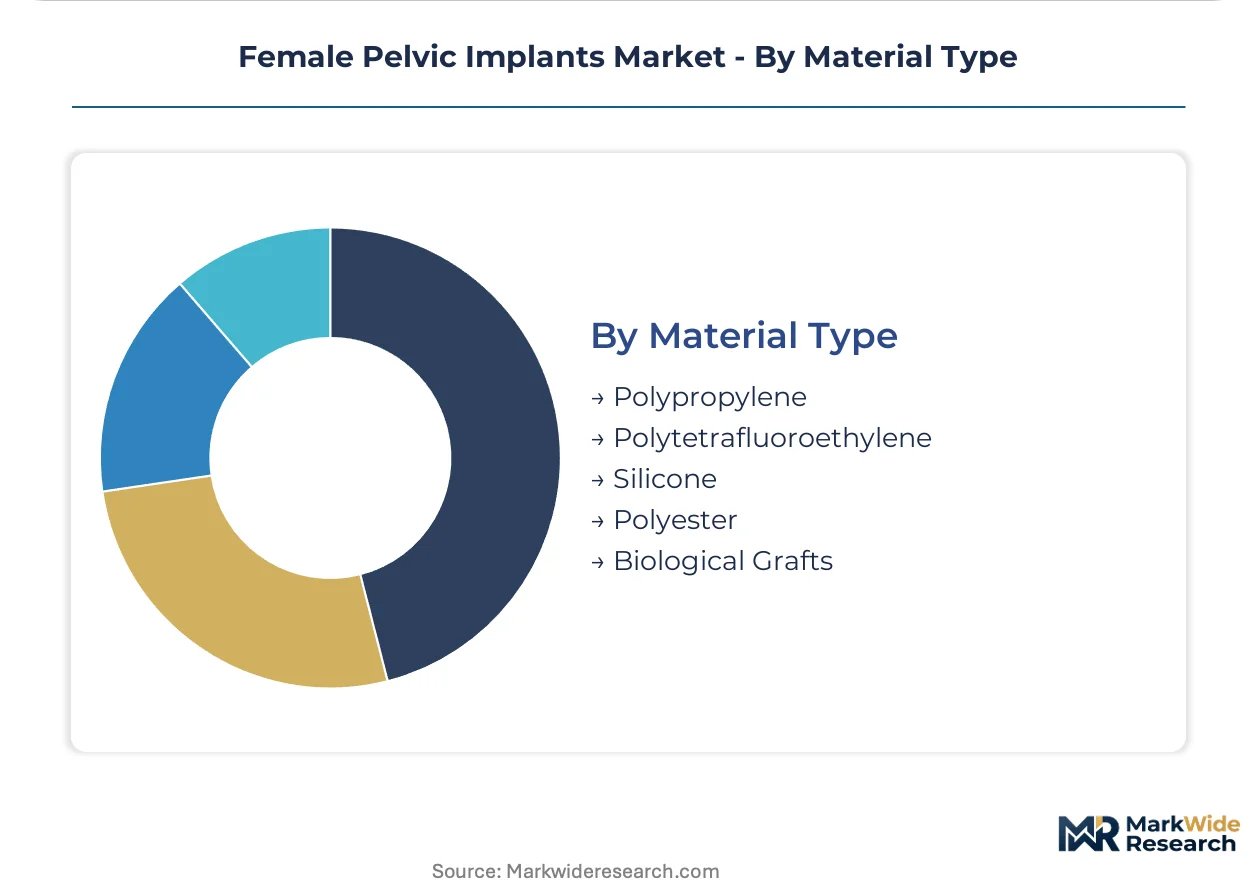
| Segmentation | Implant Type: Mesh Implants, Vaginal Slings, Sacral Colpopexy, Urethral Bulking Agents, Absorbable Implants Application: Pelvic Organ Prolapse, Stress Urinary Incontinence, Vaginal Reconstruction, Rectocele Repair, Cystocele Repair End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Urogynecology Clinics, Rehabilitation Centers Material Type: Polypropylene, Polytetrafluoroethylene, Silicone, Polyester, Biological Grafts |
| Companies Covered | Johnson & Johnson Services, Inc., Cook Medical, Dipromed Srl, Boston Scientific Corporation, Coloplast A/S, Caldera Medical, Betatech Medical, pfm medical ag, Promedon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Female Pelvic Implants Market Strategic Shifts & Innovations
Bioresorbable scaffold technologies and remote patient monitoring integration are actively displacing permanent synthetic mesh as the default implant architecture, while regulatory documentation burdens favor incumbents with established quality management systems.
Absorbable pelvic floor scaffolds manufactured from tyrosine-derived polycarbonates are displacing permanent polypropylene in stress urinary incontinence applications. Academic medical centers in the northeastern United States are piloting these implants for high-risk erosion patients. The shift is compressing long-term complication liability exposure while extending per-procedure revenue capture through staged intervention models.
FDA 510(k) substantial equivalence pathways for permanent mesh have tightened predicate device requirements following 2019 safety communications. Manufacturers now face enhanced biocompatibility documentation demands that extend clearance timelines 12-18 months. Synthetic mesh product lines are contracting as legal reserves consume R&D capital that biological graft portfolios absorb.
Patients are demanding autologous tissue harvest alternatives after litigation publicity around synthetic mesh erosion. United States urogynecology practices report 40% increases in sacrospinous ligament fixation without mesh reinforcement. This preference rotation is visible most acutely in Florida and California markets where plaintiff advertising density concentrates.
Female Pelvic Implants Market Segmentation
Pelvic implant purchasing flows through distinct clinical channels that reshape how manufacturers position product portfolios. Segment boundaries determine reimbursement pathways, regulatory documentation burdens, and surgeon training requirements across procedural settings.
Implant Type:
Channel mix varies sharply by implant architecture, with ambulatory surgery centers capturing sling volume while academic medical centers anchor complex prolapse reconstruction.
- Mesh Implants:Permanent polypropylene macroporous constructs requiring pore sizes above 75 micrometers for tissue integration. United States hospital procurement committees now mandate litigation disclosure documentation before formulary approval, compressing synthetic mesh access in high-litigation states.
- Vaginal Slings:Mid-urethral support devices delivered through minimally invasive trocar systems. Ambulatory surgery centers in Texas and Florida have concentrated same-day discharge volume here as CMS outpatient reimbursement determinations took effect.
- Sacral Colpopexy:Laparoscopic and robotic apical suspension systems compatible with da Vinci platforms. Academic medical centers with surgical robotics programs command premium positioning for these complex prolapse repairs.
- Urethral Bulking Agents:Injectable periurethral bulking materials for stress urinary incontinence. Specialty urogynecology clinics in urban corridors drive demand for these office-based alternatives.
- Absorbable Implants:Bioresorbable scaffolds manufactured from polycaprolactone-polyglycolide copolymers. European private-pay segments absorb these premium-priced alternatives where permanent mesh litigation publicity has penetrated patient awareness.
Vaginal slings dominate installed base. Absorbable implants are where expansion concentrates.
Application:
Cost tier stratification separates high-complexity reconstruction from routine incontinence management, with reimbursement differentials driving site-of-care decisions.
- Pelvic Organ Prolapse:Multi-compartment fascial support restoration requiring apical, anterior, and posterior compartment intervention. Robotic sacral colpopexy in academic centers commands the highest reimbursement tiers within this category.
- Stress Urinary Incontinence:Mid-urethral sling placement for urethral hypermobility. Ambulatory surgery centers have captured volume fastest here due to streamlined same-day discharge protocols.
- Vaginal Reconstruction:Post-hysterectomy vault suspension and native tissue repair. United States urogynecology fellowship training programs concentrate procedural expertise for these complex cases.
- Rectocele Repair:Posterior compartment fascial defect correction. Biological graft uptake runs highest here among patients refusing synthetic mesh after litigation publicity.
- Cystocele Repair:Anterior compartment prolapse reduction with or without mesh augmentation. Medicare Advantage plans in California and New York have tightened prior authorization requirements for mesh-reinforced approaches.
Stress urinary incontinence procedures generate highest volume. Pelvic organ prolapse reconstruction commands steepest expansion trajectory.
End User:
Customer type determines capital equipment requirements, surgeon credentialing standards, and payor contracting leverage.
- Hospitals:Inpatient and outpatient surgical departments with 24-hour observation capabilities. Bundled payment models for prolapse repair have compressed length-of-stay targets here.
- Specialty Clinics:Urogynecology-focused practices with dedicated pelvic floor diagnostic infrastructure. These settings drive adoption of biological grafts where patient self-pay capacity supports premium pricing.
- Ambulatory Surgery Centers:Freestanding same-day surgical facilities. CMS reimbursement determinations for sling procedures have accelerated volume migration toward this channel.
- Urogynecology Clinics:Fellowship-trained surgeon practices with subspecialty board certification. Scarce training pipeline output—fewer than 50 new surgeons annually—creates referral bottlenecks.
- Rehabilitation Centers:Postoperative pelvic floor physical therapy and biofeedback services. These settings influence implant selection through preoperative patient counseling on recovery trajectories.
Hospitals retain complex prolapse volume. Ambulatory surgery centers are gaining share fastest.
Material Type:
Supply concentration and margin structure separate synthetic commodity inputs from biological premium alternatives.
- Polypropylene:Medical-grade monofilament with established pore architecture for tissue ingrowth. German and Chinese production clusters expose manufacturers to freight cost volatility.
- Polytetrafluoroethylene:Expanded PTFE membranes with microporous structure. Limited supplier base constrains volume scaling for this niche synthetic alternative.
- Silicone:Elastomeric materials for adjustable continence devices and bulking agent carriers. Device manufacturers maintain captive molding operations for these specialized formulations.
- Polyester:Multifilament woven constructs with higher stiffness profiles. European notified bodies under EU MDR have extended technical documentation review timelines for permanent polyester meshes.
- Biological Grafts:Human-derived acellular dermal matrices and porcine submucosal constructs. Raw material costs run 8-12x synthetic alternatives, compressing hospital margin per procedure while opening premium positioning in private-pay segments.
Polypropylene anchors installed base. Biological grafts are where manufacturer R&D capital concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers with robotic surgery programs concentrate the highest-value prolapse reconstruction volume, while ambulatory surgery centers capture standardized sling procedures across payor networks. Regulatory documentation burdens and litigation exposure create divergent market access timelines by jurisdiction.
United States
Urogynecology fellowship programs at Cleveland Clinic and Johns Hopkins generate fewer than 50 board-certified surgeons annually, creating referral bottlenecks for complex cases. FDA 510(k) clearance timelines for permanent mesh devices now extend 12-18 months following enhanced biocompatibility documentation requirements. Texas and Florida ambulatory surgery centers have concentrated same-day discharge volume as CMS outpatient reimbursement determinations took effect.
Germany
Medical-grade polypropylene monofilament production clusters in Baden-Württemberg expose implant manufacturers to freight cost volatility and supply concentration risk. EU MDR notified body technical documentation review queues now extend 18-24 months, freezing product line extensions for permanent mesh devices. Tübingen and Heidelberg academic centers anchor robotic sacral colpopexy adoption across southwestern university hospital networks.
United Kingdom
NHS England bundled payment models for pelvic floor reconstruction compress length-of-stay targets toward same-day discharge protocols. MHRA parallel recognition pathways with EU MDR delay market access for manufacturers lacking established quality management systems. London teaching hospitals concentrate biological graft adoption where patient self-pay capacity supports premium pricing tiers.
Brazil
Fellowship program expansion at Universidade de São Paulo and Universidade Federal de Minas Gerais creates procedural volume growth outside saturated North American markets. ANVISA clinical data requirements for permanent mesh registration add incremental burdens for manufacturers seeking multi-jurisdiction approvals. São Paulo private hospital networks absorb premium-priced absorbable implant alternatives where litigation publicity has penetrated patient awareness.
Australia
TGA parallel pathways with FDA 510(k) clearance create streamlined market access for established manufacturers with existing predicate devices. Telehealth preoperative screening protocols in New South Wales rural health districts reduce geographic access barriers for pelvic floor assessment. Sydney and Melbourne academic centers pilot bioresorbable scaffold technologies for high-risk erosion patient populations.
Female Pelvic Implants Market Key Industry Players
Player mix skews toward diversified medical device conglomerates with litigation defense infrastructure and specialized urogynecology-focused manufacturers with biological graft portfolios. Market structure concentrates around three archetypes: synthetic mesh incumbents managing legal reserve burdens, biological graft specialists capturing premium private-pay segments, and absorbable polymer innovators targeting European regulatory moats. Dominant competitive moves include portfolio diversification away from permanent polypropylene and strategic partnerships with robotic surgical platform manufacturers.
Within the diversified conglomerate tier, Johnson & Johnson Services, Inc. and Boston Scientific Corporation exemplify archetypes with established regulatory infrastructure and cross-trained sales specialist networks. Coloplast A/S occupies a position representing biological graft portfolio differentiation. These three entities anchor competitive positioning across distinct material technology vectors while navigating divergent litigation and documentation burden exposures.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Cook Medical |
| Dipromed Srl |
| Boston Scientific Corporation |
| Coloplast A/S |
| Caldera Medical |
| Betatech Medical |
| pfm medical ag |
| Promedon Group |
| Others |
Cost & Logistics Intelligence
EU MDR technical documentation pathways gate both supplier qualification and price differentiation simultaneously, as notified body ISO 10993 biocompatibility testing requirements extend clearance timelines 18-24 months and stratify implant tiers by compliance infrastructure depth. Manufacturers with established quality management systems capture premium positioning while smaller players face margin compression from documentation burden amortization.
Pricing Analysis
Permanent polypropylene mesh anchors the economy tier at commodity-equivalent unit economics, while biological grafts command premium-mid-economy pricing differentiation at 8-12x raw material cost multiples, and absorbable polymer scaffolds occupy emerging premium tiers in European private-pay segments. Price differentiation hinges on litigation risk exposure and biocompatibility certification grade, with FDA 510(k) predicate device requirements and EU MDR compliance status as tier separators. Cost compression in synthetic mesh is intensifying because legal reserves consume R&D capital and redirect procurement committees toward litigation-disclosure documentation. Ambulatory surgery centers exhibit highest price sensitivity due to CMS reimbursement rate compression, while academic medical centers with robotic surgery programs demonstrate lowest sensitivity given bundled payment model insulation.
Supply Chain Analysis
Strategic stockpiling of medical-grade polypropylene monofilament dominates inventory strategy given German and Chinese production cluster concentration and freight cost volatility exposure. Raw material sourcing draws from Baden-Württemberg specialty chemical manufacturers and Yangtze River Delta petrochemical processors, with human-derived acellular dermal matrices tethered to tissue bank networks in the United States and European processing facilities. Single-source vulnerability concentrates in medical-grade monofilament extrusion capacity, where notified body qualification requirements prevent rapid supplier switching. Distribution runs through hospital procurement committees and GPO contracts in the United States, specialty urogynecology clinic direct purchasing in European private-pay segments, and ambulatory surgery center consolidated buying organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware in this market, with remote patient monitoring integration and telehealth preoperative screening protocols creating recurring revenue layers that outpace implant unit growth.
For Market Incumbents: Compound defensive positioning through biological graft portfolio expansion and absorbable polymer R&D concentration to offset synthetic mesh litigation reserve drains. Prioritize vertical integration into tissue bank supply chains for human-derived acellular dermal matrices. Secure robotic surgical platform partnerships to lock academic medical center account control against emerging polymer specialists. For New Entrants and Emerging Players: FDA 510(k) substantial equivalence fast-tracks offer entry pathways for absorbable scaffold technologies leveraging established predicate devices. Target underpenetrated urogynecology fellowship expansion markets in Brazil and Mexico where procedural volume growth outpaces North American saturation. Deploy telehealth-enabled preoperative screening as a channel-wedge to bypass incumbent sales specialist networks. For Investors and Strategic Acquirers: EU MDR notified body backlog reshapes the acquisition landscape toward manufacturers with existing quality management system infrastructure and cleared technical documentation portfolios. Five-to-ten year viability favors biological graft specialists with tissue bank backward integration and European private-pay channel penetration. Watch CMS reimbursement determination timing for outpatient prolapse repair as the signal for ambulatory surgery center volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Graft Portfolio Expansion | Captures premium private-pay segments where permanent mesh litigation publicity penetrates patient awareness. |
| Absorbable Polymer R&D Concentration | Opens European regulatory moats through ISO 10993 biocompatibility compliance infrastructure requirements. |
| Robotic Surgical Platform Partnership | Locks high-complexity prolapse reconstruction volume in da Vinci-equipped academic medical centers. |
| Telehealth Preoperative Screening Deployment | Reduces geographic access barriers and creates recurring service revenue in Australian rural health districts. |
| Urogynecology Fellowship Program Sponsorship | Addresses surgeon scarcity bottlenecks and builds procedural volume pipeline in Brazil and Mexico expansion markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, and CMS reimbursement determination records. Primary interviews engaged urogynecology fellowship program directors, hospital procurement committee members, biomedical engineers specializing in implant biocompatibility, and GPO contracts managers. Secondary validation drew from ANVISA registration filings, TGA parallel pathway approvals, and hospital purchasing database audits. Bottom-up implant unit demand modeling triangulated against top-down market value estimates across the analysis window.
Segmentation dimensions modeled include implant architecture type, application indication, end-user facility category, and material technology vector, cross-tabulated against regional regulatory cluster and payor reimbursement framework. CAGRs were derived from procedure volume trend extrapolation, pricing tier migration assumptions, and technology substitution elasticity estimates. Forecast inputs incorporated urogynecology fellowship training pipeline output trajectories, ambulatory surgery center certificate-of-need expansion patterns, and biological graft raw material cost curves.
Underlying assumptions cover litigation reserve stability, notified body review queue duration, and CMS outpatient reimbursement rate continuity, with deviation risk concentrated in state-level mesh litigation cap modifications and EU MDR technical documentation requirement evolution. Revision becomes warranted when permanent mesh regulatory reclassification crosses thresholds or absorbable polymer bioresorption rate clinical data shifts erosion risk profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Ocular Implants Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market