
 Global Diagnostic Catheter Market | 2026-2036
Global Diagnostic Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagnostic Catheter Market Foresight
Multi-source procurement for polymer tubing and sensor arrays is rebalancing toward vertically integrated supply chains as OEMs seek greater control over catheter performance consistency. Boston Scientific leverages captive extrusion capabilities to secure proprietary braid-reinforced shaft geometries. Medtronic sustains broad geographic manufacturing footprints across Costa Rica and Ireland to buffer against single-region disruptions. Abbott Laboratories anchors its competitive position through intensive R&D spending on next-generation pressure-sensing guidewire platforms.
A diagnostic catheter is a sterile, flexible tubular instrument engineered from engineered thermoplastics such as Pebax or nylon with embedded metallic braid reinforcement, designed to navigate vascular anatomy while delivering sensors, contrast media, or energy to targeted tissue sites for real-time physiological assessment. The device enables physicians to acquire hemodynamic data, vascular imaging, and electrical mapping without open surgical intervention. Imaging catheters lead revenue contribution due to premium pricing of optical coherence tomography and intravascular ultrasound modalities, while electrophysiology catheters represent the fastest-expanding product category as atrial fibrillation ablation volumes climb across developed health systems. Cardiac diagnostics dominates application share given coronary artery disease prevalence, though neurovascular diagnostics is gaining procedural traction as stroke intervention networks mature.
The FDA enforces stringent biocompatibility and sterilization validation requirements under 21 CFR Part 820 quality system regulations, while the EU MDR mandates enhanced clinical evidence and post-market surveillance for Class III invasive devices. Japan's PMDA imposes additional layer of local clinical testing for novel catheter technologies, extending market access timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient catheter-based diagnostics as payers scrutinize cost-effectiveness against non-invasive alternatives.
Market Dynamics
Electrophysiology catheter demand is concentrating procurement power among integrated hospital networks as atrial fibrillation ablation volumes reshape manufacturer-customer relationships across developed health systems.
Growth Catalysts
- EU MDR compliance mandates:Enhanced clinical evidence requirements for Class III invasive devices are accelerating replacement cycles as older catheter designs face re-certification pressures.
- Japan's electrophysiology lab expansion:Metropolitan hospital networks in Tokyo and Osaka are scaling catheter-based cardiac mapping infrastructure to address aging-related arrhythmia prevalence.
- Optical coherence tomography integration:Imaging catheter platforms incorporating high-resolution intravascular visualization are displacing conventional angiography in complex coronary interventions.
Market Restraints
- Nitinol and Pebax supply concentration:Specialty polymer and shape-memory alloy sourcing remains dependent on a limited supplier base concentrated in Germany and the United States.
- PMDA local clinical testing requirements:Japan's pharmaceutical and medical device agency imposes extended evaluation timelines that compress foreign manufacturers' effective patent windows.
- Non-invasive cardiac imaging substitution:CT angiography and cardiac MRI advances are capturing diagnostic volumes previously routed to catheter-based assessment in stable coronary disease presentations.
Strategic Opportunities
- India's catheterization laboratory buildout:Tier-2 city hospital networks are establishing electrophysiology capabilities where procedural penetration remains below Western benchmarks.
- Neurovascular diagnostic catheter expansion:Stroke intervention network maturation in Germany and Japan is creating dedicated demand for intracranial access and imaging platforms.
- ISO 13485 quality system harmonization:Converging international medical device quality standards are reducing multi-jurisdictional certification friction for manufacturers with established compliance infrastructure.
Industry Challenges
- Polymer extrusion technician scarcity:Precision thermoplastic processing expertise for multi-lumen catheter shafts remains concentrated among a narrow workforce pool in Costa Rica and Ireland manufacturing clusters.
- Biocompatibility validation timeline compression:FDA 21 CFR Part 820 sterilization validation requirements and evolving endotoxin testing protocols are extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagnostic Catheter Market |
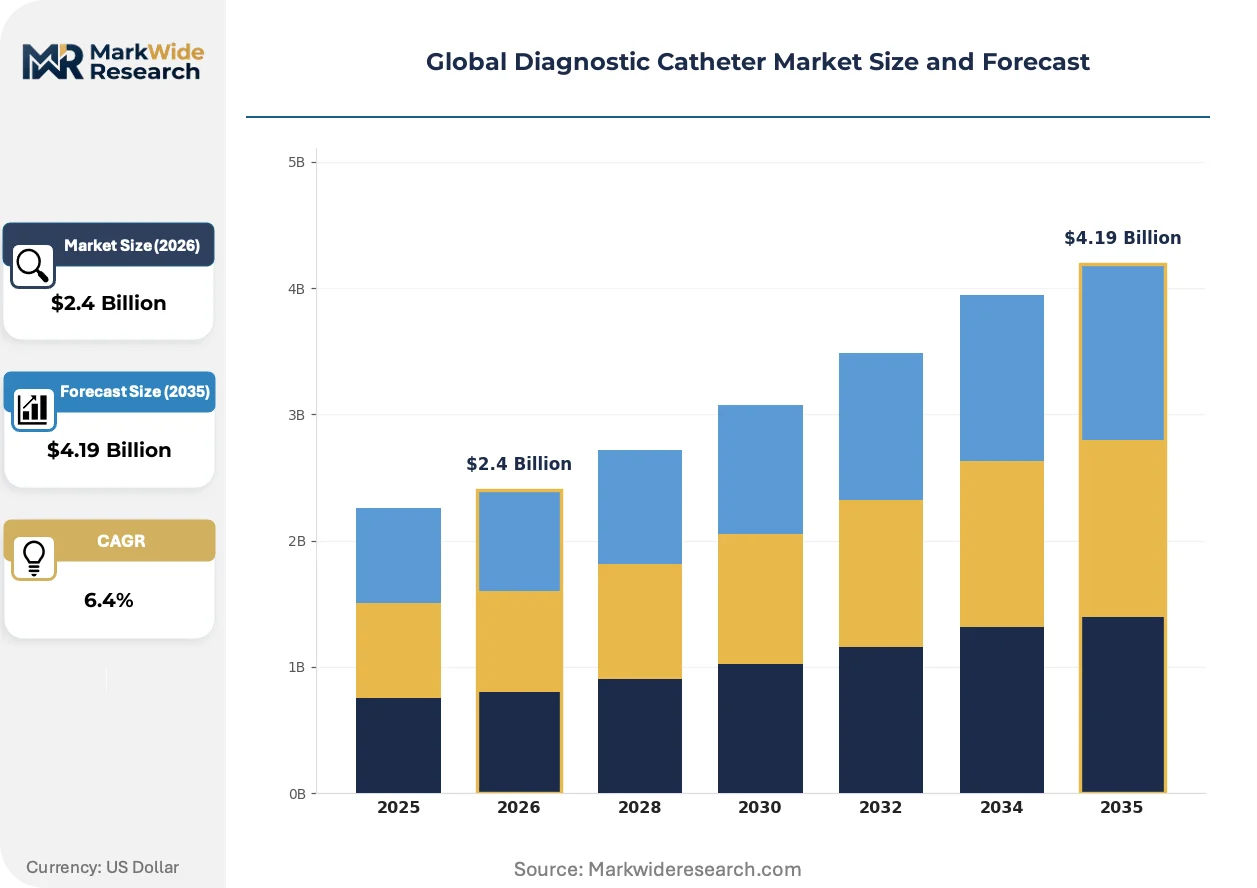
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheter, Guide Catheter, Imaging Catheter, Electrophysiology Catheter End User: Hospitals, Cardiology Centers, Diagnostic Labs, Ambulatory Surgical Centers Technology: 2D Imaging, 3D Imaging, Optical Coherence Tomography, Ultrasound Application: Cardiac Diagnostics, Neurovascular Diagnostics, Gastroenterology Diagnostics, Urological Diagnostics |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Johnson & Johnson, Koninklijke Philips N.V., B. Braun Melsungen AG, Terumo Corporation, Edwards Lifesciences Corporation, Cardinal Health, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagnostic Catheter Market Shifts & Advancements
Diagnostic catheter architecture is undergoing material and sensor integration transformation as manufacturers compete on navigation precision and real-time data fidelity without expanding device profiles.
Intravascular ultrasound technology is converging with optical coherence tomography in hybrid imaging catheter platforms that simultaneously deliver acoustic and optical tissue characterization. Cardiology centers in Germany and the United States are piloting these dual-modality systems for complex bifurcation lesion assessment. The structural consequence is compressing the addressable market for standalone IVUS and OCT catheters as purchasers consolidate capital equipment footprints.
EU MDR post-market surveillance mandates are forcing manufacturers to establish systematic clinical follow-up infrastructure for Class III device performance tracking. Industrial consequence includes elevated documentation burdens and expanded quality management system scope. Electrophysiology catheter producers with existing European notified body relationships are responding fastest, while smaller entrants face extended conformity assessment timelines.
Hospital procurement committees are consolidating vendor relationships around full-procedure catheter portfolios rather than single-device purchasing. Integrated delivery networks in the United States are displacing traditional distributor-mediated transactions with direct manufacturer agreements spanning diagnostic and interventional catheter lines. This concentration is most visible in cardiology service line management structures across multi-hospital systems in Texas and California.
Global Diagnostic Catheter Market Segmentation
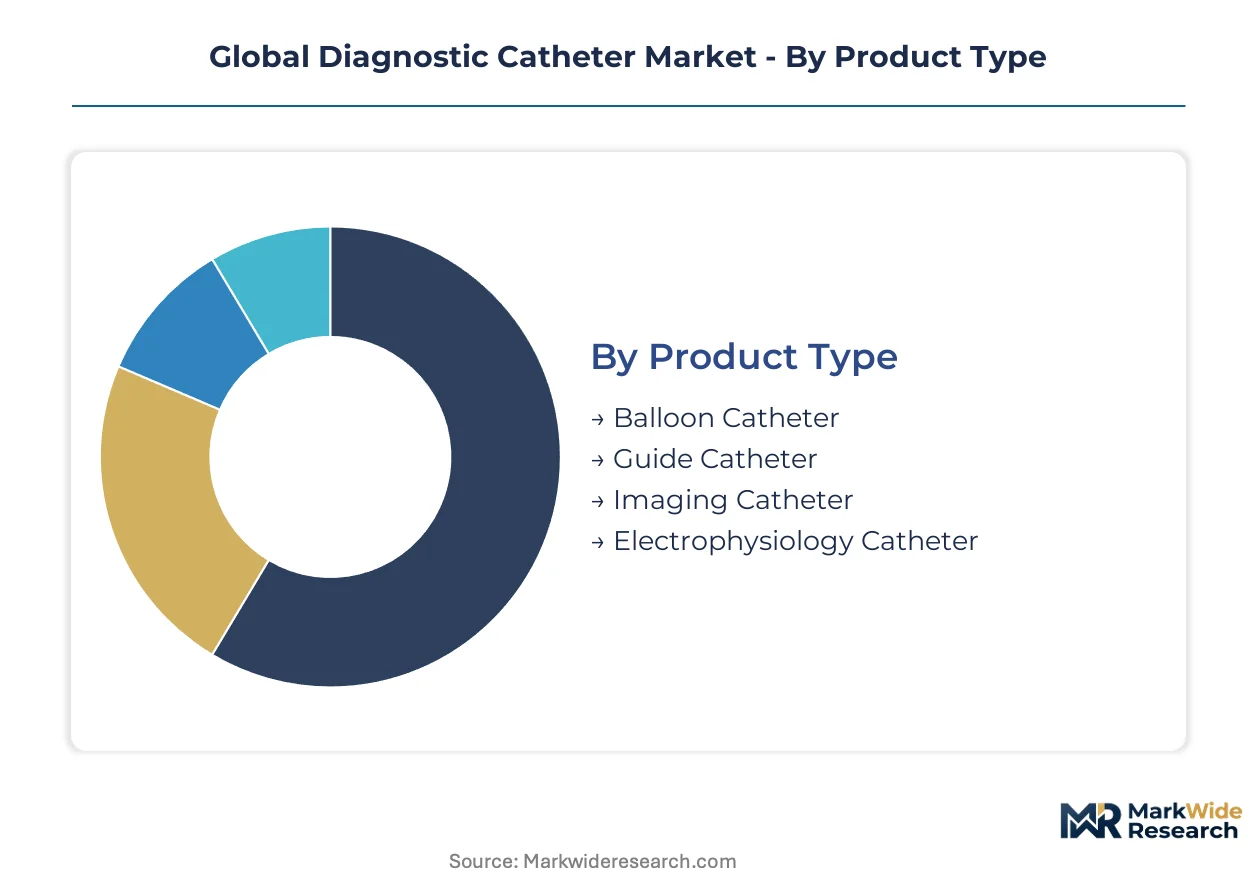
Diagnostic catheter procurement varies sharply across clinical settings and technical specifications, with regulatory classification under FDA 21 CFR Part 820 and EU MDR determining market access timelines and reimbursement eligibility for each segment cluster.
Product Type:
EU MDR Class III designation applies universally across these segments, though imaging and electrophysiology platforms face intensified clinical evidence requirements for novel sensor integrations.
- Imaging Catheter:Hybrid platforms combining optical coherence tomography with intravascular ultrasound deliver simultaneous acoustic and optical tissue characterization. Demand concentrates in German and United States cardiology centers performing complex bifurcation lesion assessment, with reimbursement premiums tied to procedural volume thresholds.
- Electrophysiology Catheter:Multi-electrode mapping arrays enable real-time cardiac electrical signal acquisition during atrial fibrillation ablation procedures. Tokyo and Osaka metropolitan hospital networks are scaling procurement as Japan's aging population drives arrhythmia intervention volumes.
- Balloon Catheter:Inflation-lumen designs with compliant or non-compliant balloon geometries facilitate vascular access and lesion crossing.
- Guide Catheter:Braided-reinforced shafts provide stable conduit delivery for interventional devices across coronary and peripheral vasculature.
Leading the category by volume: Imaging Catheter. Growing fastest: Electrophysiology Catheter.
End User:
Procurement authority concentrates differently across facility types, with integrated delivery networks in the United States consolidating purchasing power while Japan's hospital-centric system maintains centralized tender processes.
- Cardiology Centers:Dedicated electrophysiology laboratories in Germany and the United States command premium pricing for specialized diagnostic platforms. These facilities prioritize catheter portfolios spanning mapping, ablation, and imaging modalities to maximize equipment utilization rates.
- Hospitals:Multi-service-line institutions balance capital allocation across cardiac, neurovascular, and peripheral intervention programs. United States hospital systems in Texas and California are displacing distributor-mediated transactions with direct manufacturer agreements covering full-procedure catheter lines.
- Ambulatory Surgical Centers:Outpatient settings focus on streamlined diagnostic catheter configurations for lower-complexity coronary assessments.
- Diagnostic Labs:Standalone imaging facilities prioritize cost-optimized catheter specifications for high-throughput screening protocols.
Highest absolute procurement volume: Hospitals. Steepest expansion trajectory: Cardiology Centers.
Technology:
Capital equipment compatibility and software integration requirements segment purchasing decisions, with hybrid modalities commanding integrated platform investments.
- Optical Coherence Tomography:Near-infrared light interferometry achieves 10-micron resolution for coronary plaque characterization. German cardiology centers pilot dual-modality systems that compress addressable demand for standalone imaging technologies.
- 3D Imaging:Electroanatomical mapping systems reconstruct cardiac chamber geometry in real-time during ablation procedures. United States electrophysiology laboratories are replacing 2D fluoroscopy-dependent workflows with these platforms to reduce radiation exposure.
- 2D Imaging:Conventional fluoroscopic guidance remains standard for cost-sensitive procedural settings.
- Ultrasound:Intravascular acoustic imaging provides cross-sectional vessel visualization for stent sizing and optimization.
Dominant installed base: 2D Imaging. Technology transition leader: 3D Imaging.
Application:
Procedure volume distribution and reimbursement density vary substantially across anatomical targets, with cardiac interventions maintaining volume leadership while neurovascular applications gain network infrastructure.
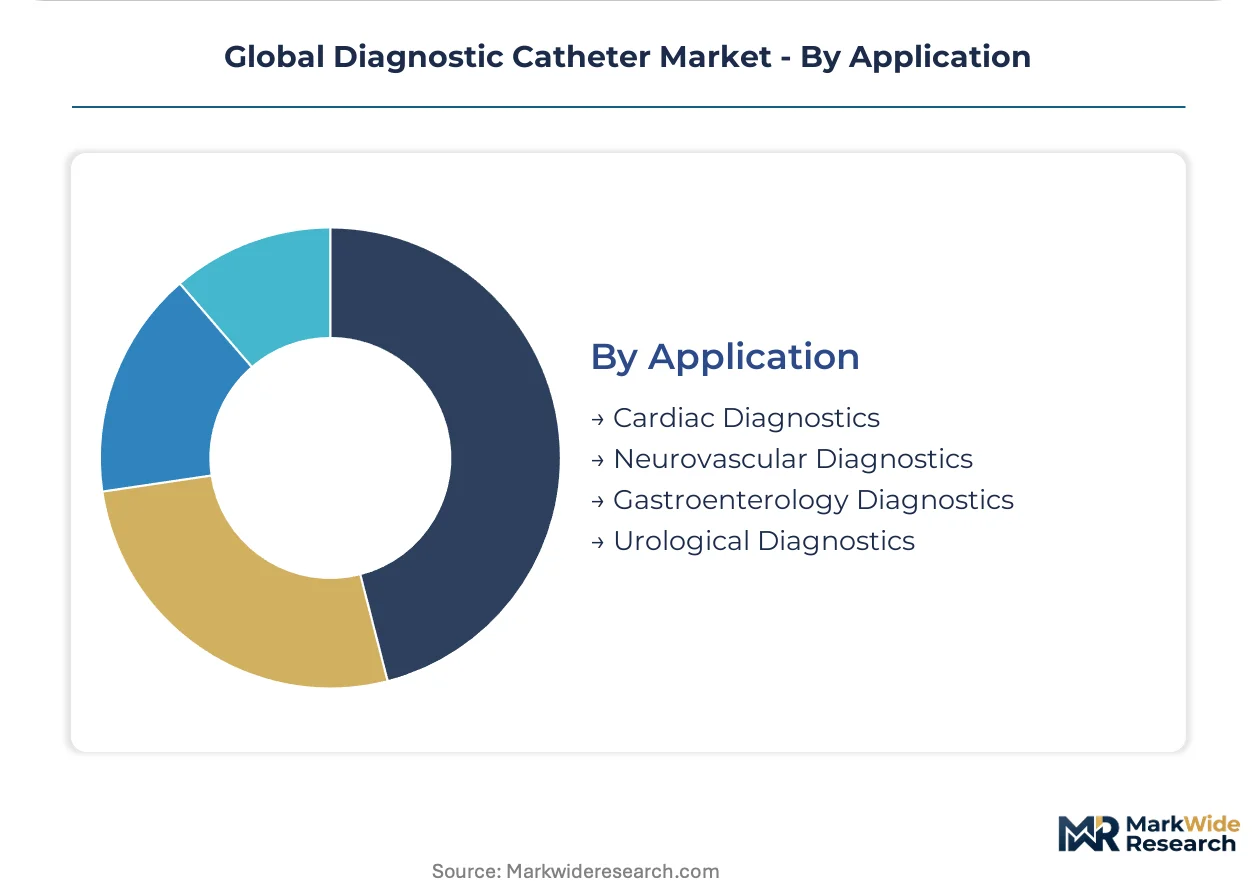
- Cardiac Diagnostics:Coronary artery disease prevalence sustains procedural dominance across all developed health systems. Catheter-based hemodynamic assessment and intravascular imaging represent standard-of-care for intermediate-risk chest pain presentations in United States and German hospitals.
- Neurovascular Diagnostics:Intracranial access platforms enable stroke intervention network maturation. Japan and Germany are establishing dedicated neurovascular catheterization capabilities as mechanical thrombectomy volumes expand.
- Gastroenterology Diagnostics:Biliary and pancreatic access catheters serve endoscopic retrograde cholangiopancreatography procedures.
- Urological Diagnostics:Ureteral access sheaths and pressure-monitoring catheters support diagnostic nephrostomy and urodynamic assessment.
Volume concentration: Cardiac Diagnostics. Segment gaining share fastest: Neurovascular Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German nitinol wire and Pebax polymer suppliers anchor the upstream supply base for catheter shaft manufacturing. United States electrophysiology lab networks and Japanese metropolitan hospital systems concentrate downstream demand. Regulatory divergence across FDA, EU MDR, and PMDA jurisdictions fragments certification timelines.
United States
Integrated delivery networks in Texas and California consolidate procurement around full-procedure catheter portfolios. FDA 21 CFR Part 820 quality system regulations enforce biocompatibility validation timelines that extend product development cycles. Boston Scientific's captive extrusion capabilities in Massachusetts exemplify backward integration into polymer processing.
Germany
Cardiology centers in Munich and Heidelberg pilot hybrid IVUS-OCT imaging platforms for complex bifurcation assessment. EU MDR Class III clinical evidence requirements accelerate replacement cycles for legacy catheter designs. The Baden-Württemberg industrial cluster hosts precision polymer extrusion specialists serving shaft geometry specifications.
Japan
Tokyo and Osaka metropolitan hospital networks scale electrophysiology laboratory infrastructure for aging-related arrhythmia volumes. PMDA local clinical testing mandates compress foreign manufacturers' effective patent windows. Terumo Corporation's domestic manufacturing footprint buffers against import-dependent supply disruptions.
India
Tier-2 city hospital networks in Maharashtra and Karnataka establish catheterization capabilities below Western procedural penetration benchmarks. CDSCO medical device regulations converge toward ISO 13485 harmonization. Hyderabad's medtech corridor attracts contract manufacturing investments for cost-optimized catheter specifications.
Costa Rica
Medtronic's manufacturing presence leverages free trade zone status for United States market access. Precision thermoplastic processing expertise concentrates in the San José metropolitan cluster. Polymer extrusion technician scarcity across this and Ireland manufacturing nodes constrains multi-lumen shaft production scaling.
Global Diagnostic Catheter Market Competitive Landscape
Backward integration into polymer extrusion dominates the current landscape as OEMs seek shaft geometry control. The vendor base stratifies across diversified multinationals with captive supply chains, mid-scale specialists with regional manufacturing footprints, and component suppliers serving private-label assemblers. Two archetypes prevail: integrated platform providers spanning diagnostic and interventional portfolios, and imaging modality specialists with capital equipment dependencies. M&A activity and strategic partnerships concentrate procurement power among hospital networks.
Among diversified multinationals, Boston Scientific Corporation, Medtronic plc, and Abbott Laboratories exemplify the integrated platform archetype. These entities occupy positions where captive manufacturing capabilities and broad geographic footprints anchor competitive positioning. Terumo Corporation represents the Asia-Pacific manufacturing specialist tier, while Koninklijke Philips N.V. and Edwards Lifesciences Corporation sit within imaging and hemodynamic monitoring specialization vectors. Johnson & Johnson and B. Braun Melsungen AG span diversified medical device portfolios with catheter line extensions. Cardinal Health occupies the distribution and logistics tier rather than primary manufacturing.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Edwards Lifesciences Corporation |
| Cardinal Health |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Nitinol wire and Pebax polymer spot indices cascade through catheter manufacturing tiers, compressing margins for non-integrated assemblers while reinforcing pricing power among OEMs with captive extrusion capabilities. Cost pass-through mechanics differentiate premium imaging platforms from standard electrophysiology configurations as raw material volatility concentrates procurement leverage.
Pricing Analysis
Service bundling separates capital equipment-inclusive contracts from bare-device transactions, with hybrid IVUS-OCT platforms commanding integrated platform premiums against unbundled diagnostic catheter sales. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification depth, and geographic service coverage. Price erosion runs through economy-tier balloon catheters as Indian contract manufacturers scale cost-optimized specifications. Ambulatory surgical centers exhibit highest price sensitivity, while German cardiology centers prioritize performance consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in San José, Costa Rica and Galway, Ireland anchor hub-and-spoke patterns serving United States and EU hospital networks respectively. Nitinol wire drawing concentrates in Germany and United States, while Pebax polymer compounding clusters in France and United States. Single-source vulnerability pervades multi-lumen extrusion tooling, with precision thermoplastic processing expertise tethered to narrow technician pools. Distribution runs through GPO-mediated contracts in United States integrated delivery networks and direct manufacturer agreements in Japanese metropolitan hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer extrusion technician scarcity props pricing across catheter shaft manufacturing, constraining capacity expansion regardless of downstream demand signals. Supply bottlenecks in Costa Rica and Ireland manufacturing nodes reinforce margin protection for incumbents with established workforce pipelines.
For Market Incumbents: Deploy captive extrusion capacity additions in Costa Rica to offset polymer processing bottlenecks. Secure exclusive supply agreements with Baden-Württemberg nitinol wire specialists before EU MDR re-certification waves disrupt supplier relationships. Channel control through direct hospital system partnerships in Texas and California insulates against GPO pricing compression. R&D prioritization on next-generation pressure-sensing guidewire platforms defends against optical coherence tomography substitution threats. For New Entrants and Emerging Players: Launch via private-label manufacturing partnerships with Hyderabad contract extrusion facilities to bypass capital-intensive captive infrastructure requirements. India's tier-2 city electrophysiology lab buildout in Maharashtra and Karnataka offers the most penetrable geographic entry point. Neurovascular diagnostic catheter applications in Japan and Germany present white-space expansion corridors with less entrenched incumbent positioning. Reimbursement strategy development must precede commercial launch given payer scrutiny of catheter-based diagnostics against CT angiography alternatives. For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with established EU MDR notified body relationships and ISO 13485 quality infrastructure. Long-term viability hinges on backward integration depth into polymer processing rather than pure assembly capabilities. Acquisition targets should demonstrate existing electrophysiology catheter portfolios with aging-related arrhythmia volume exposure. PMDA local clinical testing timeline compression serves as the critical inflection signal for Japanese market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerated clearance timelines for predicate-based diagnostic catheter platforms reduce time-to-revenue in United States markets. |
| CE Marking Under EU MDR | Enhanced clinical evidence requirements for Class III devices filter out undercapitalized competitors from European hospital procurement. |
| Hospital System Partnership | Direct agreements with Texas and California integrated delivery networks displace distributor intermediaries and secure volume commitments. |
| Software Companion Development | Electroanatomical mapping integration with 3D imaging platforms differentiates catheter portfolios in German cardiology centers. |
| Reimbursement Strategy | CMS outpatient procedure coding alignment determines commercial viability against non-invasive cardiac imaging substitutes. |
Research Methodology
FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement database extracts formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with electrophysiology laboratory directors, biomedical engineering managers at German cardiology centers, GPO contracts administrators, and polymer extrusion operations heads in Costa Rica validated demand assumptions and supply constraints. Bottom-up catheter unit demand modeling triangulated against top-down healthcare expenditure allocation trends across the analysis window.
Historical trendline analysis of electrophysiology procedure volumes, imaging catheter placement rates, and regulatory submission timelines anchored the forecast framework. Segmentation modeling spanned product type, end-user facility tier, technology modality, and application anatomy across the projection horizon. CAGR derivation incorporated procedure penetration benchmarks, reimbursement trajectory assumptions, and supply capacity expansion constraints specific to polymer processing workforce availability.
EU MDR implementation delays, PMDA local clinical testing timeline extensions, and nitinol supply disruptions are the dominant revision risks warranting forecast sensitivity analysis. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Spinal Needles Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Europe C-Arms Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Pacemakers Market
Medical Devices
Spinal Traction Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
AI-enabled Medical Devices Market