
 Wireless Surgical Cameras Market | 2026-2036
Wireless Surgical Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Surgical Cameras Market Analytics
CMOS image sensors are displacing legacy CCD architectures and is broadening the addressable market for cost-optimized wireless surgical cameras. Stryker leverages in-house sensor partnerships to sustain premium positioning across integrated operating rooms. Sunoptic Technologies specializes in fiber-optic wireless bridges that dominate niche neurosurgical applications where signal fidelity commands priority.
Wireless surgical cameras are battery-powered or tetherless visualization devices transmitting real-time video from the sterile field to display systems via radio-frequency or optical links, typically operating at 1080p to 4K resolution with latency below 150 milliseconds for surgical precision. Their primary purpose is eliminating cable clutter in operating theaters while maintaining uncompromised image quality for minimally invasive procedures. Integrated systems capture the largest margin pool as hospitals prioritize seamless connectivity with existing surgical platforms, while 3D cameras represent the fastest-expanding technology segment fueled by depth-perception requirements in robotic-assisted surgery. Handheld cameras remain the most mature product category with stable replacement cycles driving recurring revenue.
FDA 510(k) pathways and EU MDR conformity assessments govern wireless surgical camera commercialization, with electromagnetic compatibility and biocompatibility standards determining market access timelines in the United States and European Union. Japan's PMDA enforces additional radio equipment certification that shapes product design for Asia-Pacific distribution. Stakeholders must monitor evolving cybersecurity mandates for wireless medical devices as regulators tighten data transmission protocols across major markets.
Market Dynamics
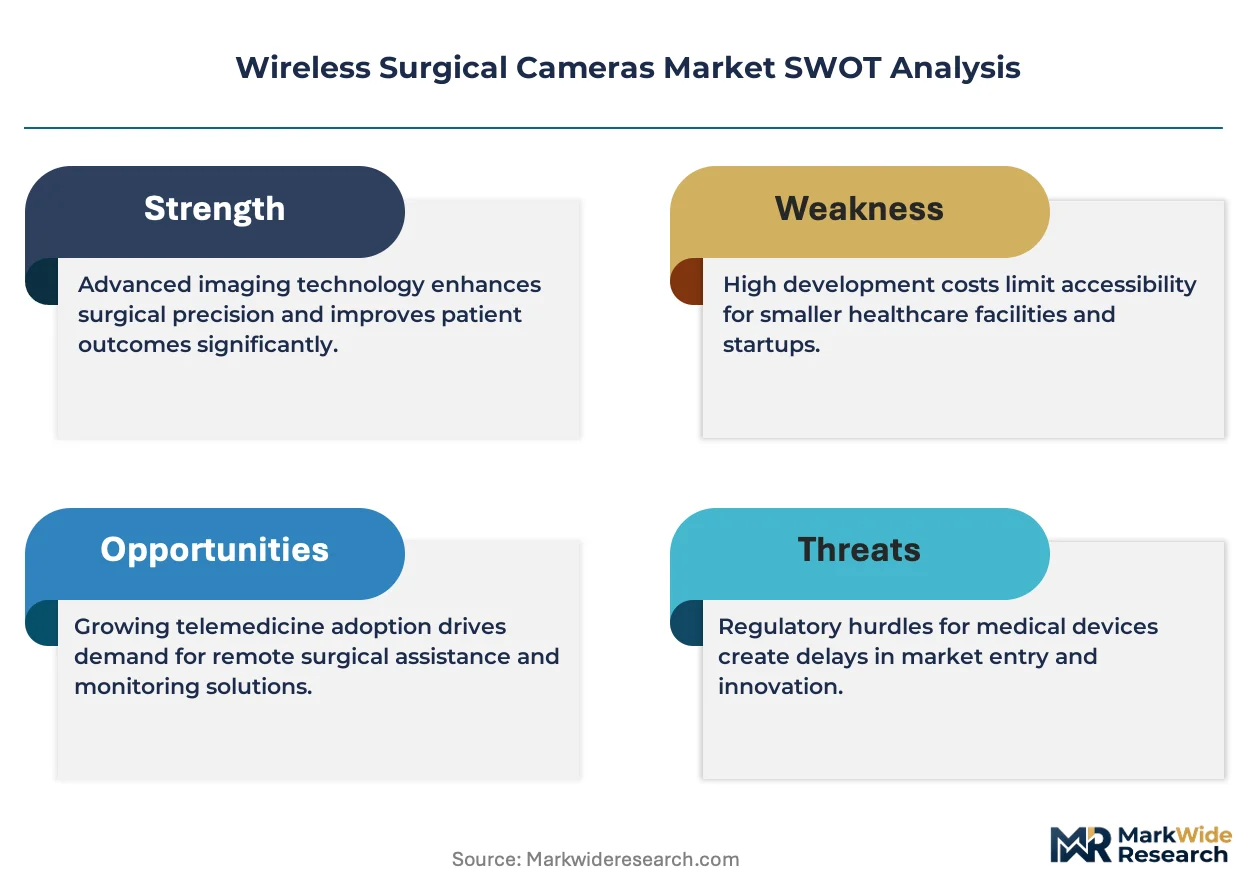
CMOS sensor migration is compressing component costs while elevating image quality thresholds, forcing manufacturers to recalibrate value propositions around wireless latency reduction rather than resolution alone.
Growth Catalysts
- FDA 510(k) streamlining:Expedited clearance pathways for predicate wireless devices are shortening commercialization timelines for minimally invasive visualization systems in the United States.
- Robotic surgery suites:Tetherless camera demand is accelerating in da Vinci and competing robotic platforms where cable management disrupts sterile field workflow.
- Germany's hospital modernization:Federal infrastructure programs are funding wireless OR upgrades across university medical centers and municipal hospital networks.
Market Restraints
- CMOS sensor supply concentration:Sony and Samsung dominate high-performance medical-grade sensor fabrication, creating single-source vulnerability for camera OEMs.
- EU MDR conformity costs:Expanded clinical evidence requirements for wireless Class IIa devices are elevating regulatory compliance expenditures for European market entry.
- Latency floor constraints:Radio-frequency transmission physics impose hard limits below 50 milliseconds, constraining real-time applications requiring sub-frame synchronization.
Strategic Opportunities
- India's surgical infrastructure:Government PLI scheme incentives for medical device manufacturing are attracting wireless camera assembly investments for domestic and export markets.
- Ambulatory surgical centers:Cost-optimized wireless systems are penetrating outpatient facilities previously excluded from integrated OR capital budgets.
- AI-assisted visualization convergence:Edge-computing integration with wireless cameras enables real-time tissue classification without proprietary endoscope-tower dependencies.
Industry Challenges
- Cybersecurity certification complexity:FDA's evolving guidance on wireless medical device data integrity is extending premarket documentation timelines.
- Legacy tower integration:Proprietary video formats from Stryker, Karl Storz, and Olympus require custom protocol bridges, elevating system engineering costs.
- RF interference management:Dense electromagnetic environments in hybrid operating rooms demand specialized shielding expertise scarce among traditional surgical device engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Surgical Cameras Market |
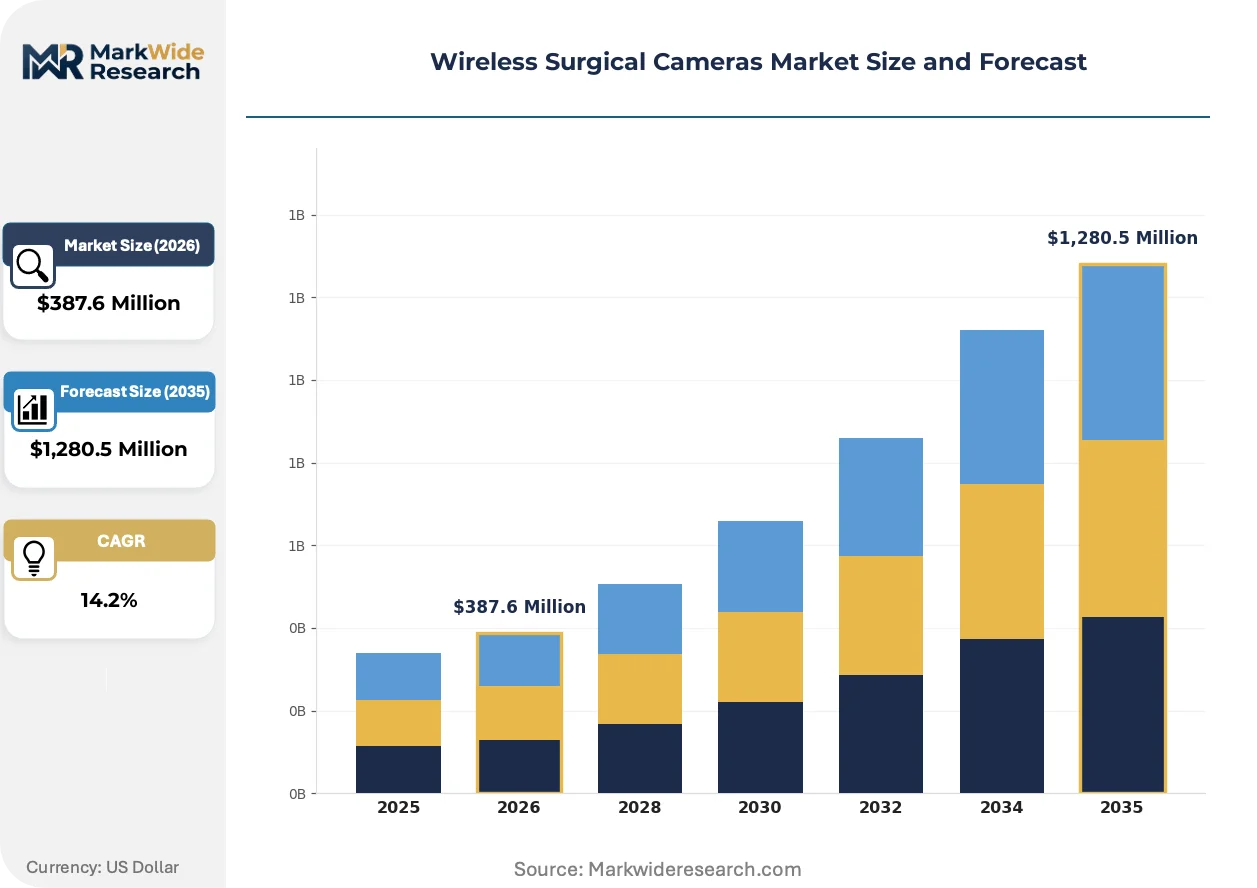
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Integrated Systems, HD Cameras, 3D Cameras End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Infrared, Wi-Fi, Bluetooth, Fiber Optics Application: General Surgery, Orthopedic Surgery, Cardiac Surgery, Neurosurgery |
| Companies Covered | Firefly Global, Xenosys, Sunoptic Technologies, Hill-Rom Services, Steris, Faspro Systems, North Southern Electronics, Lazurite, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Surgical Cameras Market Evolving Landscape
Wireless surgical cameras are undergoing architectural transformation as video processing migrates from centralized towers to edge-capable endpoints, compressing infrastructure requirements while expanding deployment flexibility.
CMOS backside-illuminated sensors are decentralizing image signal processing from external camera control units to within-sterile-field devices. Academic medical centers in Boston and Rotterdam are piloting fully untethered 4K systems eliminating fiber-optic umbilicals. This topology is compressing OR turnover time by eliminating cable sterilization cycles and reducing setup complexity for circulating nurses.
EU MDR's enhanced post-market surveillance requirements are mandating wireless transmission logging for traceability. German notified bodies are enforcing electromagnetic compatibility documentation beyond prior MEDDEV guidance. High-resolution 3D camera systems face extended conformity assessment timelines as clinical evidence standards tighten for depth-perception claims in robotic-assisted procedures.
Hospital procurement committees are unbundling camera hardware from long-term service contracts previously locked to single-vendor ecosystems. Integrated delivery networks in Texas and California are negotiating multi-source wireless visualization agreements. This purchasing pattern is most pronounced among IDNs operating twenty-plus surgical suites where vendor redundancy reduces operational risk.
Wireless Surgical Cameras Market Segmentation
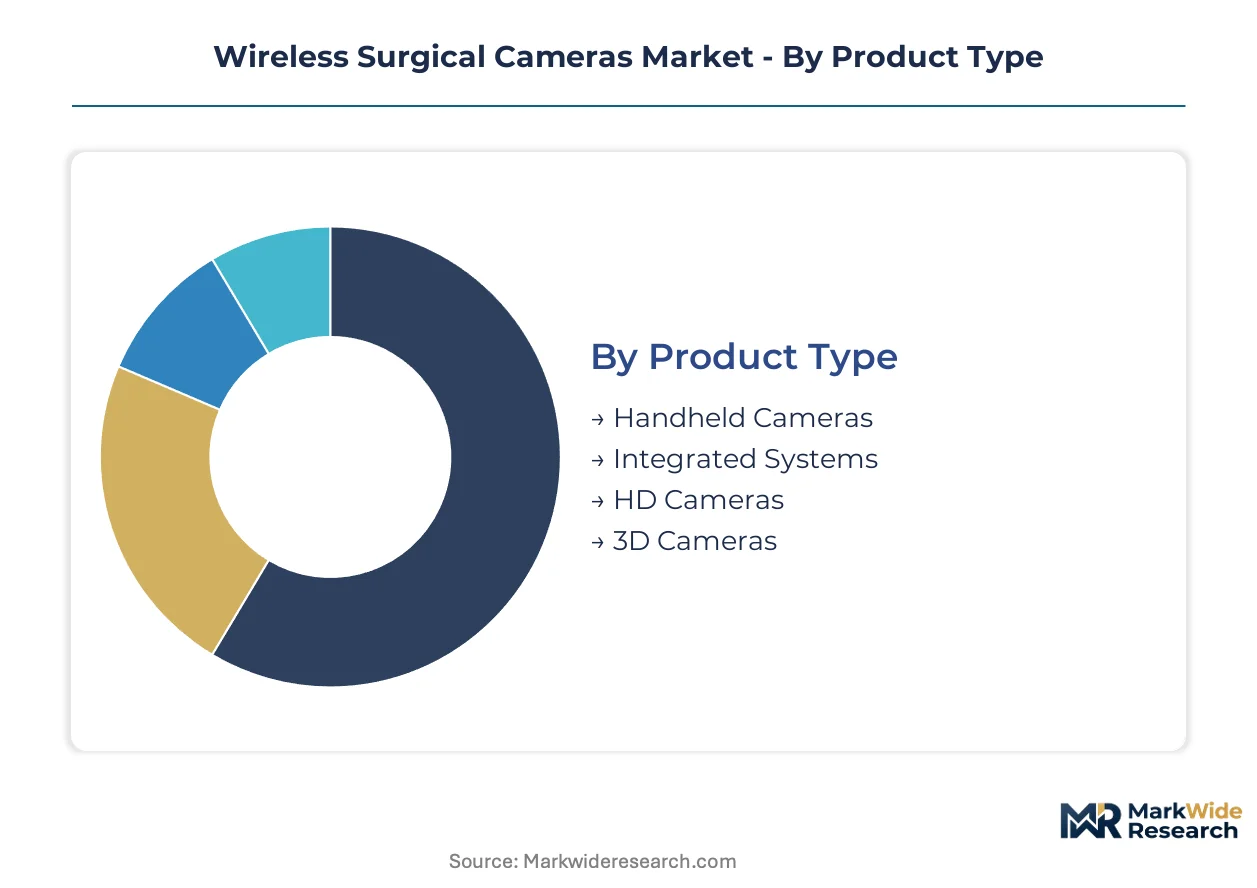
Wireless surgical camera procurement diverges sharply by facility infrastructure, procedure complexity, and integration requirements. Understanding these fault lines reveals where manufacturers must tailor performance specifications versus cost optimization.
Product Type:
Buyers differentiate primarily by capital budget tier and OR integration depth rather than resolution specifications alone.
- Integrated Systems:These comprise camera heads, processing units, and display towers engineered for seamless vendor-ecosystem compatibility. Demand concentrates in Germany's university medical centers where federal modernization programs fund complete OR renovations requiring centralized control architectures.
- 3D Cameras:Stereoscopic imaging systems deliver depth perception through dual-sensor arrays synchronized for robotic-assisted visualization. Adoption is accelerating fastest in Japan's metropolitan surgical centers where da Vinci platform density drives tetherless depth-capable alternatives.
- Handheld Cameras:Portable single-operator devices with battery-powered transmission dominate ambulatory replacement cycles.
- HD Cameras:1080p systems serve cost-constrained facilities prioritizing functional adequacy over 4K fidelity.
Integrated systems lead volumes today; 3D cameras are gaining share fastest.
End User:
Volume concentration and purchasing authority split between capital-rich hospital networks and agile outpatient operators.
- Hospitals:Multi-suite operators with dedicated biomedical engineering staff prioritize electromagnetic compatibility certification and legacy tower interoperability. Germany's municipal hospital networks represent the densest demand cluster for fully integrated wireless deployments.
- Ambulatory Surgical Centers:Freestanding facilities with compressed procedure schedules favor rapid-setup handheld systems eliminating sterilization bottlenecks. Texas and California IDNs are unbundling procurement from single-vendor service contracts across twenty-plus ASC portfolios.
- Clinics:Limited-procedure settings drive entry-level HD camera demand with minimal integration requirements.
- Research Institutions:Academic medical centers in Boston and Rotterdam pilot experimental 4K untethered topologies for protocol development.
Hospitals dominate absolute spending; ambulatory surgical centers show the steepest expansion trajectory.
Technology:
Transmission protocol selection hinges on latency tolerance, electromagnetic environment density, and sterile field mobility requirements.
- Wi-Fi:Radio-frequency systems operating in medical-grade spectrum bands enable real-time 4K streaming with sub-150 millisecond latency. FDA 510(k) clearance pathways for predicate Wi-Fi devices are accelerating commercialization timelines for US manufacturers.
- Fiber Optics:Optical transmission eliminates electromagnetic interference in hybrid OR environments where RF congestion from imaging, navigation, and robotic systems creates signal integrity challenges. Sunoptic Technologies dominates neurosurgical niche applications where fidelity commands absolute priority.
- Infrared:Short-range optical links serve specialized low-latency applications with limited mobility requirements.
- Bluetooth:Reduced-power protocols accommodate auxiliary control functions rather than primary video transmission.
Wi-Fi leads installed base today; fiber optics commands premium positioning in interference-sensitive settings.
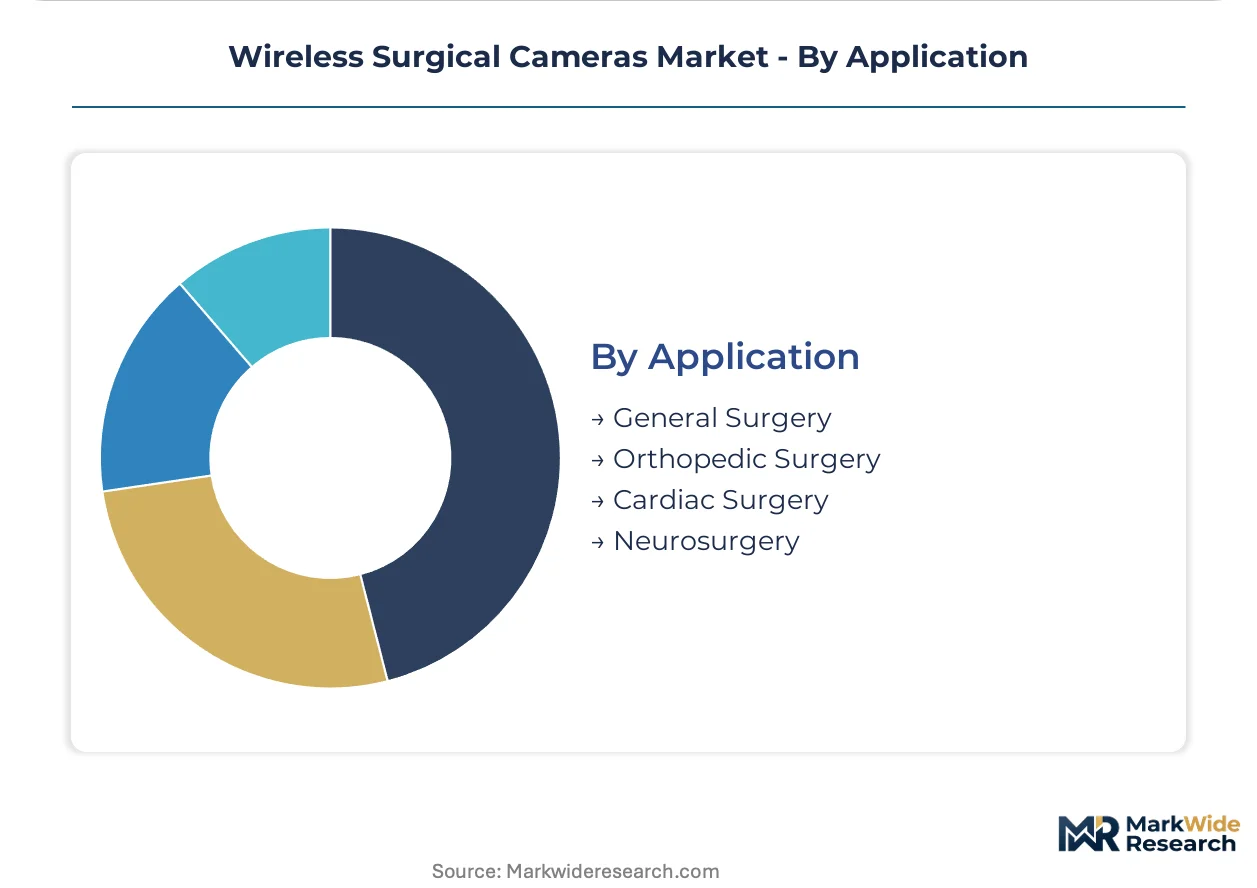
Application:
Procedure-specific visualization demands range from broad anatomical survey to sub-millimeter neural structure identification.
- General Surgery:Laparoscopic and open procedures requiring adaptable camera positioning across diverse anatomical targets. US hospital procurement committees prioritize wireless systems reducing circulating nurse setup burden across high-volume abdominal cases.
- Neurosurgery:Cranial and spinal interventions demanding maximum signal fidelity with zero electromagnetic artifact. Japan's PMDA enforces additional radio equipment certification shaping product design for Asia-Pacific distribution in this segment.
- Orthopedic Surgery:Arthroscopic and joint replacement visualization favors durable handheld formats with rapid sterilization turnaround.
- Cardiac Surgery:Sternotomy and minimally invasive cardiac procedures require specialized 3D depth perception for valvular and coronary work.
General surgery leads procedure volume today; neurosurgery commands the highest per-unit system pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university medical centers anchor demand concentration for wireless surgical camera systems, with federal infrastructure programs funding OR modernization across municipal hospital networks and academic clusters in Berlin, Munich, and Hamburg.
United States
FDA 510(k) streamlining for predicate wireless devices accelerates commercialization timelines for visualization system manufacturers. Hospital procurement committees in Texas and California unbundle camera hardware from long-term vendor service contracts. Academic medical centers in Boston pilot fully untethered 4K topologies for protocol development.
Germany
Federal hospital modernization programs fund integrated wireless OR upgrades across university medical centers and municipal networks. EU MDR conformity assessments with expanded clinical evidence requirements govern Class IIa device market access. Notified bodies in Berlin and Munich enforce electromagnetic compatibility documentation beyond prior MEDDEV guidance.
Japan
Metropolitan surgical centers in Tokyo and Osaka drive tetherless depth-capable camera demand for da Vinci platform density. PMDA enforces additional radio equipment certification shaping product design for Asia-Pacific distribution. Kanto region hospitals prioritize 3D stereoscopic systems for robotic-assisted visualization.
India
Government PLI scheme incentives attract wireless camera assembly investments for domestic and export medical device markets. CDSCO regulatory pathways govern commercialization timelines for imported and locally manufactured visualization systems. Manufacturing clusters in Maharashtra and Karnataka expand surgical infrastructure component production.
United Kingdom
NHS procurement frameworks prioritize electromagnetic compatibility certification and legacy tower interoperability for multi-suite hospital operators. MHRA post-Brexit device regulations align with EU MDR standards while maintaining independent conformity assessment pathways. London and Southeast England academic hospitals evaluate edge-computing camera integration for AI-assisted visualization.
Wireless Surgical Cameras Market Competitive Landscape
Global majors compete with regional champions across regulatory certification depth and legacy system integration capability. The vendor base organizes around three tiers: integrated surgical platform conglomerates, specialized wireless transmission technology developers, and cost-optimized component assemblers. Strategic differentiation concentrates on FDA 510(k) clearance velocity, proprietary protocol bridge engineering, and electromagnetic interference shielding expertise. Dominant competitive moves include backward integration into CMOS sensor partnerships and geographic expansion through distributor network establishment.
Within the integrated platform tier, Stryker and Steris occupy positions emphasizing seamless vendor-ecosystem compatibility and centralized control architectures. Sunoptic Technologies exemplifies the specialized transmission archetype through fiber-optic wireless bridge dominance in interference-sensitive applications. Hill-Rom Services represents the diversified medical technology conglomerate model with wireless visualization as one component within broader perioperative equipment portfolios.
| Leading Market Players |
|---|
| Firefly Global |
| Xenosys |
| Sunoptic Technologies |
| Hill-Rom Services |
| Steris |
| Faspro Systems |
| North Southern Electronics |
| Lazurite |
| Stryker |
| Others |
Value Network & Pricing Analysis
CMOS sensor wafer costs from Sony and Samsung fabs flow downstream through three pricing tiers, with medical-grade certification premiums separating integrated system vendors from handheld camera assemblers serving cost-constrained ambulatory centers.
Pricing Analysis
Input-cost pass-through from concentrated CMOS suppliers elevates tier separation between FDA-cleared integrated systems and entry-level HD devices. Price differentiation rests on electromagnetic compatibility certification grade and legacy tower interoperability depth. Pricing pressure stems from EU MDR conformity cost inflation extending European market access timelines. Ambulatory surgical centers exhibit highest price sensitivity, while German university medical centers absorb premium positioning for complete OR renovation programs.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-supplier qualification for CMOS sensors and radio-frequency transmission modules. Manufacturing concentrates in Japan, South Korea, and Germany for medical-grade sensor fabrication and precision optical component finishing. Raw material dependencies include silicon wafers, rare-earth magnet materials for motor assemblies, and medical-grade polymer housings. Single-source vulnerability in high-performance CMOS fabrication creates structural risk. Distribution runs through authorized surgical device distributors with biomedical engineering support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless surgical cameras constitute a stable compounder anchored by irreversible operating room modernization cycles across developed healthcare infrastructure.
For Market Incumbents: Cement ecosystem lock-in through proprietary protocol bridge engineering that deepens integration with Stryker, Karl Storz, and Olympus legacy towers. Prioritize backward integration into CMOS sensor partnerships to neutralize Sony and Samsung supply concentration vulnerability. Defend margin position by embedding cybersecurity certification capabilities ahead of FDA's evolving wireless medical device data integrity guidance. For New Entrants and Emerging Players: Enter via India's government PLI scheme manufacturing incentives to establish cost-optimized assembly for domestic and export medical device markets. Target ambulatory surgical centers in Texas and California IDNs where procurement unbundling from single-vendor service contracts creates white-space access. Deploy rapid-setup handheld formats with minimal sterilization bottlenecks as the primary go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where electromagnetic interference shielding expertise scarcity intersects with FDA 510(k) clearance velocity requirements. Long-term viability favors platforms with demonstrated hospital system partnership depth and multi-source wireless visualization contract traction. Target acquisition archetype: specialized fiber-optic wireless bridge developers with neurosurgical niche dominance. Signal to watch: CDSCO regulatory pathway acceleration for India-manufactured devices serving Asia-Pacific distribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened clearance timelines for predicate wireless devices unlock US hospital procurement cycles. |
| EU MDR Conformity Pathway Investment | Expanded clinical evidence capabilities secure Class IIa device market access across German and UK networks. |
| Hospital System Partnership | Integrated delivery network agreements in Texas and California reduce vendor redundancy operational risk. |
| Software Companion Development | Edge-computing integration enables AI-assisted tissue classification without proprietary endoscope-tower dependencies. |
| Reimbursement Strategy | Coding alignment with minimally invasive procedure categories accelerates capital budget approval velocity. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineering director consultations, regulatory affairs lead discussions, and GPO contracts manager briefings — were reconciled with FDA 510(k) filing databases, EU MDR notified body documentation, and hospital equipment procurement records. Secondary validation drew from PMDA radio equipment certification filings, CDSCO device registration data, and academic medical center pilot program disclosures. Bottom-up unit demand modeling and top-down healthcare capital expenditure analysis were triangulated to produce segmentation outputs.
Data-stream reconciliation across product type, end user facility tier, transmission technology protocol, and surgical application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle analysis and robotic surgery suite expansion trajectories. Forecast inputs incorporated electromagnetic compatibility certification timeline distributions and CMOS sensor supply allocation patterns from Japanese and South Korean fabrication facilities.
Inputs from hospital procurement databases and regulatory filing repositories were available through the study window; gaps in real-time ASC capital budget commitment data introduce uncertainty bands around ambulatory surgical center penetration assumptions. Deviation in FDA cybersecurity guidance finalization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Airway Management Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Gum Grafting Market