
 Digital Radiology Devices Market | 2026-2036
Digital Radiology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radiology Devices Market Analysis
Germany is reshaping European supply dynamics for digital radiology through Siemens Healthineers' concentrated manufacturing and R&D footprint near Erlangen. GE Healthcare leverages deep vertical integration in detector manufacturing to sustain margin control across CT and MRI modalities. Fujifilm Holdings Corporation anchors Asia-Pacific competitiveness through specialized digital X-ray panel production, while Koninklijke Philips competes on hybrid imaging architectures that merge functional and anatomical data streams.
Digital radiology devices encompass ionizing and non-ionizing imaging systems that convert raw energy signals into diagnostic images through digital flat-panel detectors or computed radiography plates, with spatial resolution typically ranging from 2.5 to 10 line pairs per millimeter depending on clinical application. These systems serve primarily to replace analog film workflows, enable teleradiology distribution, and support AI-assisted diagnostic interpretation across hospital networks. CT scanners occupy the largest installed base among product type segments, reflecting their indispensability in emergency and oncology workflows, while 3D imaging technology represents the fastest-expanding capability dimension as surgical planning and interventional guidance applications multiply. DR systems command premium pricing over CR systems due to direct-capture efficiency and lower per-exposure operational costs, concentrating margin pools with vendors that manufacture detectors in-house.
The FDA regulates digital radiology devices under 21 CFR Part 1020 performance standards for diagnostic X-ray systems, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-driven imaging modalities entering European markets. Japan's PMDA accelerates approval timelines for AI-augmented radiology tools through its Sakigake fast-track designation, reshaping competitive timelines for algorithm developers. Stakeholders must monitor evolving cybersecurity guidance from national regulators as network-connected imaging devices face escalating ransomware exposure and patient data breach liability.
Market Dynamics
Hospital consolidation across Germany is compressing vendor negotiation cycles and favoring enterprise-scale imaging networks over point-of-sale equipment transactions. Siemens Healthineers' concentrated manufacturing footprint near Erlangen amplifies this concentration effect, as bulk procurement mandates from merged hospital groups force smaller radiology device vendors into subcontracting relationships or exit.
Growth Catalysts
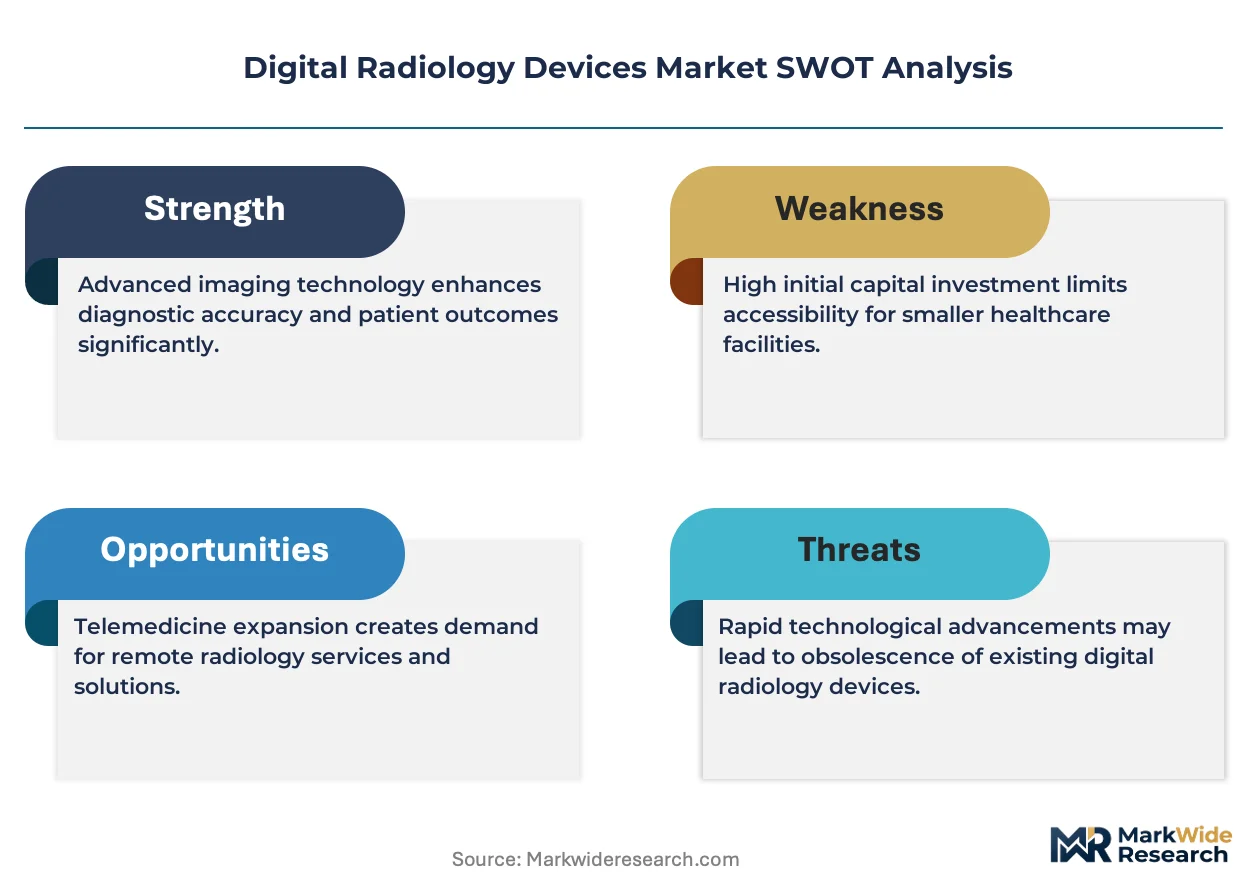
- FDA 510(k) Pathway:The FDA's streamlined clearance for software-as-a-medical-device accelerates AI-integrated radiology platforms into commercial deployment, reducing time-to-revenue for algorithm developers.
- Film Replacement Mandates:US hospitals face operational pressure to retire legacy film-based systems, creating replacement demand for digital flat-panel detectors and computed radiography infrastructure.
- Detector Manufacturing:In-house production of digital X-ray panels by specialized Asian manufacturers compresses unit costs and expands addressable volume in price-sensitive clinical segments.
Market Restraints
- Raw Material Concentration:Selenium and cesium iodide supply chains concentrate in East Asian refining operations, exposing detector manufacturers to input volatility and geopolitical disruption.
- EU MDR Compliance Burden:The EU Medical Device Regulation imposes stricter clinical evidence requirements for software-driven imaging modalities, extending approval timelines and elevating regulatory capital requirements for European market entry.
- Extended Equipment Lifecycles:CT and MRI systems operate reliably for 10-15 years with refurbishment options, compressing replacement frequency and limiting annual addressable unit volume.
Strategic Opportunities
- Interventional Radiology Expansion:Hybrid imaging architectures that merge functional and anatomical data streams open surgical planning and real-time guidance applications in oncology and cardiology workflows.
- India Diagnostic Infrastructure:Underpenetrated tier-2 and tier-3 cities present white-space demand for portable digital X-ray systems as government health schemes expand screening coverage.
- AI-Augmented Teleradiology:Algorithm-assisted image interpretation enables asynchronous diagnostic workflows, allowing radiology groups to serve rural and remote patient populations without on-site specialist presence.
Industry Challenges
- Cybersecurity Compliance:Network-connected imaging devices face escalating ransomware exposure, forcing vendors to integrate FDA cybersecurity guidance into product development cycles and post-market surveillance.
- Legacy System Interoperability:Hospital IT environments retain heterogeneous PACS architectures from multiple vendors, complicating seamless integration of new digital radiology platforms and elevating deployment costs.
- Specialized Service Engineering:Detector calibration, tube replacement, and AI algorithm maintenance require field technicians with cross-disciplinary competencies in hardware, software, and clinical workflow optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radiology Devices Market |
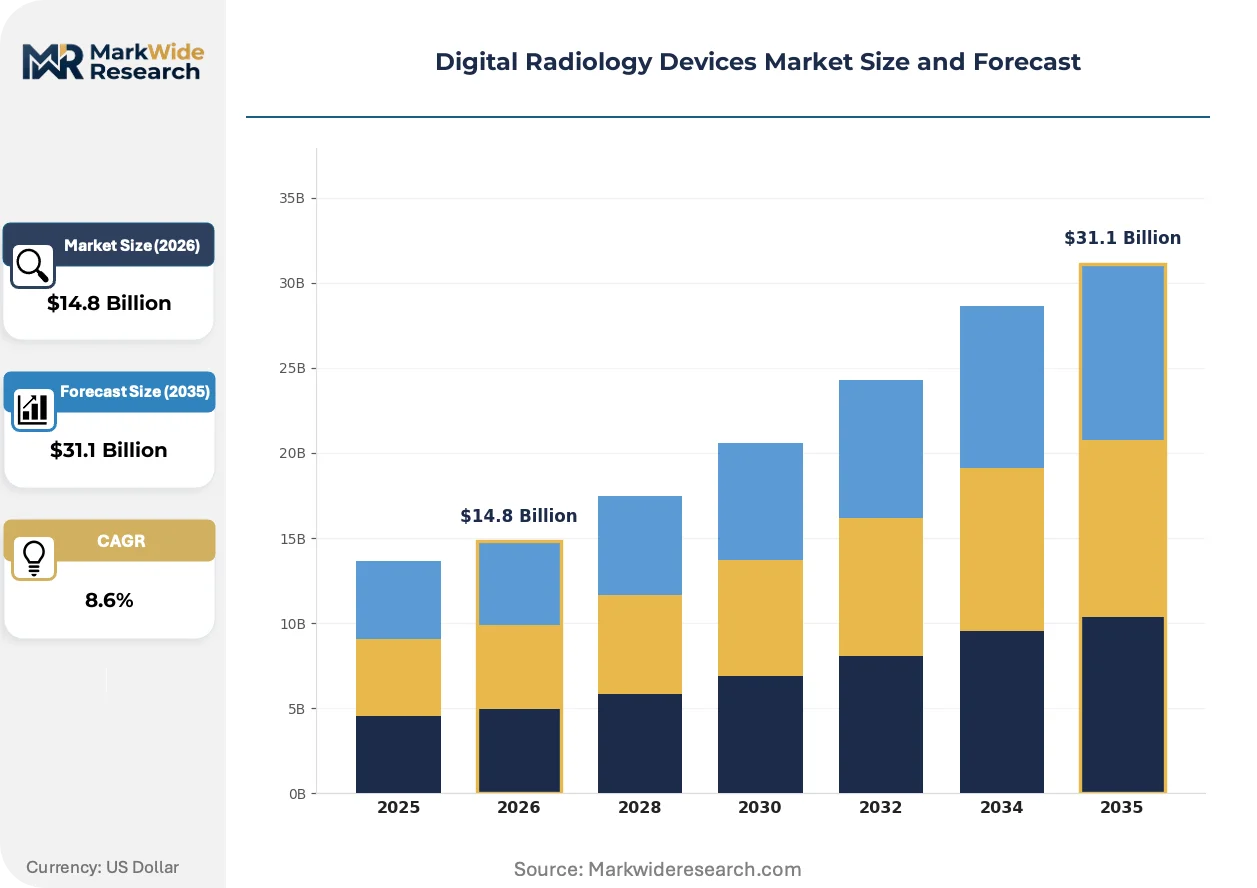
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, MRI Scanners, CT Scanners, Ultrasound Machines End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Facilities Technology: CR Systems, DR Systems, Hybrid Imaging, 3D Imaging Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Koninklijke Philips, Carestream Health, Agfa-Gevaert Group, Shimadzu Corporation, Varex Imaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radiology Devices Market Emerging Trajectories
Photon-counting detector technology is restructuring competitive positioning in CT imaging by enabling spectral resolution at lower radiation doses. Three convergent developments are compressing traditional technology adoption cycles and reshaping vendor R&D priorities.
Photon-counting CT is migrating from research installations into commercial emergency and oncology workflows. Academic medical centers in the United States and Germany have validated dose-reduction protocols for pediatric and repeat-scan populations. This migration from energy-integrating detectors compresses the addressable market for conventional CT platforms and forces incumbent vendors to accelerate detector material transitions or cede premium segment share.
Japan's PMDA Sakigake fast-track designation is compressing approval timelines for AI-augmented radiology tools by 50% relative to standard review pathways. Algorithm developers are restructuring clinical trial designs to prioritize Japanese regulatory submission, creating a competitive sequencing advantage for early Sakigake recipients. European developers are responding by establishing Tokyo-based regulatory affairs capabilities to maintain parity in approval velocity.
Radiology group purchasing organizations are unbundling equipment procurement from long-term service contracts, forcing vendors to price hardware and maintenance as separable line items. Independent imaging centers in the United States are driving this disintermediation, leveraging third-party service providers for detector replacement and tube refurbishment. This unbundling compresses vendor service margin pools and elevates price transparency in competitive bidding processes.
Digital Radiology Devices Market Segmentation
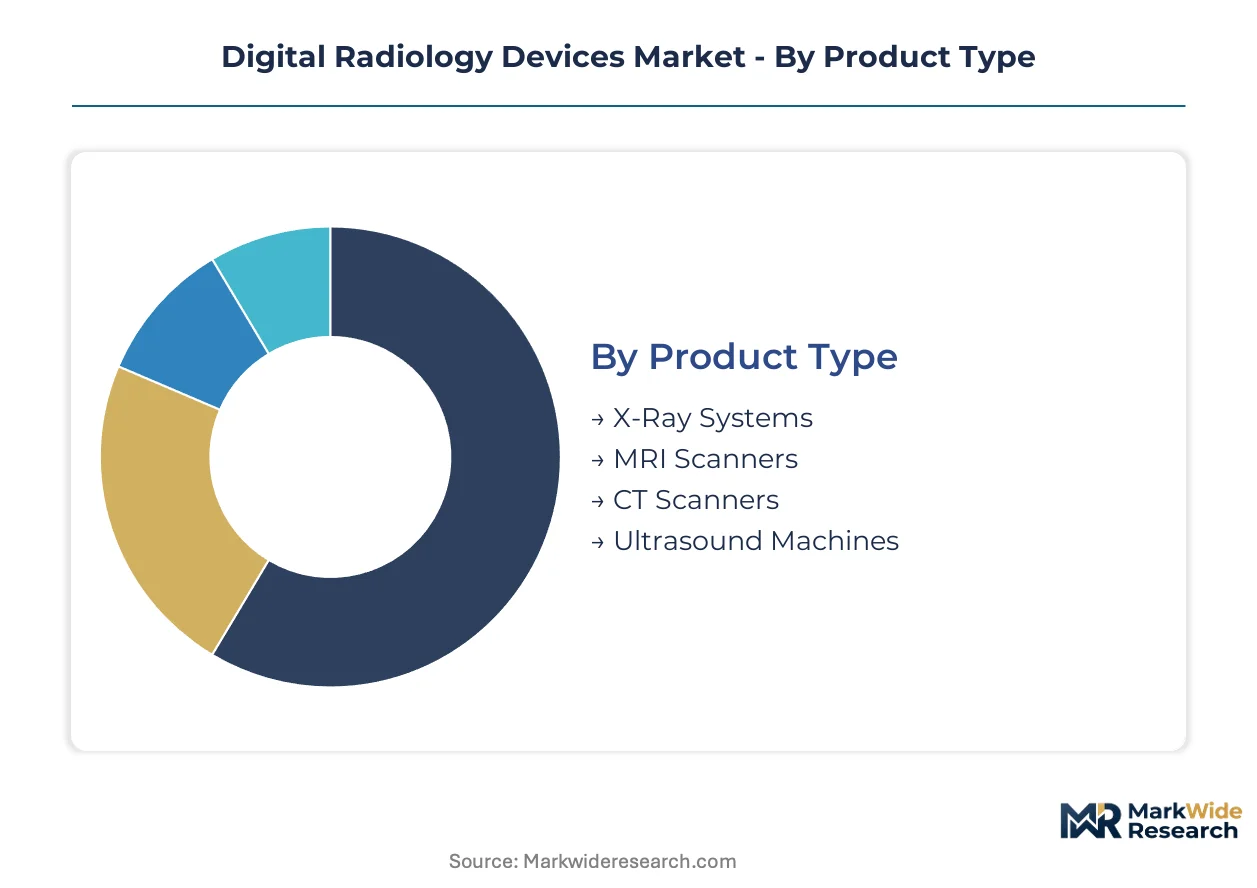
Segmentation in digital radiology reveals divergent replacement cycles and margin structures across hardware categories. Equipment lifecycle variation—from 5-year portable X-ray turnover to 15-year MRI refurbishment cycles—shapes vendor cash flow predictability and service contract economics.
Product Type:
Replacement velocity varies dramatically: CT scanners turn over fastest in high-throughput emergency settings, while MRI systems persist longest with field upgrades.
- X-Ray Systems:Digital flat-panel detectors using cesium iodide scintillators deliver 2.5-10 lp/mm spatial resolution. Demand concentrates in US outpatient clinics replacing legacy film processors, driven by teleradiology mandates and AI integration requirements.
- CT Scanners:Energy-integrating detectors face displacement by photon-counting architectures that enable spectral resolution at reduced dose. German hospital consolidation accelerates bulk procurement of 256-slice platforms for oncology and trauma workflows.
- MRI Scanners:Superconducting magnet systems with 1.5T to 3T field strength dominate installed base. Refurbishment options extend operational life to 15 years, compressing replacement frequency in budget-constrained hospital systems.
- Ultrasound Machines:Portable cart-based and handheld point-of-care variants serve interventional guidance and emergency triage. Indian diagnostic infrastructure expansion drives volume in tier-2 cities under government health schemes.
CT scanners anchor the volume base while photon-counting platforms gain share at the steepest rate.
End User:
Procurement scale and decision velocity separate institutional buyers, with consolidated hospital networks demanding enterprise-wide standardization.
- Hospitals:Acute care facilities with 500+ beds operate integrated PACS networks requiring seamless modality interoperability. FDA cybersecurity guidance for network-connected devices elevates vendor compliance costs in US installations.
- Diagnostic Centers:Independent imaging facilities unbundle equipment from service contracts, leveraging third-party detector replacement. Radiology group purchasing organizations drive price transparency through competitive bidding.
- Outpatient Clinics:Limited-space environments favor compact digital X-ray systems with wireless detector panels. Japan's PMDA Sakigake fast-track accelerates AI-augmented tool deployment in high-volume screening settings.
- Research Facilities:Academic medical centers validate dose-reduction protocols and spectral CT applications. Photon-counting detector trials in US and German institutions compress commercialization timelines.
Hospitals dominate capital deployment while diagnostic centers expand most quickly through unbundled procurement models.
Technology:
Cost structure and workflow efficiency differentiate capture modalities, with direct-conapture systems commanding premium positioning.
- CR Systems:Computed radiography plates using photostimulable phosphor storage require laser scanning and cassette handling. Price-sensitive clinical segments in developing markets retain CR infrastructure for capital-constrained facilities.
- DR Systems:Direct-capture flat-panel detectors eliminate cassette workflow, reducing per-exposure labor and retake rates. In-house detector manufacturing by Asian suppliers compresses unit costs and expands addressable volume.
- Hybrid Imaging:PET-CT and PET-MRI architectures merge functional and anatomical data streams for surgical planning. Interventional oncology and cardiology workflows drive adoption in German consolidated hospital networks.
- 3D Imaging:Cone-beam CT and tomosynthesis enable volumetric reconstruction for orthopedic and dental applications. Surgical guidance and implant planning multiply use cases beyond diagnostic interpretation.
DR systems command the revenue concentration while 3D imaging climbs the fastest on interventional application expansion.
Application:
Clinical workflow urgency and reimbursement density shape modality selection across therapeutic areas.
- Oncology:Staging and treatment monitoring require CT and PET-CT for lesion characterization and response assessment. Photon-counting spectral resolution enables iodine quantification for therapy evaluation.
- Orthopedics:Weight-bearing digital X-ray and 3D tomosynthesis guide implant positioning and fracture reduction. Outpatient surgical centers drive demand for compact systems with rapid image acquisition.
- Cardiology:Coronary CT angiography and cardiac MRI assess vascular patency and myocardial viability. Emergency department chest pain protocols accelerate CT turnover in high-throughput settings.
- Neurology:MRI diffusion and perfusion sequences evaluate stroke and tumor pathology. AI-augmented detection of intracranial hemorrhage gains FDA 510(k) clearance for triage prioritization.
Oncology anchors installed base value while cardiology applications expand most rapidly on emergency protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector manufacturing concentrates in East Asian refining corridors and German precision engineering clusters, creating dual supply poles that shape procurement economics across radiology modalities.
United States
Hospital consolidation drives enterprise-wide imaging network procurement, with acute care facilities replacing legacy film processors under teleradiology mandates. FDA 510(k) clearance pathways accelerate AI-integrated radiology platforms into commercial deployment. Boston and Minneapolis medical technology corridors anchor detector R&D and algorithm development clusters.
Germany
Hospital merger activity compresses vendor negotiation cycles and favors bulk procurement of 256-slice CT platforms for oncology workflows. EU Medical Device Regulation imposes stricter clinical evidence requirements for software-driven imaging modalities entering European markets. The Erlangen manufacturing corridor concentrates Siemens Healthineers production and amplifies concentration effects from merged hospital group mandates.
Japan
PMDA Sakigake fast-track designation compresses approval timelines for AI-augmented radiology tools by fifty percent relative to standard review pathways. Algorithm developers restructure clinical trial designs to prioritize Japanese regulatory submission. Tokyo-based regulatory affairs capabilities expand as European developers establish local presence to maintain approval velocity parity.
China
Government health scheme expansion drives demand for portable digital X-ray systems in tier-two and tier-three cities. NMPA regulatory frameworks govern diagnostic X-ray system performance standards and software-as-medical-device classifications. Yangtze River Delta manufacturing clusters scale cesium iodide scintillator production for cost-sensitive clinical segments.
India
Underpenetrated diagnostic infrastructure in secondary cities presents white-space demand for compact digital radiology platforms. CDSCO medical device regulations establish import and manufacturing compliance pathways for imaging equipment. Maharashtra and Karnataka hospital networks expand screening coverage through government-funded health initiatives.
Digital Radiology Devices Market Vendor Landscape
Vertically integrated conglomerates and specialized detector manufacturers split the market into distinct capability tiers. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates with captive detector production, standalone imaging equipment specialists, and component suppliers selling into OEM channels. Competitive moves concentrate on M&A for AI algorithm portfolios and strategic partnerships for photon-counting detector material transitions.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers exemplify the vertically integrated archetype with in-house detector manufacturing capabilities. Koninklijke Philips occupies a position within the hybrid imaging specialist tier. These three entities anchor the premium equipment segment through control over critical detector supply chains and enterprise-scale service networks.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Koninklijke Philips |
| Carestream Health |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Varex Imaging Corporation |
| Others |
Supply Flow & Price Mechanics
Raw material concentration in East Asian selenium and cesium iodide refining corridors determines both the pricing tier spreads between DR and CR systems and the geographic shape of detector manufacturing networks. This input dependency compresses margins for vendors without captive scintillator supply while amplifying pricing power for integrated manufacturers.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across AI-integrated radiology platforms, with spectral CT systems commanding premium positioning over conventional energy-integrating detectors. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting platforms from 256-slice CT systems and refurbished MRI units. Cost compression in economy-tier CR systems is intensifying because Asian panel manufacturers are expanding direct-capture output. Independent diagnostic centers exhibit the highest price sensitivity, while consolidated German hospital networks absorb premium pricing for enterprise-wide standardization.
Supply Chain Analysis
Specialized EMS providers in the Yangtze River Delta and precision engineering clusters near Erlangen hold concentrated capacity for flat-panel detector assembly and superconducting magnet fabrication. Manufacturing gravity centers on China, Germany, and Japan for cesium iodide scintillators, selenium deposition equipment, and helium cryogenic systems. Supply chain vulnerability rests on single-source dependency for high-purity helium cooling in MRI magnet production. Distribution runs through radiology group purchasing organizations in the United States and bulk procurement mandates from merged hospital networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector commercialization represents a high-growth disruption reshaping competitive positioning across CT modalities, with FDA and PMDA regulatory pathways compressing algorithm deployment timelines.
For Market Incumbents: Build captive detector manufacturing moats through backward integration into cesium iodide scintillator production and photon-counting sensor fabrication. Siemens Healthineers' Erlangen concentration and GE Healthcare's detector verticality demonstrate this defensive pattern. Consolidate service networks to counter unbundling pressure from independent imaging centers. AI algorithm portfolios require continuous FDA 510(k) submission velocity to maintain platform stickiness. For New Entrants and Emerging Players: Portable digital X-ray systems for tier-2 and tier-3 Indian cities represent the most penetrable entry point for capital-constrained health scheme deployments. AI-augmented teleradiology tools for asynchronous rural interpretation offer a second white-space channel with lower hardware capital requirements. Partner with established Asian detector manufacturers to bypass in-house fabrication barriers and accelerate commercial timelines. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors algorithm developers with regulatory fast-track positioning. Long-term viability over the next decade hinges on spectral imaging capability and AI integration depth. Acquisition targets should demonstrate PMDA Sakigake eligibility or FDA breakthrough device designation. Monitor photon-counting CT adoption curves in academic medical centers as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Augmented Tools | Accelerates commercial deployment timelines for algorithm developers seeking US market entry. |
| CE Marking Pathway Under EU MDR | Establishes clinical evidence requirements for software-driven imaging modalities in European markets. |
| Hospital System Partnership for Enterprise Networks | Secures bulk procurement mandates from consolidated German acute care facilities. |
| Software Companion Development for Hybrid Imaging | Enables surgical planning and interventional guidance applications in oncology workflows. |
| Reimbursement Strategy for Photon-Counting CT | Positions spectral imaging for coverage under CMS and private payer diagnostic protocols. |
Methodological Framework
The analysis maps digital X-ray systems, CT scanners, MRI platforms, and ultrasound modalities, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and radiology group executives. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, PMDA Sakigake designations, hospital procurement databases, and EU MDR technical documentation. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Assumptions around detector manufacturing cost curves, regulatory approval timelines, and hospital consolidation velocity were held fixed across baseline scenarios while AI adoption rates and photon-counting technology migration were varied in sensitivity analysis. Segmentation dimensions modeled include product type, end user institution scale, technology capture modality, and clinical application area. CAGRs derive from replacement cycle analysis, installed base depreciation schedules, and penetration rate projections for emerging modalities.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, helium supply availability, or trade policy affecting rare earth inputs would shift the trajectory. Quarterly review of FDA submission volumes, PMDA fast-track grants, and German hospital merger announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Medical Devices Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Cardioscope Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Prostate Biopsy Devices Market