
 MRI Safe Defibrillator Market | 2026-2036
MRI Safe Defibrillator Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Safe Defibrillator Market Foresight
FDA's 510(k) pathway revisions for active implantable devices is consolidating the cost-of-entry calculus for MRI-conditional defibrillator manufacturers. Medtronic plc leverages its integrated CRM ecosystem to sustain leadership in implantable systems across North American hospital networks. Boston Scientific Corporation anchors its position through proprietary MRI-conditional lead technology that commands premium placement in tertiary cardiac centers.
An MRI safe defibrillator is an active cardiac rhythm management device engineered with non-ferromagnetic materials, filtered circuitry, and specialized lead configurations to function without image artifact or patient heating during magnetic resonance imaging up to 1.5 or 3.0 Tesla field strengths. These devices serve the primary commercial purpose of enabling continuous arrhythmia monitoring and intervention for patients who require both defibrillation therapy and periodic MRI diagnostics. Implantable cardioverter defibrillators occupy the dominant margin pool due to their high unit value and recurring replacement cycles, while automated external defibrillators in hospital settings represent the fastest-growing installation category as emergency departments retrofit for MRI compatibility. Software-based technology segments are capturing expanding value share as algorithm-driven conditional mode switching becomes standard for device safety certification.
The FDA, EMA, and ISO 14117 standards collectively govern electromagnetic compatibility testing, material biocompatibility, and post-market surveillance for MRI-conditional cardiac devices across their respective jurisdictions. These frameworks mandate extensive bench testing and clinical validation that extend development timelines and favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving MRI field strength standards beyond 3.0 Tesla as research magnets proliferate and conditional labeling requirements expand accordingly.
Market Dynamics
Cardiac catheterization laboratories are consolidating procurement around MRI-conditional device platforms that eliminate workflow interruptions between implantation and diagnostic imaging, compressing vendor selection criteria toward integrated system suppliers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- ISO 14117 electromagnetic compatibility standards:Harmonized testing protocols across FDA and EMA jurisdictions accelerate multi-market approval timelines for manufacturers with established certification pathways.
- Japan's aging demographic concentration:Tokyo and Osaka medical centers are retrofitting electrophysiology suites with MRI-conditional systems to serve expanding cohorts of septuagenarian arrhythmia patients requiring concurrent device therapy and neurovascular imaging.
- Lead technology miniaturization:Filtration circuitry advances enable 3.0 Tesla field strength compatibility without hardware trade-offs, opening diagnostic protocols previously excluded from device-eligible patient populations.
Market Restraints
- Precious metal input volatility:Platinum-iridium electrode alloys face price pressure from automotive catalyst demand, squeezing gross margins on lead assemblies.
- Regulatory friction from FDA 510(k) pathway revisions:Elevated premarket submission requirements for active implantable devices extend development timelines and favor incumbents with captive clinical trial infrastructure.
- Technical limitation at ultra-high field strengths:Conditional labeling currently stops at 3.0 Tesla, excluding patients requiring 7.0 Tesla research magnet protocols for neurodegenerative diagnostics.
Strategic Opportunities
- Underpenetrated German ambulatory surgical centers:Outpatient electrophysiology facilities outside Berlin and Munich lack MRI-conditional device inventories, creating first-mover positioning for distributors with technical training capabilities.
- Software-based conditional mode switching:Algorithm-driven safety certification reduces hardware redesign cycles and opens recurring revenue streams through firmware update subscriptions.
- EU MDR transition tailwinds:Stricter post-market surveillance requirements disadvantage smaller competitors without dedicated quality management systems, consolidating shelf space for compliant manufacturers.
Industry Challenges
- Electrophysiologist training bottlenecks:MRI-conditional lead extraction and revision procedures require specialized simulation-based credentialing that outpaces fellowship program expansion.
- Legacy device incompatibility:Patient populations with non-conditional implanted leads face explant surgery risks when upgrading to MRI-compatible systems, complicating conversion campaigns.
- Supply chain reconfiguration friction:Non-ferromagnetic material sourcing from Japan and Germany requires dual-qualified suppliers with medical-grade certification, constraining volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Safe Defibrillator Market |
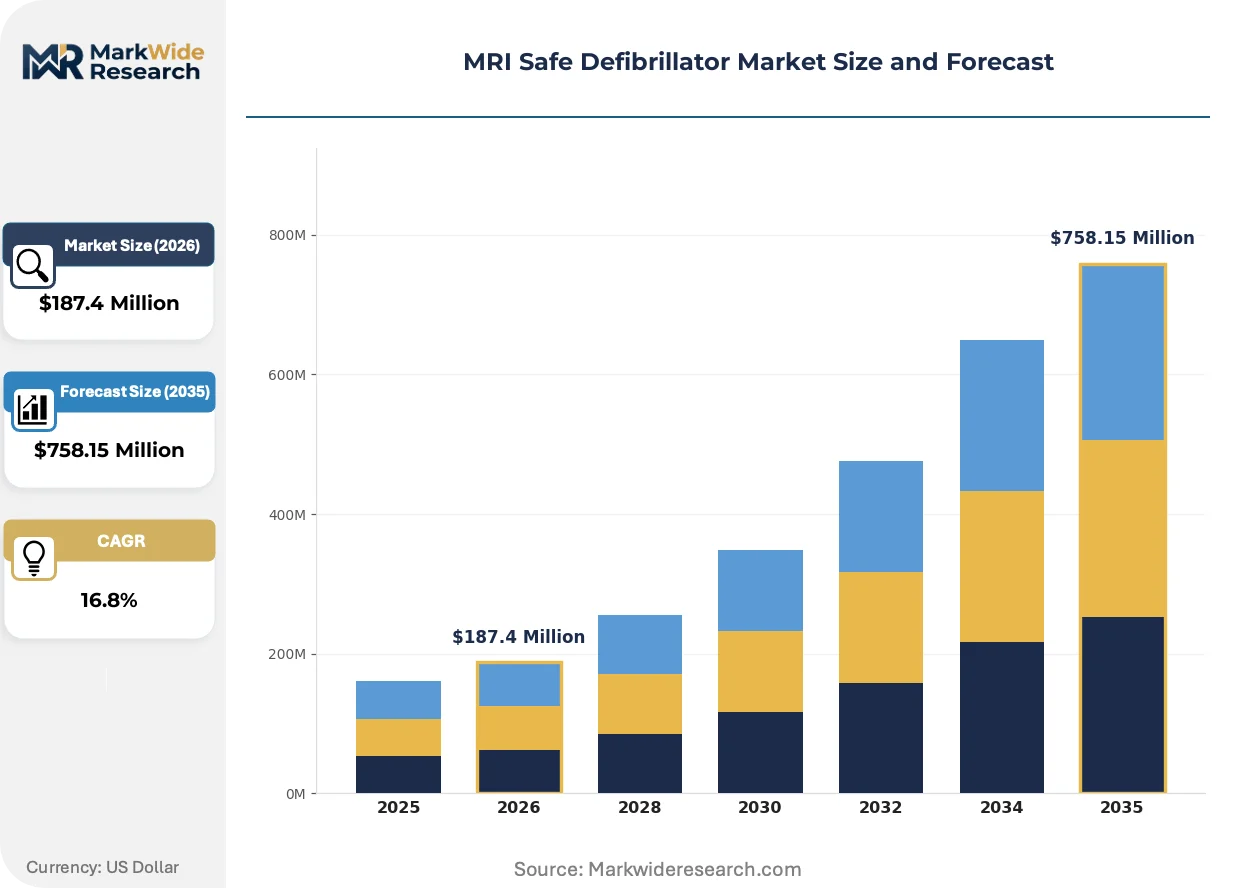
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Defibrillators, Automated External Defibrillators, Implantable Cardioverter Defibrillators, Wearable Defibrillators End User: Hospitals, Clinics, Emergency Medical Services, Homecare Settings Technology: Electrical, Electromechanical, Software-Based, Hybrid Service Type: Rental Services, Sales, Maintenance Services, Consulting |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Biotronik SE & Co. KG, MicroPort Scientific Corporation, LivaNova PLC, Zoll Medical Corporation, Philips, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Safe Defibrillator Market Shifts & Advancements
Algorithm-driven device management is compressing the hardware-software boundary in cardiac rhythm management, enabling diagnostic capability expansion without physical implant revision. This convergence is reshaping competitive positioning toward platform ecosystems.
Subcutaneous ICD form factors with integrated MRI-conditional sensing are overtaking transvenous systems in pre-implant evaluation protocols. Electrophysiology departments at Cleveland Clinic and Charité Berlin are prioritizing these configurations for patients with compromised venous access. The technology is overtaking traditional lead-dependent architectures by eliminating long-term lead failure modes while preserving full-body MRI eligibility.
EMA's Medical Device Regulation (MDR) post-market clinical follow-up requirements are mandating systematic real-world evidence collection for MRI-conditional devices. Manufacturers must now maintain active implant registries with minimum five-year follow-up intervals, elevating data infrastructure costs. High-volume tertiary cardiac centers in France and Italy are consolidating procurement toward suppliers with established European registry participation.
Hospital purchasing committees are unbundling device procurement from technical service contracts, forcing manufacturers to compete on discrete value components. Cardiac catheterization laboratories in the United States are negotiating direct software licensing agreements separate from hardware acquisition, compressing traditional bundled pricing power. This pattern is most visible in Texas and Florida health systems with centralized supply chain governance.
MRI Safe Defibrillator Market Segmentation
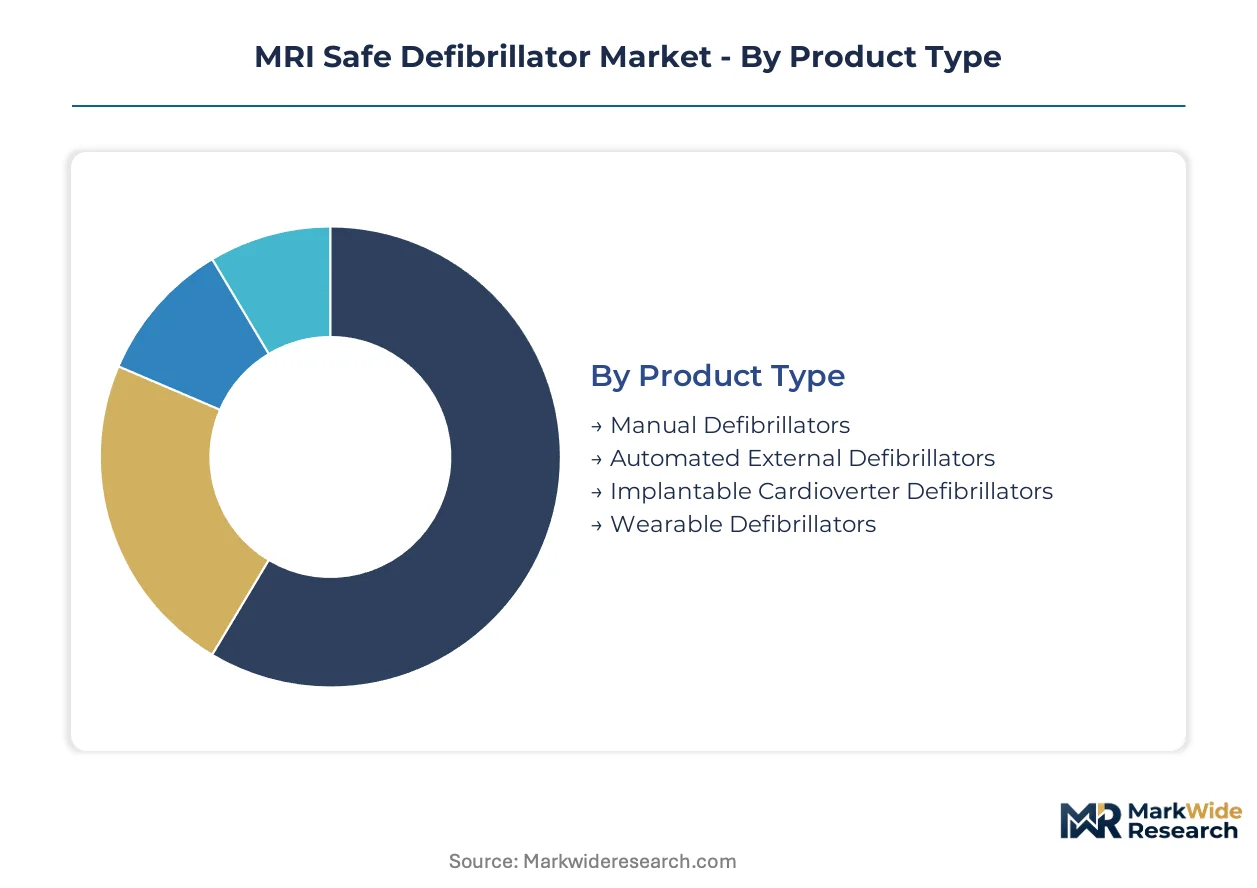
Segmentation in MRI-conditional cardiac devices reveals how procurement priorities diverge across clinical settings and technology platforms. Supply chain configuration and regulatory compliance requirements vary substantially by product form factor and service model.
Product Type:
Supply concentration in active implantable systems tilts toward manufacturers with captive lead production and dedicated MRI-conditional testing facilities.
- Implantable Cardioverter Defibrillators:These transvenous and subcutaneous systems incorporate filtered circuitry, non-ferromagnetic housings, and specialized leads rated for 1.5 to 3.0 Tesla field strengths. Tertiary cardiac centers in the United States and Germany concentrate procurement around platforms with integrated remote monitoring ecosystems.
- Automated External Defibrillators:Hospital-grade units with MRI-conditional labeling enable emergency deployment within diagnostic suites without patient transfer delays. Emergency departments in Japan and Texas health systems are retrofitting crash carts with these configurations to eliminate workflow interruptions.
- Manual Defibrillators:These devices serve catheterization laboratories requiring direct physician control over energy delivery parameters during electrophysiology procedures.
- Wearable Defibrillators:Vest-based systems provide temporary arrhythmia protection for patients awaiting permanent implantation or explant recovery.
Today's leader: Implantable Cardioverter Defibrillators. Tomorrow's challenger: Automated External Defibrillators.
End User:
Cost tier differentiation separates capital-intensive hospital procurement from episodic purchasing patterns in outpatient and emergency settings.
- Hospitals:Integrated delivery networks negotiate multi-year enterprise agreements covering device hardware, software licensing, and technical service contracts. Cardiac catheterization laboratories in Cleveland Clinic and Charité Berlin standardize on single-vendor platforms to streamline credentialing and inventory management.
- Emergency Medical Services:Ambulance fleets and first-response units require portable MRI-conditional units for field deployment. Municipal procurement in Osaka and Munich prioritizes lightweight configurations with extended battery autonomy.
- Clinics:Outpatient electrophysiology facilities outside major metropolitan clusters lack dedicated MRI-conditional device inventories.
- Homecare Settings:Post-discharge monitoring and wearable defibrillator programs serve patients with temporary contraindications to permanent implantation.
Procurement volume concentrates in Hospitals. Steepest expansion trajectory: Emergency Medical Services.
Technology:
Application-specific requirements drive divergence between hardware-centric and algorithm-dependent safety architectures.
- Software-Based:Algorithm-driven conditional mode switching enables real-time device reconfiguration during MRI sequences without physical intervention. FDA and EMA certification pathways for firmware-controlled safety systems are compressing hardware redesign cycles for manufacturers with established software quality management systems.
- Electrical:Traditional filtered circuitry architectures dominate legacy device installed bases requiring lead replacement protocols.
- Electromechanical:Hybrid designs integrate mechanical switching with electronic control for high-reliability applications.
- Hybrid:Combined hardware-software approaches serve research magnet protocols up to 3.0 Tesla with conditional labeling.
Software-Based systems are gaining share fastest. Electrical platforms defend installed base through replacement cycles.
Service Type:
Customer type stratification separates capital purchasers from operational expenditure models in budget-constrained settings.
- Sales:Direct device acquisition dominates hospital procurement with bundled warranty and training provisions. German ambulatory surgical centers and United States health systems with centralized supply chain governance favor outright purchase for implantable systems.
- Maintenance Services:Post-implant surveillance, lead integrity monitoring, and battery replacement programs generate recurring revenue. EU MDR post-market clinical follow-up requirements mandate systematic device registry participation.
- Rental Services:Temporary wearable defibrillator programs and emergency department surge capacity utilize short-term equipment deployment.
- Consulting:Electrophysiology workflow optimization and MRI safety protocol development support technology adoption.
Sales transactions anchor revenue. Maintenance Services deliver expanding margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiologist talent clusters in Cleveland Clinic, Charité Berlin, and Tokyo University Hospital anchor MRI-conditional device demand in their respective national markets. These specialized workforce concentrations drive procurement standards and technology adoption curves.
United States
Integrated delivery networks in Texas and Florida health systems negotiate enterprise agreements covering device hardware and software licensing separately. FDA 510(k) pathway revisions for active implantable devices elevate compliance costs. Cleveland Clinic's cardiac catheterization laboratory standardizes on single-vendor platforms to streamline credentialing.
Germany
EMA Medical Device Regulation post-market surveillance requirements mandate five-year implant registries. Charité Berlin's electrophysiology department prioritizes subcutaneous ICD configurations for patients with compromised venous access. Outpatient facilities outside Berlin and Munich lack MRI-conditional inventories.
Japan
Tokyo and Osaka medical centers retrofit electrophysiology suites to serve expanding septuagenarian arrhythmia populations. METI standards govern electromagnetic compatibility testing alongside ISO 14117 protocols. Municipal procurement in Osaka prioritizes lightweight portable units for emergency medical services.
United Kingdom
NHS England's specialized commissioning frameworks concentrate MRI-conditional device procurement in designated cardiac centers. MHRA regulations align with EMA MDR transition timelines. London teaching hospitals consolidate purchasing through centralized supply chain governance.
Switzerland
Swissmedic certification requirements for active implantable devices emphasize electromagnetic compatibility validation. Zurich and Geneva cardiac centers serve cross-border patient flows from neighboring EU markets. Tertiary facilities maintain dedicated MRI-conditional testing laboratories.
MRI Safe Defibrillator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the MRI-conditional cardiac device landscape. The vendor base stratifies into three tiers: integrated CRM ecosystem providers with captive lead production, mid-scale manufacturers with regional certification expertise, and emerging entrants targeting software-based conditional mode switching. Consolidation pressure intensifies as EU MDR transition requirements disadvantage smaller competitors without dedicated quality management systems. Dominant competitive moves include strategic partnerships for non-ferromagnetic material sourcing and algorithm licensing agreements for firmware-controlled safety systems.
Within the integrated ecosystem tier, Medtronic plc and Boston Scientific Corporation occupy positions defined by proprietary lead technology and remote monitoring platform integration. Abbott Laboratories exemplifies the diversified medical device conglomerate archetype, leveraging cross-divisional regulatory affairs infrastructure. These three companies anchor competitive dynamics through established FDA and EMA certification pathways, hospital network relationships, and electrophysiology training program partnerships.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| Zoll Medical Corporation |
| Philips |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in Texas and Florida health systems negotiate enterprise agreements that unbundle hardware acquisition from software licensing and technical service contracts, compressing traditional bundled pricing power toward discrete component negotiation.
Pricing Analysis
Bundled hardware-service contracts are fragmenting into separately negotiated software licensing agreements and technical service subscriptions. Price differentiation hinges on ISO 14117 certification tier and MRI field strength rating, with 3.0 Tesla conditional labeling commanding premium placement. Cost compression in lead assemblies is intensifying because platinum-iridium electrode alloys face automotive catalyst demand pressure. Outpatient electrophysiology facilities exhibit highest price sensitivity, while tertiary cardiac centers prioritize integrated ecosystem reliability over unit cost.
Supply Chain Analysis
Medical-grade non-ferromagnetic material certification gates supplier qualification, constraining volume scaling to dual-qualified producers in Japan and Germany with ISO 13485 quality management systems. Manufacturing draws from platinum-iridium electrode alloys, titanium housings, and specialized filtration circuitry substrates. Single-source vulnerability concentrates in Japanese precision metal suppliers qualified for active implantable device standards. Distribution runs through hospital purchasing committees, GPO contracts, and specialized cardiac device distributors with electrophysiology training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-based conditional mode switching is displacing hardware redesign cycles, creating margin expansion through firmware update subscriptions that reduce physical implant revision frequency.
For Market Incumbents: Extend remote monitoring platform integration to capture recurring revenue from algorithm-driven safety certification updates. Consolidate lead production through backward integration into non-ferromagnetic material sourcing, neutralizing precious metal input volatility. Defend against emerging software-centric entrants by accelerating FDA 510(k) pathway submissions for firmware-controlled systems.
For New Entrants and Emerging Players: Enter via German ambulatory surgical centers outside Berlin and Munich, where MRI-conditional device inventories remain underdeveloped and technical training capabilities create differentiation. Target emergency medical services in Osaka and Munich with lightweight portable configurations featuring extended battery autonomy. Pursue direct software licensing agreements separate from hardware to circumvent incumbent bundled pricing structures.
For Investors and Strategic Acquirers: Diversified medical device conglomerates with cross-divisional regulatory affairs infrastructure are the most active acquirers in this space, seeking algorithm licensing capabilities and European registry participation. Acquisition target archetypes include software quality management specialists and regional distributors with electrophysiology training programs. Watch EU MDR post-market surveillance compliance rates as inflection indicator for competitive consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Agreement | Firmware-controlled safety systems compress hardware redesign cycles for ISO 14117 certification. |
| Hospital System Partnership | Cleveland Clinic and Charité Berlin standardization creates reference site leverage for enterprise procurement. |
| Non-Ferromagnetic Material Sourcing Partnership | Dual-qualified Japanese and German suppliers constrain volume scaling without captive supply agreements. |
| Software Companion Development | Remote monitoring ecosystems generate recurring revenue through conditional mode switching subscriptions. |
| Reimbursement Strategy | CMS Medicare coverage determinations and NHS England specialized commissioning frameworks dictate procurement eligibility. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA 510(k) filings, EMA Medical Device Regulation submissions, hospital procurement databases, and ISO 14117 certification registries. Triangulation across these data streams ensures segmentation accuracy.
Historical trendline analysis of implant volumes and replacement cycles informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user setting, technology architecture, and service model. CAGRs were derived from weighted average growth trajectories across these segments. Forecast inputs incorporate electrophysiologist training program expansion rates and MRI suite retrofit investment pipelines.
Inputs from FDA premarket submission databases and European implant registries were available through the study window; gaps in real-world evidence collection for subcutaneous ICD configurations introduce uncertainty bands around adoption curve assumptions. A model refresh is warranted upon material change in EU MDR post-market surveillance enforcement intensity or MRI field strength standard revisions beyond 3.0 Tesla.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Embolization Plugs Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Intubation Tubes Market