
 Neurostimulation Market | 2026-2036
Neurostimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Neurostimulation Market Outlook
The EU Medical Device Regulation is recalibrating compliance burdens for implantable neuromodulation systems entering European markets. Medtronic leverages its vertically integrated manufacturing footprint to sustain cost advantages across spinal cord and deep brain stimulation portfolios. Boston Scientific Corporation anchors its competitive stance through specialized pain management platforms, while Abbott differentiates via directional lead technology that targets neural structures with enhanced precision.
Neurostimulation encompasses implantable and external devices that deliver electrical impulses to specific neural targets, typically operating at frequencies between 2 Hz and 10,000 Hz with pulse widths of 60–450 microseconds to modulate pathological neural activity. These systems treat medication-resistant conditions including chronic pain, epilepsy, and Parkinson's disease by interrupting aberrant signaling pathways or restoring normalized firing patterns. Spinal cord stimulators occupy the largest revenue pool given established reimbursement for failed back surgery syndrome, while deep brain stimulators command premium pricing due to complex surgical placement and programming requirements. Non-invasive transcranial magnetic stimulation devices represent the fastest-expanding category as clinics adopt outpatient depression protocols without surgical infrastructure.
FDA premarket approval pathways and the EU MDR's clinical evidence requirements shape product development timelines and market access conditions for neurostimulation manufacturers. The EPA and ISO 14708 standards additionally govern battery disposal and active implantable device safety protocols that constrain material selection. Stakeholders must monitor evolving CMS coverage determinations for novel indications and adaptive trial designs that regulators increasingly accept for breakthrough neuromodulation therapies.
Market Dynamics
Implantable neuromodulation systems face intensifying pressure from the EU MDR's clinical evidence requirements, which are extending development timelines while simultaneously compressing reimbursement windows for legacy devices.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates commercialization timelines for novel neuromodulation platforms targeting medication-resistant epilepsy and movement disorders.
- Chronic pain clinics:Ambulatory surgical centers are expanding spinal cord stimulation programs as CMS coverage determinations broaden eligibility for failed back surgery syndrome.
- Directional lead technology:Precision targeting of neural structures is expanding addressable patient populations beyond traditional cylindrical lead limitations.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material sourcing from East Asian refiners creates vulnerability for implantable pulse generator manufacturers.
- EU MDR clinical evidence burden:Legacy spinal cord stimulators face costly post-market surveillance upgrades to maintain CE marking validity.
- Non-invasive TMS substitution:Transcranial magnetic stimulation devices capture depression patients who would otherwise proceed to surgical implantation.
Strategic Opportunities
- Japan's aging demographic:Parkinson's disease prevalence is driving PMDA fast-track designations for next-generation deep brain stimulation systems.
- Closed-loop adaptive algorithms:Convergence of embedded sensors and machine learning enables real-time seizure detection and automated responsive stimulation.
- Remote programming platforms:Telehealth reimbursement permanence allows device titration without specialist clinic visits, expanding rural patient access.
Industry Challenges
- Neurophysiologist scarcity:Complex programming requirements for directional leads outpace fellowship-trained specialist availability in community hospital settings.
- ISO 14708-1 compliance timelines:Active implantable device safety protocol updates delay product launches by 12-18 months for battery chemistry modifications.
- Legacy system integration:Magnetic resonance imaging conditional labeling gaps force costly device exchanges when patients require diagnostic scans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurostimulation Market |
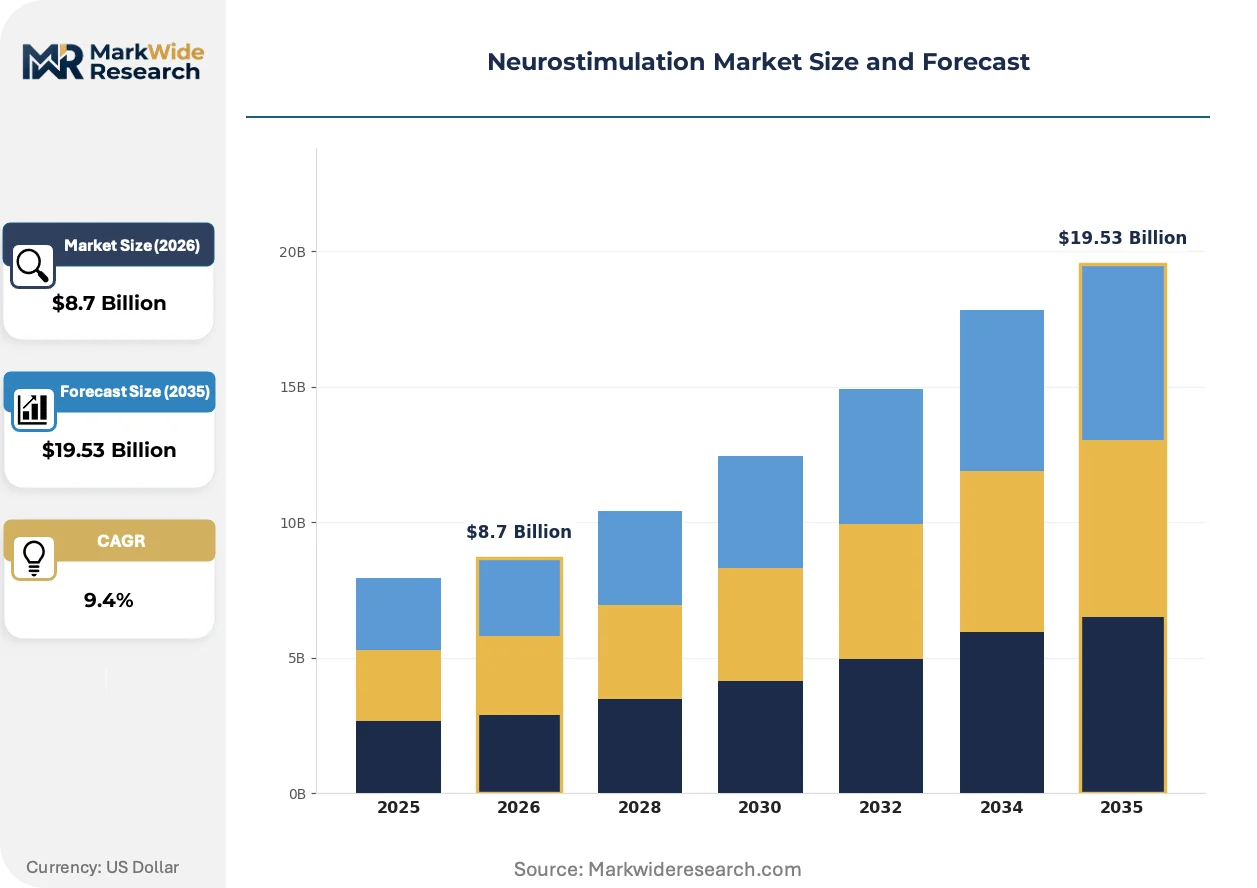
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Cord Stimulators, Deep Brain Stimulators, Vagus Nerve Stimulators, Transcranial Magnetic Stimulation Devices End User: Hospitals, Clinics, Homecare, Research Institutions Technology: Invasive, Non-Invasive, Wireless, Programmable Application: Chronic Pain Management, Epilepsy, Parkinson's Disease, Depression |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, LivaNova PLC, Nevro Corp, NeuroPace, Axonics, Neuronetics, Saluda Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurostimulation Market Strategic Shifts
Neurostimulation technology trajectories center on miniaturization, biocompatibility advances, and algorithmic autonomy that collectively reduce surgical footprint while expanding therapeutic precision.
Closed-loop sensing electrodes are absorbing the burden of manual programming adjustments by detecting local field potentials and autonomously modulating stimulation parameters. Movement disorder centers in Germany and the Netherlands are piloting these systems for Parkinson's disease, compressing the traditional six-month optimization window into weeks. The technology is absorbing clinical capacity constraints that previously limited deep brain stimulation to major academic medical centers.
REACH restrictions on nickel and cobalt compounds are forcing material substitutions in electrode alloys and battery cathodes for devices entering European markets. Manufacturers are accelerating titanium-nitride coating development and solid-state battery prototypes to preempt supply chain disruptions. Spinal cord stimulators with traditional lithium-thionyl chloride chemistry face the steepest reformulation costs under the EU Green Deal's circular economy mandates.
After-sales service unbundling is fragmenting the traditional device-plus-programming bundle as payers scrutinize specialist reimbursement rates. Pain management practices in Texas and Florida are separating hardware implantation from ongoing parameter optimization, with remote monitoring platforms capturing the latter revenue stream. This shift is most visible in commercial insurance populations where prior authorization requirements increasingly mandate documented conservative therapy failure before implantation approval.
Neurostimulation Market Segmentation
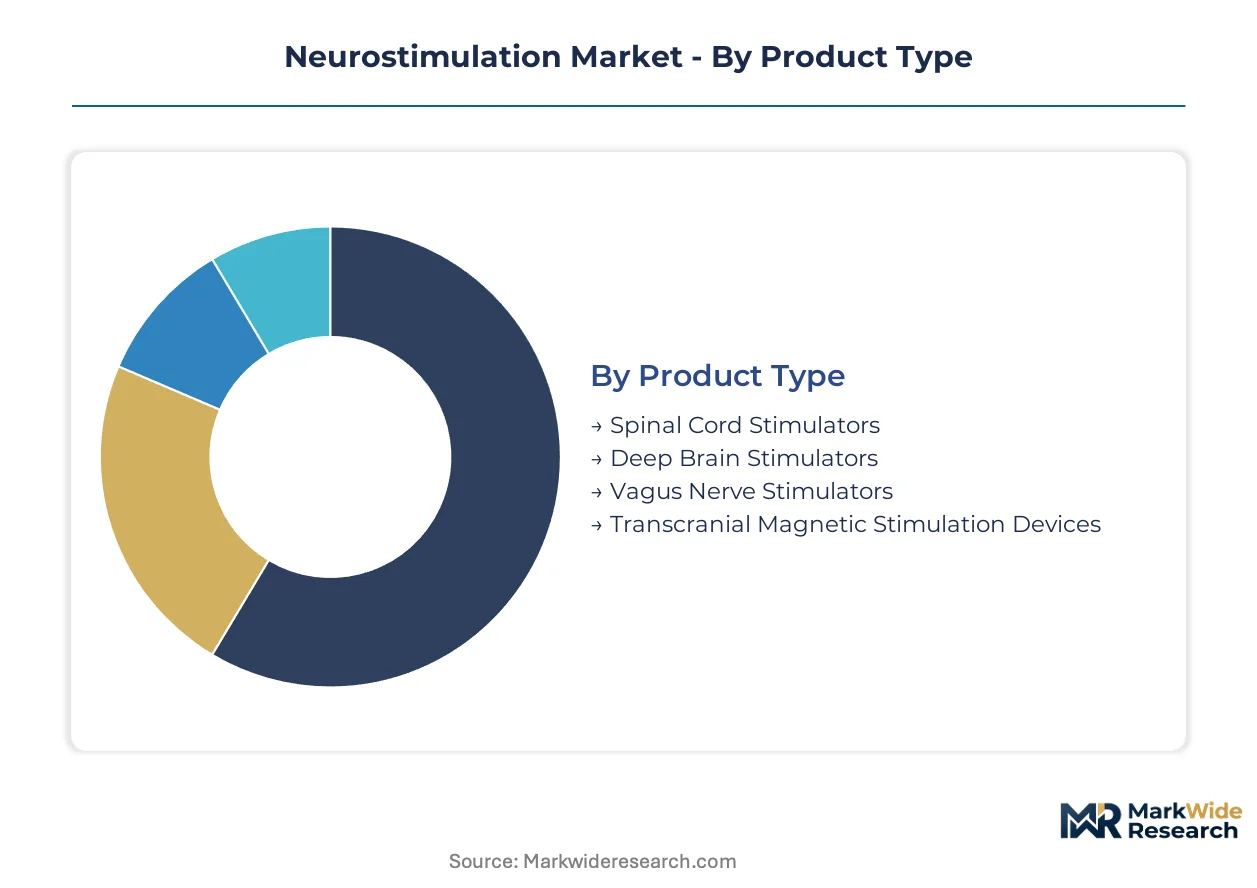
Neurostimulation segmentation reveals distinct procurement patterns across surgical versus ambulatory settings, with reimbursement pathways and regulatory complexity driving buyer preferences for specific device configurations.
Product Type:
Implant complexity and surgical infrastructure requirements dictate hospital capital allocation across neuromodulation portfolios.
- Spinal Cord Stimulators:These systems deliver electrical impulses to the dorsal column via epidural leads, typically operating at 40–60 Hz for neuropathic pain modulation. Demand concentrates in United States ambulatory surgical centers where CMS coverage determinations for failed back surgery syndrome support procedure volume. Battery longevity and MRI-conditional labeling drive replacement cycles and upgrade decisions.
- Deep Brain Stimulators:Bilateral electrode arrays target subthalamic nucleus or globus pallidus interna with high-frequency stimulation above 100 Hz. Academic medical centers in Germany and the Netherlands absorb the majority of European placements for Parkinson's disease, constrained by neurosurgeon availability and specialized programming requirements. Premium pricing reflects complex surgical placement and months-long parameter optimization protocols.
- Vagus Nerve Stimulators:Implantable pulse generators with lead coils wrapped around the left cervical vagus nerve deliver intermittent stimulation for medication-resistant epilepsy.
- Transcranial Magnetic Stimulation Devices:Non-invasive coil systems generate magnetic fields inducing cortical electrical currents for depression protocols without surgical infrastructure.
Volume sits with spinal cord stimulators; growth tilts toward transcranial magnetic stimulation devices.
End User:
Reimbursement permanence and care delivery site flexibility are redistributing patient volume across institutional settings.
- Hospitals:These facilities retain complex implantation procedures requiring general anesthesia, intraoperative neurophysiological monitoring, and overnight observation. United States health systems with dedicated neuromodulation centers capture deep brain stimulation cases requiring stereotactic neurosurgical suites and multidisciplinary movement disorder teams.
- Clinics:Ambulatory surgical centers and pain management practices perform spinal cord stimulator trials and permanent implants under local anesthesia with sedation. Texas and Florida pain practices are unbundling device implantation from programming services, with remote monitoring platforms absorbing follow-up revenue streams.
- Homecare:Patient-operated external trial stimulators and wearable non-invasive devices enable therapy continuation outside clinical settings.
- Research Institutions:Academic centers pilot closed-loop adaptive algorithms and novel neural targets under investigational device exemptions.
Procedure concentration favors hospitals; patient touchpoint expansion favors clinics.
Technology:
Connectivity architecture and surgical invasiveness determine regulatory pathway length and commercial launch timelines.
- Invasive:Fully implantable pulse generators with transcutaneous or inductive power transfer require FDA premarket approval or EU MDR conformity assessment. These systems command the highest ASPs but face extended development timelines due to biocompatibility testing and long-term reliability validation.
- Non-Invasive:External coil or electrode systems avoid surgical risk and regulatory burden, enabling faster market entry and broader prescriber pools for depression and migraine indications.
- Wireless:Leadless or RF-powered implants eliminate percutaneous connections and associated infection vectors.
- Programmable:Software-defined parameter sets allow post-implant therapy adjustment without hardware revision.
Revenue accumulates in invasive platforms; regulatory efficiency favors non-invasive alternatives.
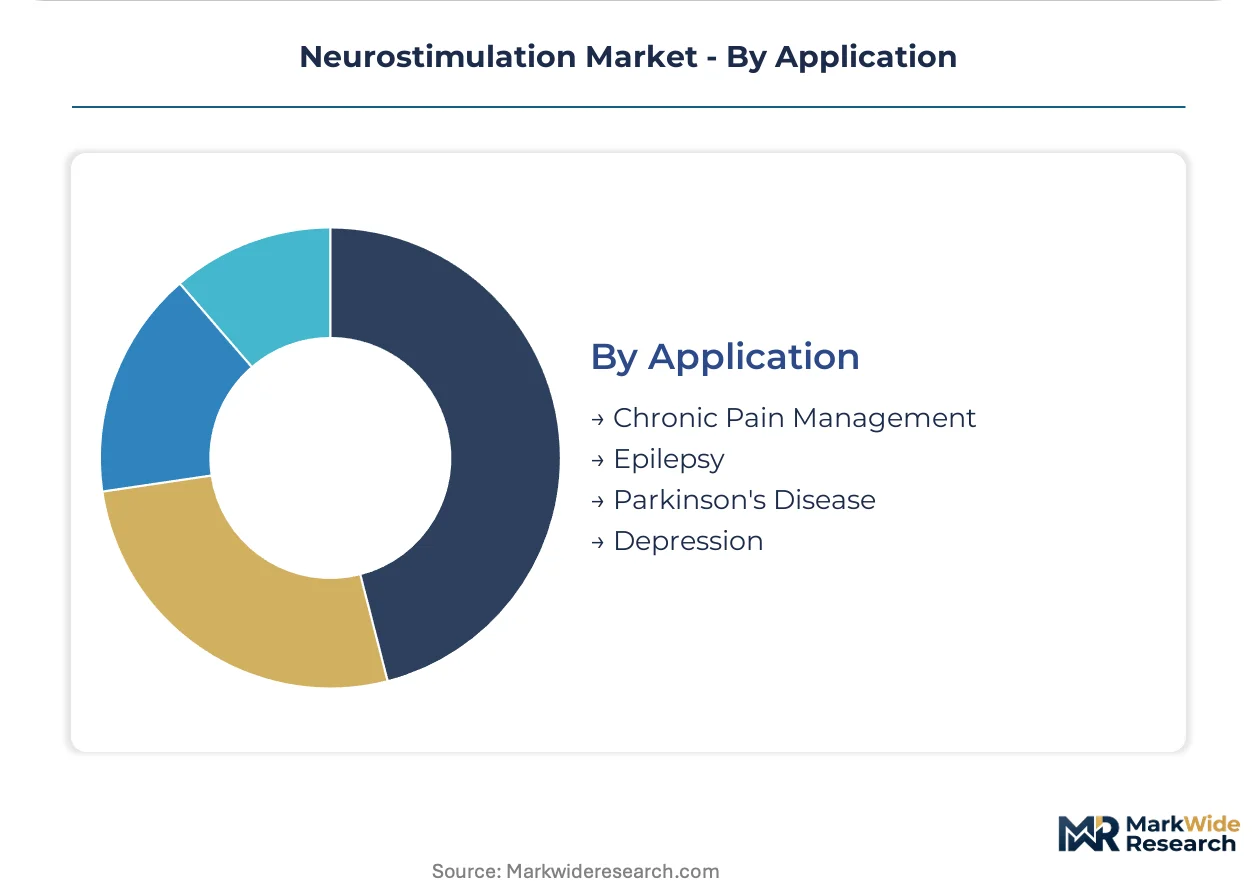
Application:
Clinical evidence thresholds and payer coverage determinations segment addressable populations by neurological condition.
- Chronic Pain Management:Failed back surgery syndrome and complex regional pain syndrome represent the largest reimbursed indication pools. Spinal cord stimulation competes with intrathecal drug delivery and repeat surgery for intractable neuropathic pain, with United States commercial insurers mandating documented conservative therapy failure prior to authorization.
- Epilepsy:Vagus nerve stimulation and responsive neurostimulation target medication-resistant seizures with closed-loop detection capabilities. Pediatric populations and adults with bilateral foci drive device selection when resection is contraindicated.
- Parkinson's Disease:Deep brain stimulation addresses motor fluctuations and dyskinesias in patients with inadequate levodopa response.
- Depression:Transcranial magnetic stimulation and emerging vagus nerve stimulation indications target treatment-resistant major depressive disorder.
Patient volume concentrates in chronic pain; evidence generation accelerates in depression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American neurostimulation manufacturing through vertically integrated production campuses serving spinal cord and deep brain stimulation portfolios. The metropolitan cluster concentrates FDA-cleared device assembly, sterile packaging operations, and specialized logistics for implantable pulse generators distributed across ambulatory surgical networks.
United States
Commercial insurers mandate documented conservative therapy failure prior to spinal cord stimulator authorization, concentrating demand in Texas and Florida pain management corridors. CMS coverage determinations for failed back surgery syndrome sustain procedure volume in ambulatory surgical centers. The FDA's breakthrough device designation pathway accelerates market entry for closed-loop epilepsy systems in Greater Boston's neuromodulation research triangle.
Germany
Academic medical centers in Munich and Heidelberg absorb the majority of European deep brain stimulator placements for Parkinson's disease motor fluctuations. EU MDR clinical evidence requirements extend development timelines for legacy device recertification. REACH restrictions on nickel and cobalt compounds force electrode alloy substitutions in manufacturing facilities across Baden-Württemberg's precision engineering belt.
Japan
Parkinson's disease prevalence among aging populations drives PMDA fast-track designations for next-generation deep brain stimulation systems. METI industrial policy supports domestic production of implantable pulse generators through medical device innovation clusters. Osaka-based movement disorder centers pilot closed-loop adaptive algorithms that compress traditional parameter optimization windows from months to weeks.
Netherlands
Movement disorder specialists in Amsterdam and Rotterdam lead European adoption of directional lead technology for enhanced neural targeting precision. ECHA chemical safety protocols govern battery disposal and active implantable device material selection. Eindhoven's health technology corridor hosts research institutions investigating responsive neurostimulation for medication-resistant epilepsy under investigational device exemptions.
Australia
TGA regulatory pathways enable faster market entry for non-invasive transcranial magnetic stimulation devices targeting treatment-resistant depression. Private health insurance funds increasingly cover outpatient neuromodulation protocols without surgical infrastructure requirements. Sydney and Melbourne pain clinics expand spinal cord stimulation programs as diagnostic referral networks mature across New South Wales and Victoria.
Neurostimulation Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory pathway complexity. Consolidation characterizes the implantable device segment where FDA premarket approval requirements create steep barriers to entry, while fragmentation prevails in non-invasive external systems with faster commercialization timelines. Three archetypes dominate: diversified medical technology conglomerates with vertically integrated manufacturing footprints, specialized neuromodulation pure-plays with focused R&D pipelines, and emerging wireless platform developers leveraging telehealth reimbursement permanence. Competitive dynamics center on M&A activity targeting closed-loop sensing capabilities and strategic partnerships securing lithium-ion battery supply chains.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify scale-driven archetypes with established spinal cord stimulation portfolios, while Abbott occupies a differentiated position through directional lead technology specialization. These three entities anchor competitive positioning across implantable neuromodulation systems, with their manufacturing footprints and regulatory expertise representing structural advantages in FDA and EU MDR compliance environments. Smaller pure-play specialists including Nevro Corp and Axonics occupy innovation-driven tiers focused on specific indications or technological discontinuities such as rechargeable pulse generators and MRI-conditional labeling.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| LivaNova PLC |
| Nevro Corp |
| NeuroPace |
| Axonics |
| Neuronetics |
| Saluda Medical |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up pain management practice networks in Texas and Florida anchor device procurement volume, concentrating buyer power while simultaneously compressing specialist reimbursement rates and fragmenting the traditional hardware-plus-programming bundle. This ownership pattern feeds pricing discipline downward through unbundled after-sales service contracts and remote monitoring platform adoption.
Pricing Analysis
Value-based pricing anchors on documented conservative therapy failure prior to implantation authorization, with United States commercial insurers mandating this clinical threshold for spinal cord stimulator coverage. Pricing stratifies across premium, standard, and economy tiers based on MRI-conditional labeling completeness and battery longevity specifications. Cost compression in rechargeable pulse generators intensifies as Nevro and Axonics force legacy lithium-thionyl chloride systems toward replacement cycles. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedural margins, while academic medical centers absorb premium directional lead technology with less elasticity.
Supply Chain Analysis
ISO 14708-1 active implantable device safety certification gates entry for electrode alloys and battery cathodes entering European markets. Manufacturing concentrates in the United States, Germany, and Japan, with cathode material sourcing drawing from East Asian refiners for lithium-ion supply. REACH restrictions on nickel and cobalt compounds create regulatory risk for legacy device recertification under EU MDR timelines. Distribution runs through sterile packaging operations in Minneapolis and specialized logistics networks serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurostimulation supply is tightening around neurophysiologist scarcity and EU MDR clinical evidence requirements, with these capacity bottlenecks propping pricing power for programmable platforms that reduce manual optimization burden.
For Market Incumbents: To counter non-invasive transcranial magnetic stimulation substitution for depression indications, deepen backward integration into solid-state battery prototypes and titanium-nitride coating development. Secure lithium-ion cathode supply through long-term offtake agreements with East Asian refiners. Invest in remote programming platform certification to capture unbundled after-sales revenue streams. For New Entrants and Emerging Players: Capture white-space in closed-loop adaptive algorithms for Parkinson's disease by targeting Germany and Netherlands movement disorder centers piloting autonomous parameter modulation. Prioritize Japan's aging demographic through PMDA fast-track designations. Lead with telehealth-enabled device titration to bypass specialist clinic infrastructure constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor wireless platform developers with telehealth reimbursement permanence in United States rural access corridors. Five-to-ten year viability hinges on adaptive algorithm differentiation and MRI-conditional labeling completeness. Watch CMS coverage determination expansions for novel epilepsy indications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for closed-loop epilepsy systems in Greater Boston research corridors. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend recertification timelines for legacy spinal cord stimulators. |
| Hospital System Partnership | United States health systems with dedicated neuromodulation centers capture deep brain stimulation cases requiring stereotactic suites. |
| Software Companion Development | Remote monitoring platforms absorb follow-up revenue streams as Texas and Florida practices unbundle programming services. |
| Reimbursement Strategy | CMS coverage determinations for failed back surgery syndrome sustain procedure volume in ambulatory surgical centers. |
Study Parameters
Document review covered FDA premarket approval filings, EU MDR conformity assessment databases, and CMS national coverage determinations, complemented by interviews with movement disorder specialists, pain management physicians, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, ISO 14708 standard documentation, and REACH chemical safety protocols. Bottom-up device shipment analysis triangulated against top-down reimbursement claim trends.
Market size outputs across product type, technology, application, and end-user segments were stress-tested against implantable pulse generator production disclosures and ambulatory surgical center procedure volume data. CAGRs were derived from weighted average of historical pricing trajectories and penetration rate assumptions for closed-loop systems. Forecast inputs incorporated neurophysiologist fellowship training pipeline data and PMDA fast-track designation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement stringency and lithium-ion supply chain disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Global Concussion Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Electronic Smart Mask Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Intubation Tubes Market
Medical Devices
Global External Fixators Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
France Respiratory Devices Market