
 Dystonia Drugs Market | 2026-2036
Dystonia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Dystonia Drugs Market Analysis
Multi-source API procurement for botulinum toxin is hardening as manufacturers diversify beyond single fermentation facilities. AbbVie Inc. leverages captive biologics capacity to secure supply continuity across North American distribution channels. Merz Pharmaceuticals anchors its position through specialized neurotoxin purification expertise developed over decades in German manufacturing sites. Ipsen Pharma competes via differentiated formulation science that extends product stability profiles.
Dystonia drugs comprise pharmacological agents targeting involuntary sustained muscle contractions through neuromodulation of acetylcholine, dopamine, or GABA pathways, with botulinum toxin formulations requiring precise unit dosing measured in mouse units per injection vial. The injectable delivery mode dominates revenue capture due to the precision required for intramuscular administration near affected nerve terminals. Oral anticholinergics retain substantial volume in generalized dystonia management where systemic distribution addresses widespread symptoms. Cervical dystonia therapy area commands premium positioning given the functional disability associated with torticollis and the established reimbursement for targeted injections.
FDA neurotoxin lot release testing and EMA biosimilar pathway requirements shape product standards and market access timelines for new entrants. The EPA and corresponding European environmental frameworks govern fermentation waste disposal from Clostridium botulinum culture processes, adding compliance cost layers. Stakeholders must monitor evolving FDA guidance on long-acting neurotoxin formulations and EMA pharmacovigilance requirements for distant spread adverse events as these will determine competitive differentiation and manufacturing investment priorities.
Market Dynamics
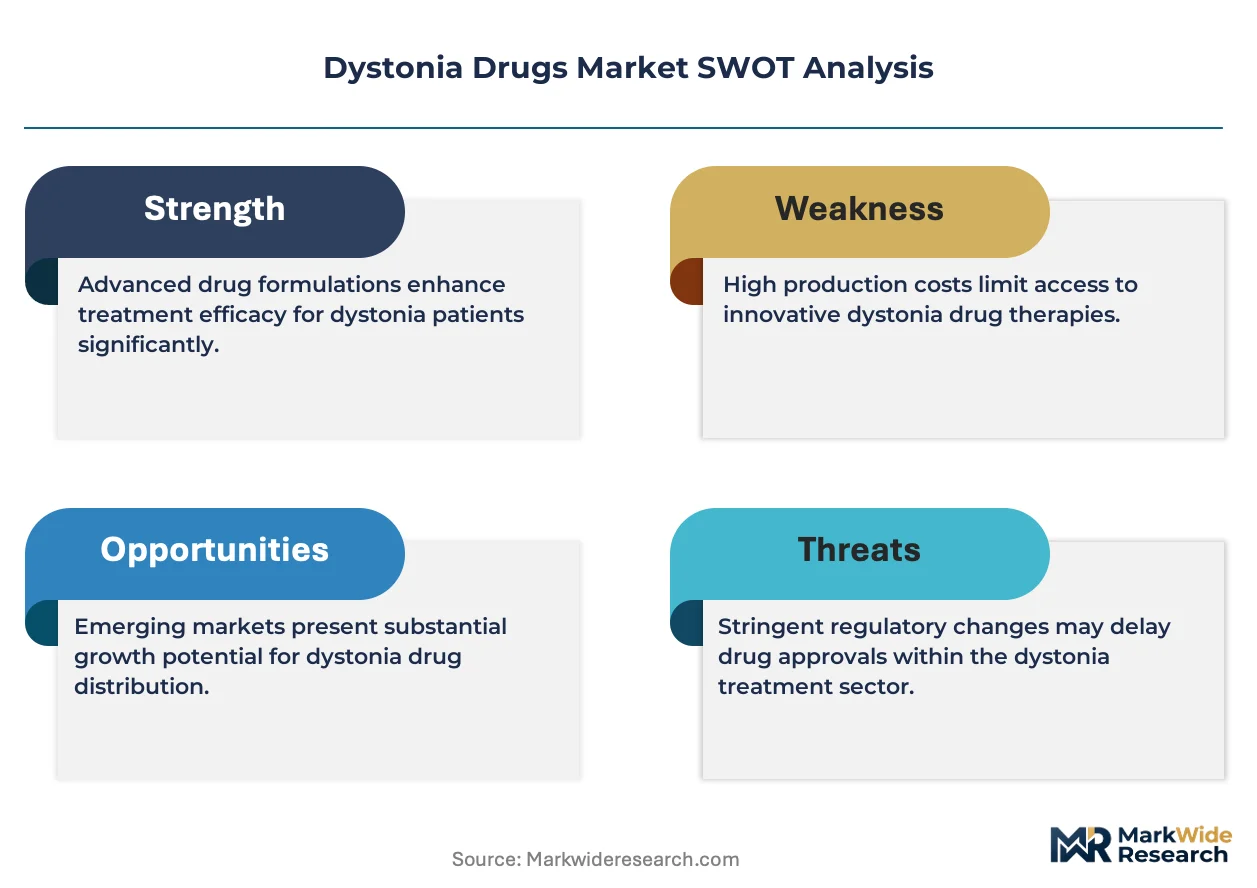
Botulinum toxin manufacturing concentrates among three biologics suppliers with captive fermentation capacity, creating supply-side leverage that shapes pricing power and distribution channel economics across North American and European markets.
Growth Catalysts
- FDA neurotoxin lot release testing:Stringent batch verification protocols elevate quality barriers that filter substandard entrants and reinforce incumbent positioning in US distribution networks.
- Neurology clinic expansion:German movement disorder centers are scaling injection administration under EMA guidelines for cervical and focal dystonia subtypes.
- Intradermal microinjection devices:Precision delivery hardware advances are reducing injection-site variability and expanding treatable patient populations.
Market Restraints
- Clostridium botulinum fermentation waste disposal:EPA and European environmental frameworks impose costly compliance layers on manufacturing site operations.
- Single-source biologics dependency:API procurement remains concentrated among captive fermentation facilities with limited geographic diversification.
- Oral anticholinergic substitution:Systemic pharmacotherapy retains substantial volume in generalized dystonia management where injection precision offers limited advantage.
Strategic Opportunities
- EMA pharmacovigilance pathway evolution:Distant spread adverse event monitoring requirements create differentiation potential for formulation stability leaders.
- Long-acting neurotoxin formulations:Extended duration injectables address injection burden in chronic cervical dystonia patients with high treatment frequency.
- Specialized neurotoxin purification:German manufacturing expertise in complex biologic isolation represents transferable capability for emerging market partnerships.
Industry Challenges
- Mouse unit standardization:Potency assay variability between laboratories complicates dose equivalence and therapeutic switching protocols.
- Cold chain integrity maintenance:Temperature-sensitive biologics distribution requires specialized logistics infrastructure that fragments last-mile delivery economics.
- Reimbursement coding precision:Procedure classification granularity affects physician practice revenue capture and patient access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dystonia Drugs Market |
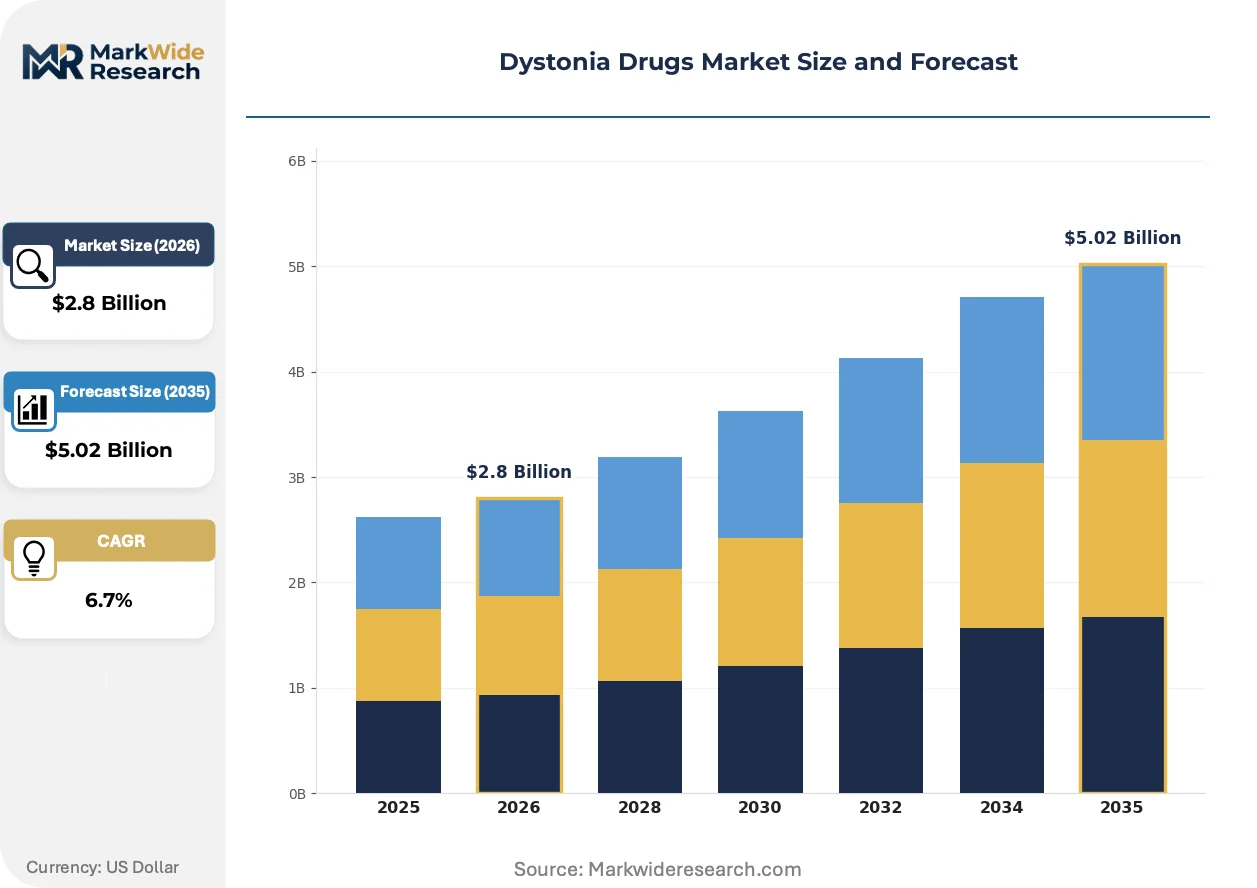
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Anticholinergics, Dopamine Agonists, Muscle Relaxants Therapy Area: Cervical Dystonia, Focal Dystonia, Generalized Dystonia, Writer's Cramp End User: Hospitals, Clinics, Homecare, Research Institutions Delivery Mode: Injectable, Oral, Transdermal, Intrathecal |
| Companies Covered | AbbVie Inc., Merz Pharmaceuticals, Ipsen Pharma, Teva Pharmaceutical Industries, F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, Amneal Pharmaceuticals, Hameln Pharma GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dystonia Drugs Market Emerging Trajectories
Formulation science and delivery mechanism advances are compressing treatment intervals while regulatory frameworks on both sides of the Atlantic recalibrate safety surveillance expectations for neuromodulatory biologics.
Extended-release botulinum toxin formulations are consolidating competitive positioning around injection frequency reduction. Chronic cervical dystonia patients with quarterly or more frequent dosing requirements represent the primary adoption segment. This consolidation is compressing market share for conventional duration products and forcing reformulation investment priorities.
EMA biosimilar pathway requirements are extending market access timelines for new neurotoxin entrants. Comparative efficacy and immunogenicity demonstration obligations add development cost layers. European manufacturers with established pharmacovigilance infrastructure are adapting submission strategies to accommodate these expanded evidentiary demands.
Specialized infusion center networks are displacing hospital outpatient departments as preferred injection administration sites. Movement disorder neurologists are consolidating practice volume into dedicated facilities with optimized workflow and reimbursement capture. This channel migration is most visible in US metropolitan markets with concentrated dystonia patient populations.
Dystonia Drugs Market Segmentation
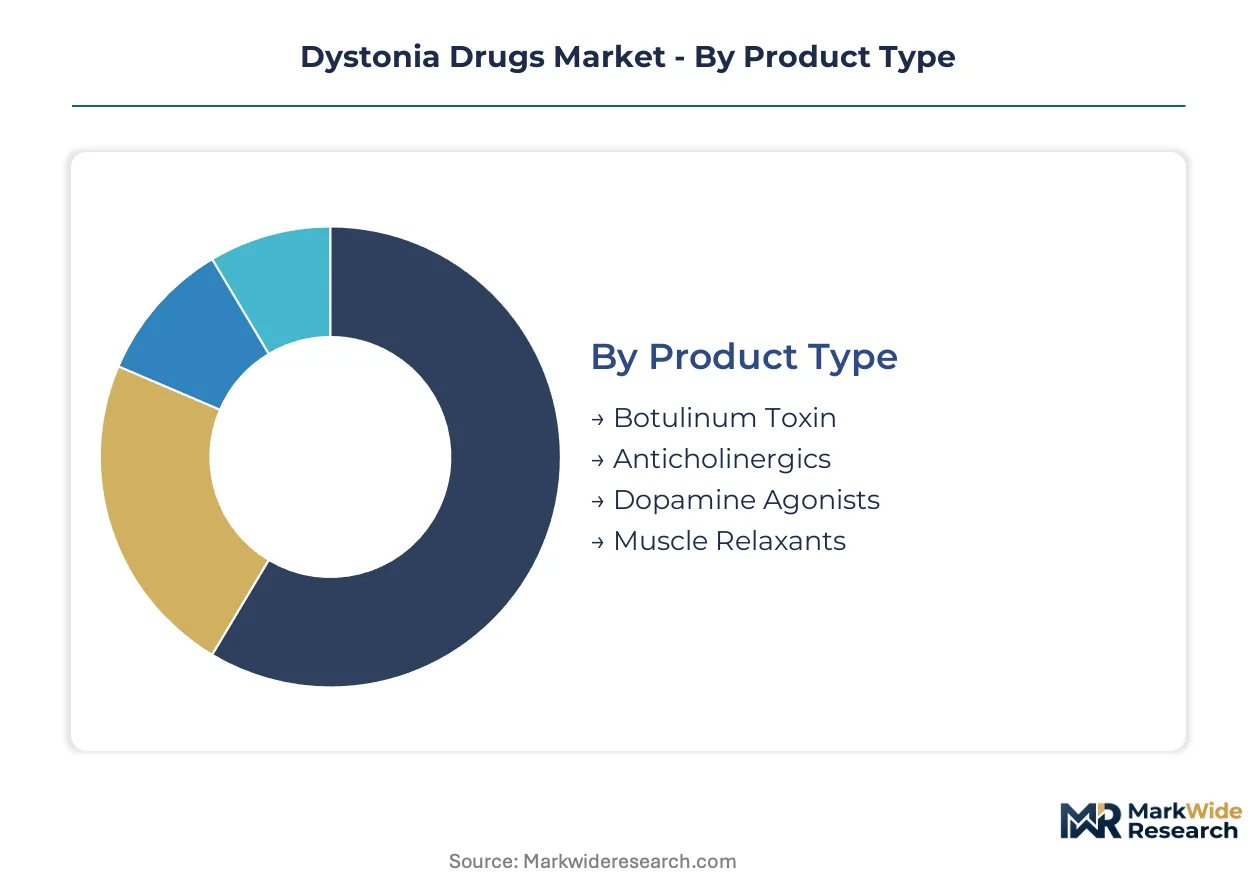
Dystonia drug segmentation reveals distinct procurement and administration patterns across therapeutic modalities. Product type and delivery mode configurations determine reimbursement pathways and clinical adoption velocity in movement disorder treatment.
Product Type:
Botulinum toxin formulations operate as standalone biologic interventions requiring specialized handling, while oral agents integrate into broader systemic pharmacotherapy regimens.
- Botulinum Toxin:Purified neuroprotein complexes manufactured through Clostridium botulinum fermentation demand cold chain logistics and unit-dose precision measured in mouse units. Cervical dystonia applications in German neurology clinics concentrate demand under EMA movement disorder guidelines.
- Anticholinergics:Systemic agents targeting muscarinic acetylcholine receptors address generalized dystonia where widespread muscle involvement exceeds focal injection feasibility. Oral administration routes in US hospital formularies retain substantial volume for pediatric and multifocal presentations.
- Dopamine Agonists:Dopaminergic modulators prescribed for dopa-responsive dystonia subtypes.
- Muscle Relaxants:GABA-ergic agents including baclofen formulations for spasticity-associated dystonias.
Botulinum toxin leads volumes today; anticholinergics are gaining share fastest in generalized dystonia management.
Therapy Area:
Cost tier stratification separates premium-positioned focal indications from economy-tier systemic management approaches.
- Cervical Dystonia:Torticollis and related neck muscle disorders command premium reimbursement for targeted chemodenervation. US metropolitan infusion centers concentrate injection volume given established CPT coding and functional disability documentation requirements.
- Focal Dystonia:Isolated body region presentations including blepharospasm and oromandibular variants. Precision injection protocols in specialized movement disorder clinics drive demand for high-unit-potency formulations.
- Generalized Dystonia:Multifocal presentations spanning multiple body regions.
- Writer's Cramp:Task-specific focal hand dystonia affecting professional and recreational writing populations.
Cervical dystonia commands highest per-patient revenue; focal dystonia applications are expanding most quickly with microinjection device advances.
End User:
Customer type fragmentation reflects reimbursement capture capabilities and treatment complexity thresholds across care settings.
- Hospitals:Academic medical centers manage complex generalized dystonia with multidisciplinary coordination. Inpatient botulinum toxin administration for severe spasticity presentations anchors procurement volume under bundled payment structures.
- Clinics:Dedicated movement disorder centers optimize injection workflow and physician reimbursement. German neurology clinics scaling under EMA guidelines represent the fastest-expanding channel for focal dystonia procedures.
- Homecare:Oral medication management and caregiver-administered supportive therapies.
- Research Institutions:Clinical trial sites investigating novel neuromodulatory approaches and extended-duration formulations.
Clinics lead procedure volume growth; hospitals retain highest-complexity case concentration.
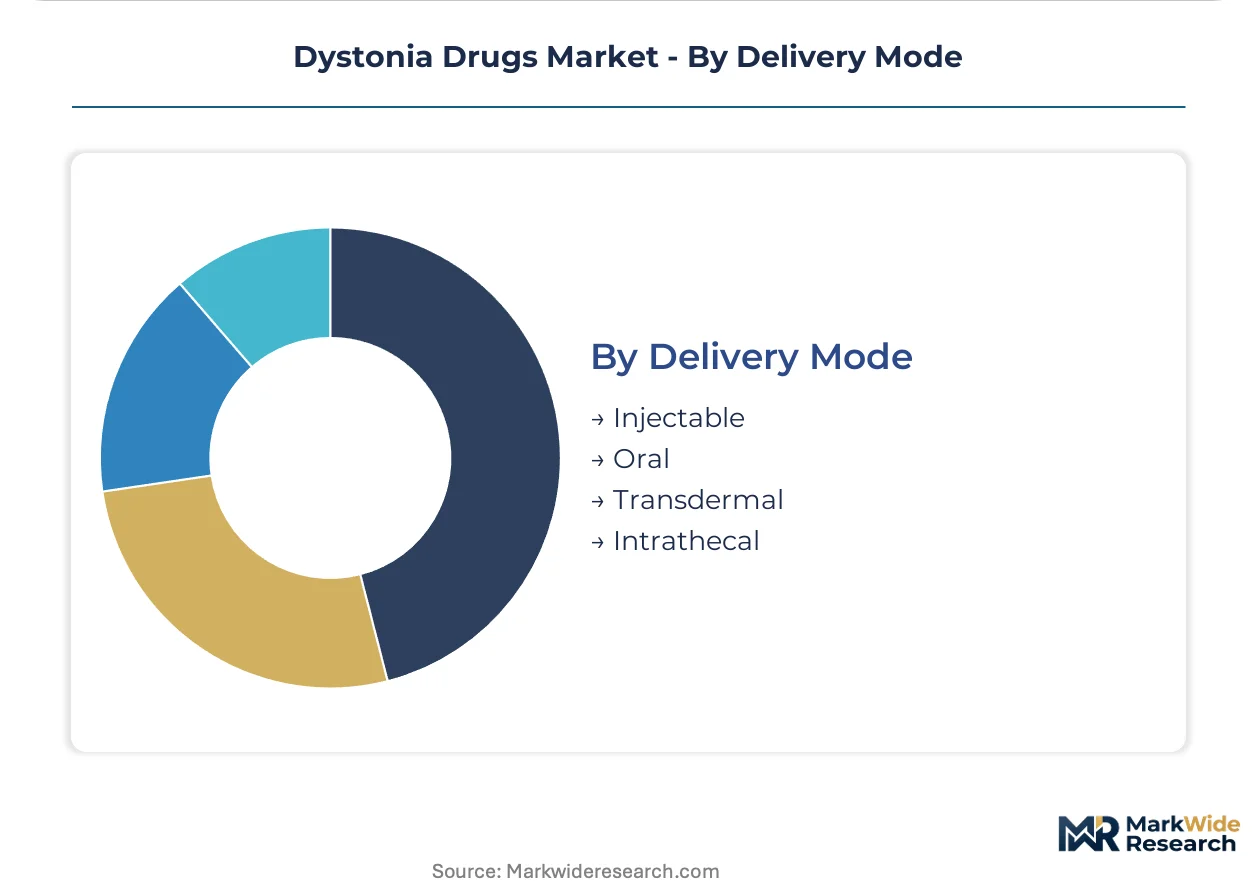
Delivery Mode:
Supply concentration in biologics manufacturing shapes channel economics and patient access timelines.
- Injectable:Intramuscular and intradermal administration requires precision delivery near affected nerve terminals. Captive fermentation capacity among three biologics suppliers creates supply-side leverage across North American distribution networks.
- Oral:Systemic distribution enables generalized symptom management without procedure dependency. Anticholinergic and muscle relaxant tablets retain volume in pediatric dystonia where injection tolerance is limited.
- Transdermal:Patch-based delivery systems for sustained drug release.
- Intrathecal:Direct CNS delivery via implanted pump systems for severe spasticity-dystonia combinations.
Injectable modes dominate revenue capture; oral administration maintains widest patient access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as fermentation facility operators migrate toward jurisdictions with streamlined environmental permitting and lower biosafety containment costs.
United States
FDA lot release testing protocols create quality barriers that filter substandard entrants and reinforce incumbent positioning. The EPA governs Clostridium botulinum fermentation waste disposal, adding compliance cost layers to domestic manufacturing. US metropolitan infusion centers concentrate injection volume given established CPT coding and movement disorder neurologist density in Boston, New York, and Los Angeles corridors.
Germany
German neurology clinics are scaling botulinum toxin administration under EMA guidelines for cervical and focal dystonia subtypes. EMA pharmacovigilance requirements for distant spread adverse events shape product standards and market access timelines. Specialized manufacturing sites in Frankfurt and Munich leverage decades of neurotoxin purification expertise to anchor European supply networks.
Switzerland
Swissmedic oversight of biologics manufacturing attracts precision formulation science investments from established neurotoxin producers. The country's national pharmaceutical regulator maintains stringent batch verification protocols that align with FDA standards. Basel and Zurich host research institutions investigating extended-duration formulations for chronic cervical dystonia.
Japan
PMDA review pathways for novel neuromodulatory biologics extend development timelines but reward formulation stability leaders with premium positioning. METI industrial policy supports domestic fermentation capacity expansion for critical biologics. Tokyo and Osaka medical centers drive adoption of microinjection devices that reduce injection-site variability in focal dystonia treatment.
United Kingdom
NHS reimbursement coding precision affects physician practice revenue capture and patient access timelines for botulinum toxin procedures. The country's national pharmaceutical regulator aligns post-Brexit with MHRA frameworks that maintain EMA-equivalent standards. London movement disorder centers consolidate referral patterns from regional neurology services across England and Scotland.
Dystonia Drugs Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar pathways and extended-release formulations. Three biologics suppliers with captive fermentation capacity dominate supply-side economics, creating tiered pricing power across North American and European distribution channels. Strategic archetypes include captive biologics manufacturers, specialized neurotoxin purification specialists, and differentiated formulation science developers. Competitive moves concentrate on strategic partnerships for emerging market access and portfolio diversification into adjacent movement disorder indications.
Within the captive biologics tier, AbbVie Inc. and Merz Pharmaceuticals exemplify supply continuity strategies anchored in North American and German manufacturing footprints. Ipsen Pharma occupies a position representing formulation science differentiation through extended stability profiles. These three entities collectively anchor the competitive structure, with Teva Pharmaceutical Industries and F. Hoffmann-La Roche Ltd representing diversified pharmaceutical conglomerates that compete via integrated neurology portfolios rather than standalone neurotoxin specialization.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Merz Pharmaceuticals |
| Ipsen Pharma |
| Teva Pharmaceutical Industries |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| Amneal Pharmaceuticals |
| Hameln Pharma GmbH |
| Others |
Supply Flow & Price Mechanics
Captive fermentation capacity among three biologics suppliers anchors both supply continuity and pricing power across North American and European distribution networks. This vertical integration into Clostridium botulinum culture processes insulates incumbents from API procurement volatility while enabling premium positioning for unit-dose precision measured in mouse units.
Pricing Analysis
Distributor margins on botulinum toxin vials compress downstream economics while manufacturer pricing stratifies across premium, standard, and economy tiers based on formulation stability profiles and cold chain certification levels. Price differentiation hinges on FDA lot release testing documentation and EMA pharmacovigilance infrastructure investment. Pricing pressure stems from oral anticholinergic substitution in generalized dystonia management. Hospital procurement committees exhibit highest price sensitivity; specialized movement disorder clinics prioritize unit consistency over cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss manufacturing sites that anchor European neurotoxin purification expertise. Fermentation capacity draws from captive facilities in the United States, Germany, and Switzerland, with raw material dependencies on specialized growth media, biosafety containment systems, and cold chain logistics infrastructure. Supply chain risk centers on EPA and EMA environmental framework compliance for Clostridium botulinum waste disposal. Distribution runs through specialized infusion center networks displacing hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through extended-duration formulation premiums and manufacturing scale efficiencies that reduce per-unit fermentation costs.
For Market Incumbents: Anticipate biosimilar pathway entrants by securing EMA pharmacovigilance infrastructure advantages and extending formulation stability profiles beyond competitor reach. Deepen backward integration into specialized growth media supply to reduce input cost volatility. Prioritize certification investment in FDA long-acting neurotoxin guidance alignment. For New Entrants and Emerging Players: Microinjection device compatibility offers a technology-first wedge into focal dystonia segments where precision delivery reduces injection-site variability. Target German neurology clinic expansion under EMA guidelines as the most penetrable geography. Pursue white-space in generalized dystonia oral formulations with improved tolerability profiles versus anticholinergics. For Investors and Strategic Acquirers: Roll-up economics work for specialized neurotoxin purification specialists because EMA biosimilar pathway requirements extend development timelines and favor incumbent capability aggregation. Five-to-ten year viability hinges on formulation science differentiation rather than commodity fermentation capacity. Watch FDA guidance evolution on long-acting neurotoxin formulations as the primary inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Duration Formulation Development | Addresses injection burden in chronic cervical dystonia patients with high treatment frequency requirements. |
| EMA Pharmacovigilance Infrastructure Investment | Creates differentiation potential for distant spread adverse event monitoring capabilities under evolving guidelines. |
| Specialized Infusion Center Partnership | Captures procedure volume migrating from hospital outpatient departments in US metropolitan markets. |
| Backward Integration into Growth Media Supply | Reduces input cost volatility and secures continuity for Clostridium botulinum fermentation processes. |
| Microinjection Device Compatibility Certification | Expands treatable patient populations through reduced injection-site variability in focal dystonia applications. |
Methodological Framework
Bottom-up neurology clinic procedure modeling reconciled against top-down biologics manufacturing capacity tracking forms the analytical core of this study. Primary interviews with movement disorder neurologists, hospital formulary directors, infusion center administrators, and payer access specialists combined with secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement databases. This dual-layer approach enables cross-verification of injection volume estimates against vial production and distribution records.
Input-output matrices map botulinum toxin unit demand across therapy area, delivery mode, and end-user configuration dimensions throughout the forecast period. CAGRs derive from segmented procedure growth trajectories reconciled with manufacturing capacity expansion announcements. Forecast inputs incorporate EMA guideline evolution timelines, FDA neurotoxin lot release testing protocol changes, and oral anticholinergic substitution elasticity in generalized dystonia management.
The model holds under stable regulatory frameworks for biologics manufacturing and reimbursement; deviation in FDA long-acting neurotoxin guidance or EMA biosimilar pathway requirements would shift competitive positioning and investment return profiles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market