
 Spinal Cord Stimulators Market | 2026-2036
Spinal Cord Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Cord Stimulators Market Analytics
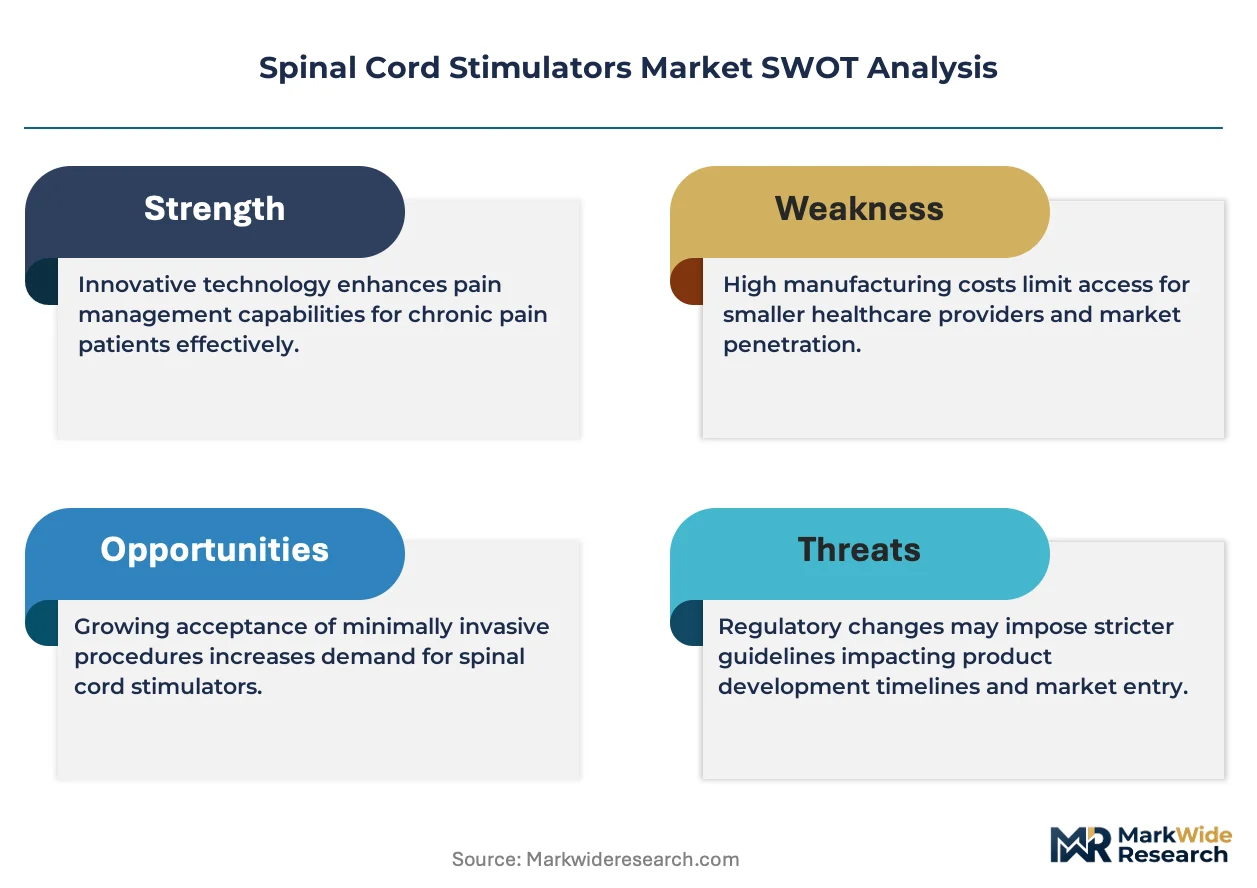
FDA premarket notification requirements for spinal cord stimulators is hardening the cost-of-entry calculus for new competitors. Medtronic leverages decades of clinical data archives to sustain its regulatory dossier advantage across multiple indications. Boston Scientific Corporation anchors its position through deep manufacturing scale in implantable pulse generators. Abbott differentiates via proprietary burst stimulation algorithms that command premium positioning in pain management clinics.
Spinal cord stimulators are implantable neuromodulation systems that deliver electrical impulses to the dorsal column of the spinal cord to interrupt pain signal transmission, typically operating at frequencies between 2 Hz and 10 kHz depending on programmed therapy mode. These devices serve the primary commercial purpose of reducing opioid dependency among patients with refractory chronic pain conditions. Implantable devices dominate current revenue pools due to higher unit economics and recurring battery replacement cycles, while closed-loop systems represent the fastest-growing technology segment as automated feedback mechanisms promise improved efficacy and reduced programming burden for clinicians. Chronic pain management anchors the application mix, though failed back surgery syndrome commands disproportionate clinical attention and dedicated reimbursement codes.
The FDA governs device safety and efficacy through its Center for Devices and Radiological Health, while the Centers for Medicare & Medicaid Services shapes demand through national coverage determinations and transcutaneous electrical nerve stimulation coverage exclusions that indirectly steer patients toward implantable alternatives. ISO 14155 clinical investigation standards and IEC 60601-1 electrical safety requirements form the baseline compliance architecture for manufacturers seeking multi-jurisdiction market access. Stakeholders must monitor how real-world evidence mandates and value-based reimbursement pilots reshape the evidentiary threshold for competitive differentiation beyond traditional randomized controlled trials.
Market Dynamics
FDA premarket notification requirements for neuromodulation devices are hardening the cost-of-entry calculus for new competitors, while established manufacturers leverage decades of clinical data archives to sustain regulatory dossier advantages across multiple pain indications.
Growth Catalysts
- Chronic pain prevalence:Aging populations in the United States and Western Europe are expanding the addressable patient pool for refractory neuropathic conditions, driving implant volumes at specialized interventional pain centers.
- CMS national coverage determinations:Medicare reimbursement frameworks for spinal cord stimulation therapy create predictable payment pathways that reduce hospital capital risk and accelerate device procurement cycles.
- Burst stimulation algorithms:Proprietary waveform technologies that modulate dorsal column firing patterns without paresthesia are commanding premium positioning in outpatient pain management clinics.
Market Restraints
- Biocompatible materials cost volatility:Titanium alloy enclosures and platinum-iridium electrode arrays face supply concentration from specialized foundries, compressing gross margins on implantable pulse generators.
- Long-term battery replacement cycles:Rechargeable systems extending device longevity to 10-15 years are elongating revenue recognition timelines and reducing recurring hardware sales.
- Transcutaneous electrical nerve stimulation substitution:Non-invasive peripheral nerve stimulation devices are capturing mild-to-moderate chronic pain cases before patients progress to surgical implantation.
Strategic Opportunities
- Closed-loop automated feedback:Integration of evoked compound action potential sensing with real-time amplitude adjustment is integrating physician programming burden reduction with improved pain response consistency.
- Japan's aging demographic:METI healthcare technology adoption incentives and PMDA streamlined review pathways for breakthrough devices are opening access to the world's oldest population cohort.
- Failed back surgery syndrome expansion:Dedicated diagnosis-related group reimbursement codes for post-laminectomy pain are creating procedure volume tailwinds distinct from general chronic pain indications.
Industry Challenges
- Interventional pain specialist training pipelines:Fellowship program capacity constraints in the United States are limiting the specialist workforce required for trial lead placement and permanent implantation procedures.
- Real-world evidence collection infrastructure:Post-market surveillance obligations under FDA 21st Century Cures Act mandates require manufacturers to build patient registry networks that strain operational resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Cord Stimulators Market |
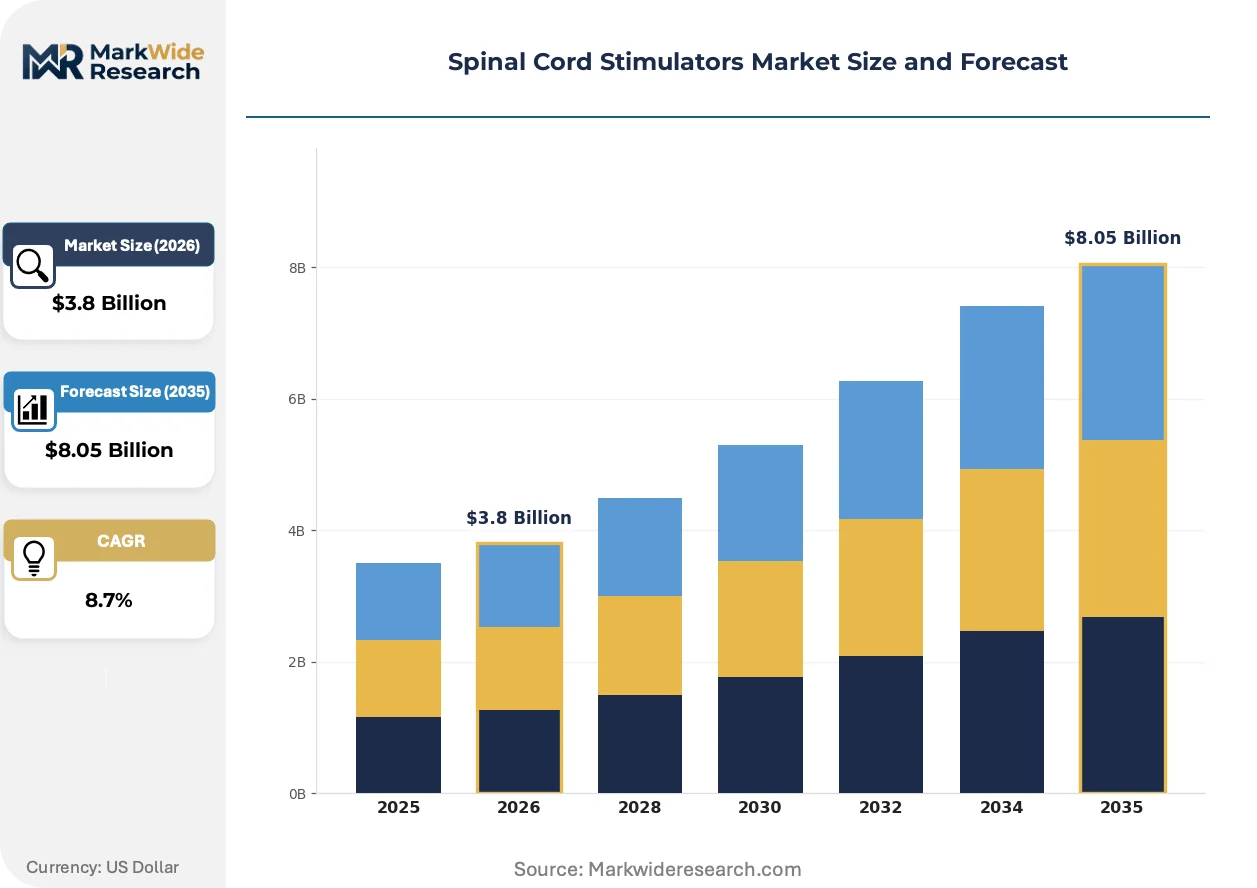
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Devices, Wireless Systems, Combination Systems End User: Hospitals, Rehabilitation Centers, Pain Management Clinics, Home Care Settings Technology: Conventional Stimulation, Burst Stimulation, High-Frequency Stimulation, Closed-Loop Systems Application: Chronic Pain Management, Neuropathic Pain Treatment, Failed Back Surgery Syndrome, Peripheral Vascular Disease |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Nevro Corp, Saluda Medical Pty Ltd, Stimwave LLC, Cirtec Medical, Nuvectra, Beijing PINS Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Cord Stimulators Market Evolving Landscape
Neuromodulation hardware is converging with digital health platforms, reshaping how spinal cord stimulators are prescribed, monitored, and reimbursed across pain management workflows.
Closed-loop sensing technology is integrating evoked response detection with automated amplitude modulation. Pain management clinics in the United States are adopting these systems at accelerating pace to reduce manual programming visits. The technology is integrating physician time compression with sustained therapeutic efficacy, reshaping service delivery economics.
The FDA's Breakthrough Devices Program is compressing review timelines for novel stimulation waveforms that demonstrate superior pain reduction metrics. Manufacturers are prioritizing burst and high-frequency protocols in premarket submissions to capture expedited access. Implantable pulse generator portfolios are most affected, with firms restructuring regulatory affairs teams to align with real-world evidence requirements.
Hospital procurement committees are unbundling device acquisition from implantation service contracts, forcing manufacturers to compete on hardware margins alone. Integrated delivery networks in the United States are centralizing purchasing decisions at system level, displacing individual physician preference. This concentration is most visible in the Midwest and Southeast regions where Catholic health initiatives and for-profit chains dominate bed capacity.
Spinal Cord Stimulators Market Segmentation
Spinal cord stimulator manufacturers structure portfolios around distinct upgrade cycles, reimbursement pathways, and clinical workflow integration. Each segmentation dimension reveals divergent margin profiles and competitive intensity.
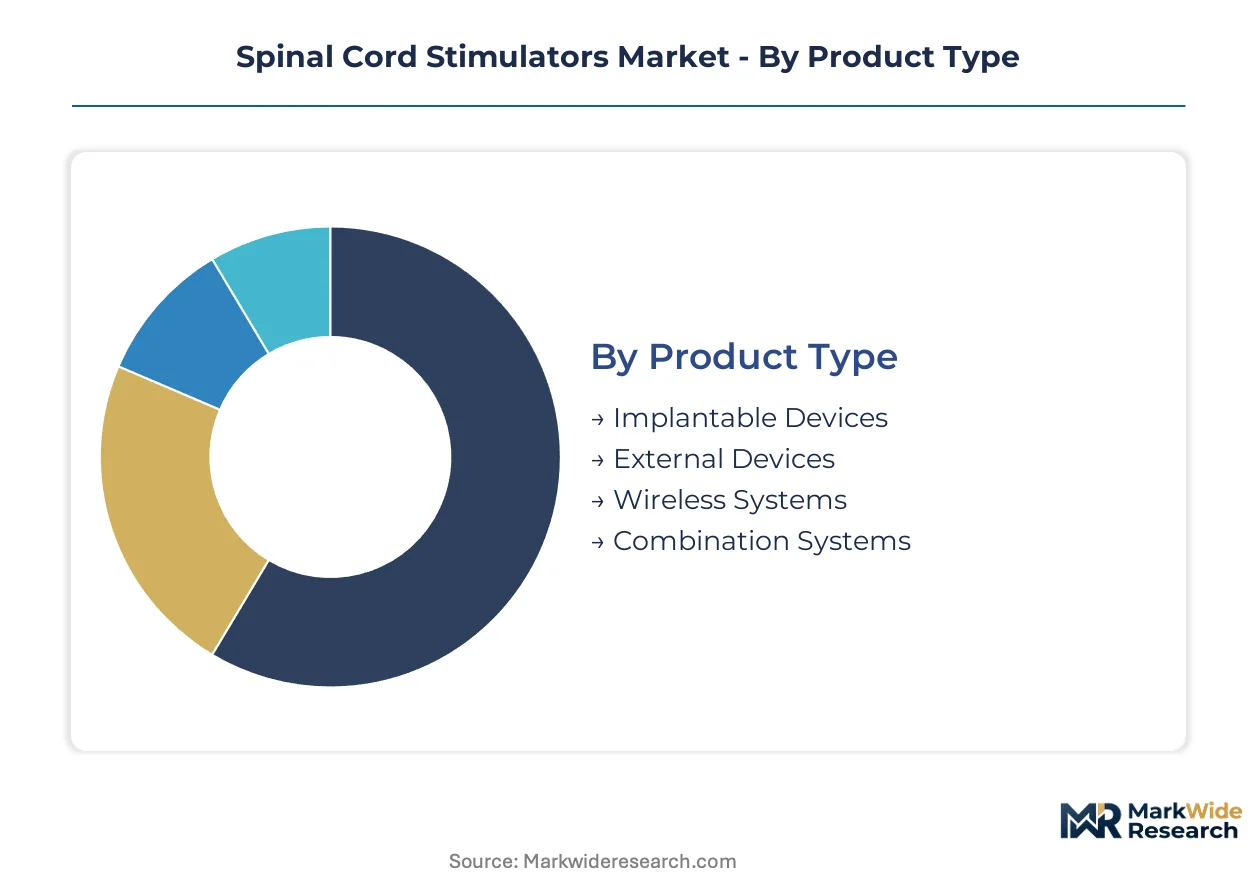
Product Type:
Replacement timelines and hardware refresh rates vary sharply across implantable versus external configurations, reshaping revenue recognition patterns.
- Implantable Devices:Titanium-enclosed pulse generators with platinum-iridium electrode arrays anchor revenue pools through higher unit economics and recurring battery replacement procedures. Demand clusters at specialized interventional pain centers in the United States where Medicare reimbursement frameworks reduce hospital capital risk.
- External Devices:Trial stimulators with percutaneous lead placement enable temporary pain relief assessment before permanent implantation commitment. Pain management clinics in Florida and Texas deploy these systems heavily to qualify candidates for full implantation coverage.
- Wireless Systems:Inductive power transfer eliminates transcutaneous leads, reducing infection risk in outpatient settings.
- Combination Systems:Hybrid architectures merge spinal cord stimulation with peripheral nerve field stimulation capabilities.
Volume placements concentrate in Implantable Devices; the faster expansion belongs to Wireless Systems.
End User:
Procurement authority and clinical decision-making autonomy differ materially across facility types, fragmenting go-to-market approaches.
- Pain Management Clinics:Physician-owned ambulatory surgery centers dominate implant volumes through streamlined prior authorization workflows and direct device contracting. These facilities in Arizona and Nevada are expanding dedicated neuromodulation suites faster than hospital-based alternatives.
- Hospitals:Integrated delivery networks centralize purchasing decisions, compressing hardware margins through system-level contracting. Catholic health initiatives in the Midwest and for-profit chains in the Southeast are unbundling device acquisition from implantation service contracts.
- Rehabilitation Centers:Post-implant programming and parameter adjustment services generate recurring revenue streams.
- Home Care Settings:Remote monitoring platforms enable patient self-management with clinician oversight.
Pain Management Clinics capture the dominant placement share; Rehabilitation Centers are climbing the fastest as programming burden shifts downstream.
Technology:
Algorithm differentiation and sensing capabilities are concentrating competitive advantage among waveform innovators.
- Closed-Loop Systems:Evoked compound action potential sensing with real-time amplitude modulation reduces manual programming visits while sustaining therapeutic consistency. Pain management clinics in California and New York are adopting these systems at accelerating pace to compress physician time per patient.
- Burst Stimulation:Proprietary waveform protocols modulate dorsal column firing without paresthesia, commanding premium positioning in outpatient settings. The FDA's Breakthrough Devices Program is compressing review timelines for manufacturers submitting burst protocol premarket notifications.
- High-Frequency Stimulation:10 kHz delivery without paresthesia sensation targets patients intolerant to conventional tonic stimulation.
- Conventional Stimulation:Tonic waveform delivery at 2-120 Hz remains the reimbursement baseline for coverage determinations.
Conventional Stimulation retains the installed base majority; Closed-Loop Systems are gaining share fastest through outcomes-based contracting.
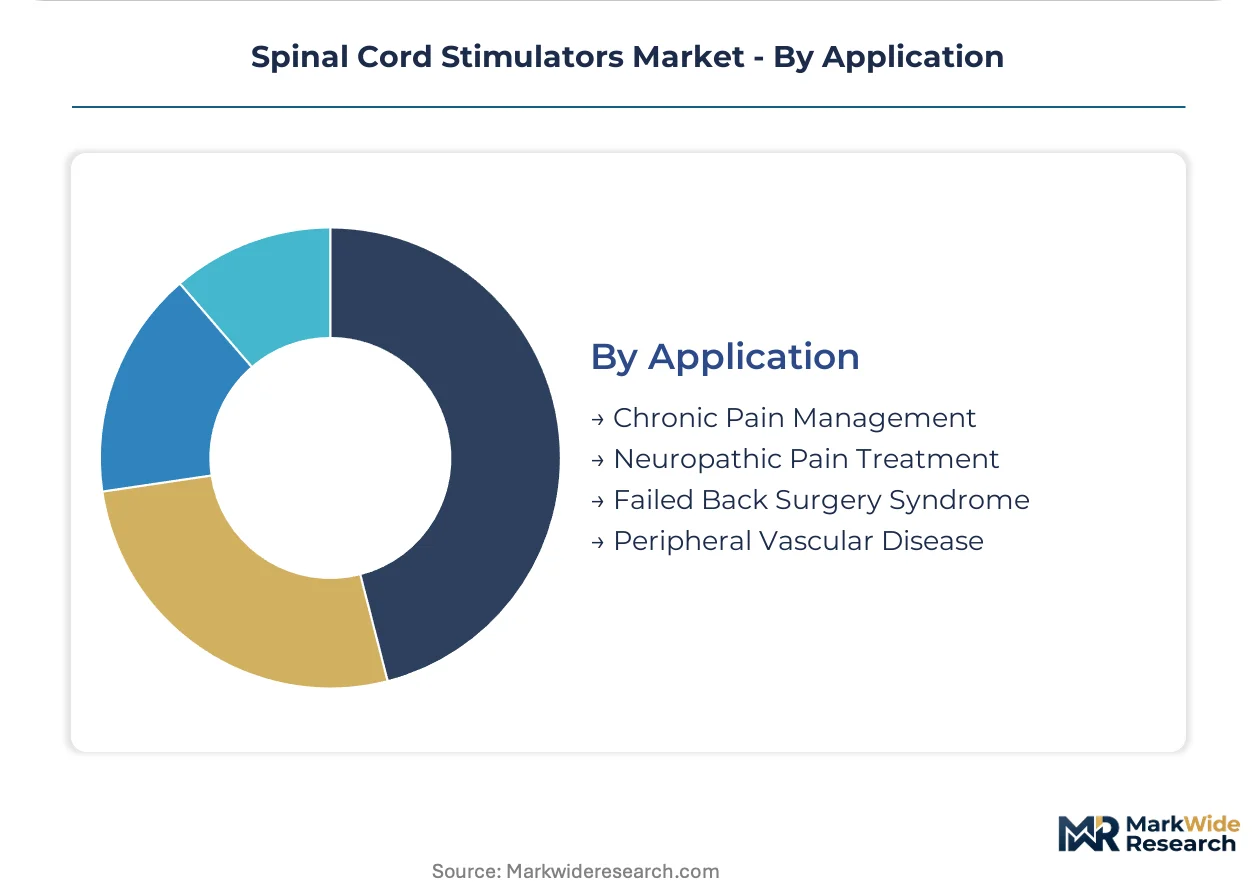
Application:
Reimbursement code specificity and diagnosis-related group assignments create divergent addressable market economics.
- Failed Back Surgery Syndrome:Dedicated diagnosis-related group codes for post-laminectomy pain create procedure volume tailwinds distinct from general chronic pain indications. Medicare national coverage determinations explicitly prioritize this indication for spinal cord stimulation access.
- Chronic Pain Management:Broad refractory neuropathic conditions represent the largest addressable patient pool, though reimbursement pathways remain less codified than syndrome-specific alternatives. Aging demographics in the United States and Western Europe expand this segment's underlying prevalence base.
- Neuropathic Pain Treatment:Diabetic peripheral neuropathy and complex regional pain syndrome drive demand for high-frequency protocols.
- Peripheral Vascular Disease:Limb ischemia applications leverage spinal cord stimulation for vasodilation effects.
Chronic Pain Management holds the broadest placement base; Failed Back Surgery Syndrome shows the steepest expansion trajectory through dedicated reimbursement codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for medical device manufacturing in Ireland and Puerto Rico concentrate spinal cord stimulator production capacity, while Japan's Kobe Biomedical Innovation Cluster and Switzerland's MedTech Valley anchor European and Asian demand centers.
United States
Medicare national coverage determinations for spinal cord stimulation therapy create predictable reimbursement pathways that reduce hospital capital risk. FDA premarket notification requirements under 21 CFR 882.5880 govern device safety and efficacy submissions. Pain management clinics in Florida and Texas deploy trial stimulators heavily to qualify candidates for permanent implantation coverage.
Germany
Diagnosis-related group reimbursement codes for failed back surgery syndrome drive procedure volumes at specialized interventional pain centers. EU Medical Device Regulation (MDR) 2017/745 imposes strengthened clinical evidence requirements for neuromodulation device market access. Medical technology clusters in Baden-Württemberg and North Rhine-Westphalia host manufacturing operations for implantable pulse generator components.
Japan
METI healthcare technology adoption incentives accelerate penetration among the world's oldest population cohort. PMDA streamlined review pathways for breakthrough devices compress regulatory timelines for novel stimulation waveforms. The Kobe Biomedical Innovation Cluster concentrates R&D facilities for closed-loop sensing technology development.
Switzerland
Swissmedic regulatory frameworks align with EU MDR standards while maintaining distinct conformity assessment procedures for implantable neuromodulation systems. Premium pricing environments in private healthcare channels sustain higher device margins. The MedTech Valley corridor between Zurich and Basel hosts headquarters operations for major neuromodulation manufacturers.
Australia
TGA approval pathways for active implantable medical devices require compliance with IEC 60601-1 electrical safety standards. Public hospital procurement frameworks through state health departments centralize purchasing decisions for spinal cord stimulator systems. Specialist pain clinics in New South Wales and Victoria expand dedicated neuromodulation suites faster than other states.
Spinal Cord Stimulators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the spinal cord stimulator value chain, creating a tiered market structure where regulatory dossier depth separates sustainable competitors from marginal entrants. Consolidation pressure intensifies as FDA evidentiary requirements harden and hospital procurement committees unbundle device acquisition from implantation services. Three archetypes dominate: diversified medical technology conglomerates with decades of clinical data archives, mid-scale neuromodulation specialists with proprietary waveform algorithms, and emerging wireless system developers targeting outpatient settings. Strategic moves concentrate on technology licensing partnerships for closed-loop sensing capabilities and backward integration into electrode array manufacturing.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation occupy positions defined by manufacturing scale and regulatory dossier breadth across multiple pain indications. Abbott exemplifies the waveform innovation archetype through proprietary stimulation protocols that command premium positioning. Nevro Corp represents the high-frequency specialization vector, while Beijing PINS Medical Co., Ltd. anchors the Asia-Pacific geographic expansion pattern for domestic market penetration.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Nevro Corp |
| Saluda Medical Pty Ltd |
| Stimwave LLC |
| Cirtec Medical |
| Nuvectra |
| Beijing PINS Medical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up pain management clinic chains in Florida and Texas are consolidating device procurement authority, compressing hardware margins through system-level contracting while simultaneously demanding extended payment terms that strain manufacturer working capital cycles.
Pricing Analysis
Short lead-time premiums for titanium-enclosed implantable pulse generators command 15-20% markups over standard delivery schedules, while spot inventory of platinum-iridium electrode arrays trades at discounts to clear excess stock. Three-tier pricing structure across premium closed-loop systems, standard rechargeable devices, and economy non-rechargeable alternatives reflects algorithm sophistication and battery longevity differentiation. Pricing pressure stems from hospital procurement committees unbundling device acquisition from implantation service contracts. Integrated delivery networks exhibit highest price sensitivity, whereas physician-owned ambulatory surgery centers prioritize waveform performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Memphis and Louisville anchor hub-and-spoke patterns for implantable pulse generator fulfillment, with satellite warehouses in Phoenix and Tampa serving high-volume pain management corridors. Manufacturing concentrates in Ireland, Puerto Rico, and Switzerland, drawing from specialized foundries in Germany and Japan for titanium alloy enclosures and platinum-iridium electrode arrays. Single-source vulnerability in biocompatible materials exposes producers to foundry capacity constraints. Distribution runs through manufacturer-direct sales forces for implantable devices and third-party distributors for external trial systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory dossier depth, with FDA premarket notification requirements forcing weaker players toward exit or acquisition as evidentiary thresholds harden.
For Market Incumbents: Deploy backward integration into electrode array manufacturing to capture margin currently lost to specialized foundries. Deepen clinical data archives across multiple pain indications to sustain regulatory dossier advantages against emerging waveform competitors. Lock in long-term supply agreements with titanium alloy producers before biocompatible materials cost volatility intensifies. For New Entrants and Emerging Players: Launch via direct-to-pain-clinic distribution models bypassing hospital procurement committee gatekeepers. Target wireless system development for outpatient settings where infection risk reduction commands premium positioning. Exploit Japan's PMDA streamlined review pathways for breakthrough devices to establish regulatory beachhead before scaling to United States FDA submissions. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale neuromodulation specialists with proprietary burst stimulation algorithms in European markets where EU MDR transition has strained smaller competitors. Five-to-ten-year viability hinges on closed-loop sensing technology integration capabilities. Watch FDA Breakthrough Devices Program designation velocity as inflection indicator for waveform innovation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Program Submission | Expedited review timelines compress regulatory barriers for novel stimulation waveforms. |
| Closed-Loop Sensing Technology Licensing | Evoked compound action potential integration reduces physician programming burden per patient. |
| Hospital System Partnership | Integrated delivery network contracting secures volume commitments against procurement centralization. |
| Reimbursement Strategy Development | Medicare national coverage determination alignment unlocks predictable payment pathways. |
| Software Companion Development | Remote monitoring platforms enable patient self-management with clinician oversight. |
Research Methodology
FDA 510(k) premarket notification databases, CMS national coverage determination records, and ISO 14155 clinical investigation standards formed the secondary backbone for regulatory pathway mapping. Primary interviews with interventional pain specialists, hospital purchasing committee members, biomedical engineers at implant centers, and GPO contracts managers validated demand assumptions and procurement workflow dynamics. Bottom-up and top-down triangulation reconciled device shipment data with procedure volume estimates across pain management clinics and hospital-based settings.
Bottom-up modeling built from implant volume projections by technology type, application indication, and end-user facility category across the analysis window. Segmentation dimensions included product configuration, stimulation waveform protocol, rechargeable versus non-rechargeable battery architecture, and regional regulatory cluster. CAGRs derived from spline interpolation between historical shipment trajectories and clinician adoption curve assumptions. Forecast inputs incorporated Medicare reimbursement rate stability and PMDA breakthrough device designation velocity.
Regulatory timeline delays, biocompatible materials supply disruptions, and transcutaneous electrical nerve stimulation substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions regarding FDA review pathway efficiency and specialist workforce expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Manometry System Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Global Sperm Separation Devices Market