
 Multiple Sclerosis Therapies Market | 2026-2036
Multiple Sclerosis Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Sclerosis Therapies Market Intelligence
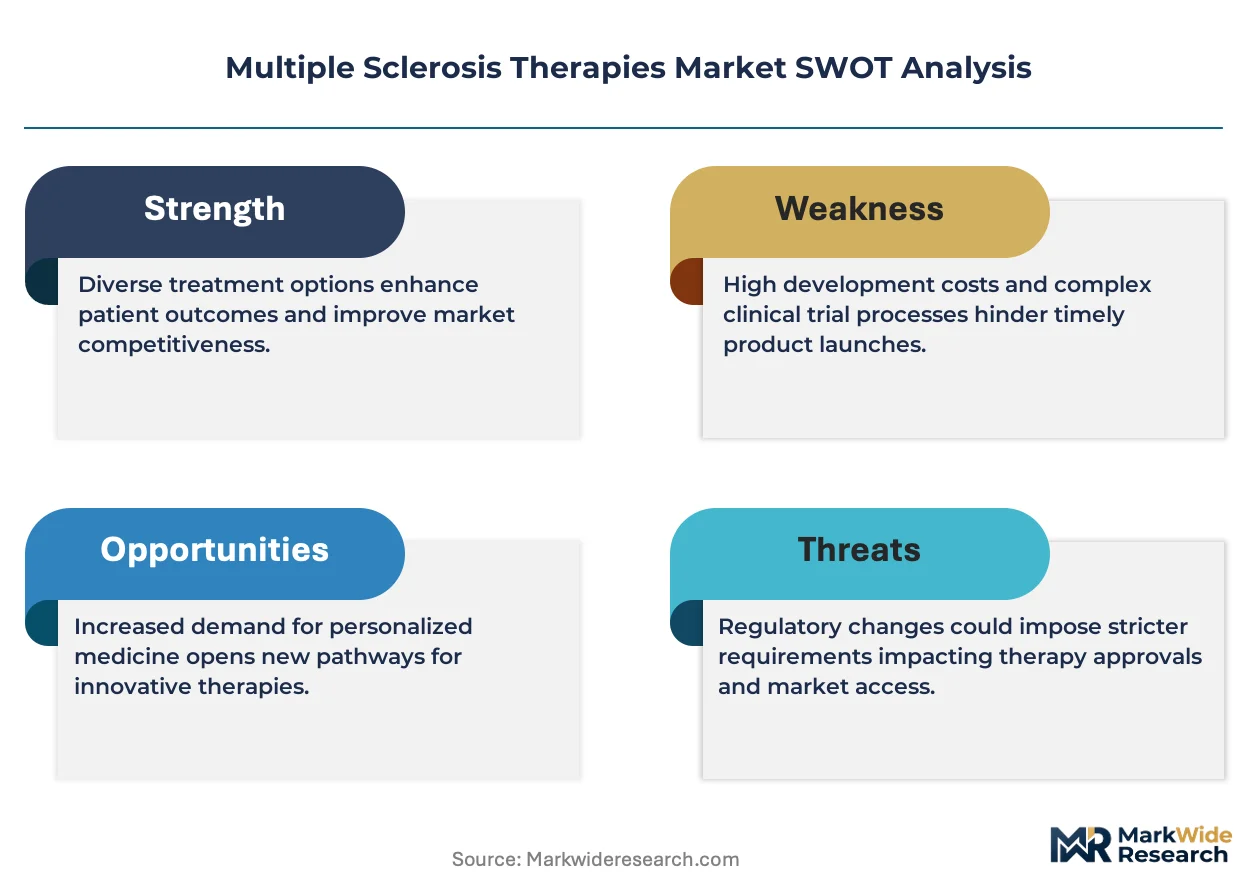
The FDA's Breakthrough Therapy designation is broadening the cost-of-entry calculus for developers of anti-CD20 and S1P receptor modulator platforms. Biogen leverages its manufacturing scale to sustain supply security for high-volume interferon and monoclonal antibody portfolios. Novartis anchors European market access through its Basel-based regulatory affairs infrastructure and EMA rapporteur relationships.
Multiple sclerosis therapies encompass pharmacological agents designed to modify disease progression, manage acute relapses, or alleviate neurological symptoms through immunomodulation, anti-inflammatory action, or neuroprotection; these compounds typically require cold-chain distribution, sterile parenteral formulation, and batch-level traceability to ensure potency and safety across extended dosing intervals. Disease-modifying treatments occupy the deepest margin pools due to chronic administration cycles and patent-protected biologic architectures, while infusion therapies command premium reimbursement tied to supervised administration protocols in hospital settings. Oral delivery modes are gaining share as patient preference shifts toward self-administration, though hepatotoxicity monitoring requirements limit their addressable population.
The FDA, EMA, and national health technology assessment bodies such as NICE in the United Kingdom shape demand through distinct evidentiary thresholds for clinical efficacy, cost-effectiveness, and comparative effectiveness against standard-of-care interferons. REACH and MDR frameworks in Europe impose stringent purity and traceability standards on parenteral biologics, raising compliance costs for manufacturers without established quality management systems. Stakeholders must monitor evolving biosimilar entry timelines and corresponding originator defense strategies across major reimbursement markets.
Market Dynamics
Biologics manufacturing concentration is reshaping competitive positioning in MS therapies, as cold-chain infrastructure requirements and EMA rapporteur relationships create asymmetric access advantages for established European operators.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated review pathways compress development timelines for anti-CD20 and S1P receptor modulator platforms, reducing regulatory uncertainty for developers targeting neurodegenerative indications.
- EMA centralized approval protocols:Statutory health insurance reimbursement frameworks in Germany create predictable demand access, anchoring European market expansion for disease-modifying treatments.
- Infusion capacity expansion:Neurology clinics across the United States are scaling monoclonal antibody administration infrastructure, enabling higher-volume patient throughput for supervised biologic regimens.
Market Restraints
- REACH and MDR compliance costs:Stringent purity and traceability standards for parenteral biologics in Europe raise barriers for manufacturers without established quality management systems.
- Hepatotoxicity monitoring requirements:Oral S1P receptor modulators require ongoing liver function surveillance, limiting their addressable population relative to parenteral alternatives.
- Batch-level cold-chain dependency:Extended dosing intervals for biologic therapies require uninterrupted temperature-controlled distribution, concentrating supply risk with specialized logistics providers.
Strategic Opportunities
- Self-administration preference shift:Oral delivery modes are capturing share from infusion protocols as patient demand for at-home dosing convenience intensifies, particularly in North American markets.
- Biosimilar entry timeline monitoring:Originator defense strategies across major reimbursement markets present white-space opportunities for follow-on biologic developers with established regulatory affairs infrastructure.
- NICE cost-effectiveness thresholds:Evidentiary requirements in the United Kingdom create openings for therapies demonstrating superior comparative effectiveness against standard-of-care interferons.
Industry Challenges
- Neuroimmunology specialist scarcity:Qualified clinical investigators for MS trials concentrate in major academic medical centers, constraining site activation for novel mechanism studies.
- Legacy interferon manufacturing retooling:Capacity conversion from platform proteins to next-generation monoclonal antibodies requires substantial capital deployment and process validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Sclerosis Therapies Market |
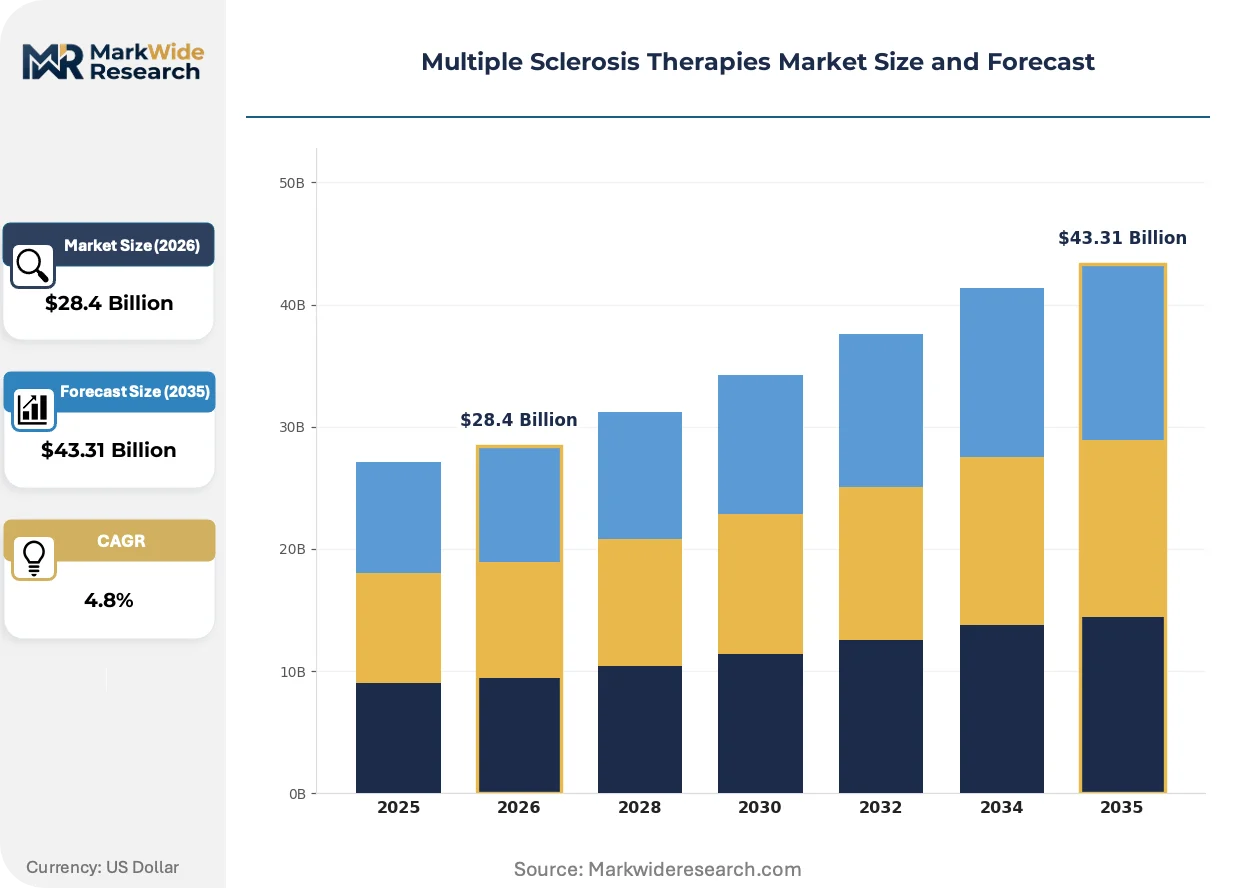
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disease-Modifying Treatments, Corticosteroids, Symptomatic Treatments, Infusion Therapies Delivery Mode: Injection, Infusion, Oral, Intranasal End User: Hospitals, Clinics, Home Care, Pharmacies Application: Relapsing-Remitting MS, Primary Progressive MS, Secondary Progressive MS, Neuropathic Pain |
| Companies Covered | Biogen, F. Hoffmann-La Roche Ltd, Novartis AG, Sanofi, Teva Pharmaceutical Industries Ltd, Merck KGaA, Bristol-Myers Squibb Company, AbbVie Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Sclerosis Therapies Market Strategic Shifts & Innovations
Patient-centric dosing models are compressing traditional site-of-care boundaries, while regulatory convergence between FDA and EMA pathways accelerates development velocity for novel immunomodulators.
Subcutaneous monoclonal antibody formulations are electrifying administration convenience expectations in the MS therapeutic landscape. Neurology practices are adopting these delivery systems at accelerating velocity to reduce infusion center burden. This shift is electrifying competitive pressure on intravenous protocols and compressing reimbursement premiums previously tied to supervised administration.
EMA's Medical Device Regulation framework is tightening traceability requirements for combination products incorporating drug-delivery devices. Manufacturers must now integrate unique device identification with batch-level pharmaceutical tracking. Infusion therapy portfolios face the steepest compliance burden, driving consolidation toward integrated device-drug developers with established European quality systems.
Site-of-care migration toward home-based administration is fragmenting traditional hospital-centered distribution networks. Specialty pharmacies are capturing dispensing volume previously controlled by hospital outpatient departments, particularly for oral disease-modifying therapies. Germany and the United States exhibit the most pronounced channel shift, where statutory reimbursement codes increasingly favor ambulatory settings.
Multiple Sclerosis Therapies Market Segmentation
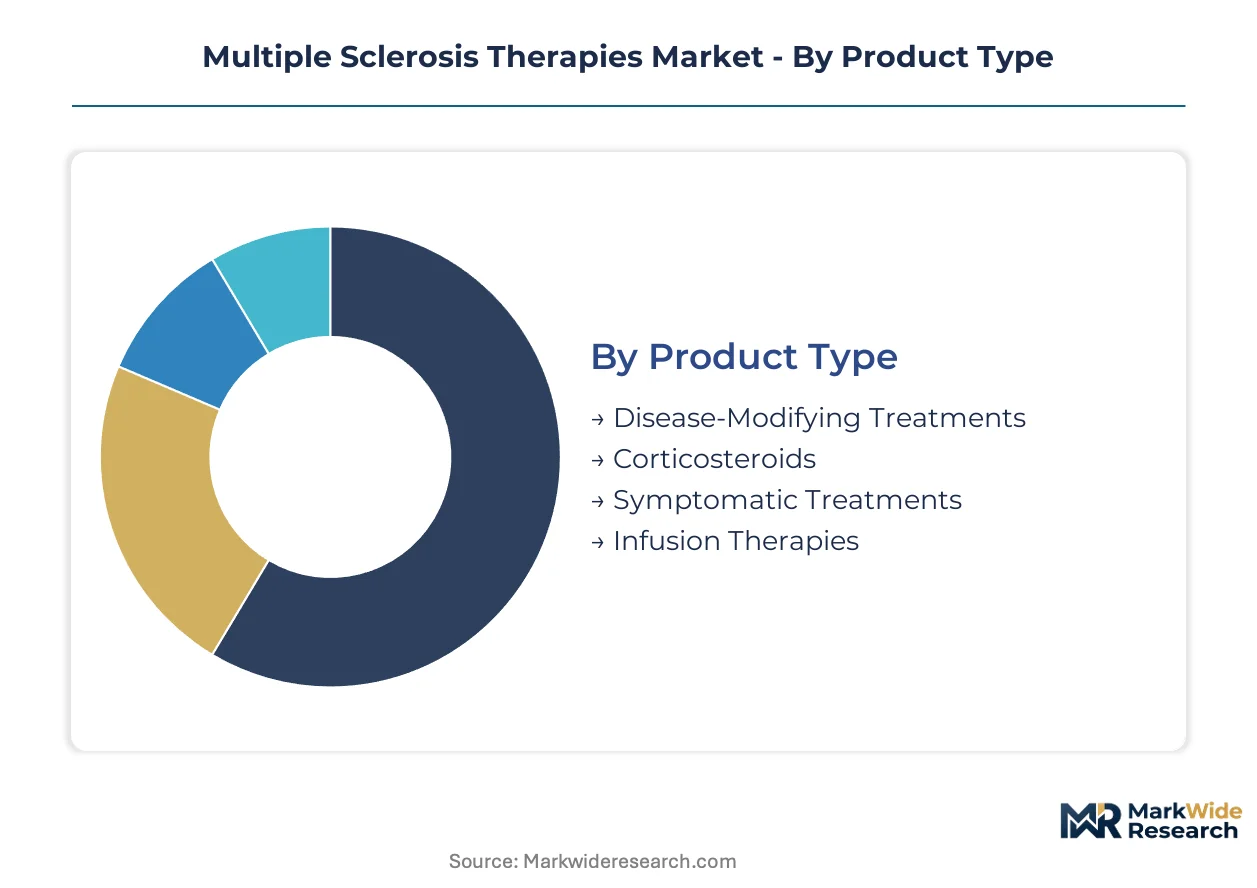
Segmentation in MS therapies reveals divergent margin structures and regulatory exposure across administration modes and care settings. Manufacturers align portfolio investments with reimbursement codes that favor chronic disease-modifying regimens over acute symptomatic management.
Product Type:
Cost tiers separate chronic immunomodulators from episodic symptom management, with biologic manufacturing scale determining competitive viability.
- Disease-Modifying Treatments:Immunomodulatory and anti-inflammatory biologics including interferons, glatiramer acetate, and monoclonal antibodies that alter disease trajectory through sustained immune system modulation. Demand concentrates in Germany and the United States where statutory reimbursement frameworks guarantee multi-year treatment coverage; patent cliffs and biosimilar entry timelines now compress originator defense windows.
- Infusion Therapies:Hospital-administered monoclonal antibodies requiring supervised delivery in certified infusion centers with cold-chain integrity and adverse event monitoring protocols. Neurology clinics across the United States are expanding capacity to capture patient throughput; EMA centralized approvals in Europe anchor predictable access through statutory health insurance mechanisms.
- Corticosteroids:High-dose methylprednisolone and related agents for acute relapse management in hospital and acute care settings.
- Symptomatic Treatments:Agents targeting spasticity, fatigue, and bladder dysfunction without disease-modifying properties.
Volume sits with Disease-Modifying Treatments; growth tilts toward Infusion Therapies.
Delivery Mode:
Patient preference for self-administration is fragmenting traditional site-of-care economics and redistributing margin capture across channel participants.
- Oral:S1P receptor modulators and fumarate derivatives enabling at-home dosing without injection burden or infusion center scheduling. Germany and the United States exhibit pronounced channel shift toward specialty pharmacy dispensing; hepatotoxicity monitoring requirements limit addressable population relative to parenteral alternatives.
- Injection:Subcutaneous and intramuscular formulations including interferon-beta and glatiramer acetate with established self-administration training protocols. Patient demand for reduced injection frequency drives platform migration toward pegylated interferons and extended-release formulations.
- Infusion:Intravenous monoclonal antibodies requiring certified administration infrastructure and batch-level cold-chain integrity.
- Intranasal:Emerging delivery modality for symptomatic agents targeting rapid onset through nasal mucosa absorption.
Injection retains installed base volume; oral modalities are climbing the fastest as convenience preferences intensify.
End User:
Site-of-care migration toward ambulatory settings is compressing hospital outpatient department margins while elevating specialty pharmacy influence.
- Home Care:Self-administered oral and injection therapies supported by home health nursing for training and monitoring. The United States leads channel shift with reimbursement codes favoring ambulatory dispensing; Germany follows with statutory health insurance protocols enabling predictable home-based access.
- Clinics:Neurology specialty practices and infusion centers managing supervised biologic administration and patient monitoring. Capacity expansion for monoclonal antibody throughput concentrates in major metropolitan clusters.
- Hospitals:Acute relapse management, diagnostic workup, and initial therapy initiation in inpatient and outpatient departments.
- Pharmacies:Retail and specialty pharmacy channels capturing oral disease-modifying therapy dispensing volume.
Clinics anchor current volume; home care settings show steepest expansion trajectory as self-administration protocols mature.
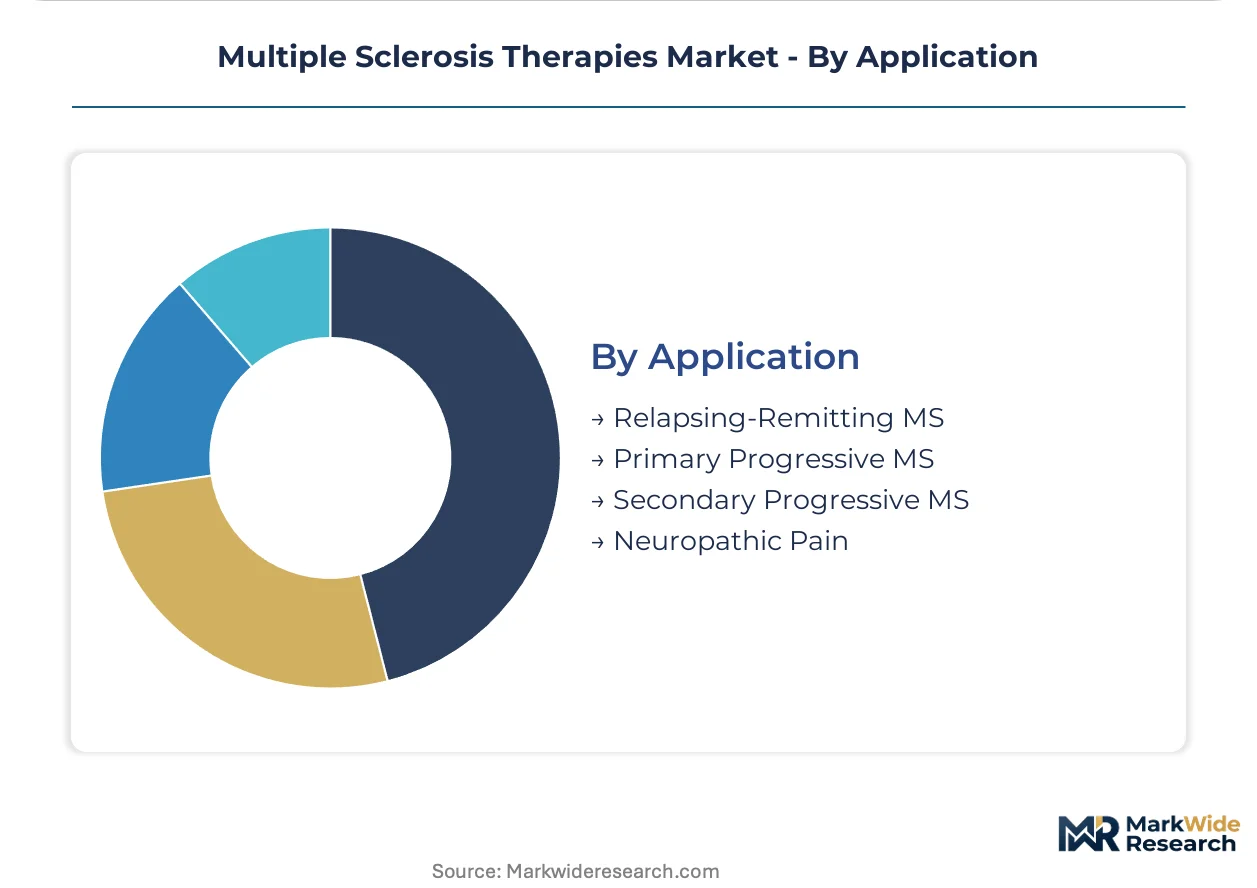
Application:
Disease subtype determines therapy selection, reimbursement eligibility, and clinical trial enrollment criteria across regulatory jurisdictions.
- Relapsing-Remitting MS:The predominant disease phenotype characterized by discrete inflammatory episodes with partial or complete recovery intervals. FDA Breakthrough Therapy designation pathways accelerate review for novel mechanisms; EMA centralized approvals create parallel European access with Germany anchoring demand concentration.
- Primary Progressive MS:Continuous neurological deterioration from onset without relapsing history, presenting limited therapeutic options and challenging trial design. Ocrelizumab and emerging anti-CD20 platforms address this underserved population with specialized labeling.
- Secondary Progressive MS:Progressive deterioration following initial relapsing-remitting course, with treatment goals shifting toward disability delay.
- Neuropathic Pain:Symptomatic management of dysesthetic extremity pain through sodium channel modulators and adjunctive agents.
Relapsing-Remitting MS commands treatment volume; Primary Progressive MS represents the fastest-growing trajectory as novel mechanisms expand labeled indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina and Boston-Cambridge corridor concentrate US biopharma development, while Basel and Munich anchor European monoclonal antibody manufacturing. These zones attract venture deployment through R&D tax credits and accelerated FDA-EMA regulatory harmonization.
United States
FDA Breakthrough Therapy designations compress neurodegenerative drug review timelines, drawing venture capital toward anti-CD20 platforms. The IRA's Medicare price negotiation provisions reshape reimbursement forecasting for chronic immunomodulators. Neurology clinics in Boston, New York, and San Francisco expand infusion capacity to capture monoclonal antibody patient throughput.
Germany
EMA centralized approvals and statutory health insurance reimbursement protocols create predictable demand access for disease-modifying treatments. The country's national pharmaceutical regulator enforces batch-level traceability standards under MDR frameworks for parenteral biologics. Manufacturing clusters in Munich and Heidelberg concentrate cold-chain infrastructure for European distribution.
Switzerland
Swissmedic's alignment with EMA rapporteur procedures accelerates market authorization for Basel-headquartered developers. Federal innovation incentives support biologics manufacturing scale-up for export markets. The Basel metropolitan area hosts integrated device-drug developers with established European quality management systems.
United Kingdom
NICE cost-effectiveness thresholds shape formulary placement for therapies demonstrating comparative effectiveness against standard-of-care interferons. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for novel S1P receptor modulators. London and Cambridge biotech clusters attract licensing deals targeting NHS procurement frameworks.
Japan
PMDA's Sakigake designation system accelerates review for first-in-class immunomodulators addressing underserved progressive MS phenotypes. METI's healthcare export promotion program supports domestic biologics manufacturers seeking Asian market expansion. The Kanto region around Tokyo concentrates clinical trial infrastructure for neuroimmunology studies.
Multiple Sclerosis Therapies Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the MS therapeutic landscape. The market structure consolidates around biologics manufacturers with established cold-chain infrastructure and EMA rapporteur relationships. Three archetypes dominate: integrated pharmaceutical conglomerates with neurology franchises, biologics specialists with monoclonal antibody platforms, and emerging developers targeting progressive MS indications. Competitive moves concentrate on portfolio diversification into subcutaneous formulations and strategic partnerships for home-based administration protocols.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and F. Hoffmann-La Roche Ltd occupy positions anchoring European market access through Basel-centered regulatory affairs infrastructure. US-based Biogen Inc. exemplifies the biologics specialist archetype with manufacturing scale sustaining supply security. These three entities represent divergent strategic postures: diversified conglomerate depth versus focused therapeutic concentration versus platform-scale manufacturing dominance.
| Leading Market Players |
|---|
| Biogen |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Merck KGaA |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
Biologics raw material indices for monoclonal antibody production cascade through cold-chain infrastructure costs into three-tier pricing structure across premium, standard, and economy levels, with batch-level traceability requirements under REACH and MDR frameworks concentrating margin capture among established European manufacturers with validated quality systems.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with premium tiers commanding surcharge multiples for expedited batch release and spot inventory clearing at discounted rates through secondary distribution channels. Price differentiation hinges on EMA rapporteur relationship depth and FDA Breakthrough Therapy designation status, while cost compression in oral S1P receptor modulators intensifies due to hepatotoxicity monitoring burden limiting addressable populations. Hospital outpatient departments exhibit highest price sensitivity as site-of-care migration shifts volume toward ambulatory settings with compressed reimbursement codes.
Supply Chain Analysis
Cell culture media supply rests on German and Swiss specialty chemical producers, with single-use bioreactor components drawing from Massachusetts and North Carolina manufacturing clusters. Raw material dependencies include recombinant protein feeds, chromatography resins, and pharmaceutical-grade excipients; single-source vulnerability concentrates in affinity column supply for anti-CD20 platform purification. Distribution runs through integrated device-drug developers with established European quality management systems, bypassing fragmented third-party logistics for temperature-sensitive parenteral biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Multiple Sclerosis Therapies Market sits in a technology-transition phase as subcutaneous monoclonal antibody formulations displace intravenous infusion protocols, compressing site-of-care economics and redistributing margin capture toward self-administration platforms.
For Market Incumbents: Acquire cold-chain logistics assets in Germany and the United States to defend against biosimilar entry timelines eroding originator pricing power; consolidate EMA rapporteur relationships and invest in subcutaneous formulation R&D to offset infusion center volume migration threatening hospital-based revenue streams. For New Entrants and Emerging Players: FDA Breakthrough Therapy designation in the United States opens a window for anti-CD20 platform developers to capture relapsing-remitting MS volume through accelerated review pathways; target primary progressive MS indications with specialized labeling strategies and partner with specialty pharmacy networks for home-based administration protocol deployment. For Investors and Strategic Acquirers: The window for entry favors biologics specialists with monoclonal antibody manufacturing scale and established European regulatory affairs infrastructure; monitor EMA centralized approval velocity as inflection indicator for portfolio valuation compression among originator-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependency and captures patient preference for at-home dosing convenience. |
| EMA Centralized Approval Pathway | Secures predictable German statutory health insurance reimbursement for disease-modifying treatments. |
| Specialty Pharmacy Partnership | Enables channel control for oral S1P receptor modulators amid site-of-care migration acceleration. |
| Biosimilar Defense Manufacturing Scale-Up | Sustains supply security and cost competitiveness against follow-on biologic entry timelines. |
| Home-Based Administration Protocol Investment | Aligns portfolio positioning with reimbursement code shifts favoring ambulatory care settings. |
Research Approach
Document review covered FDA Breakthrough Therapy designation filings, EMA centralized approval submissions, and ClinicalTrials.gov protocol registries, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from payer access databases, SEC 10-K pharmaceutical disclosures, and formulary placement records. Bottom-up patient population modeling and top-down revenue triangulation anchored segmentation outputs.
Market sizing and growth trajectory outputs reflect convergence across epidemiological prevalence data, treatment penetration rates, and pricing elasticity assumptions over the projection horizon. Segmentation dimensions modeled include disease phenotype, administration route, care setting, and regional regulatory cluster. CAGRs were derived from log-linear regression on historical therapy adoption curves, with inputs from biologics manufacturing capacity expansion timelines and EMA approval velocity indicators.
Caveats apply where biosimilar entry acceleration, Medicare price negotiation implementation, or neuroimmunology specialist supply constraints could materially shift the outlook. Forecasts reflect documented assumptions on reimbursement code stability and cold-chain infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Mexico Neurology Devices Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Australia Neurology Devices Market
Neurology
Argentina Neurology Devices Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Neurocutaneous Disorders Market
Neurology
Hepatic Encephalopathy Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
CNS Treatment and Therapy Market
Neurology
Brain Ischemia Market
Neurology
CNS Lymphoma Market
Neurology
Pediatric Neurology Device Market
Neurology
Asia-Pacific Neurology Monitoring Market