
 Neurology Devices Market | 2026-2036
Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurology Devices Market Intelligence
Project finance for hospital neuro-interventional suites is reshaping procurement patterns for high-end neurology devices. Medtronic plc leverages its integrated neurovascular portfolio to anchor catheter lab conversions across North American health systems. Boston Scientific Corporation competes through specialized deep-brain stimulation platforms that sustain recurring revenue from implantable pulse generators. Abbott Laboratories differentiates its neuromodulation line with directional lead technology that extends therapeutic precision for chronic pain applications.
Neurology devices encompass instruments and systems designed to diagnose, monitor, or treat disorders of the central and peripheral nervous systems, typically operating through electrical stimulation, mechanical intervention, or advanced imaging modalities with spatial resolution below one millimeter for functional mapping. These systems serve primary commercial purposes in reducing morbidity from stroke, managing movement disorders, and restoring sensory or motor function through implanted or external interfaces. Neurostimulators command the largest revenue pool among product categories due to long-term implant cycles and battery replacement protocols, while neurovascular devices represent the fastest-expanding segment driven by mechanical thrombectomy adoption in stroke networks. Neuroimaging devices retain mature margins from hospital capital budgets, though PET-CT hybrid systems face pressure from MRI-based functional alternatives in research institutions.
FDA breakthrough device designation compresses development timelines for novel neuromodulation systems, while EU MDR recertification demands expanded clinical evidence portfolios from manufacturers seeking CE marking retention. The FDA's evolving software-as-medical-device guidance intersects with AI-enabled neuroimaging analytics, creating parallel compliance tracks for algorithm validation and hardware safety. Stakeholders must monitor reimbursement coding decisions for remote neuromodulation programming, as payor classification of digital therapeutic add-ons will determine whether home care settings achieve viable economics for device deployment.
Market Dynamics
Mechanical thrombectomy adoption across stroke networks is compressing hospital procurement cycles for neurovascular platforms while simultaneously elevating performance benchmarks for catheter-based navigation systems.
Growth Catalysts
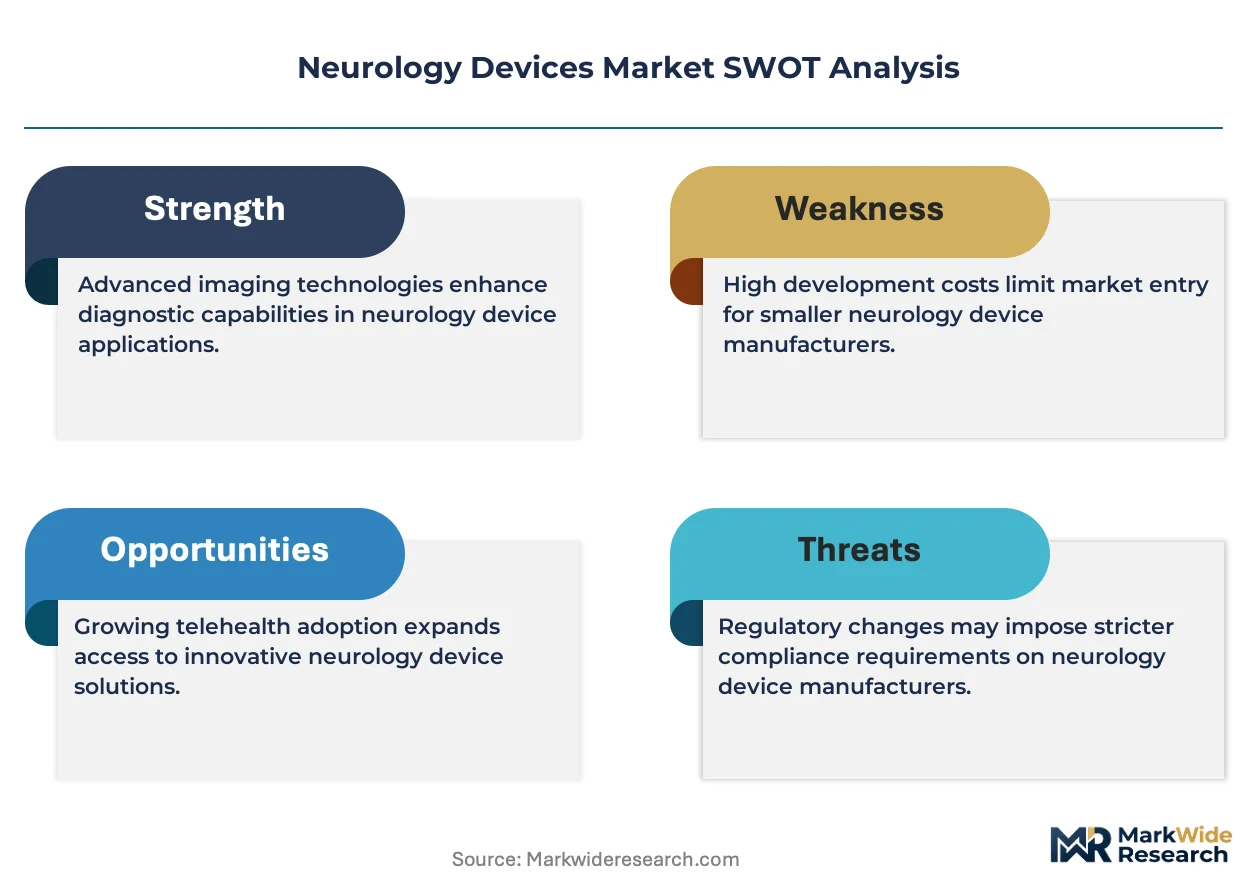
- EU MDR Recertification Pressure:Expanded clinical evidence requirements for CE marking retention are forcing manufacturers to consolidate R&D pipelines around highest-margin neuromodulation platforms, accelerating portfolio rationalization.
- Deep-Brain Stimulation Battery Replacement Cycles:Implantable pulse generators with finite lifespans create predictable recurring revenue streams that stabilize hospital capital planning for neurosurgical departments.
- University Hospital Clustering in Germany:Academic medical centers anchor multi-site clinical trial networks that compress patient enrollment timelines for novel neurostimulation therapies.
Market Restraints
- Platinum-Iridium Electrode Material Costs:Precious metal price volatility in directional lead manufacturing constrains gross margin expansion for implantable neurostimulation devices.
- FDA Software-as-Medical-Device Guidance:Parallel compliance tracks for algorithm validation and hardware safety extend development timelines for AI-enabled neuroimaging analytics.
- Functional MRI Substitution:Research institutions are redirecting capital budgets from PET-CT hybrid systems toward MRI-based functional alternatives, pressuring installed base maintenance revenue.
Strategic Opportunities
- Remote Neuromodulation Programming:Payor classification of digital therapeutic add-ons for home care settings creates viable economics for device deployment outside traditional hospital environments.
- AI-Enabled Image Analytics Convergence:Machine learning algorithms integrated with intraoperative navigation systems are reducing procedure times for deep-brain stimulation implantation.
- Stroke Network Expansion in Secondary Markets:Community hospitals without on-site neurosurgical coverage represent underpenetrated demand for portable mechanical thrombectomy platforms.
Industry Challenges
- Electrophysiology-Trained Surgical Workforce Scarcity:Limited fellowship programs producing specialists capable of directional lead placement constrains procedure volume growth.
- EU MDR Technical Documentation Burden:Legacy device families require retrospective clinical data compilation that diverts regulatory affairs resources from new product submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurology Devices Market |
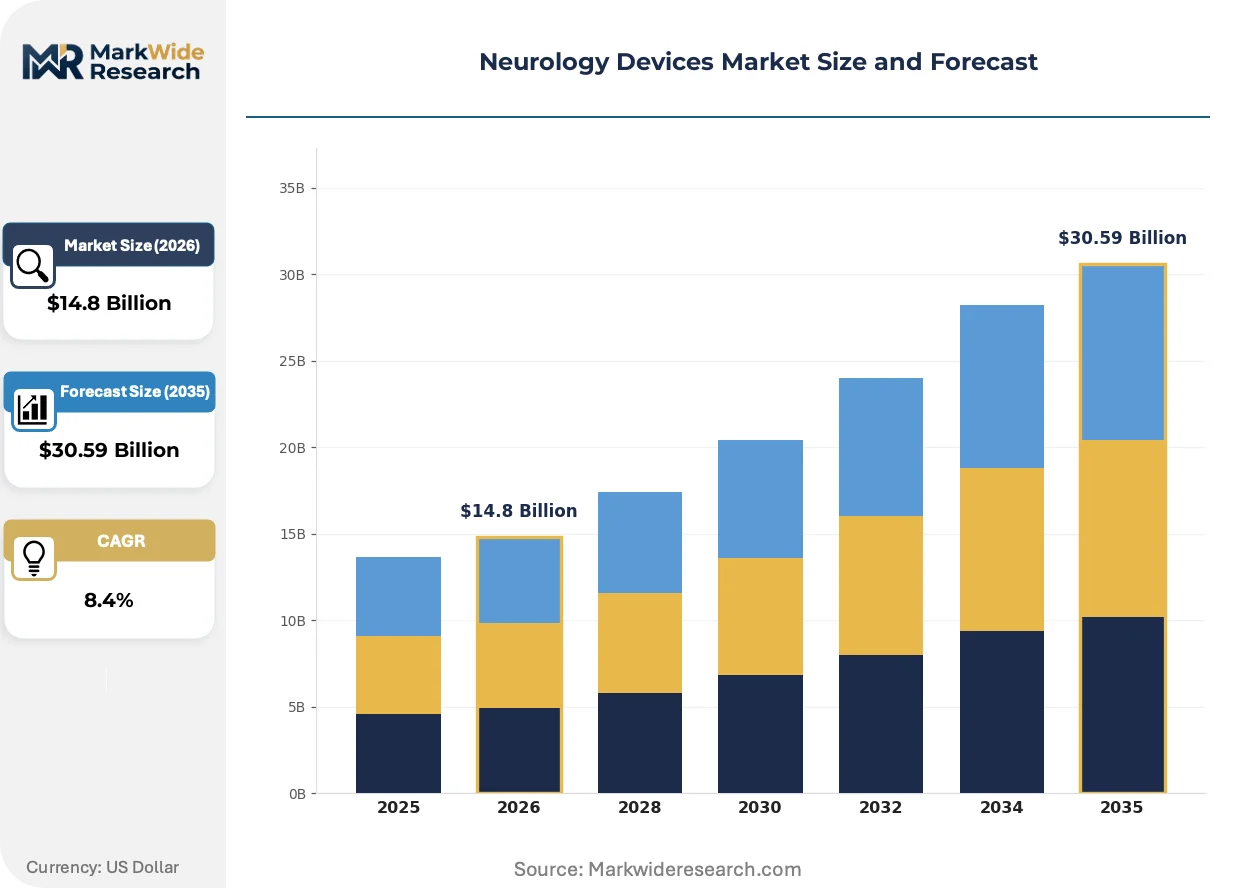
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulators, Neuroimaging Devices, Neurovascular Devices, Neuroprosthetics Application: Parkinson's Disease, Epilepsy, Chronic Pain, Stroke End User: Hospitals, Clinics, Research Institutions, Home Care Settings Technology: Electrophysiology, MRI, CT Scan, PET Scan |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Stryker Corporation, Penumbra, Inc., LivaNova PLC, Johnson & Johnson Services, Inc., Zimmer Biomet, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurology Devices Market Strategic Shifts & Innovations
Neurology device development is pivoting toward closed-loop stimulation architectures and algorithm-driven therapeutic adjustment, displacing open-loop systems that require manual programming.
Directional lead technology with independent current steering is rendering obsolete traditional cylindrical electrodes that deliver diffuse electrical fields. Academic medical centers in Germany and the United States are prioritizing these platforms for chronic pain and movement disorder programs. The shift is compressing average procedure times while expanding addressable patient populations previously excluded due to stimulation side effects.
FDA breakthrough device designation creates accelerated review pathways for novel neuromodulation systems addressing irreversibly debilitating conditions. Manufacturers must demonstrate reasonable expectation of meaningful advantage over approved alternatives through smaller premarket trials. Neurostimulator categories with existing predicate devices face compressed timelines, while first-in-class platforms encounter heightened scrutiny for long-term safety databases.
Hospital systems are consolidating neuro-interventional suite procurement through integrated service contracts spanning capital equipment, disposables, and remote technical support. Traditional device-only purchasing is yielding to multi-year partnerships that bundle training, maintenance, and technology refresh guarantees. This restructuring is most visible across United States health systems expanding comprehensive stroke center certification.
Neurology Devices Market Segmentation
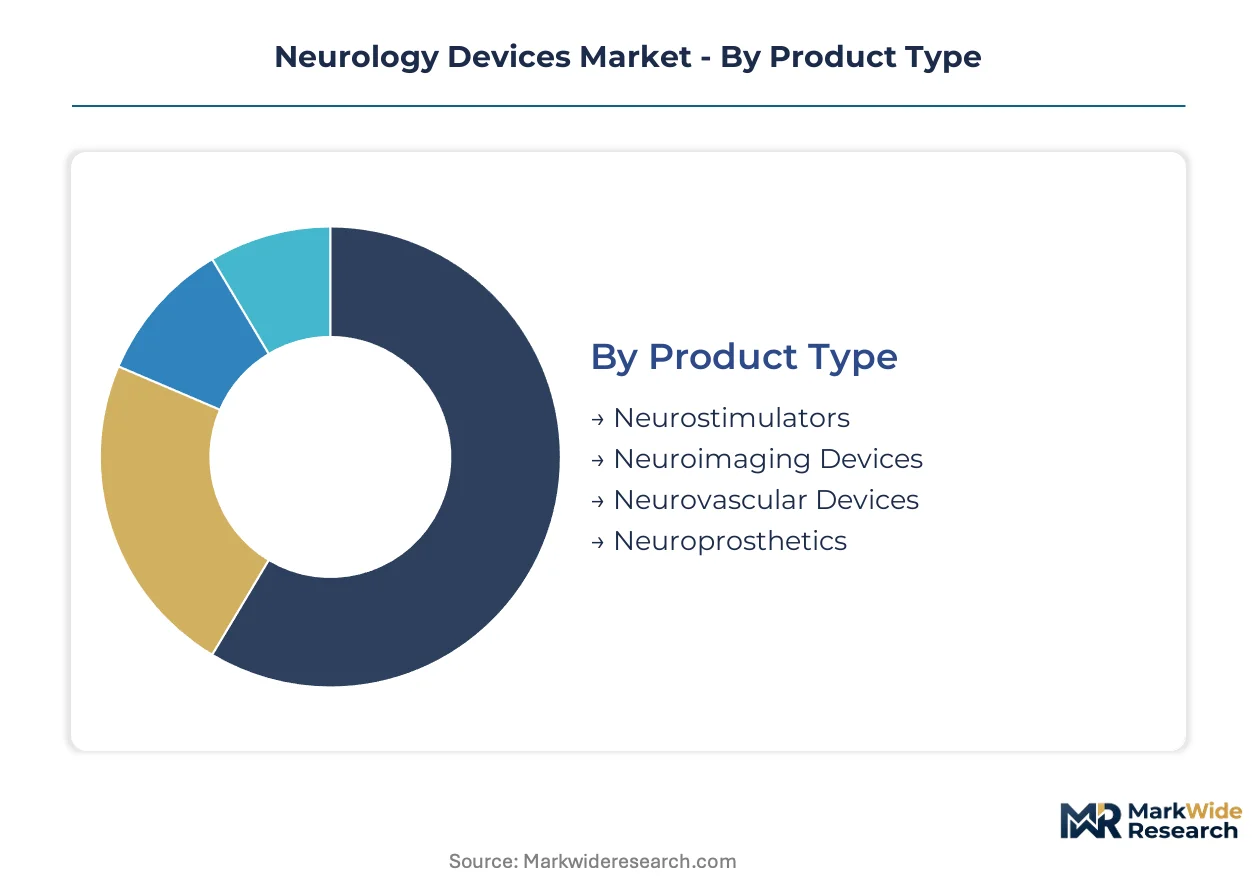
Neurology devices segment along four distinct axes that determine procurement cadence and margin structure. Product type separates capital-intensive imaging platforms from recurring-revenue implantable systems. Application and end-user dimensions dictate reimbursement pathways and regulatory scrutiny intensity.
Product Type:
Cycle times vary dramatically: neurovascular catheters turn over in months, neurostimulators in years, and imaging platforms in decades.
- Neurostimulators:Implantable pulse generators with finite battery lifespans create predictable replacement revenue streams. Demand concentrates in movement disorder centers at academic medical centers in Germany and the United States, where deep-brain stimulation volumes anchor neurosurgical department economics.
- Neurovascular Devices:Mechanical thrombectomy platforms and catheter-based navigation systems serve acute stroke intervention. Hospital systems in the United States are expanding neuro-interventional suites fastest, compressing procurement cycles for these disposable-intensive platforms.
- Neuroimaging Devices:PET-CT hybrid systems and MRI-based functional alternatives provide structural and metabolic brain mapping. Research institutions redirect capital budgets toward MRI-based platforms, pressuring installed base maintenance revenue for legacy PET-CT systems.
- Neuroprosthetics:Neural interface systems restore sensory or motor function through implanted or external electrodes. Development pipelines focus on closed-loop architectures that displace open-loop systems requiring manual programming.
Neurostimulators dominate installed base. Neurovascular devices are where expansion concentrates.
Application:
Reimbursement intensity separates chronic conditions with recurring intervention opportunities from acute events with single-episode economics.
- Stroke:Mechanical thrombectomy adoption across certified stroke networks drives neurovascular platform demand. Community hospitals without on-site neurosurgical coverage represent underpenetrated demand for portable intervention systems.
- Chronic Pain:Directional lead technology with independent current steering expands addressable populations previously excluded due to stimulation side effects. Academic medical centers prioritize these platforms for their precision advantages.
- Parkinson's Disease:Deep-brain stimulation targets motor symptoms through implanted electrodes in subthalamic nucleus or globus pallidus. Battery replacement cycles create recurring revenue that stabilizes hospital capital planning.
- Epilepsy:Responsive neurostimulation systems detect seizure onset and deliver targeted electrical intervention. FDA breakthrough device designation accelerates review pathways for novel platforms addressing drug-resistant cases.
Chronic pain anchors implantable device revenue. Stroke intervention is climbing the fastest.
End User:
Capital depth and regulatory sophistication determine which settings can support advanced neurology device deployment.
- Hospitals:Comprehensive stroke centers and academic medical centers anchor demand for integrated neuro-interventional suites. United States health systems consolidate procurement through multi-year service contracts bundling capital equipment, disposables, and remote technical support.
- Research Institutions:University hospitals in Germany anchor multi-site clinical trial networks that compress patient enrollment timelines for novel neurostimulation therapies. Functional MRI substitution pressures PET-CT hybrid system demand.
- Clinics:Outpatient settings manage chronic pain and movement disorder programming with lower capital requirements. Remote neuromodulation programming creates viable economics for device deployment outside traditional hospital environments.
- Home Care Settings:Payor classification of digital therapeutic add-ons determines whether remote monitoring and adjustment achieves viable reimbursement. Home care represents the most underpenetrated demand layer.
Hospitals dominate installed base. Home care settings are where expansion concentrates.
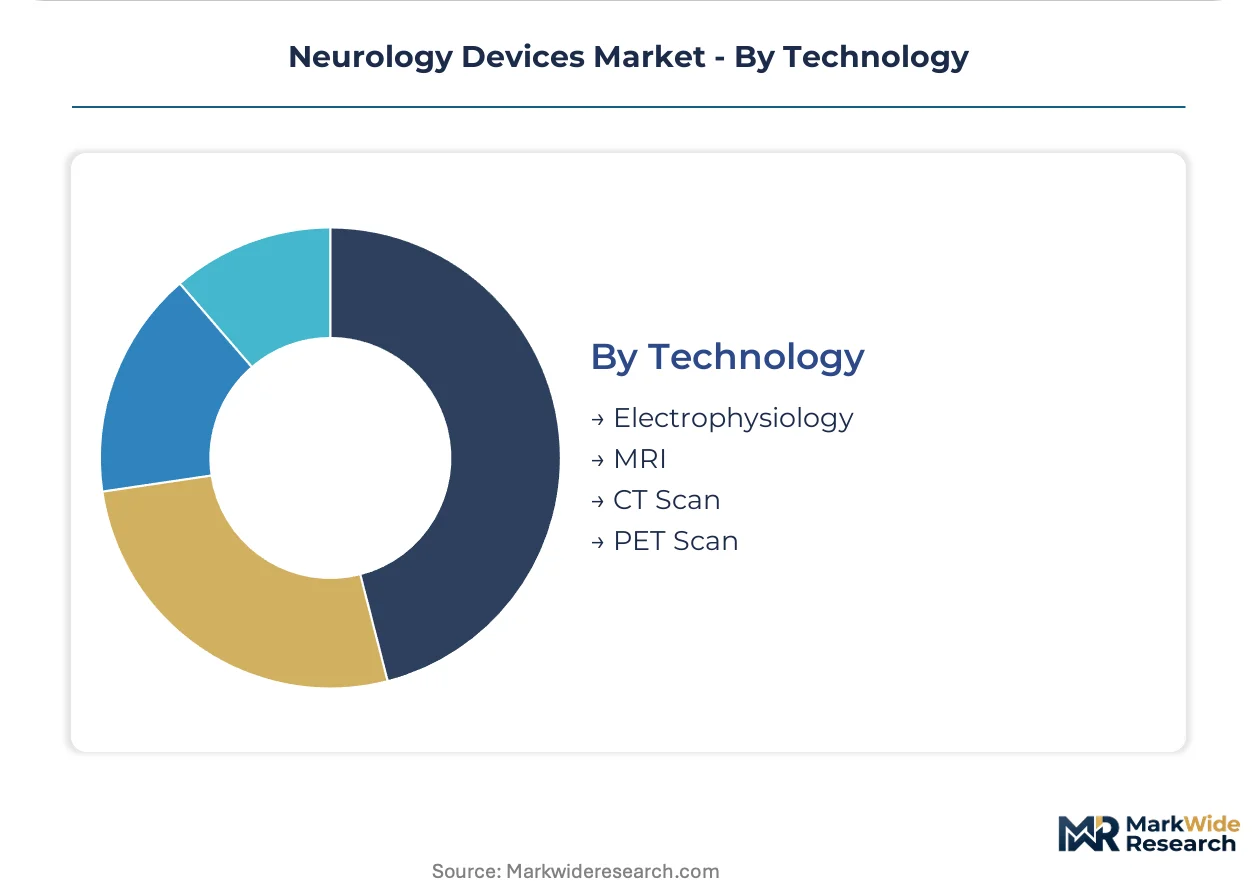
Technology:
Regulatory pathways diverge sharply between hardware-only systems and software-integrated platforms.
- Electrophysiology:Directional lead technology with independent current steering renders traditional cylindrical electrodes obsolete. Limited fellowship programs producing specialists capable of precise lead placement constrain procedure volume growth.
- MRI:Functional MRI alternatives displace PET-CT hybrid systems in research institutions. MRI-based functional mapping achieves spatial resolution below one millimeter without ionizing radiation exposure.
- CT Scan:Rapid structural imaging supports acute stroke triage and hemorrhage detection. CT angiography guides mechanical thrombectomy patient selection in time-critical settings.
- PET Scan:Metabolic imaging reveals neurodegenerative disease biomarkers and treatment response. Hybrid PET-CT systems face pressure from MRI-based functional alternatives redirecting research institution capital budgets.
Electrophysiology dominates implantable device integration. MRI is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in neurology devices reflect concentrated manufacturing in the United States and Germany against rising import dependency across Asia-Pacific markets seeking advanced neurostimulation and neurovascular platforms.
United States
Hospital systems expand neuro-interventional suites fastest here, compressing procurement cycles for mechanical thrombectomy platforms. FDA breakthrough device designation accelerates review pathways for novel neuromodulation systems. Comprehensive stroke centers in Texas, Florida, and California anchor demand for integrated catheter lab conversions.
Germany
University hospitals anchor European clinical trial networks for neuromodulation systems, compressing patient enrollment timelines. EU MDR recertification demands expanded clinical evidence portfolios from manufacturers seeking CE marking retention. The Baden-Württemberg and Bavaria clusters concentrate directional lead manufacturing and electrophysiology research.
Japan
Aging demographics drive deep-brain stimulation volumes for Parkinson's disease management. PMDA regulatory pathways for software-integrated neuromodulation platforms intersect with evolving digital therapeutic guidance. Tokyo and Osaka metropolitan areas concentrate academic medical centers prioritizing closed-loop stimulation architectures.
China
Domestic manufacturers scale production of neurovascular catheters while import dependency persists for high-end neurostimulators. NMPA review timelines for innovative neuromodulation devices compress against EU and US benchmarks. Shanghai and Beijing anchor multi-site clinical trial networks for novel neurostimulation therapies.
United Kingdom
NHS capital budgets redirect toward MRI-based functional alternatives, pressuring PET-CT hybrid system demand. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for algorithm validation. London and the Southeast concentrate research institutions adopting AI-enabled intraoperative navigation systems.
Neurology Devices Market Key Industry Players
On the supply side, the industry is consolidating around integrated neurovascular portfolios and specialized neuromodulation platforms that sustain recurring revenue through battery replacement cycles. Tiered competitive dynamics separate diversified medical technology conglomerates from focused electrophysiology specialists and emerging neurovascular pure-plays. Dominant competitive moves include portfolio rationalization around highest-margin platforms and multi-year service contracts bundling capital equipment with disposables and remote technical support.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positioning across neurovascular and neuromodulation segments. Abbott Laboratories anchors the specialized neuromodulation vector with directional lead technology. These three entities occupy positions that reflect strategic archetypes: integrated portfolio breadth, recurring revenue platform depth, and precision therapeutic differentiation respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Stryker Corporation |
| Penumbra, Inc. |
| LivaNova PLC |
| Johnson & Johnson Services, Inc. |
| Zimmer Biomet |
| Integra LifeSciences |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's directional lead manufacturing cluster concentrates capacity for platinum-iridium electrode production, granting incumbent neuromodulation suppliers pricing leverage over hospital systems negotiating multi-year service contracts. This geographic concentration of electrophysiology component fabrication feeds directly into downstream premium positioning for implantable pulse generators.
Pricing Analysis
Hospital systems anchor neurology device procurement through multi-year service contracts bundling capital equipment, disposables, and remote technical support. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms from predicate devices and legacy systems. Cost compression in standard-tier neurovascular catheters intensifies because domestic Chinese manufacturers scale production. Community hospitals without on-site neurosurgical coverage exhibit highest price sensitivity, while academic medical centers in Germany and the United States demonstrate lowest sensitivity due to research funding insulation.
Supply Chain Analysis
Contract manufacturing for implantable pulse generators concentrates with specialized EMS providers in Ireland, Costa Rica, and Malaysia serving FDA-regulated production requirements. Platinum-iridium electrode fabrication draws from precious metal suppliers in South Africa and Russia, with polymer biocompatibility testing resting on ISO-certified laboratories in Germany and Switzerland. Single-source vulnerability in directional lead micro-machining creates supply chain risk for neuromodulation platforms. Distribution runs through GPO-negotiated contracts with integrated delivery networks in the United States and university hospital procurement consortia in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital system consolidation across the United States and Germany shifts buyer power toward integrated delivery networks capable of extracting multi-year technology refresh guarantees from neurology device suppliers.
For Market Incumbents: Build regulatory data moats by compiling expanded clinical evidence portfolios for EU MDR recertification before predicate device timelines expire. Deepen backward integration into platinum-iridium electrode supply through captive sourcing agreements with South African refiners. Directional lead technology substitution from emerging electrophysiology specialists threatens premium positioning, making certification investment in closed-loop stimulation architectures the critical defensive lever. For New Entrants and Emerging Players: Community hospitals in secondary United States markets without comprehensive stroke center certification represent the most penetrable demand layer for portable mechanical thrombectomy platforms. Home care settings for remote neuromodulation programming offer white-space expansion as payor classification of digital therapeutic add-ons stabilizes. Partner with regional GPOs to bypass incumbent hospital system contracts and secure initial catheter lab conversions. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because implantable pulse generator replacement cycles create predictable cash flows independent of new patient enrollment. Acquisition targets should display FDA breakthrough device designation progress or EU MDR technical documentation completion for neuromodulation platforms. Watch FDA software-as-medical-device guidance finalization as the signal indicating which AI-enabled neuroimaging analytics platforms achieve accelerated commercial timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses premarket timelines for novel neuromodulation systems addressing irreversibly debilitating conditions. |
| EU MDR Technical Documentation | Retrospective clinical data compilation diverts regulatory resources from new product submissions for legacy device families. |
| Hospital System Partnership | Integrated service contracts bundling capital equipment, disposables, and remote support displace traditional device-only purchasing. |
| Software Companion Development | AI-enabled intraoperative navigation reduces procedure times for deep-brain stimulation implantation at academic medical centers. |
| Reimbursement Strategy | Payor classification of remote neuromodulation programming determines viable economics for home care deployment outside hospitals. |
Research Approach
Cross-validation between primary interviews with neurosurgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up triangulation across product type, application, end user, and technology segments converges with top-down macroeconomic calibration.
Calibration against historical shipment data and installed base maintenance revenue patterns informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology, with geographic regulatory cluster as an additional neurology-specific dimension. CAGRs derive from weighted average growth rates across segment-level demand curves, incorporating mechanical thrombectomy adoption velocity and battery replacement cycle predictability as industry-specific forecast inputs.
Practitioners should monitor FDA software-as-medical-device guidance finalization and EU MDR recertification timeline compression for early signals requiring forecast revision. Forecasts reflect assumptions about reimbursement coding decisions for remote neuromodulation programming and platinum-iridium price volatility. Quarterly review of hospital neuro-interventional suite expansion announcements and breakthrough device designation grants is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Transcranial Doppler Market
Neurology
Vocal Cord Paralysis Market
Neurology
China Neurology Devices Market
Neurology
Global Neuromarketing Market
Neurology
South America Neurology Monitoring Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Hepatic Encephalopathy Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Optic Neuritis Treatment Market
Neurology
Movement Disorder Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Neurology Digital Therapeutics Market
Neurology
CNS Treatment and Therapy Market
Neurology
Hydrocephalus Market
Neurology
Cognitive Neuroscience Market