
 Ischemic Cerebral Stroke Market | 2026-2036
Ischemic Cerebral Stroke Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Cerebral Stroke Market Foresight
Mechanical thrombectomy is tilting the treatment paradigm from pharmacological dissolution to endovascular clot retrieval. Stryker Corporation leverages its Trevo device portfolio to anchor North American neurointerventional share. Medtronic competes through integrated stroke care pathways that span imaging to intervention. Boehringer Ingelheim sustains relevance in the evolving landscape with its established alteplase franchise and companion diagnostics development.
Ischemic cerebral stroke refers to focal brain infarction caused by arterial occlusion, typically from thromboembolism, requiring recanalization within 4.5 to 24 hours depending on imaging-selected collateral status. The primary commercial purpose centers on restoring cerebral perfusion to salvage penumbral tissue and reduce long-term disability burden. Antithrombotics and antiplatelet agents occupy mature margin pools where generic erosion pressures pricing but volume remains substantial across secondary prevention protocols. Thrombolytics command premium positioning in hyperacute settings where time-dependent efficacy creates high willingness-to-pay. Rehabilitation devices represent the fastest-growing segment as health systems shift reimbursement toward functional outcomes and post-acute recovery metrics.
The FDA governs device premarket approval and breakthrough designation pathways that compress commercialization timelines for thrombectomy platforms. EMA's Medical Device Regulation imposes enhanced clinical evidence requirements that filter market access across European stroke centers. Japan's PMDA maintains distinct pharmacovigilance standards for anticoagulant therapies that shape regional product differentiation. Stakeholders must monitor how real-world evidence mandates from these regulators reshape post-market study obligations and competitive positioning.
Market Dynamics
Mechanical thrombectomy is virtualizing the acute stroke workflow by collapsing the time from door-to-puncture through AI-guided imaging triage and mobile stroke unit deployment. This procedural shift is redistributing capital expenditure from pharmaceutical inventory toward interventional suites and specialized training infrastructure.
Growth Catalysts
- Extended Treatment Windows:Imaging-selected collateral assessment protocols now enable mechanical thrombectomy up to 24 hours post-onset, expanding the addressable patient population beyond traditional 4.5-hour thrombolytic constraints.
- Japan's PMDA Streamlined Pathways:Accelerated approval frameworks for neurointerventional devices compress commercialization timelines and incentivize domestic manufacturing partnerships.
- Mobile Stroke Units:Prehospital CT-capable ambulances equipped with telemedicine links are compressing triage delays and routing patients directly to thrombectomy-capable centers.
Market Restraints
- Platinum-Iridium Alloy Dependency:Thrombectomy device manufacturing concentrates supply risk on South African and Russian platinum group metal refining capacity, exposing producers to input cost volatility and export restriction scenarios.
- Specialized Physician Scarcity:Neurointerventionalist training pipelines produce fewer than 150 new operators annually across the United States, creating a hard constraint on thrombectomy service expansion regardless of device availability.
- Reimbursement Compression:CMS hospital outpatient prospective payment rates for mechanical thrombectomy have flattened while device acquisition costs rise, squeezing stroke center operating margins.
Strategic Opportunities
- Germany's Digitale-Versorgung-Gesetz:Federal mandates for interoperable health data infrastructure create procurement tailwinds for AI-enabled stroke imaging platforms integrated into hospital information systems.
- Artificial Intelligence Convergence:Large-vessel occlusion detection algorithms merged with automated perfusion mapping are enabling non-specialist radiologists to initiate thrombectomy protocols without neuroradiologist confirmation.
- Post-Acute Rehabilitation:Brain-computer interface upper-limb exoskeletons represent an underpenetrated application segment where functional outcome-based reimbursement creates willingness-to-pay for premium devices.
Industry Challenges
- Neurointerventionalist Training Bottlenecks:Simulation-based credentialing programs require 500+ proctored cases for certification, limiting workforce expansion despite thrombectomy demand growth.
- Legacy PACS Integration Friction:AI stroke platforms face deployment delays from DICOM compatibility gaps and hospital cybersecurity protocols that block cloud-based image processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Cerebral Stroke Market |
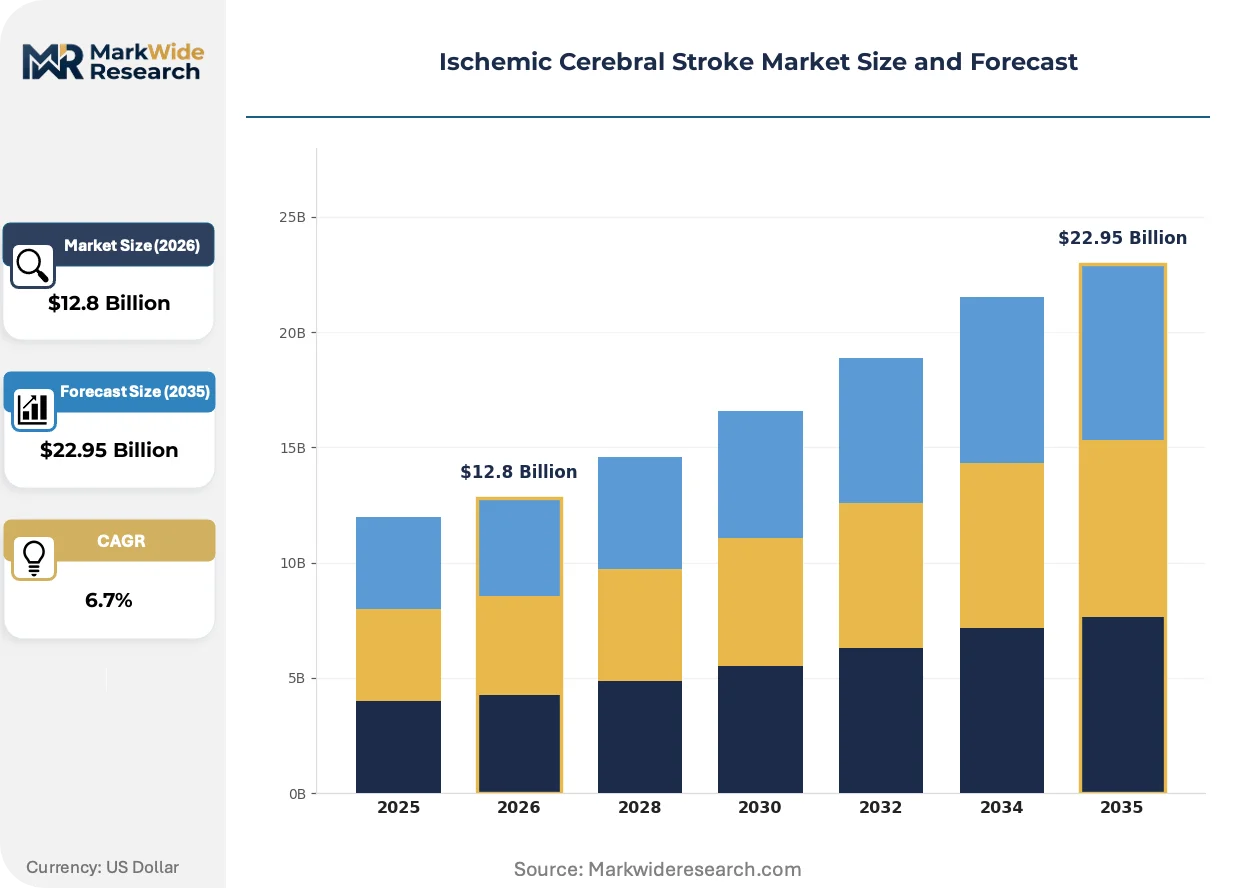
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombolytics, Antithrombotics, Antiplatelet Agents, Rehabilitation Devices Treatment Method: Intravenous Therapy, Intra-arterial Therapy, Surgical Intervention, Telemedicine Delivery Mode: Intravenous, Intra-arterial, Oral, Transdermal End User: Hospitals, Rehabilitation Centers, Homecare, Long-term Care Facilities |
| Companies Covered | Boehringer Ingelheim, Bristol-Myers Squibb, Pfizer Inc., AstraZeneca, Johnson & Johnson, Bayer AG, Stryker Corporation, Medtronic, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Cerebral Stroke Market Shifts & Advancements
Digital twin modeling of cerebral vasculature is compressing device development cycles and enabling patient-specific thrombectomy planning before arterial puncture. This computational shift is redrawing competitive boundaries between device manufacturers and software platforms.
Computed tomography perfusion software is virtualizing the penumbra assessment workflow by automating core-infarct quantification and collateral scoring. Comprehensive stroke centers in the United States are adopting these platforms at replacement pace for traditional MR-based protocols. The technology is virtualizing the neuroradiologist's gatekeeper role and accelerating treatment decisions in community hospital settings.
The FDA's breakthrough device designation pathway is compressing premarket approval timelines for aspiration catheter technologies by accepting simulated bench testing in lieu of full clinical trials. Manufacturers are responding by front-loading computational fluid dynamics validation to secure expedited entry. Large-bore aspiration platforms targeting distal medium vessel occlusions are capturing the majority of recent breakthrough designations.
Hospital purchasing consortia are consolidating neurointerventional device procurement through single-source agreements that bundle thrombectomy platforms with stroke program consulting services. Integrated delivery networks in the United States are displacing traditional distributor relationships with direct manufacturer contracts that include outcome guarantees and volume commitments. This concentration is most visible in the southeastern United States where HCA and Tenet systems dominate stroke center density.
Ischemic Cerebral Stroke Market Segmentation
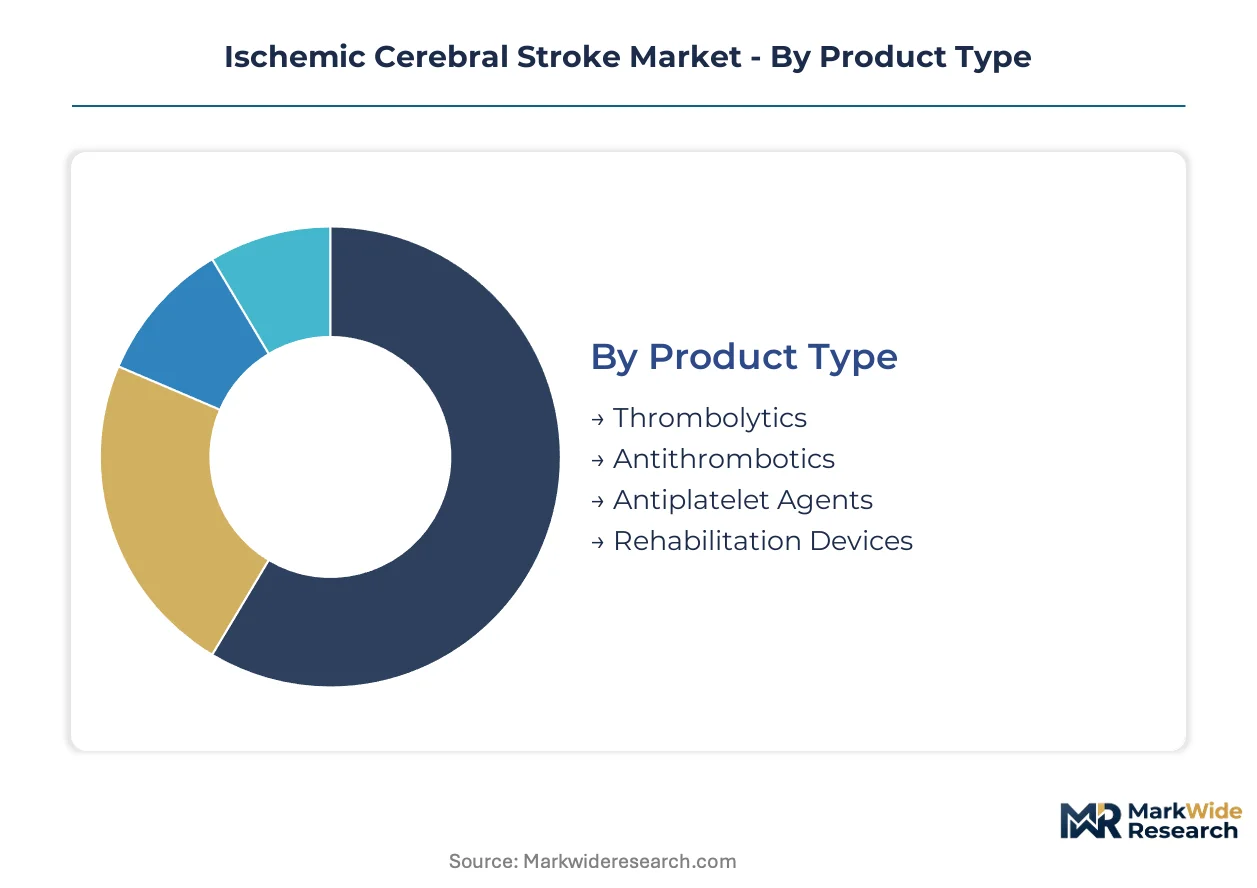
Stroke care segmentation reflects divergent margin structures across acute intervention versus chronic management. Product type stratification separates premium-priced thrombectomy devices from commoditized antithrombotics. End-user concentration determines reimbursement capture and capital deployment intensity.
Product Type:
Cost tier stratification separates acute intervention premiums from chronic therapy volume pools.
- Thrombolytics:Tissue plasminogen activator formulations dissolve clots pharmacologically within narrow therapeutic windows. United States emergency departments concentrate demand for alteplase and tenecteplase amid strict 4.5-hour onset protocols. Reimbursement rates compress under CMS bundled payment models.
- Rehabilitation Devices:Brain-computer interface exoskeletons and robotic upper-limb trainers target functional recovery metrics. German rehabilitation clinics drive adoption under Digitale-Versorgung-Gesetz outcome-linked compensation. These platforms command pricing premiums tied to disability-adjusted life year improvements.
- Antithrombotics:Direct oral anticoagulants and heparin derivatives prevent recurrent embolism in secondary prevention protocols. Volume concentrates in outpatient cardiology practices.
- Antiplatelet Agents:Aspirin, clopidogrel, and ticagrelor combinations reduce platelet aggregation post-event. Generic erosion dominates pricing dynamics.
Thrombolytics holds installed capacity. Rehabilitation Devices is rotating up the share rankings.
Treatment Method:
Application intensity varies by intervention invasiveness and facility capability requirements.
- Intra-arterial Therapy:Mechanical thrombectomy via femoral or radial access achieves direct clot retrieval in large-vessel occlusions. Japan's stroke centers expand catheterization lab capacity under PMDA streamlined pathways. Procedure volumes accelerate with 24-hour imaging-selected treatment windows.
- Telemedicine:Real-time neurologist consultation platforms extend specialist reach to rural and community hospitals. United States mobile stroke units integrate CT-capable ambulances with teleradiology links. CMS reimbursement parity with in-person consultation sustains platform economics.
- Intravenous Therapy:Systemic thrombolytic administration remains first-line where thrombectomy access is delayed. Protocol standardization limits differentiation.
- Surgical Intervention:Decompressive craniectomy addresses malignant cerebral edema refractory to medical management. Case volume concentrates at Level I trauma centers.
Intra-arterial Therapy holds installed capacity. Telemedicine is climbing the fastest in share rankings.
Delivery Mode:
Customer type preferences shape route selection between acute efficacy and chronic compliance.
- Intra-arterial:Direct arterial catheterization enables localized high-concentration drug delivery and device deployment. Comprehensive stroke centers in Germany and the United States anchor utilization. Operator scarcity constrains expansion regardless of device availability.
- Oral:Antiplatelet and anticoagulant maintenance therapy relies on patient adherence for secondary prevention. Homecare settings in Japan emphasize once-daily dosing regimens to maximize compliance.
- Intravenous:Rapid systemic absorption suits hyperacute settings where time-to-treatment drives outcomes. Emergency medical services prehospital initiation is expanding.
- Transdermal:Patch-based delivery systems address swallowing dysfunction in post-stroke dysphagia patients. Neurological rehabilitation units pilot adhesion-optimized formulations.
Intravenous holds installed capacity. Intra-arterial is rotating up the share rankings.
End User:
Geography and reimbursement structure determine site-of-care migration between acute and post-acute settings.
- Hospitals:Acute care facilities capture thrombectomy procedures and intravenous thrombolysis under diagnosis-related group reimbursement. United States integrated delivery networks consolidate purchasing through direct manufacturer contracts. Capital expenditure concentrates on interventional suite upgrades.
- Rehabilitation Centers:Inpatient and outpatient facilities manage functional recovery protocols with robotics and constraint-induced movement therapy. German federal mandates for interoperable health data infrastructure accelerate AI-enabled platform procurement.
- Homecare:Post-discharge anticoagulation monitoring and telerehabilitation extend care continuity. Japan's aging demographics expand remote monitoring deployment.
- Long-term Care Facilities:Skilled nursing settings manage secondary prevention in high-recurrence-risk populations. Medication adherence programs address polypharmacy complexity.
Hospitals holds installed capacity. Rehabilitation Centers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in neurointerventional devices and thrombolytic therapies tilt toward net import dependence in most markets, with Germany and the United States running structural deficits in platinum-group metals that concentrate manufacturing risk. Capital deployment tracks reimbursement clarity and aging demographic velocity.
United States
Medicare's hospital outpatient prospective payment system anchors thrombectomy reimbursement rates, while integrated delivery networks consolidate procurement through direct manufacturer contracts. The FDA's breakthrough device designation pathway compresses premarket approval timelines for aspiration catheter technologies. Stroke center density concentrates in the southeastern states where HCA and Tenet systems anchor interventional suite expansion.
Germany
The Digitale-Versorgung-Gesetz mandates interoperable health data infrastructure, creating procurement tailwinds for AI-enabled stroke imaging platforms. EMA's Medical Device Regulation imposes enhanced clinical evidence requirements that filter market access across European stroke centers. Comprehensive stroke centers in Bavaria and North Rhine-Westphalia anchor thrombectomy service density.
Japan
PMDA streamlined approval frameworks for neurointerventional devices compress commercialization timelines and incentivize domestic manufacturing partnerships. Aging demographics expand the addressable patient population for mechanical thrombectomy beyond traditional treatment windows. Stroke centers in the Kanto and Kansai regions concentrate catheterization lab capacity expansion.
China
NMPA regulatory harmonization with international standards accelerates market entry for foreign thrombectomy device manufacturers. Provincial health commissions in Jiangsu and Guangdong pilot volume-based procurement pilots that compress device pricing. Yangtze River Delta stroke centers anchor domestic neurointerventionalist training pipeline expansion.
United Kingdom
NHS England's specialized commissioning framework concentrates thrombectomy procedures at designated comprehensive stroke centers, creating tiered access geography. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for novel neurointerventional devices. London and Greater Manchester anchor interventional neuroradiology workforce training capacity.
Ischemic Cerebral Stroke Market Competitive Landscape
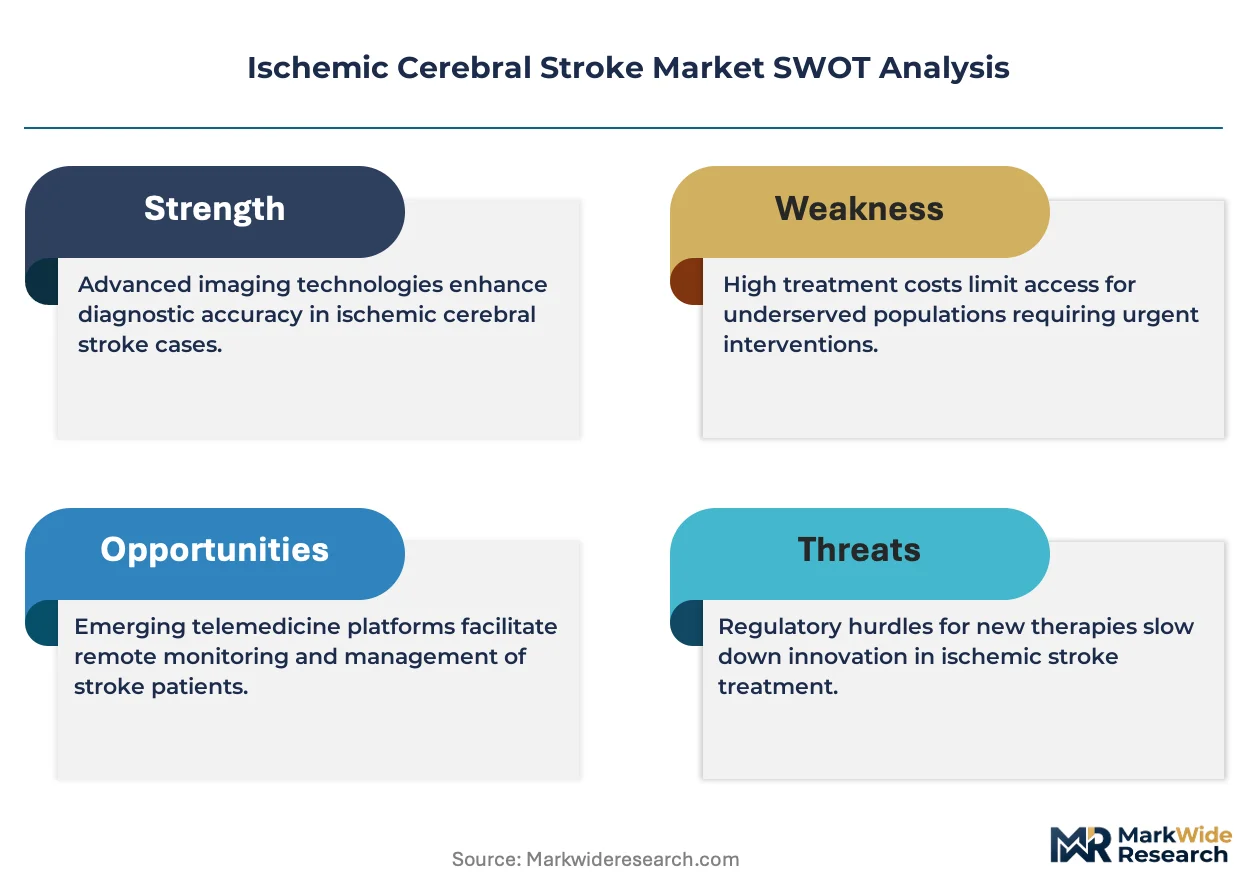
On the supply side, the industry is bifurcated between pharmaceutical incumbents with established thrombolytic franchises and device specialists capturing margin migration toward endovascular intervention. Strategic archetypes include integrated stroke pathway providers, pure-play thrombectomy device manufacturers, and anticoagulant portfolio defenders. Dominant competitive moves encompass hospital purchasing consortia consolidation and AI-enabled imaging platform integration into acute workflow.
Among pharmaceutical incumbents, Boehringer Ingelheim and Bristol-Myers Squibb occupy positions anchored by anticoagulant and antiplatelet maintenance therapy portfolios. Stryker Corporation exemplifies the device-specialist archetype, with its Trevo portfolio representing the neurointerventional pure-play competitive vector. Medtronic sits within the integrated pathway tier, spanning imaging to intervention capabilities that align with health system consolidation preferences.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Bristol-Myers Squibb |
| Pfizer Inc. |
| AstraZeneca |
| Johnson & Johnson |
| Bayer AG |
| Stryker Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
South African and Russian platinum group metal refining capacity concentrates upstream feedstock for thrombectomy device manufacturing, tethering margin pools to geopolitical export stability and alloy pricing volatility. This upstream concentration reshapes downstream pricing power across neurointerventional suites.
Pricing Analysis
Hospital purchasing consortia anchor three-tier pricing structure across premium, standard, and economy levels for thrombectomy platforms. Price differentiation rests on FDA breakthrough designation status and procedural outcome guarantees bundled with device procurement. Cost compression in standard-tier aspiration catheters is intensifying because provincial volume-based procurement pilots in China compress device pricing. Academic medical centers show least price sensitivity due to research funding offsets, while community hospitals in integrated delivery networks face greatest margin pressure.
Supply Chain Analysis
Platinum-iridium alloy feedstock draws from South Africa, Russia, and limited secondary recycling capacity in Germany and Japan. Component dependencies span nitinol hypotubes from United States precision metal fabricators, polymer extrusions from Ireland and Switzerland, and sterilization packaging from Mexico. Single-source vulnerability concentrates in South African platinum refining where electricity grid instability disrupts batch consistency. Distribution runs through manufacturer-direct contracts with integrated delivery networks displacing traditional distributor relationships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ischemic cerebral stroke market sits in a cyclical recovery phase as extended 24-hour treatment windows expand addressable patient populations and justify capital expenditure on interventional suites. This cyclical driver resets utilization assumptions across thrombectomy-capable centers.
For Market Incumbents: Harden neurointerventionalist training pipelines through simulation-based credentialing partnerships with academic medical centers to offset physician scarcity constraints. Deepen backward integration into platinum group metal sourcing through offtake agreements with South African refiners to defend against supply disruption. Lock in multi-year direct purchasing contracts with HCA and Tenet systems before competitive entrants secure southeastern United States stroke center density.
For New Entrants and Emerging Players: Establish a beachhead in brain-computer interface upper-limb exoskeletons where functional outcome-based reimbursement creates pricing premiums and incumbent concentration remains lowest. Target German rehabilitation clinics under Digitale-Versorgung-Gesetz mandates for interoperable health data infrastructure as the most penetrable procurement environment. Pursue go-to-market partnerships with AI-enabled stroke imaging platforms to bypass legacy PACS integration friction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed neurointerventional device manufacturers holding FDA breakthrough designations but lacking integrated stroke pathway capabilities. Five-to-ten year viability hinges on convergence toward software-hardware bundles that capture recurring revenue streams. Monitor PMDA streamlined approval pathway utilization rates as inflection indicator for Japanese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct manufacturer contracts with HCA and Tenet displace distributor relationships across southeastern United States stroke centers. |
| Software Companion Development | AI-enabled large-vessel occlusion detection algorithms accelerate treatment decisions without neuroradiologist gatekeeper confirmation. |
| Reimbursement Strategy | CMS hospital outpatient prospective payment rate optimization determines stroke center operating margin sustainability. |
| CE Marking Pathway | EMA Medical Device Regulation clinical evidence requirements filter market access across European comprehensive stroke centers. |
| Manufacturing Scale-Up | Domestic catheter production partnerships under PMDA streamlined pathways compress commercialization timelines for Japan entry. |
Research Methodology
Desk research of FDA 510(k) filings, EMA medical device registration databases, and hospital procurement contract disclosures preceded structured interviews with neurointerventionalists, stroke program directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare claims data, NMPA regulatory harmonization notices, and PMDA approval pathway documentation. Bottom-up procedure volume modeling and top-down device revenue triangulation anchored market sizing across the analysis window.
Assumptions held fixed include regulatory pathway timelines and reimbursement rate structures, while variables spanned neurointerventionalist training pipeline expansion rates and platinum group metal price trajectories. Segmentation dimensions modeled encompassed product type, treatment method, delivery mode, and end-user facility tier alongside regional regulatory cluster differentiation. CAGRs derived from logistic adoption curve fitting to extended treatment window protocol diffusion. Industry-specific inputs included mobile stroke unit deployment trajectories and AI imaging platform penetration rates.
Sensitivities concentrate around PMDA export restriction scenarios and CMS reimbursement compression beyond current outpatient prospective payment rates. Forecasts reflect documented assumptions regarding physician workforce expansion and device manufacturing capacity scaling. Cross-checking against Japan Stroke Society procedure registry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Chile Neurology Devices Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Labyrinthitis Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Arachnoiditis Treatment Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Intracranial Aneurysm Market
Neurology
Germany Neurology Devices Market
Neurology
Italy Neurology Devices Market
Neurology
Diabetic Neuropathy Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
South America Neurology Monitoring Market