
 India Neurology Devices Market | 2026-2036
India Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Neurology Devices Market Foresight
Multi-source procurement of neurostimulation components is broadening across Indian hospital chains and device distributors. Medtronic PLC leverages its deep channel presence to sustain implantable device supply lines across tier-1 cities. B. Braun Melsungen AG anchors its competitive stance through specialized neurosurgical instrument portfolios tailored to Indian procedural volumes.
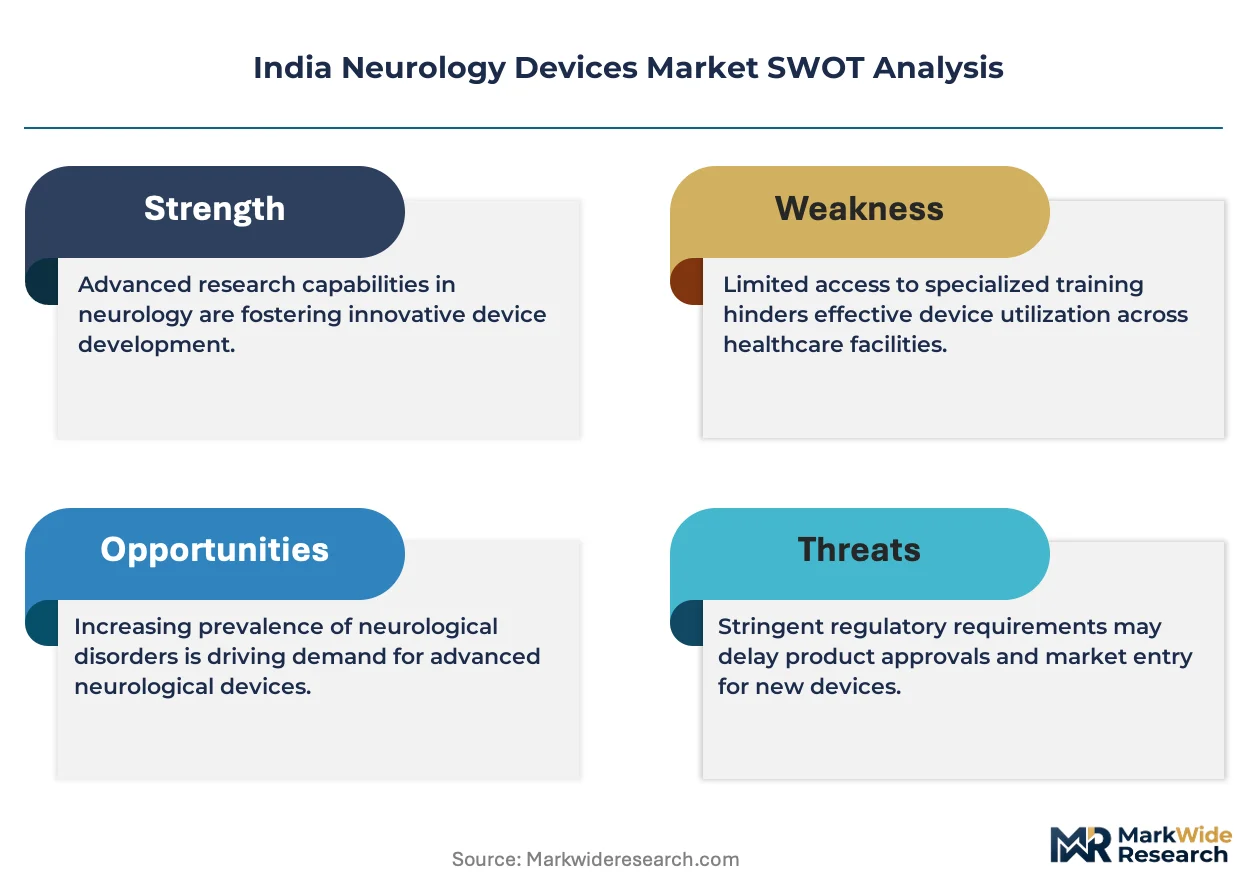
Neurology devices encompass instruments, implants, and electronic systems engineered for diagnosis, monitoring, or intervention within the central and peripheral nervous systems, typically requiring biocompatibility certifications and precision manufacturing tolerances below 50 microns. These systems serve clinical objectives ranging from seizure localization to deep-brain electrical modulation. Neurostimulation devices command the steepest margin pools given reimbursement complexity and long implant lifecycles. Non-invasive technology segments attract accelerated capital deployment as outpatient neurology expands across Indian metro corridors.
CDSCO governs device registration and clinical trial protocols for neurology implants, while BIS certification mandates electrical safety and electromagnetic compatibility standards for imported and domestically manufactured EEG and MRI systems. The PLI scheme for medical electronics reduces import dependency for core components but requires manufacturers to align with both CDSCO quality audits and BIS technical specifications. Stakeholders must monitor how state-level hospital procurement policies reconcile central subsidy programs with institutional buying preferences.
Market Dynamics
Stroke management protocols in tertiary care hospitals are expanding device utilization across India's neuro-specialty infrastructure. The PLI scheme for medical electronics is accelerating domestic manufacturing capacity while CDSCO registration requirements reshape competitive entry barriers.
Growth Catalysts
- PLI scheme subsidies:The medical electronics production-linked incentive reduces import dependency for core neurology device components and attracts capital into domestic EEG and neurostimulation assembly lines.
- Tertiary hospital expansion:Neuro-specialty clusters in Maharashtra and Karnataka are procuring advanced intraoperative monitoring systems to support rising surgical volumes.
- Deep-brain modulation protocols:Movement disorder centers are embedding implantable pulse generators into standard Parkinson's care pathways, extending device lifecycles.
Market Restraints
- Biocompatibility certification delays:CDSCO quality audits for implantable neurology devices extend commercialization timelines by twelve to eighteen months versus comparable ASEAN markets.
- Precious metal input volatility:Platinum-iridium electrodes and titanium casings expose manufacturers to commodity price swings that compress margin pools on neurostimulation systems.
- Concentrated component sourcing:Precision microelectromechanical systems for neural sensing remain captive to East Asian foundry capacity, creating single-source vulnerability.
Strategic Opportunities
- Outpatient neurology corridors:Non-invasive technology segments attract capital deployment as ambulatory EEG and transcranial stimulation expand across Indian metro corridors.
- BIS-CDSCO alignment:Manufacturers achieving concurrent electrical safety and electromagnetic compatibility certification unlock faster hospital procurement cycles in government tenders.
- State-level procurement integration:Tamil Nadu and Telangana are consolidating neuro-device purchasing through centralized medical equipment corporations, creating volume aggregation channels.
Industry Challenges
- Neuro-electrophysiology technician scarcity:Qualified operators for intraoperative neuromonitoring remain concentrated in six urban centers, constraining surgical throughput expansion.
- Legacy hospital IT integration:Digital neurology platforms must interface with heterogeneous electronic health record systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Neurology Devices Market |
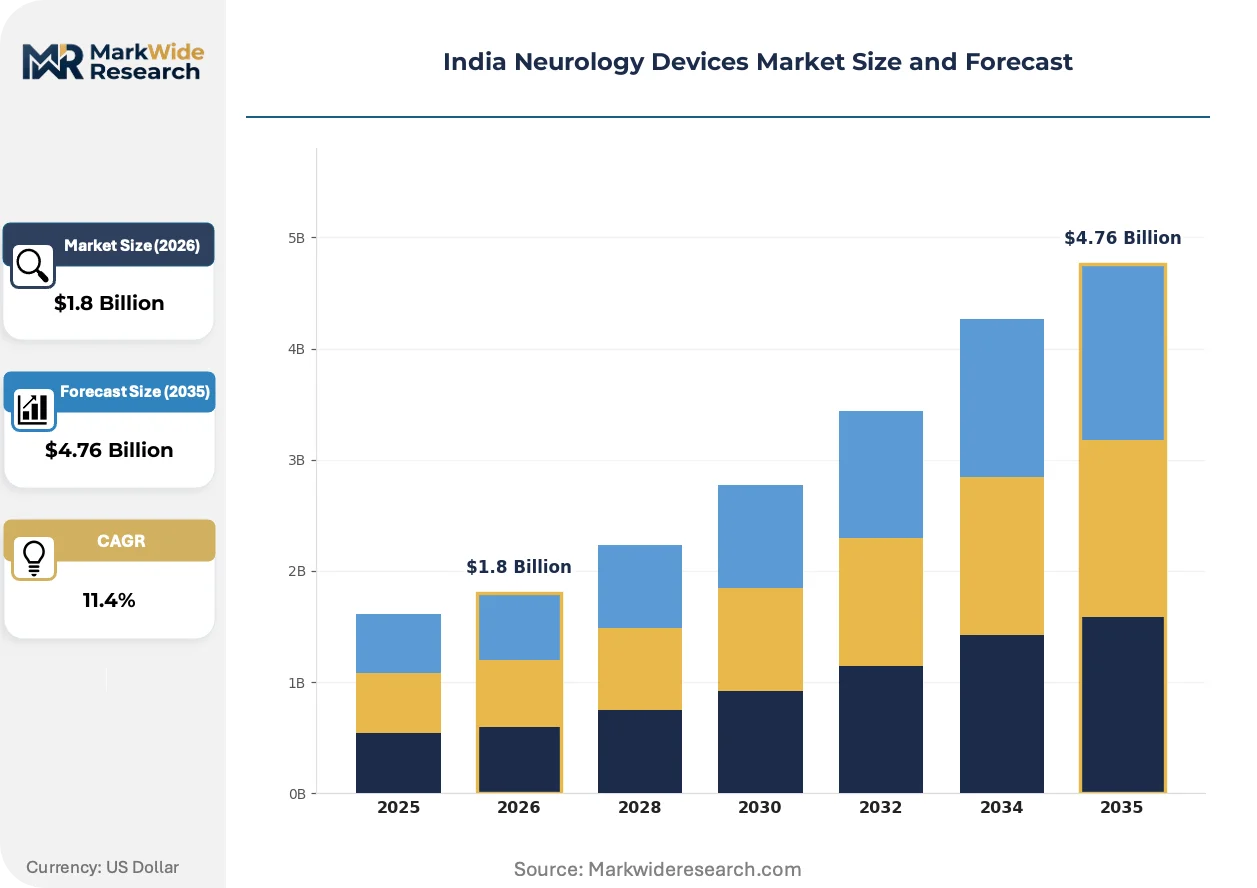
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
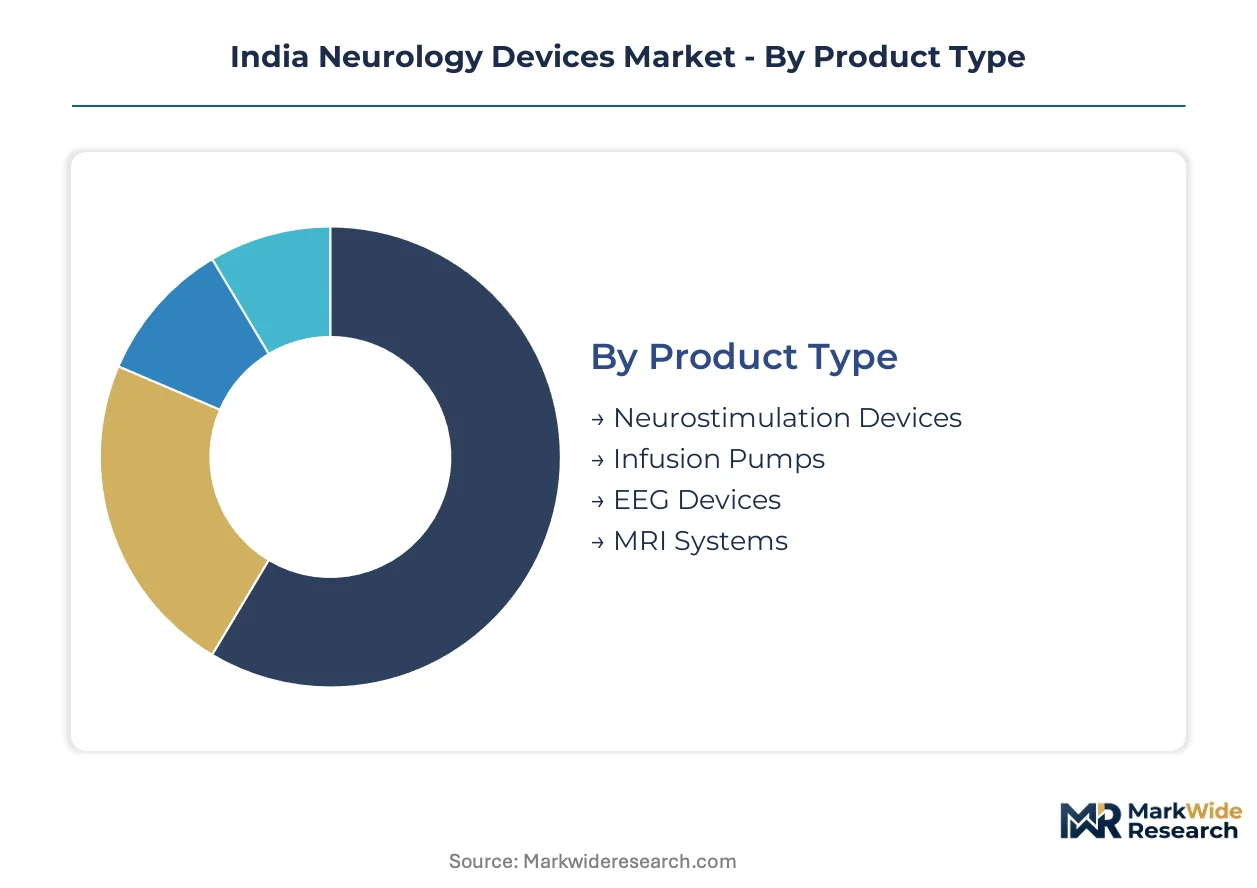
| Segmentation | Product Type: Neurostimulation Devices, Infusion Pumps, EEG Devices, MRI Systems End User: Hospitals, Clinics, Specialty Centers, Research Institutions Technology: Invasive, Non-Invasive, Robotic, Wearable Application: Stroke Management, Epilepsy Treatment, Pain Management, Neurorehabilitation |
| Companies Covered | Medtronic PLC, Johnson & Johnson, B. Braun Melsungen AG, Smith & Nephew, MicroPort Scientific Corporation, Boston Scientific Corporation, Nihon Kohden Corporation, Abbott Laboratories, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Neurology Devices Market Shifts & Advancements
Neurology device architecture is converging toward closed-loop sensing and modulation systems that reduce physician intervention cycles. This shift is compressing the boundary between diagnostic and therapeutic modalities while rewriting procurement specifications for hospital capital committees.
Closed-loop neurostimulation platforms are integrating real-time biomarker detection with adaptive output adjustment. Movement disorder centers in Mumbai and Bengaluru are piloting these systems for Parkinson's disease management. The technology is integrating seizure prediction algorithms that preempt electrical discharge events before clinical manifestation, reducing emergency department utilization.
CDSCO has tightened clinical trial protocol requirements for novel neurology implants, mandating extended follow-up periods for biocompatibility validation. This regulatory friction is favoring established manufacturers with existing trial infrastructure. Implantable pulse generator categories face the steepest compliance burden, with registration dossiers now requiring electromagnetic compatibility documentation under BIS standards.
Hospital procurement committees are unbundling device acquisition from long-term service contracts, compressing vendor lock-in periods. State-level medical equipment corporations in Maharashtra and Karnataka are leading this disintermediation, separating hardware purchase from technical support agreements. Neurodiagnostic equipment distributors are responding with modular pricing structures that decouple capital expenditure from software maintenance fees.
India Neurology Devices Market Segmentation
Neurology device procurement in India follows distinct pathways shaped by reimbursement tiers, procedural complexity, and institutional capacity. Hospital administrators weigh capital intensity against patient throughput, while clinicians prioritize diagnostic precision and therapeutic efficacy.
Product Type:
Purchase committees evaluate devices through a lens of lifecycle cost and service dependency, with implantable systems demanding extended vendor relationships.
- Neurostimulation Devices:Implantable pulse generators and electrode arrays deliver electrical modulation for movement disorders and chronic pain. Maharashtra's neuro-specialty clusters in Mumbai and Pune are embedding these into standard Parkinson's care pathways, extending replacement cycles through programmable settings.
- EEG Devices:Electroencephalography systems capture cortical electrical activity for seizure localization and sleep disorder diagnosis. Karnataka's tertiary hospitals are upgrading to high-density array configurations, driven by epilepsy surgery volume expansion in Bengaluru.
- Infusion Pumps:Programmable drug delivery systems administer intrathecal analgesics and antispasmodics with precision dosing protocols.
- MRI Systems:Magnetic resonance imaging platforms with neuro-specific coils enable structural and functional brain mapping.
Neurostimulation devices lead on scale; EEG devices lead on momentum.
End User:
Facility type determines reimbursement pathways and capital allocation authority, with government teaching hospitals operating under distinct procurement frameworks.
- Hospitals:Tertiary care institutions with neurosurgery departments command the highest device utilization rates. Stroke management protocols in Maharashtra and Karnataka are driving intraoperative monitoring system purchases.
- Specialty Centers:Dedicated neurology and movement disorder facilities concentrate advanced therapeutic device deployment.
- Clinics:Outpatient neurology practices are expanding ambulatory diagnostic capacity across Indian metro corridors.
- Research Institutions:Academic medical centers conduct clinical trials for novel neurology implants under CDSCO protocols.
Hospitals dominate installed base; specialty centers are climbing the fastest.
Technology:
Technical architecture shapes regulatory pathway complexity and operator training requirements, with invasive systems facing steeper CDSCO scrutiny.
- Invasive:Implantable systems requiring surgical placement, including deep-brain stimulators and responsive neurostimulation devices.
- Non-Invasive:External therapeutic and diagnostic platforms, including transcranial magnetic stimulation and conventional EEG, are expanding across outpatient corridors.
- Robotic:Computer-assisted surgical systems for stereotactic electrode placement and tumor resection.
- Wearable:Ambulatory monitoring devices for seizure detection and sleep architecture analysis.
Non-invasive technology leads on deployment velocity; invasive systems lead on revenue per procedure.
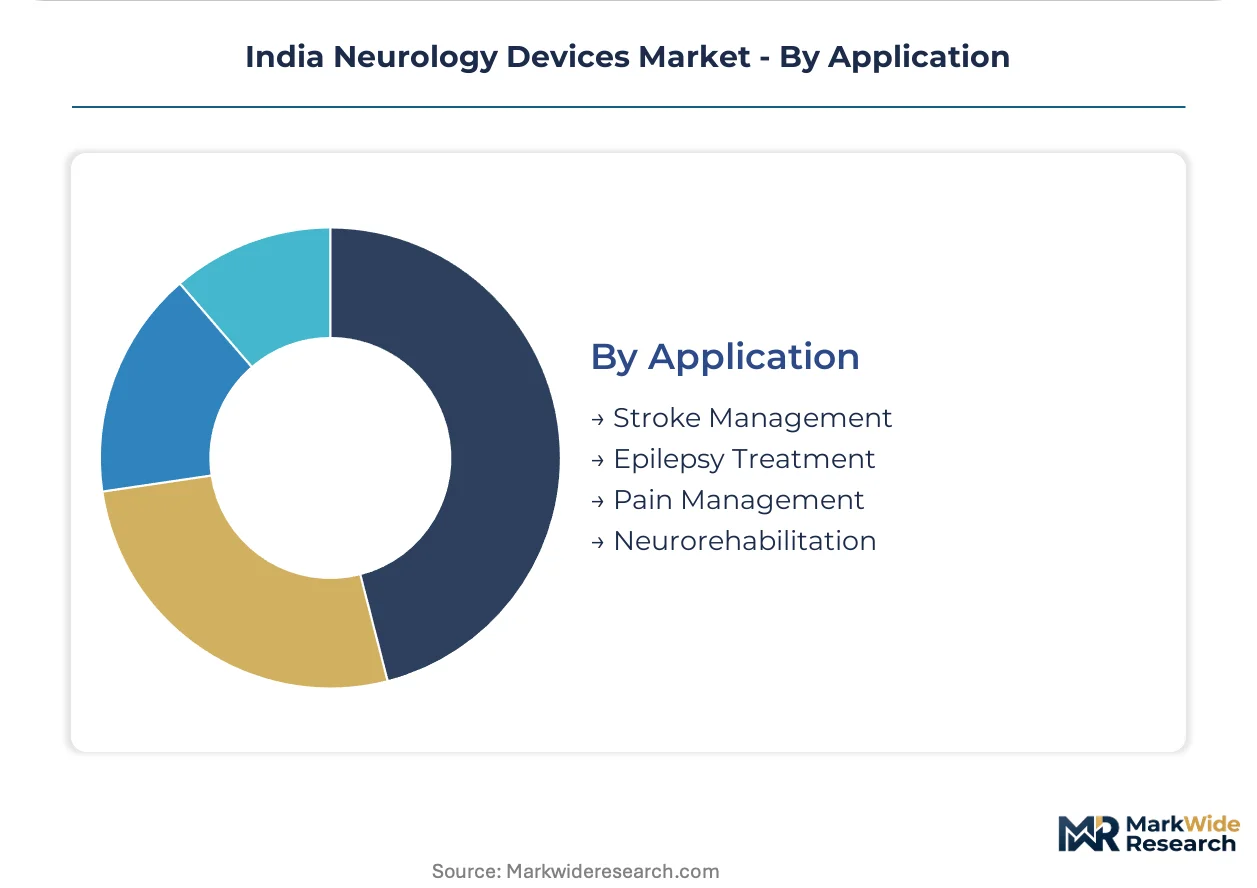
Application:
Clinical indication determines device selection criteria, with acute stroke protocols prioritizing speed and epilepsy surgery demanding precision localization.
- Stroke Management:Acute intervention and rehabilitation protocols utilize thrombectomy devices, intracranial pressure monitors, and neurorehabilitation robotics. Tertiary care expansion in Tamil Nadu and Telangana is accelerating device procurement.
- Epilepsy Treatment:Seizure localization and neuromodulation therapies require stereoelectroencephalography and responsive neurostimulation systems.
- Pain Management:Spinal cord stimulation and intrathecal drug delivery address chronic neuropathic conditions.
- Neurorehabilitation:Robotic exoskeletons and brain-computer interfaces support motor recovery post-stroke and spinal cord injury.
Stroke management leads on institutional spending; neurorehabilitation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives under India's PLI scheme are compressing the cost-of-compliance gap that previously favored imported neurology devices, redirecting capital toward Maharashtra and Karnataka assembly corridors.
Maharashtra
Mumbai and Pune neuro-specialty clusters are embedding deep-brain stimulators into standard Parkinson's care pathways. CDSCO registration requirements for implantable devices extend commercialization timelines but favor established manufacturers with existing trial infrastructure. The state's tertiary hospitals are procuring advanced intraoperative monitoring systems to support rising surgical volumes.
Karnataka
Bengaluru's epilepsy surgery centers are upgrading to high-density EEG array configurations, driven by rising procedural volumes. BIS certification mandates electrical safety standards for domestically manufactured systems. The state's medical device parks are attracting assembly investments for neurostimulation components under PLI scheme subsidies.
Tamil Nadu
Chennai-based hospital networks are consolidating neuro-device purchasing through centralized medical equipment corporations. State-level procurement policies are reconciling central subsidy programs with institutional buying preferences. Stroke management protocols in tertiary care institutions are expanding thrombectomy device utilization.
Telangana
Hyderabad's movement disorder centers are piloting closed-loop neurostimulation platforms for adaptive output adjustment. CDSCO quality audits for biocompatibility validation are reshaping competitive entry barriers. The state's neuro-rehabilitation corridors are deploying robotic exoskeletons for post-stroke motor recovery.
Delhi-NCR
Government teaching hospitals in the capital region operate under distinct procurement frameworks for neurodiagnostic equipment. DGFT import regulations intersect with PLI scheme domestic content requirements. Research institutions are conducting clinical trials for novel neurology implants under extended CDSCO follow-up protocols.
India Neurology Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue non-invasive outpatient corridors and modular pricing structures. The market structure concentrates around implantable system manufacturers with deep channel presence and specialized neurosurgical instrument portfolios. Three archetypes dominate: multinational device conglomerates with registration infrastructure, mid-scale domestic assemblers leveraging PLI subsidies, and precision component specialists serving East Asian foundry networks. Competitive moves center on unbundling hardware acquisition from long-term service contracts and achieving concurrent BIS-CDSCO certification for faster government tender cycles.
Among multinational device conglomerates, Medtronic PLC and Boston Scientific Corporation exemplify the established-tier archetype with deep channel presence across Indian tier-1 cities. B. Braun Melsungen AG anchors the specialized instrument portfolio segment. These entities represent varying responses to regulatory friction: some compress commercialization timelines through existing trial infrastructure, others align with state-level procurement consolidation in Maharashtra and Karnataka.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Smith & Nephew |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Nihon Kohden Corporation |
| Abbott Laboratories |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors with generational presence in Mumbai and Bengaluru medical device corridors anchor pricing discipline through captive relationships with Maharashtra neuro-specialty hospitals, compressing margin leakage while PLI scheme subsidies reshape domestic assembly economics.
Pricing Analysis
Distributor margins spanning fifteen to twenty-two percent separate implantable neurostimulation systems from diagnostic EEG hardware across Indian hospital procurement cycles. Three-tier pricing structure across premium, standard, and economy levels tracks BIS-CDSCO concurrent certification status, with fully certified systems commanding twelve to eighteen month payback premiums. Cost compression in economy-tier EEG devices is intensifying because state-level medical equipment corporations aggregate volume tenders. Government teaching hospitals exhibit highest price sensitivity; private neuro-specialty chains in Karnataka demonstrate lowest.
Supply Chain Analysis
Skilled electrophysiology technician scarcity in Hyderabad and Chennai medical device parks constrains domestic assembly line expansion for precision neurostimulation components. Manufacturing gravity centers on China for platinum-iridium electrode foundry capacity, Germany for precision microelectromechanical systems, and domestic Maharashtra corridors for final device integration under PLI scheme subsidies. Raw material dependencies span titanium casings, biocompatible polymers, and rare-earth magnetic elements. Single-source vulnerability in East Asian MEMS foundry capacity threatens component security. Distribution runs through authorized hospital equipment dealers with CDSCO import license holdings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's neurology device market operates as a regulatory compounder where CDSCO's extended biocompatibility validation protocols for implantable systems create durable competitive moats favoring established trial infrastructure.
For Market Incumbents: Hedge platinum-iridium input exposure through long-term offtake agreements with East Asian precious metal refiners before commodity volatility compresses neurostimulation margin pools. Fortify position by deepening backward integration into domestic EEG assembly lines under PLI scheme subsidies, insulating against state-level procurement consolidation in Tamil Nadu and Telangana. For New Entrants and Emerging Players: Enter via outpatient neurology corridors where ambulatory EEG and transcranial magnetic stimulation devices face lower CDSCO registration barriers than implantable systems. Target clinic segments in Delhi-NCR and Bengaluru metro corridors with modular pricing structures that decouple hardware capital expenditure from software maintenance fees. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale domestic assemblers leveraging PLI subsidies but lacking BIS-CDSCO concurrent certification. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Monitor CDSCO registration dossier approval velocity as inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| BIS-CDSCO Concurrent Certification | Achieving simultaneous electrical safety and electromagnetic compatibility approval unlocks faster government tender cycles in Maharashtra and Karnataka. |
| PLI Scheme Alignment | Domestic assembly investments for neurostimulation components reduce import dependency while satisfying state-level procurement domestic content requirements. |
| Outpatient Corridor Expansion | Non-invasive technology deployment across Indian metro corridors captures ambulatory diagnostic demand with lower regulatory friction than implantable systems. |
| State Procurement Integration | Centralized medical equipment corporation partnerships in Tamil Nadu and Telangana create volume aggregation channels with extended contract terms. |
| Closed-Loop Platform Development | Real-time biomarker detection with adaptive output adjustment integrates seizure prediction algorithms that reduce emergency department utilization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against CDSCO registration databases, BIS certification records, state medical equipment corporation tender documents, and PLI scheme beneficiary disclosures. Bottom-up device shipment estimates triangulated against top-down tertiary hospital capacity expansion models.
Segment-weighting approaches distributed value across neurostimulation, EEG, infusion pump, and MRI system categories, with further disaggregation by invasive versus non-invasive technology architecture and stroke versus epilepsy versus pain management application areas. CAGRs were derived from installed base replacement cycles, procedural volume expansion in Maharashtra and Karnataka neuro-specialty clusters, and reimbursement pathway evolution under Ayushman Bharat.
Inputs from CDSCO registration filings and state procurement databases were available through the study window; gaps in real-time hospital capital expenditure commitment data introduce uncertainty bands around near-term device procurement timing. Forecasts reflect assumptions regarding PLI scheme continuity, CDSCO audit throughput capacity, and precious metal price stability. Material deviation in CDSCO registration timeline compression or PLI subsidy withdrawal warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Transcranial Doppler Market
Neurology
Hepatic Encephalopathy Market
Neurology
Interventional Neurology Market
Neurology
Nerve Repair Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Status Epilepticus Treatment Market
Neurology
Neurology Software Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Bell Palsy Treatment Market
Neurology
CNS Treatment and Therapy Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Cluster Headache Syndrome Market