
 AIDS Related Primary CNS Lymphoma Market | 2026-2036
AIDS Related Primary CNS Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
AIDS Related Primary CNS Lymphoma Market Outlook
A shortage of neuro-oncologists with HIV/AIDS clinical expertise is redrawing competitive boundaries in this market. Bristol-Myers Squibb leverages its immuno-oncology portfolio to sustain presence in combination regimens for this patient population. Roche anchors its position through diagnostic and therapeutic integration across CNS lymphoma workflows. AbbVie differentiates via targeted therapy development addressing molecular vulnerabilities in Epstein-Barr virus-driven lymphomas.
AIDS Related Primary CNS Lymphoma comprises aggressive diffuse large B-cell lymphoma confined to the brain, spinal cord, or meninges in immunocompromised patients, typically requiring methotrexate-based high-dose chemotherapy with blood-brain barrier penetration as a core functional parameter. The chemotherapy segment retains the largest patient volume base due to established methotrexate protocols, while immunotherapy represents the fastest-expanding category as checkpoint inhibitors demonstrate intracranial activity. Among end users, oncology centers capture concentrated margin pools through dedicated neuro-oncology programs, whereas hospitals handle the bulk of acute presentation and initial staging procedures.
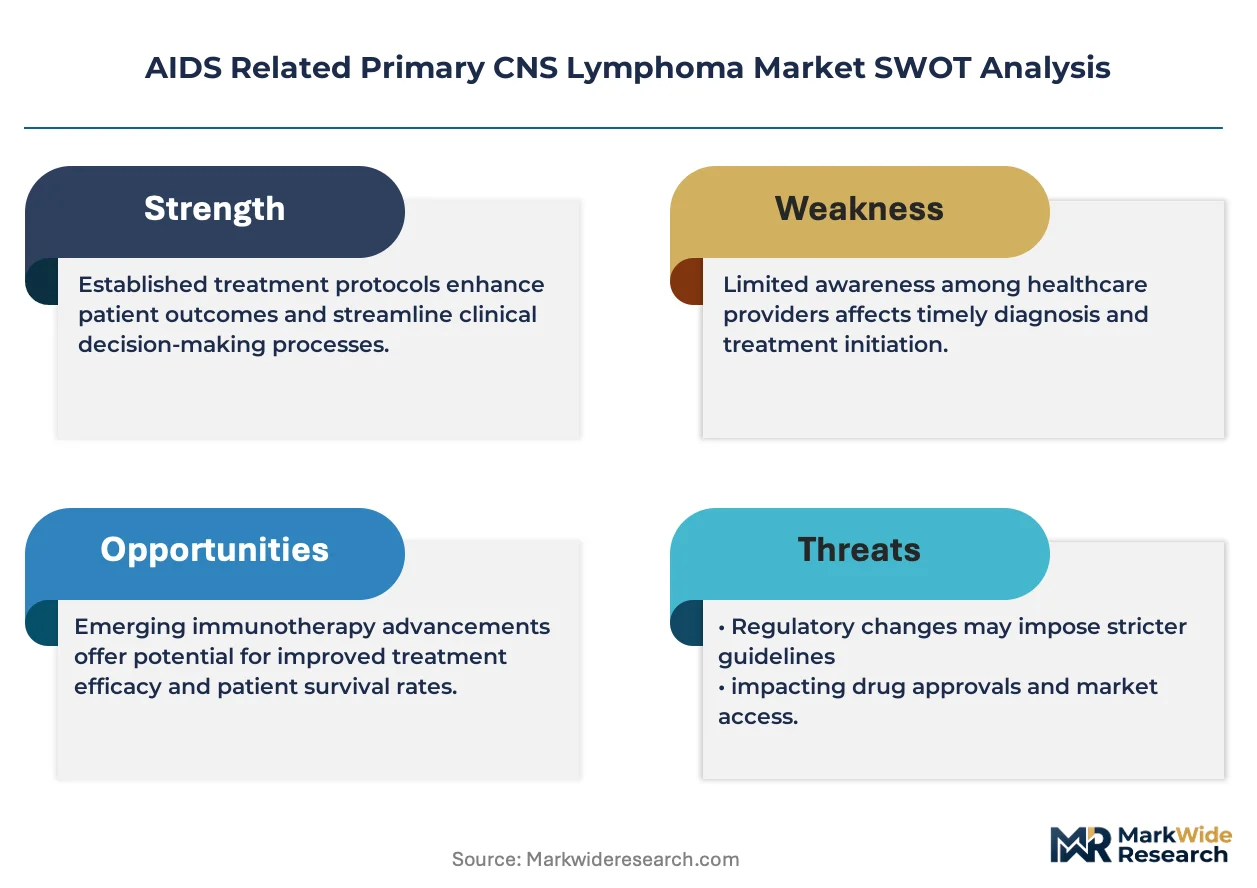
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics by compressing regulatory timelines and extending market exclusivity for sponsors. WHO guidelines on HIV-associated malignancies establish minimum care standards that influence national reimbursement decisions and treatment access. Stakeholders must monitor biomarker-driven patient stratification advances that could fragment addressable populations across CD20 expression, EBV viral load, and MYC rearrangement subtypes.
Market Dynamics
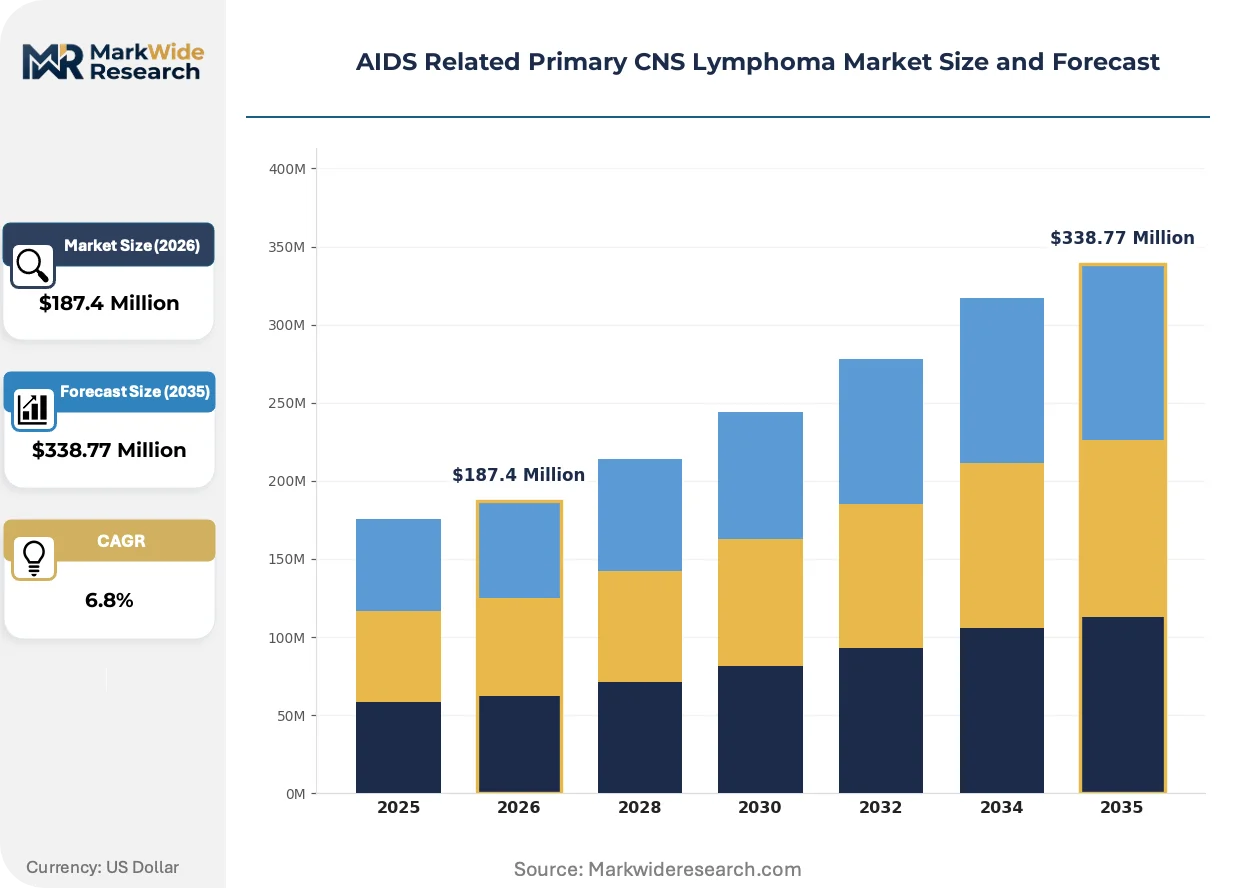
The AIDS Related Primary CNS Lymphoma market pivots on the tension between extended HIV patient survival from antiretroviral therapy and the consequent rise in immunocompromised-associated malignancies, creating concentrated demand for blood-brain barrier-penetrating therapeutics.
Growth Catalysts
- EMA's Priority Medicines Scheme:The European regulator's accelerated assessment pathway compresses development timelines for rare CNS malignancies, drawing sponsor investment toward orphan indications.
- High-dose methotrexate protocols:Established chemotherapy regimens with proven intracranial efficacy anchor first-line treatment, preserving patient volume for combination therapy expansion.
- Oncology center specialization:Dedicated neuro-oncology units in tertiary care institutions concentrate expertise and referral networks for complex HIV-positive lymphoma cases.
Market Restraints
- Neuro-oncologist scarcity:The shortage of clinicians dually trained in HIV/AIDS management and CNS malignancy care restricts treatment capacity at specialized centers.
- Blood-brain barrier pharmacokinetics:Limited CNS penetration of systemic agents necessitates high-dose regimens with substantial toxicity profiles, constraining therapeutic index.
- Biomarker assay fragmentation:Non-standardized EBV viral load and CD20 expression testing across diagnostic laboratories complicates patient stratification for targeted therapy selection.
Strategic Opportunities
- Checkpoint inhibitor intracranial activity:PD-1/PD-L1 agents demonstrating CNS efficacy in other indications present expansion potential for combination regimens in this population.
- Diagnostic-therapeutic integration:Liquid biopsy and CSF circulating tumor DNA platforms enable real-time treatment response monitoring without repeated invasive procedures.
- Sub-Saharan Africa access programs:The region's high HIV burden and limited neuro-oncology infrastructure create demand for simplified, resource-adapted treatment protocols.
Industry Challenges
- Clinical trial enrollment:The rare disease incidence complicates recruitment for adequately powered studies, prolonging development timelines and regulatory submission preparation.
- Reimbursement pathway complexity:Payer categorization disputes between oncology and infectious disease benefit structures create access friction for combination therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AIDS Related Primary CNS Lymphoma Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Targeted Therapy End User: Oncology Centers, Hospitals, Clinics, Research Institutes Delivery Mode: Intravenous, Oral, Subcutaneous, Intra-arterial Stage: Localized, Advanced, Recurrent, Newly Diagnosed |
| Companies Covered | Amgen, Bristol-Myers Squibb, Merck, Roche, AbbVie, Novartis, Fresenius SE & Co. KGaA, Gilead Sciences, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AIDS Related Primary CNS Lymphoma Market Strategic Shifts
Therapeutic innovation in this market converges on three vectors: intracranial drug delivery advancement, biomarker-driven patient selection, and care model reconfiguration toward specialized centers.
Intrathecal chemotherapy delivery systems are miniaturizing, enabling sustained methotrexate release directly into cerebrospinal fluid compartments. Neurosurgical oncology units at institutions like Memorial Sloan Kettering and MD Anderson are adopting these implantable reservoir technologies for refractory cases. This miniaturization is compressing the interval between diagnosis and effective CNS drug exposure, potentially displacing systemic high-dose protocols in selected patient subsets.
WHO guidelines on HIV-associated malignancies establish minimum care standards that national health systems translate into reimbursement mandates. The framework's 2021 revision elevated CNS lymphoma to priority status, triggering budget allocation shifts in low- and middle-income countries. Sub-Saharan African health ministries are responding by integrating neuro-oncology modules into existing HIV treatment infrastructure.
Patient referral patterns are consolidating toward dedicated AIDS malignancy centers capable of coordinated antiretroviral and chemotherapeutic management. Community oncology practices lacking infectious disease expertise are ceding complex cases to academic medical centers with embedded HIV specialists. This geographic concentration is most pronounced in the United States, where Medicare reimbursement differentials favor comprehensive cancer center designation.
AIDS Related Primary CNS Lymphoma Market Segmentation
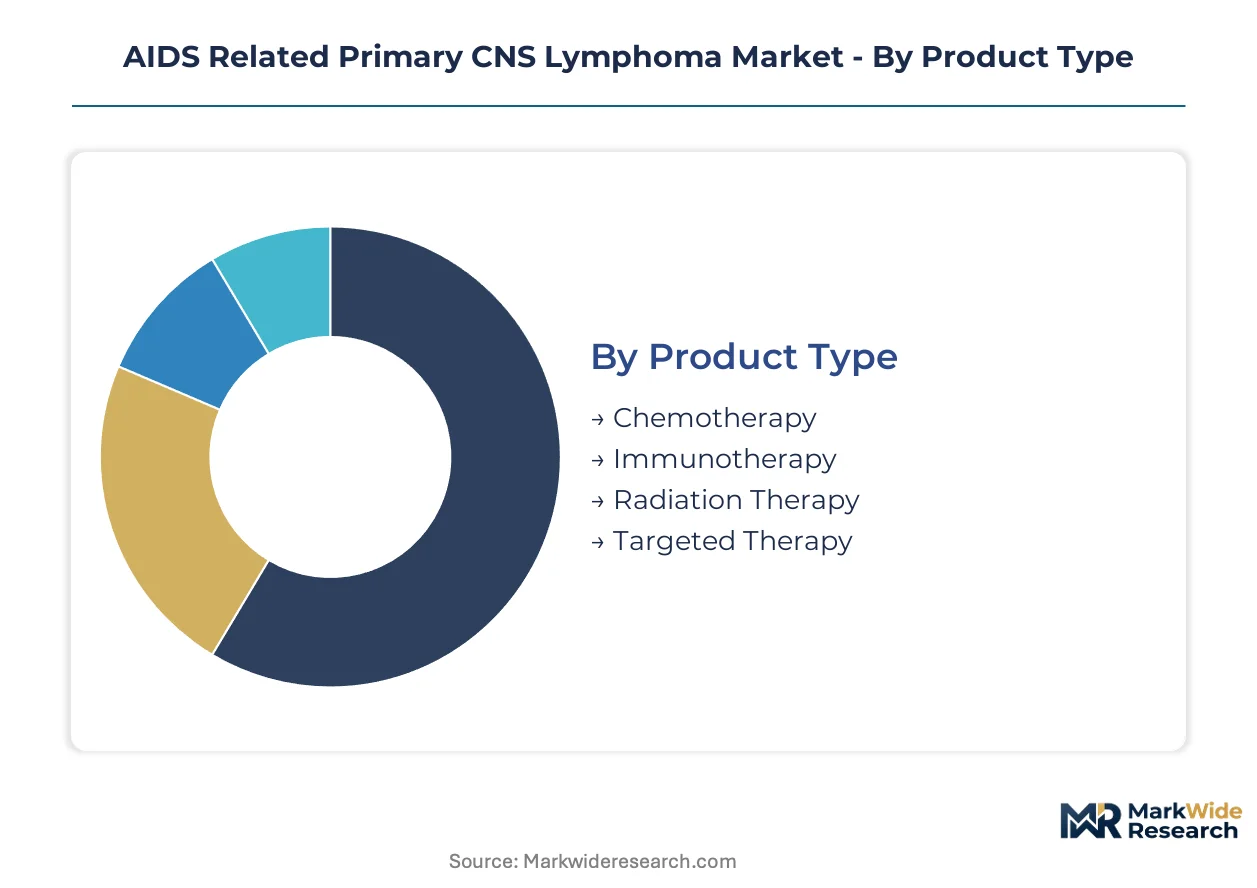
Segmentation in the AIDS Related Primary CNS Lymphoma market reveals distinct therapeutic modalities, care delivery settings, and disease progression stages that shape procurement patterns and clinical investment priorities. Understanding these divisions enables stakeholders to align development resources with areas of unmet medical need and reimbursement viability.
Product Type:
Domestic formulation capabilities concentrate chemotherapy production in established pharmaceutical manufacturing clusters, while immunotherapy and targeted therapy development draws cross-border clinical trial investment and technology licensing.
- Chemotherapy:Methotrexate-based high-dose regimens with blood-brain barrier penetration anchor first-line protocols. Demand concentrates in United States oncology centers with embedded HIV specialist teams, driven by established reimbursement pathways and clinical familiarity with toxicity management.
- Immunotherapy:Checkpoint inhibitors and CAR-T constructs demonstrate emerging intracranial activity in investigator-initiated trials. European academic medical centers in Germany and the Netherlands lead adoption of PD-1 combination protocols for relapsed cases, supported by EMA's priority medicines framework.
- Radiation Therapy:Whole-brain radiotherapy and stereotactic approaches address localized or refractory presentations, typically sequenced with systemic agents.
- Targeted Therapy:EBV-directed and CD20-targeted agents address molecular subtypes with defined biomarker profiles.
Chemotherapy holds the largest share; momentum sits with immunotherapy.
End User:
Cost tier stratification separates high-complexity comprehensive cancer centers from community hospitals and outpatient clinics based on infrastructure requirements and specialist availability.
- Oncology Centers:Dedicated neuro-oncology units with embedded infectious disease expertise manage complex antiretroviral-chemotherapy interactions. Memorial Sloan Kettering, MD Anderson, and similar tertiary institutions capture concentrated case volumes through referral networks.
- Hospitals:Acute presentation and initial staging procedures dominate hospital admissions, with emergency departments serving as diagnostic entry points for neurologic symptom onset.
- Clinics:Outpatient infusion centers handle stable maintenance phases and monitoring for selected low-risk patients.
- Research Institutes:Academic centers with NIH or EORTC affiliations drive protocol development and biomarker validation studies.
Oncology centers command the highest margins per case; volume expansion is accelerating fastest in hospital-based integrated delivery networks.
Delivery Mode:
Application context determines route selection, with CNS penetration requirements and treatment intensity driving intravenous dominance despite patient convenience trade-offs.
- Intravenous:High-dose methotrexate infusion with leucovorin rescue remains the functional standard for blood-brain barrier penetration. United States comprehensive cancer centers and European university hospitals maintain specialized pharmacy infrastructure for compounding and administration.
- Oral:Temozolomide and select targeted agents offer outpatient convenience for maintenance or palliative protocols, though CNS penetration limitations constrain first-line utility.
- Subcutaneous:Limited current application in this indication, with investigational use for supportive care agents.
- Intra-arterial:Experimental delivery approaches at specialized neuro-interventional centers explore enhanced CNS drug concentration.
Intravenous administration retains dominant volume; oral regimens are gaining share fastest in maintenance settings.
Stage:
Patient volume distribution and margin structure vary sharply across disease progression states, with newly diagnosed cases requiring intensive resource deployment and recurrent presentations driving clinical trial enrollment.
- Localized:Single or limited CNS lesions amenable to focal radiation or surgical consideration. United States neuro-oncology programs and German brain tumor centers concentrate expertise for multimodal local therapy integration.
- Advanced:Multifocal or disseminated leptomeningeal disease requiring systemic high-dose protocols. Academic medical centers in France and the United Kingdom manage complex cases through national referral networks.
- Recurrent:Relapsed or refractory presentations drive demand for experimental protocols and compassionate access programs.
- Newly Diagnosed:Initial presentation captures the full diagnostic and therapeutic intensity of the care pathway.
Advanced stage captures the largest patient volume; steepest expansion trajectory sits with recurrent cases as survival prolongation extends the at-risk window.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between high-income markets with specialized neuro-oncology infrastructure and emerging regions where HIV burden outpaces diagnostic capacity. Antiretroviral therapy penetration rates determine CNS lymphoma incidence trajectories, while regulatory pathways shape where sponsors prioritize clinical investment.
United States
High-dose methotrexate protocols dominate first-line treatment at comprehensive cancer centers with embedded HIV specialist teams. FDA orphan drug designation accelerates development timelines for blood-brain barrier-penetrating candidates. Memorial Sloan Kettering and MD Anderson anchor referral networks that concentrate complex case volumes.
Germany
Academic medical centers in Heidelberg and Berlin lead adoption of PD-1 combination protocols for relapsed presentations. EMA's priority medicines scheme compresses regulatory assessment periods for rare CNS malignancies. The German Brain Tumor Center network standardizes biomarker-driven patient stratification across federal states.
France
National referral networks manage advanced leptomeningeal disease through university hospital centers in Paris and Lyon. ANSM expedites compassionate access for experimental intrathecal delivery systems. The Île-de-France region concentrates diagnostic pathology expertise for EBV viral load quantification.
United Kingdom
NHS England's specialized commissioning framework routes CNS lymphoma cases to designated neuro-oncology centers in London and Manchester. MHRA rolling review mechanisms align with EMA accelerated pathways for orphan indications. The Cambridge-Oxford corridor drives liquid biopsy validation for CSF circulating tumor DNA monitoring.
South Africa
The Western Cape and Gauteng provinces integrate neuro-oncology modules into existing HIV treatment infrastructure. WHO guideline implementation triggers budget reallocation toward CNS malignancy care at public sector facilities. Cape Town's Groote Schuur Hospital anchors a referral network serving high-incidence populations across sub-Saharan Africa.
AIDS Related Primary CNS Lymphoma Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with oncology-focused pharmaceutical conglomerates controlling combination therapy platforms while biotechnology specialists anchor immuno-oncology innovation. The market structure rewards backward integration into diagnostic capabilities and forward integration into patient support services. Two strategic archetypes dominate: diversified oncology portfolio holders leveraging cross-indication synergies, and targeted therapy developers concentrating on molecularly defined lymphoma subtypes. Competitive intensity concentrates on diagnostic-therapeutic bundling and accelerated regulatory pathway capture.
Within the integrated pharmaceutical tier, Bristol-Myers Squibb and Roche occupy positions exemplifying divergent strategic vectors—one anchored in immuno-oncology combination development, the other in diagnostic-therapeutic workflow integration. AbbVie represents the targeted therapy archetype through its concentration on molecular vulnerability exploitation. These three entities collectively illustrate how competitive positioning in this orphan indication depends on portfolio breadth, biomarker platform control, and regulatory relationship depth rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Amgen |
| Bristol-Myers Squibb |
| Merck |
| Roche |
| AbbVie |
| Novartis |
| Fresenius SE & Co. KGaA |
| Gilead Sciences |
| Dr. Reddy's Laboratories |
| Others |
Value Chain & Pricing Dynamics
Batch-scale economies in high-dose methotrexate compounding anchor supply concentration among United States comprehensive cancer centers and European university hospitals, compressing per-dose costs for intravenous protocols while elevating price floors for smaller institutions lacking specialized pharmacy infrastructure. This scale asymmetry concentrates procurement leverage within tertiary neuro-oncology networks and fragments access for community hospitals managing sporadic case volumes.
Pricing Analysis
Long-term offtake agreements between oncology centers and compounding pharmacies dominate procurement for methotrexate-based regimens, with spot purchasing limited to emergency restocking scenarios. Price differentiation rests on GMP certification tier and cold-chain logistics capability, with FDA-registered 503B facilities commanding premiums over standard hospital pharmacies. Cost compression in first-line chemotherapy intensifies as biosimilar methotrexate formulations expand, though checkpoint inhibitor combination therapies exhibit pricing resilience due to orphan indication exclusivity. Community hospitals demonstrate highest price sensitivity, while academic medical centers with embedded NIH funding absorb premium pricing for experimental protocols.
Supply Chain Analysis
Strait of Hormuz transit vulnerability for methotrexate active pharmaceutical ingredient sourced from Indian API manufacturers introduces geopolitical risk into North American and European supply continuity. Production gravity centers on India, Germany, and the United States for finished dosage forms, with China dominating precursor chemical supply. Raw material dependencies encompass folate antagonist precursors, sterile water for injection, and specialized CNS-penetrant formulation excipients. Single-source vulnerability concentrates in EBV diagnostic assay reagents manufactured by Roche and Abbott. Distribution runs through specialized oncology distributors with cold-chain certification rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient support services and biomarker testing bundling expand faster than standalone therapeutic revenue, creating service-attach economics that reward diagnostic-therapeutic integration over drug-only positioning.
For Market Incumbents: Shield market position through backward integration into CSF liquid biopsy platforms and captive supply of leucovorin rescue agents. Consolidate referral network relationships at Memorial Sloan Kettering, MD Anderson, and Heidelberg University Hospital to preempt emerging immuno-oncology competitors. The priority lever is diagnostic workflow control. For New Entrants and Emerging Players: Anchor in Sub-Saharan Africa access programs where WHO guideline implementation outpaces neuro-oncology infrastructure buildout. Target Western Cape and Gauteng provinces with resource-adapted high-dose methotrexate protocols. The most penetrable segment is simplified intrathecal delivery systems for settings lacking specialized pharmacy compounding. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors targeted therapy developers with EBV-directed molecular platforms over broad immuno-oncology portfolio holders facing combination regimen commoditization. Long-term viability hinges on biomarker-driven patient stratification capabilities. The signal to watch is EMA priority medicines scheme expansion for CNS orphan indications.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor intracranial activity trials at German and Dutch academic centers accelerate regulatory pathway capture. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses development timelines for blood-brain barrier-penetrating candidates. |
| Manufacturing Scale-Up | High-dose methotrexate compounding capacity expansion at 503B facilities addresses oncology center demand concentration. |
| Pipeline Diversification | EBV-directed targeted therapy development addresses molecularly defined lymphoma subtypes with defined biomarker profiles. |
| Strategic Partnership | Diagnostic-therapeutic bundling with Roche or Abbott anchors CSF circulating tumor DNA monitoring adoption. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neuro-oncologists, HIV/AIDS clinical specialists, hospital pharmacy directors, and regulatory affairs leads at EMA and FDA. Secondary validation drew from ClinicalTrials.gov investigator-initiated trial registrations, EMA priority medicines scheme designations, WHO HIV-associated malignancy guideline revisions, and CMS Medicare reimbursement coding updates. Bottom-up patient volume modeling and top-down epidemiological incidence estimates were triangulated across the analysis window.
Across the projection horizon, the analytical framework modeled treatment modality segmentation, disease stage progression, delivery route utilization, and regional regulatory cluster adoption patterns. CAGRs were derived from epidemiological trend extrapolation, therapy penetration curves, and pricing trajectory assumptions. Industry-specific forecast inputs incorporated antiretroviral therapy survival extension rates and neuro-oncology specialist workforce expansion constraints.
Underlying assumptions cover sustained HIV patient survival prolongation, stable orphan drug incentive frameworks, and biomarker assay standardization progress, with deviation risk concentrated in clinical trial enrollment delays and reimbursement pathway disputes between oncology and infectious disease benefit structures. Practitioners should keep alternative scenarios live as EMA accelerated assessment criteria and FDA orphan exclusivity interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Chiari Malformation Treatment Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Global Neuromarketing Market
Neurology
North America Neurology Monitoring Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Narcolepsy Treatment Market
Neurology
Neurology Services Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Neurological Biomarkers Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Neurology Software Market
Neurology
Asia-Pacific Neurology Monitoring Market