
 Middle-East and Africa Neurology Monitoring Market | 2026-2036
Middle-East and Africa Neurology Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Neurology Monitoring Market Foresight
Modular hardware-software bundles is decoupling across the Middle-East and Africa Neurology Monitoring Market, allowing hospitals to purchase EEG acquisition hardware separately from cloud analytics subscriptions. Philips Healthcare leverages its installed base of patient monitors to cross-sell neurology modules into intensive care units across the Gulf. Siemens Healthineers sustains R&D intensity in portable EEG platforms designed for ambulatory epilepsy programs in North African markets. GE HealthCare anchors its regional position through localized service networks that reduce downtime for high-acuity NICU monitors.
Neurology monitoring encompasses electrophysiological acquisition systems, cerebral function analyzers, and intracranial pressure sensors that capture electrical, hemodynamic, and metabolic parameters from the central and peripheral nervous systems, typically sampling neural signals at 256–1024 Hz with 24-bit resolution for clinical diagnostic interpretation. EEG Devices dominate procurement volumes across tertiary hospitals, while Wearable Tech represents the fastest-expanding technology dimension as ambulatory epilepsy and sleep disorder programs proliferate in urban South African and Gulf markets. Cloud-based Solutions concentrate margin pools through recurring software licensing attached to hardware installations, though Portable Devices retain stronger penetration in markets with intermittent power infrastructure.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority enforce electrical safety and software lifecycle standards that shape product registration timelines and post-market surveillance obligations for neurology device suppliers. The UAE's Ministry of Health and Prevention has aligned medical device classification rules with GCC harmonization initiatives, streamlining multi-country market access for manufacturers holding European CE marking. Stakeholders must monitor how national health insurance reimbursement frameworks evolve for remote neurology monitoring services, as coverage decisions will determine whether cloud-connected wearable platforms achieve scalable deployment outside cash-pay private channels.
Market Dynamics
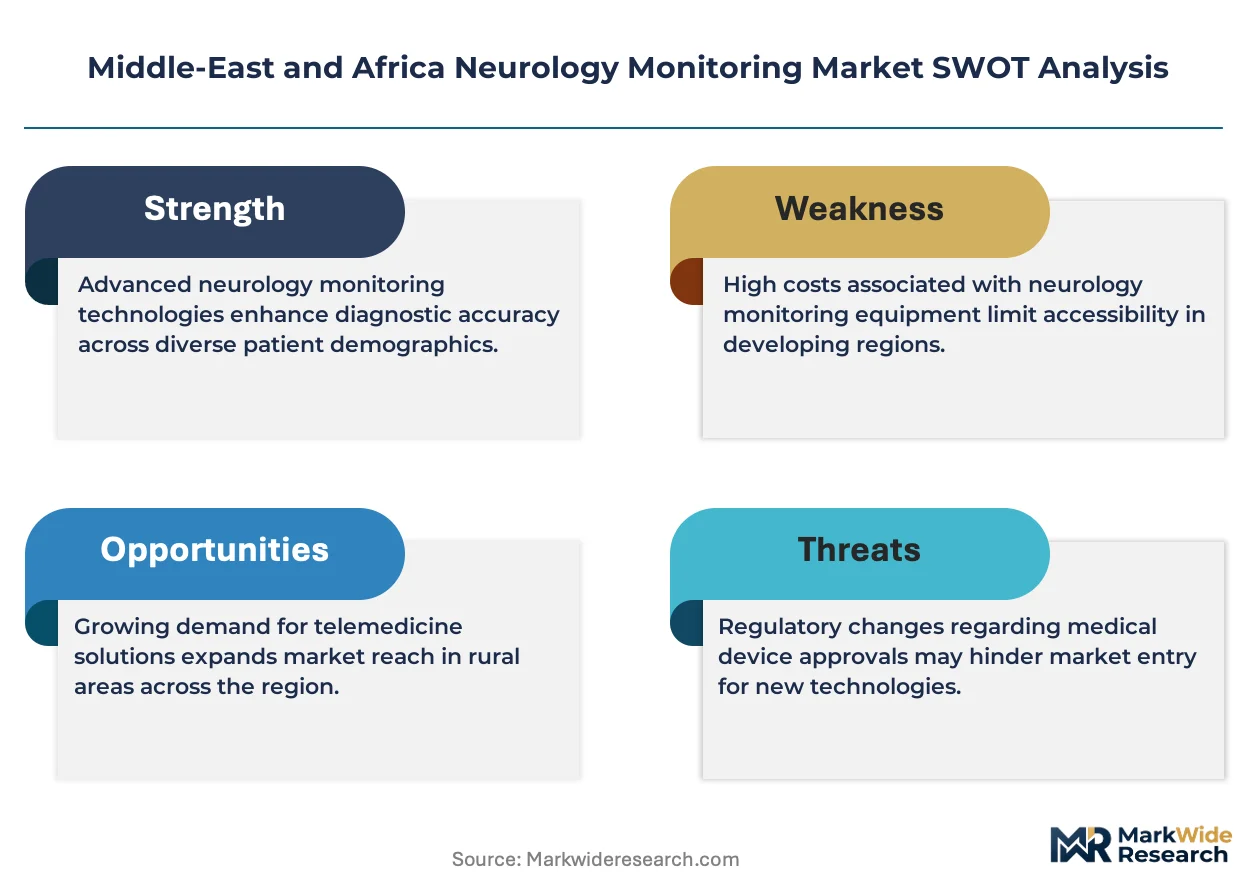
Modular hardware-software decoupling is restructuring procurement economics across the Middle-East and Africa Neurology Monitoring Market, enabling hospitals to unbundle EEG acquisition systems from analytics subscriptions and compress capital deployment timelines.
Growth Catalysts
- Vision 2030 Infrastructure:Saudi Arabia's health transformation program is establishing dedicated neurology centers in Riyadh, Jeddah, and Dammam, generating concentrated demand for integrated monitoring platforms.
- GCC Regulatory Harmonization:The UAE's Ministry of Health and Prevention has aligned medical device classification with GCC-wide standards, reducing registration friction for European CE-marked neurology systems.
- Ambulatory Program Expansion:Urban epilepsy and sleep disorder clinics in South African metropolitan markets are scaling wearable EEG deployments for remote patient monitoring.
Market Restraints
- Electrical Safety Recertification:South Africa's Health Products Regulatory Authority has tightened software validation requirements, forcing manufacturers to revalidate existing product lines and extend registration timelines.
- Power Infrastructure Variability:Intermittent grid reliability in secondary African markets limits penetration of cloud-dependent monitoring platforms, favoring portable devices with local storage.
- Specialized Service Network Requirements:High-acuity NICU monitors demand localized technical support capabilities that few vendors have established outside Gulf urban centers.
Strategic Opportunities
- North African Ambulatory Networks:Portable EEG platforms designed for epilepsy programs in Morocco, Tunisia, and Algeria remain undersupplied relative to clinical demand.
- Remote Monitoring Reimbursement:National health insurance frameworks across the GCC are evaluating coverage for cloud-connected wearable neurology services, with approval creating scalable deployment pathways.
- Cross-Selling into ICU Ecosystems:Patient monitor installed bases in Gulf hospitals provide anchor points for neurology module attachments without dedicated capital procurement cycles.
Industry Challenges
- Neurocritical Care Specialist Shortage:Expansion of neurocritical care units across Gulf Cooperation Council hospitals outpaces availability of trained clinical staff to operate sophisticated multimodal monitoring systems.
- Legacy System Integration Complexity:Tertiary hospitals in South Africa and Saudi Arabia maintain heterogeneous device fleets that resist seamless data interoperability with new cloud analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Neurology Monitoring Market |
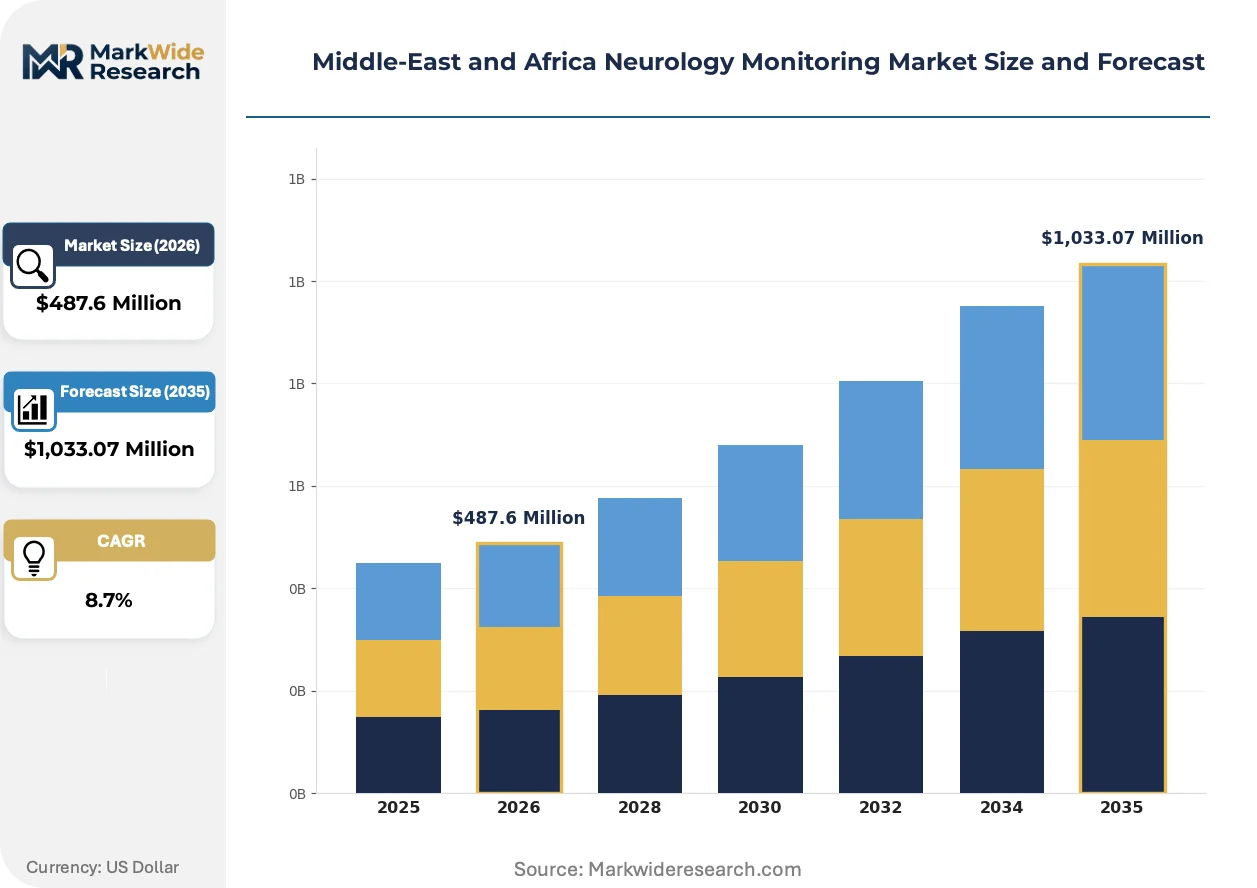
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Devices, EMG Devices, NICU Monitors, Infusion Pumps Technology: Wireless Monitoring, Portable Devices, Wearable Tech, Cloud-based Solutions End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Application: Epilepsy Monitoring, Sleep Disorders, Neurodegenerative Disorders, Brain Stroke |
| Companies Covered | Philips Healthcare, Siemens Healthineers, GE HealthCare, Medtronic, Nihon Kohden Corporation, Natus Medical, Drägerwerk, Abbott Laboratories, Masimo Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Neurology Monitoring Market Shifts & Advancements
Technology architecture and procurement economics are diverging from integrated system sales toward componentized purchasing models that separate hardware acquisition from software capability access.
EEG acquisition hardware is modularizing from cloud analytics subscriptions, allowing tertiary hospitals in the Gulf to purchase 256–1024 Hz sampling devices upfront while deferring artificial intelligence-enabled diagnostic software to recurring licensing arrangements. Intensive care units across Saudi Arabia and the UAE are adopting this unbundled approach to spread capital expenditure across fiscal years. The structural consequence is compressing traditional bundled system margins while expanding addressable hospital accounts that previously faced upfront cost barriers.
South Africa's Health Products Regulatory Authority has imposed tightened electrical safety and software lifecycle standards that extend product registration timelines for neurology device suppliers. Manufacturers must now submit enhanced post-market surveillance protocols and periodic software validation documentation. Portable EEG platforms targeting ambulatory programs face the steepest compliance burden, with several vendors prioritizing Gulf market entries where SFDA pathways offer clearer predictability.
Hospital purchasing committees across the Middle-East and Africa Neurology Monitoring Market are unbundling service contracts from hardware procurement, negotiating separate agreements for installation, training, and maintenance. This disintermediation of after-sales economics is most visible in Saudi Arabia's Ministry of Health tenders, where technical service specifications now stand as independent evaluation criteria. Vendors with captive service networks in Riyadh and Jeddah are capturing preference over competitors dependent on third-party technical partnerships.
Middle-East and Africa Neurology Monitoring Market Segmentation
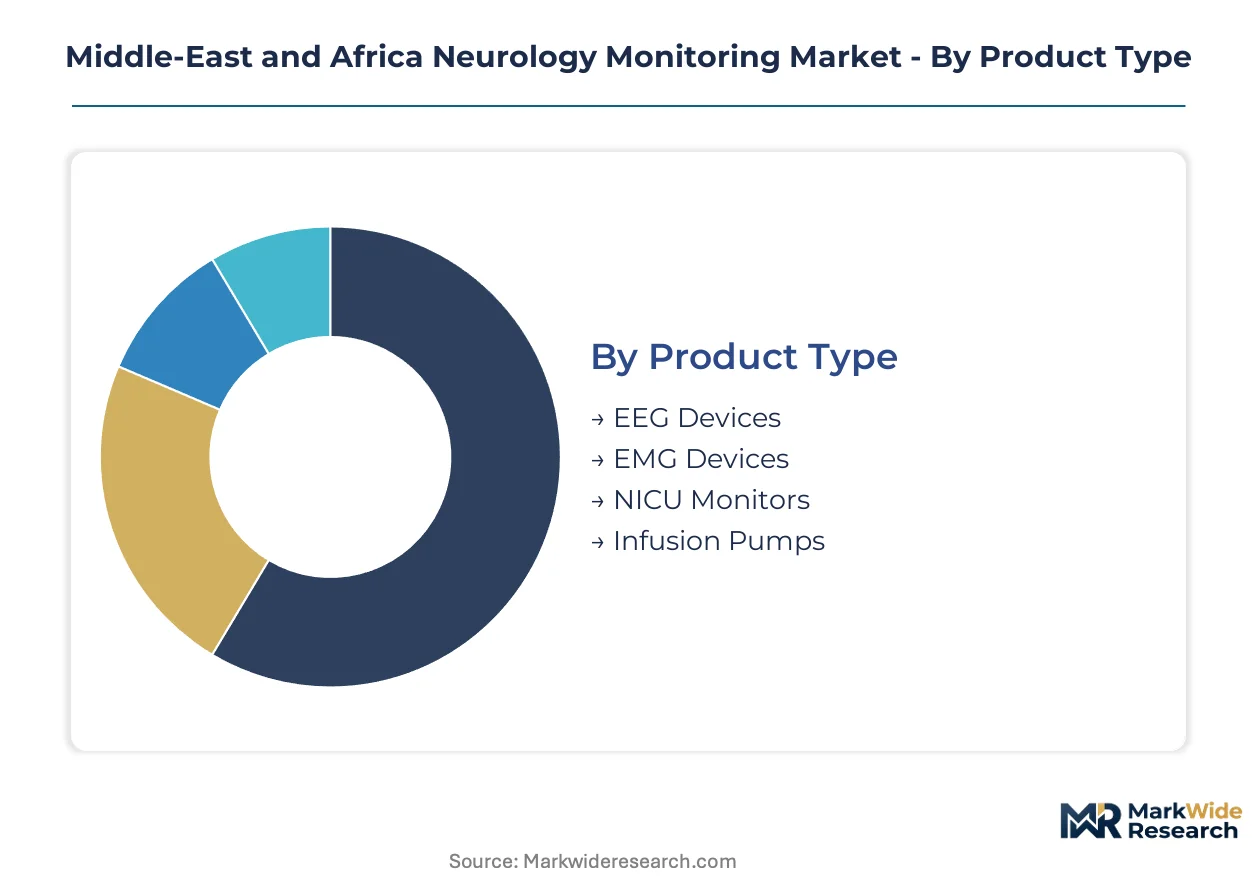
Segmentation in neurology monitoring reveals divergent integration pathways across the Middle-East and Africa. Some segments deploy as standalone capital equipment requiring dedicated infrastructure, while others embed into broader patient monitoring ecosystems or ambulatory care networks.
Product Type:
Integration depth varies sharply across product categories, with some systems functioning as isolated diagnostic platforms while others weave into hospital-wide monitoring architectures.
- EEG Devices:Electrophysiological acquisition systems sampling neural signals at 256–1024 Hz with 24-bit resolution. Procurement concentrates in tertiary hospitals across Riyadh, Jeddah, and Dammam where Vision 2030 neurology centers demand high-channel-count platforms for epilepsy and sleep disorder diagnosis.
- NICU Monitors:Multimodal systems tracking cerebral function, intracranial pressure, and hemodynamic parameters in neonatal intensive care. Gulf Cooperation Council hospitals expanding neurocritical care units drive concentrated demand, though localized service networks remain limited outside urban centers.
- EMG Devices:Peripheral nerve and muscle signal acquisition systems for neuromuscular assessment.
- Infusion Pumps:Drug delivery systems integrated with neuromonitoring for sedated patients in critical care settings.
Volume placements concentrate in EEG Devices; the faster expansion belongs to NICU Monitors.
Technology:
Cost tier stratification separates premium subscription-based platforms from capital-efficient hardware purchases, reshaping procurement committee evaluations across the region.
- Cloud-based Solutions:Analytics platforms delivered via recurring software licensing attached to hardware installations. Margin pools concentrate here through subscription economics, though intermittent power infrastructure in secondary African markets constrains penetration outside Gulf urban centers.
- Wearable Tech:Ambulatory EEG and neural monitoring devices for epilepsy and sleep disorder programs. Urban South African metropolitan clinics and Gulf private hospitals are scaling deployments fastest, pending national health insurance reimbursement decisions.
- Portable Devices:Battery-powered acquisition systems with local storage capability.
- Wireless Monitoring:Radio-frequency or cellular-connected platforms for untethered patient surveillance.
Revenue concentration sits with Cloud-based Solutions; Wearable Tech is gaining share fastest as ambulatory programs proliferate.
End User:
Customer type determines purchasing authority complexity, from centralized Ministry of Health tenders to individual clinician decisions in fragmented outpatient settings.
- Hospitals:Integrated delivery networks with dedicated neurology departments and neurocritical care units. Saudi Arabia's Ministry of Health and UAE hospital groups dominate procurement volumes, unbundling hardware from service contracts in recent tender structures.
- Specialty Clinics:Focused epilepsy, sleep medicine, and neurology outpatient facilities. South African urban markets and Gulf private healthcare clusters show accelerating demand for portable and wearable platforms.
- Homecare:Remote patient monitoring settings with caregiver-assisted device operation.
- Research Institutions:Academic medical centers conducting clinical trials and neurophysiology research.
Capital deployment concentrates in Hospitals; Specialty Clinics are climbing the fastest as ambulatory care networks expand.
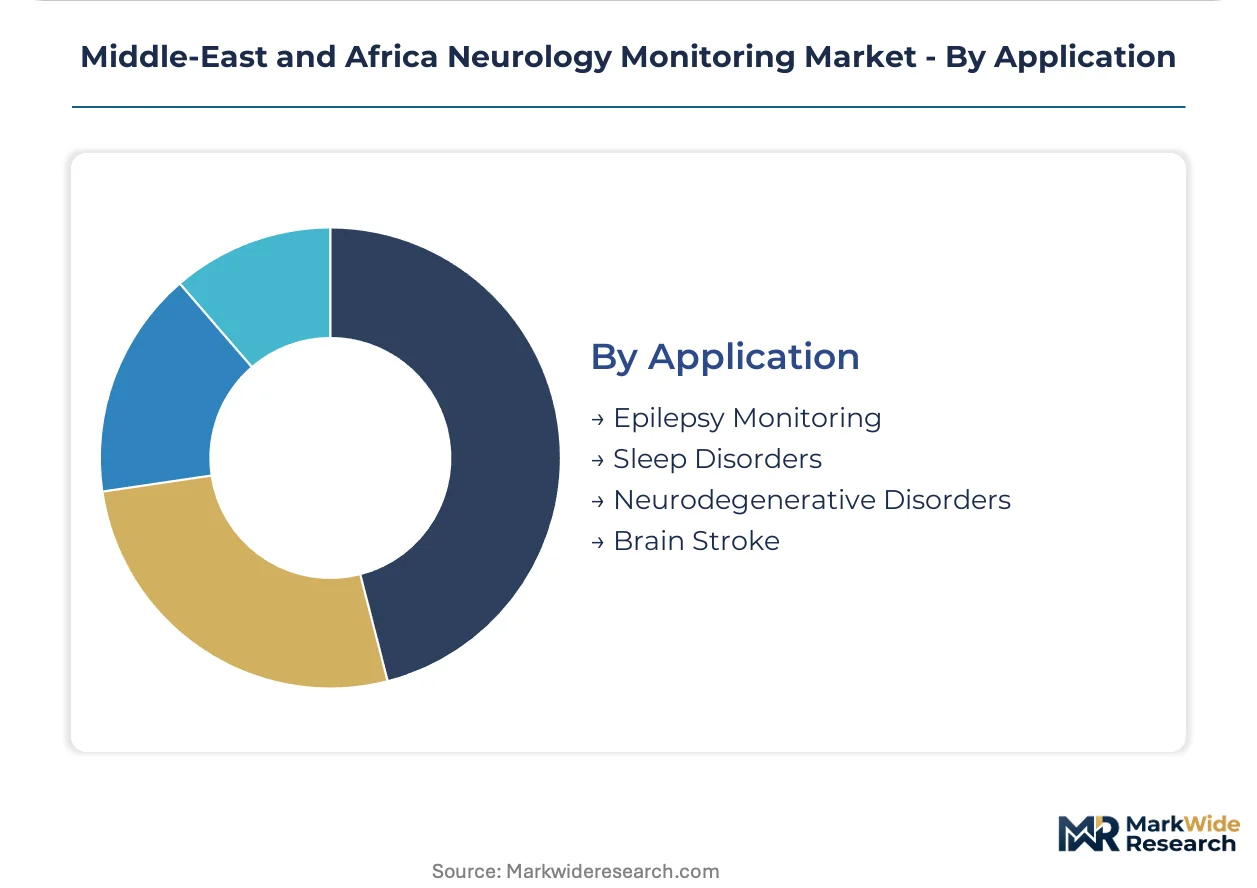
Application:
Clinical indication drives specification requirements, from high-channel-count epilepsy monitoring to streamlined sleep disorder screening protocols.
- Epilepsy Monitoring:Long-term video-EEG and ambulatory seizure detection programs. North African markets including Morocco, Tunisia, and Algeria remain undersupplied relative to clinical demand, creating openings for portable platform suppliers.
- Sleep Disorders:Polysomnography and home sleep apnea testing with neural signal components. Gulf private hospital chains and South African metropolitan clinics are scaling screening programs fastest.
- Neurodegenerative Disorders:Cognitive monitoring and disease progression tracking for dementia and Parkinson's disease.
- Brain Stroke:Acute hemodynamic and electrical monitoring during cerebrovascular events.
Procedure volumes concentrate in Epilepsy Monitoring; Sleep Disorders show the steepest expansion trajectory as diagnostic awareness spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for neurology monitoring systems sits in Western Europe, North America, and East Asia, while consumption growth concentrates across Gulf Cooperation Council states and select African metropolitan markets. The Middle-East and Africa region imports nearly all deployed neurology monitoring equipment, creating procurement dependencies on foreign service networks and extended supply lead times.
Saudi Arabia
Vision 2030 health transformation investments are establishing dedicated neurology centers in Riyadh, Jeddah, and Dammam, generating concentrated demand for high-channel-count EEG platforms and integrated monitoring systems. The Saudi Food and Drug Authority enforces electrical safety and software lifecycle standards that shape product registration timelines and post-market surveillance obligations for device suppliers. King Faisal Specialist Hospital and Research Centre in Riyadh anchors the kingdom's neurocritical care expansion, driving procurement of multimodal cerebral function monitors.
United Arab Emirates
The Ministry of Health and Prevention has aligned medical device classification rules with GCC harmonization initiatives, streamlining multi-country market access for manufacturers holding European CE marking. Dubai Healthcare City and Abu Dhabi's Sheikh Khalifa Medical City are expanding neurocritical care unit capacity, creating demand for NICU monitors with localized technical support requirements. Private hospital chains in Dubai are scaling ambulatory epilepsy programs, accelerating wearable EEG deployments pending reimbursement framework decisions.
South Africa
The Health Products Regulatory Authority has tightened electrical safety and software validation requirements, compelling manufacturers to recertify existing product lines and extend registration timelines for neurology devices. Groote Schuur Hospital and Red Cross War Memorial Children's Hospital in Cape Town maintain the country's deepest neurocritical care expertise, though specialist shortages constrain multimodal monitoring system utilization. Urban metropolitan clinics in Johannesburg and Pretoria are scaling portable EEG deployments for ambulatory epilepsy and sleep disorder programs.
Egypt
Cairo's Ain Shams University Hospital and Alexandria University Hospitals anchor the country's neurology monitoring demand, though procurement volumes remain constrained by foreign currency availability and extended import clearance timelines. The Egyptian Drug Authority maintains medical device registration pathways that prioritize products with prior European or US regulatory clearance, favoring established multinational suppliers. Private healthcare clusters in New Cairo and 6th of October City are investing in sleep medicine facilities, creating openings for polysomnography system suppliers.
Morocco
Centre Hospitalier Universitaire Ibn Sina in Rabat and CHU Hassan II in Fez lead public sector neurology service provision, with procurement concentrated in Ministry of Health tender processes that favor bundled hardware-service offerings. The country's medical device regulatory framework continues aligning with European standards, reducing registration friction for CE-marked portable EEG platforms. Casablanca's private clinic networks are expanding diagnostic neurology capabilities, creating demand for ambulatory monitoring systems suited to intermittent power infrastructure.
Middle-East and Africa Neurology Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established patient monitoring installed bases. Philips Healthcare, Siemens Healthineers, and GE HealthCare anchor the market through cross-selling neurology modules into intensive care units and leveraging localized service networks. Three archetypes dominate: integrated critical care platform vendors, portable EEG specialists, and patient monitor incumbents extending into neurophysiology. Competitive moves concentrate on unbundling hardware from software subscriptions and establishing captive technical service capabilities in Gulf urban centers.
Within the diversified medical technology tier, Philips Healthcare exemplifies the cross-selling archetype through its patient monitor installed base, while Siemens Healthineers occupies a position emphasizing portable platform development. GE HealthCare anchors the service-network-dependent segment through localized technical support capabilities. These three conglomerates represent distinct strategic postures: modular hardware-software bundling, ambulatory-focused R&D intensity, and after-sales infrastructure depth.
| Leading Market Players |
|---|
| Philips Healthcare |
| Siemens Healthineers |
| GE HealthCare |
| Medtronic |
| Nihon Kohden Corporation |
| Natus Medical |
| Drägerwerk |
| Abbott Laboratories |
| Masimo Corporation |
| Others |
Supply & Pricing Matrix
Modular hardware-software decoupling across the Middle-East and Africa Neurology Monitoring Market is simultaneously compressing upfront capital requirements and fragmenting procurement authority toward hospital biomedical engineering departments. This unbundling dynamic allows Gulf tertiary hospitals to acquire 256-channel EEG acquisition systems from Western European manufacturers while deferring cloud analytics subscriptions to recurring operational budgets, fundamentally altering how pricing power distributes between device OEMs and software platform vendors.
Pricing Analysis
Cost-down pressure on premium-tier integrated monitoring platforms accelerates because Saudi Arabia's Ministry of Health tenders now evaluate hardware and service contracts as independent line items. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked multimodal NICU systems from refurbished portable EEG units and unbranded acquisition hardware. Pricing pressure stems from South Africa's Health Products Regulatory Authority recertification requirements extending vendor cost recovery timelines. Public hospital procurement committees in Riyadh and Jeddah exhibit highest price sensitivity, while private Dubai hospital chains prioritize after-sales response time over unit economics.
Supply Chain Analysis
Refurbishment flows for high-acuity NICU monitors create secondary supply channels serving Egyptian and Moroccan markets with extended-warranty hardware sourced from Gulf hospital fleet upgrades. Manufacturing concentration rests on Germany, the Netherlands, and Japan for EEG acquisition components, with semiconductor substrates and 24-bit analog-to-digital converters drawing from East Asian foundries. Single-source vulnerability concentrates in specialized intracranial pressure sensor membranes produced by two European component houses. Distribution runs through authorized distributor networks in Dubai Healthcare City and direct hospital contracts in Saudi Arabia's Vision 2030 infrastructure program.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized neurocritical care technical service capacity scarcity props pricing for vendors with captive Gulf maintenance networks, constraining market access for competitors dependent on third-party partnerships.
For Market Incumbents: Anchor market position through backward integration into localized technical service capabilities across Riyadh, Jeddah, and Dammam to defend against portable EEG specialists offering compressed deployment timelines. Prioritize certification investment for SFDA electrical safety pathways ahead of South Africa's Health Products Regulatory Authority software validation requirements. Capacity addition in Dubai service hubs addresses NICU monitor uptime demands that purchasing committees now weight equally with hardware specifications. For New Entrants and Emerging Players: Distributor partnerships with established Gulf medical device houses provide the fastest route to hospital purchasing committee access without dedicated capital for captive service networks. North African ambulatory epilepsy programs in Morocco, Tunisia, and Algeria represent the most penetrable geography, with clinical demand substantially exceeding portable platform supply. A software-first go-to-market angle—selling cloud analytics subscriptions compatible with existing hospital EEG hardware—sidesteps upfront capital barriers and accelerates revenue recognition. For Investors and Strategic Acquirers: Re-rating potential sits with portable EEG platform specialists possessing CE marking and ambulatory program reference sites, given pending GCC national health insurance reimbursement decisions for remote monitoring services. Long-term viability across the analysis window hinges on regulatory pathway predictability rather than hardware differentiation alone. Watch for SFDA and South African Health Products Regulatory Authority harmonization signals on software lifecycle standards as the inflection indicator for scalable cloud-connected deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Software Lifecycle Compliance Investment | Accelerates product registration timelines for Saudi Arabia's Vision 2030 neurology center procurement. |
| Cloud Analytics Platform Development | Captures recurring revenue streams from hardware installations across Gulf hospital systems. |
| Localized Technical Service Network Expansion | Reduces downtime penalties for high-acuity NICU monitors in neurocritical care units. |
| Ambulatory Epilepsy Program Partnership | Opens scalable deployment pathways pending South African reimbursement framework decisions. |
| CE Marking Pathway Prioritization | Streamlines multi-country GCC market access under UAE Ministry of Health harmonization initiatives. |
Research Methodology
Hospital procurement databases, GPO contracts, and SFDA registration filings formed the secondary backbone, supplemented by customs records tracking EEG device imports into Jeddah and Cape Town ports. Primary interviews with biomedical engineers, hospital purchasing committee chairs, and neurology department heads in Riyadh, Dubai, and Johannesburg combined with secondary validation. Conversations with Gulf distributor technical service managers and South African Health Products Regulatory Authority compliance officers anchored supply-side perspectives. Bottom-up and top-down triangulation cross-validated equipment placement volumes against Ministry of Health tender awards.
Bottom-up modeling tracked individual hospital neurocritical care unit expansion timelines across Saudi Arabia's Vision 2030 program, while top-down analysis assessed regional healthcare infrastructure investment flows. Segmentation dimensions spanned product type, technology architecture, end-user purchasing authority, and clinical application across the projection horizon. CAGRs derived from fitted trend analysis of historical procurement cycles and forward pipeline visibility from announced neurology center construction. Forecast inputs incorporated ambulatory program reimbursement policy trajectories and electrical safety regulatory pathway evolution.
Caveats apply where SFDA software validation requirement tightening or South African Health Products Regulatory Authority recertification delays could materially shift the outlook for cloud-dependent platform deployments. Forecasts reflect assumptions regarding Gulf power infrastructure stability and foreign currency availability for Egyptian hospital procurement. Practitioners should monitor national health insurance reimbursement decisions for remote neurology monitoring services and GCC regulatory harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
White Matter Injury Treatment Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Neurology Digital Therapeutics Market
Neurology
CNS Treatment and Therapy Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
US Optic Neuritis Market
Neurology
Germany Neurology Devices Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Cognitive Neuroscience Market
Neurology
Argentina Neurology Devices Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Global Neuroblastoma Market
Neurology
Spinal Laminoplasty Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market