
 Global Laryngeal Cancer Therapeutics Market | 2026-2036
Global Laryngeal Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laryngeal Cancer Therapeutics Market Foresight
Oncology nursing specialization is bifurcating the competitive landscape, as centers with dedicated head and neck cancer teams attract disproportionate patient flows. Bristol-Myers Squibb leverages its immuno-oncology platform to sustain leadership in checkpoint inhibitor development for laryngeal indications. Merck anchors its position through broad clinical trial networks spanning North America and Europe. AstraZeneca differentiates via antibody-drug conjugate investments targeting epidermal growth factor receptor pathways in squamous cell carcinomas.
Laryngeal cancer therapeutics encompass pharmaceutical agents and biologics designed to treat malignant neoplasms of the larynx, including the supraglottis, glottis, and subglottis, with formulations ranging from platinum-based cytotoxic compounds to monoclonal antibodies requiring cold-chain distribution. These therapies serve the primary commercial purpose of improving five-year survival rates while preserving vocal function and reducing the need for total laryngectomy. Immunotherapy now commands the fastest expansion within therapy type segmentation, driven by durable response data in recurrent and metastatic disease settings. Targeted therapy occupies concentrated margin pools where epidermal growth factor receptor inhibitors generate premium pricing against biomarker-selected patient subsets. Surgery and radiation therapy segments remain mature revenue bases with predictable reimbursement but limited growth velocity.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme together compress development timelines for novel laryngeal cancer agents, while Japan's PMDA operates accelerated review tracks that reward domestic clinical data generation. These frameworks shape demand by steering investment toward immunotherapy and targeted therapy portfolios over cytotoxic chemotherapy platforms. Stakeholders must monitor biomarker testing infrastructure buildout and companion diagnostic partnerships as gatekeepers to premium therapy access.
Market Dynamics
FDA breakthrough therapy designations and EMA priority medicines schemes are compressing development timelines for novel laryngeal cancer agents, redirecting R&D investment toward immunotherapy platforms and away from cytotoxic chemotherapy foundations.
Growth Catalysts
- Biomarker Testing Infrastructure:Companion diagnostic partnerships are expanding access to epidermal growth factor receptor inhibitors in tertiary oncology centers across Germany and Japan.
- EMA Priority Medicines Scheme:Accelerated review tracks reward domestic clinical data generation, shortening time-to-market for antibody-drug conjugate candidates.
- Aging Demographics:Patient volumes in the United States sustain demand for larynx-preserving therapeutic protocols among long-duration tobacco exposure cohorts.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibody formulations require temperature-controlled logistics that inflate per-dose delivery expenses by 15-25 percent versus small-molecule alternatives.
- Platinum Compound Supply Concentration:Active pharmaceutical ingredient production for cisplatin and carboplatin concentrates in Chinese and Indian manufacturing clusters, exposing procurement to geopolitical friction.
- Biomarker Testing Gaps:Community oncology practices in rural United States regions lack next-generation sequencing capacity, restricting patient identification for targeted therapy eligibility.
Strategic Opportunities
- Voice Preservation Protocols:Functional outcomes data is expanding reimbursement for organ-sparing immunotherapy combinations in early-stage glottic disease.
- Japan PMDA Accelerated Review:Domestic clinical trial investment unlocks priority review status for novel checkpoint inhibitor combinations in recurrent disease settings.
- Telemedicine Triage Integration:Remote laryngoscopy and multidisciplinary tumor board coordination are extending specialist reach into underserved United States markets.
Industry Challenges
- Head and Neck Oncology Nursing Shortage:Specialized training programs for laryngeal cancer patient management remain underdeveloped relative to breast and lung cancer nursing pipelines.
- Companion Diagnostic Harmonization:Discordant epidermal growth factor receptor testing methodologies across United States, European, and Japanese laboratories complicate global trial enrollment.
- Legacy Cytotoxic Manufacturing Retention:Capacity allocation decisions between platinum-based chemotherapy and biologic production lines strain contract manufacturing organization flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laryngeal Cancer Therapeutics Market |
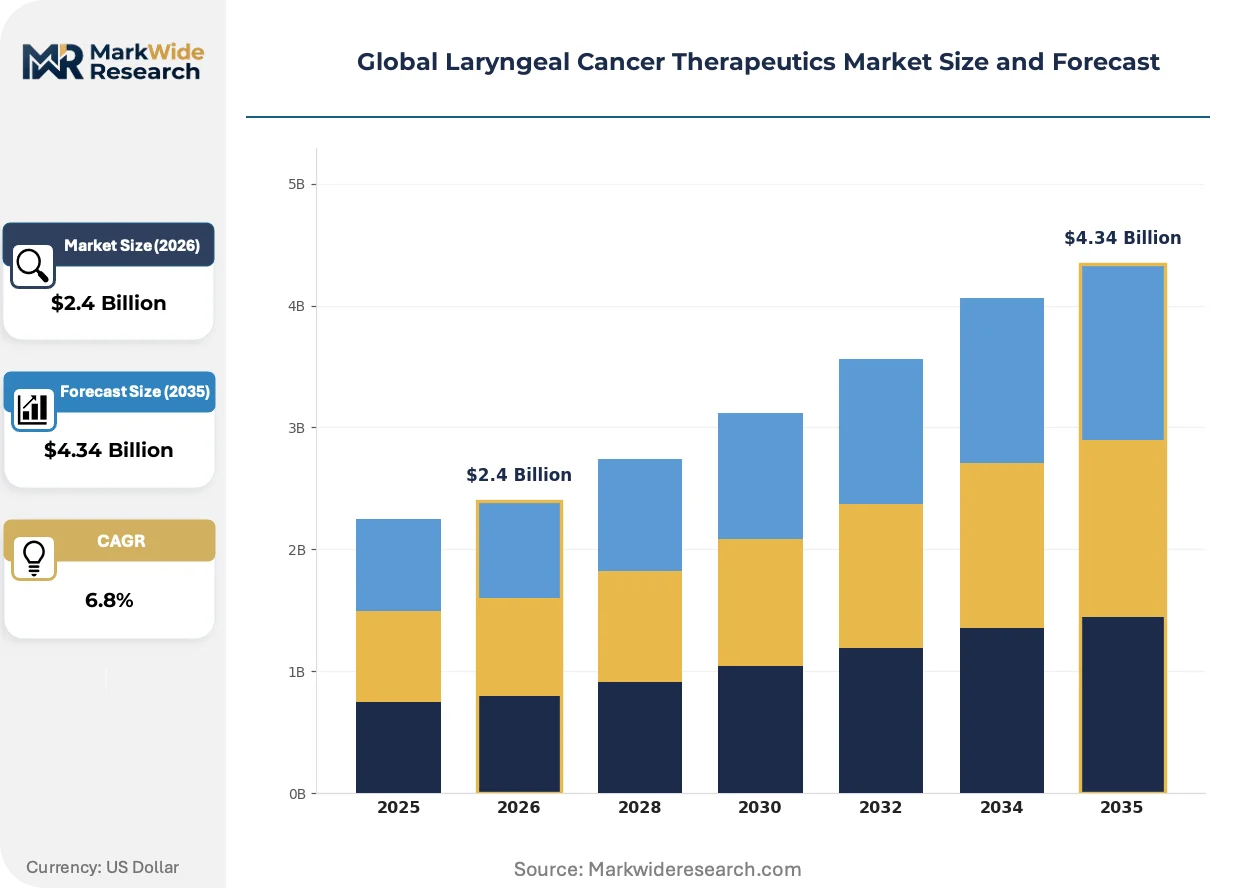
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy, Immunotherapy Delivery Method: Oral, Intravenous, Topical, Inhalation, Injection Patient Demographic: Adult Males, Adult Females, Senior Citizens, Pediatric Patients Treatment Setting: Hospitals, Cancer Centers, Specialty Clinics, Outpatient Facilities |
| Companies Covered | Roche, Bristol-Myers Squibb, Merck, Eli Lilly, Sanofi, AbbVie, Pfizer, AstraZeneca, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laryngeal Cancer Therapeutics Market Shifts & Advancements
Neoadjuvant immunotherapy protocols are rewriting surgical eligibility criteria, while real-world evidence collection infrastructures reshape post-market surveillance obligations for laryngeal cancer therapeutics developers.
Artificial intelligence-powered histopathology analysis is decomposing traditional diagnostic workflows in academic medical centers. Pathology departments at tertiary hospitals in the United States and Germany deploy deep learning algorithms to quantify tumor-infiltrating lymphocyte density. This capability is decomposing reliance on centralized reference laboratory review, compressing diagnostic turnaround from days to hours.
REACH regulation amendments targeting pharmaceutical manufacturing effluent are tightening active pharmaceutical ingredient discharge standards across European Union production facilities. EMA guidance now requires environmental risk assessments for novel oncology compounds prior to marketing authorization. Biologic manufacturers with antibody-drug conjugate pipelines are investing in closed-loop solvent recovery systems to maintain compliance.
Hospital procurement committees are consolidating laryngeal cancer therapeutic purchasing under value-based framework agreements. United States cancer centers increasingly bundle checkpoint inhibitor acquisition with companion diagnostic service contracts. This purchasing consolidation is concentrating vendor relationships among three to five integrated delivery networks per metropolitan region.
Global Laryngeal Cancer Therapeutics Market Segmentation
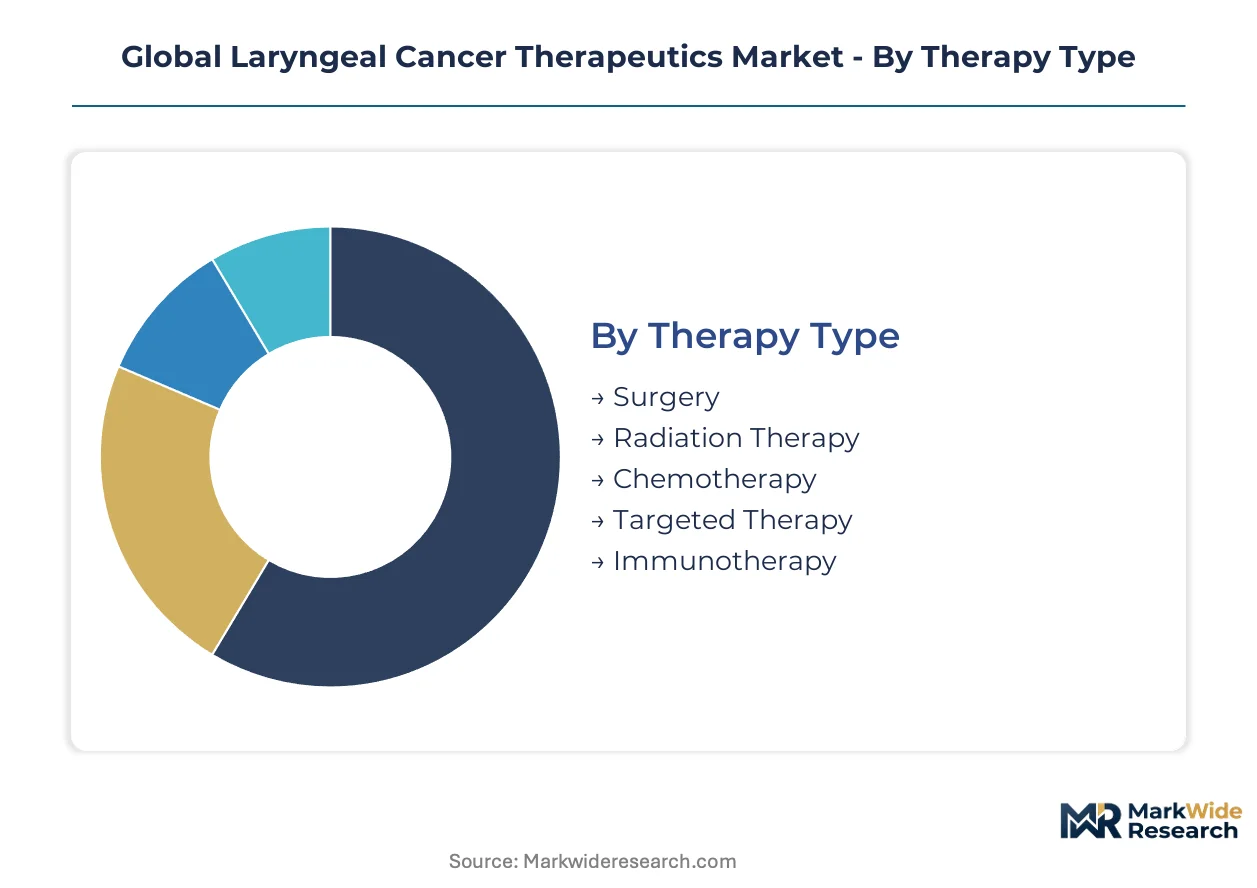
Therapeutic modality selection in laryngeal oncology hinges on tumor staging, organ preservation goals, and biomarker eligibility. Segmentation reveals how voice-function priorities redirect patient flows across delivery channels and care settings.
Therapy Type:
Surgery and radiation concentrate demand domestically across established tertiary centers, while immunotherapy and targeted therapy segments draw cross-border patient mobility for protocol access.
- Surgery:Total and partial laryngectomy procedures remain the definitive intervention for T3-T4a tumors with cartilage invasion. Demand clusters at academic medical centers in the United States and Germany where multidisciplinary tumor boards coordinate salvage protocols. Reimbursement stability supports predictable capacity planning despite limited volume growth.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways command premium positioning in recurrent and metastatic settings. United States cancer centers attract international patients for neoadjuvant pembrolizumab protocols. FDA breakthrough therapy designations compress enrollment timelines for combination trials.
- Radiation Therapy:Intensity-modulated and proton beam modalities preserve laryngeal function in early-stage glottic disease. Concentrated at regional referral networks with linear accelerator infrastructure.
- Chemotherapy:Platinum-based cisplatin and carboplatin regimens anchor induction and concurrent protocols. Generic pricing pressures constrain margin expansion despite persistent clinical utility.
- Targeted Therapy:EGFR inhibitors serve biomarker-selected squamous cell carcinoma subsets. Companion diagnostic dependencies limit addressable population.
Surgery commands the established base. The steepest expansion runs through immunotherapy.
Delivery Method:
Route selection maps directly to therapy type economics, with biologic formulations demanding cold-chain infrastructure that small-molecule oral agents bypass.
- Intravenous:Monoclonal antibody and platinum compound administration dominates hospital infusion center throughput. Cold-chain requirements inflate per-dose logistics costs by 15-25 percent versus oral alternatives. United States oncology networks consolidate purchasing under value-based framework agreements.
- Oral:Tyrosine kinase inhibitors and supportive care agents enable outpatient management. Germany's statutory health insurance funds favor oral regimens for reduced hospitalization expenditure.
- Injection:Subcutaneous checkpoint inhibitor formulations reduce infusion chair time. Japan's PMDA accelerated review tracks reward domestic clinical data for novel delivery technologies.
- Topical:Photodynamic therapy agents target superficial laryngeal lesions. Limited to specialized head and neck centers with laser infrastructure.
- Inhalation:Experimental aerosolized chemotherapy delivery remains investigational. Concentrated at academic research hospitals with dedicated pulmonary oncology units.
Intravenous delivery anchors current revenue. Oral formulations are climbing the fastest as patient preference and payer cost-containment converge.
Patient Demographic:
Age and sex distribution reflects tobacco and alcohol exposure epidemiology, with male-predominant incidence patterns shaping protocol design and marketing allocation.
- Adult Males:Historical tobacco and occupational carcinogen exposure drives 70-plus percent of incident cases. Voice preservation priorities intensify demand for organ-sparing protocols in professional voice users.
- Senior Citizens:Comorbidity burdens complicate treatment selection, favoring radiation and immunotherapy over surgical morbidity. Medicare reimbursement frameworks in the United States shape access patterns.
- Adult Females:Rising incidence among never-smoker cohorts prompts HPV testing integration. Japan's aging female population sustains patient volume in East Asian markets.
- Pediatric Patients:Rhabdomyosarcoma and rare laryngeal malignancies concentrate at designated children's hospitals. Clinical trial networks span St. Jude Children's Research Hospital and European pediatric oncology cooperative groups.
Adult males command the established base. Senior citizens are gaining share fastest as life expectancy extends and competing mortality declines.
Treatment Setting:
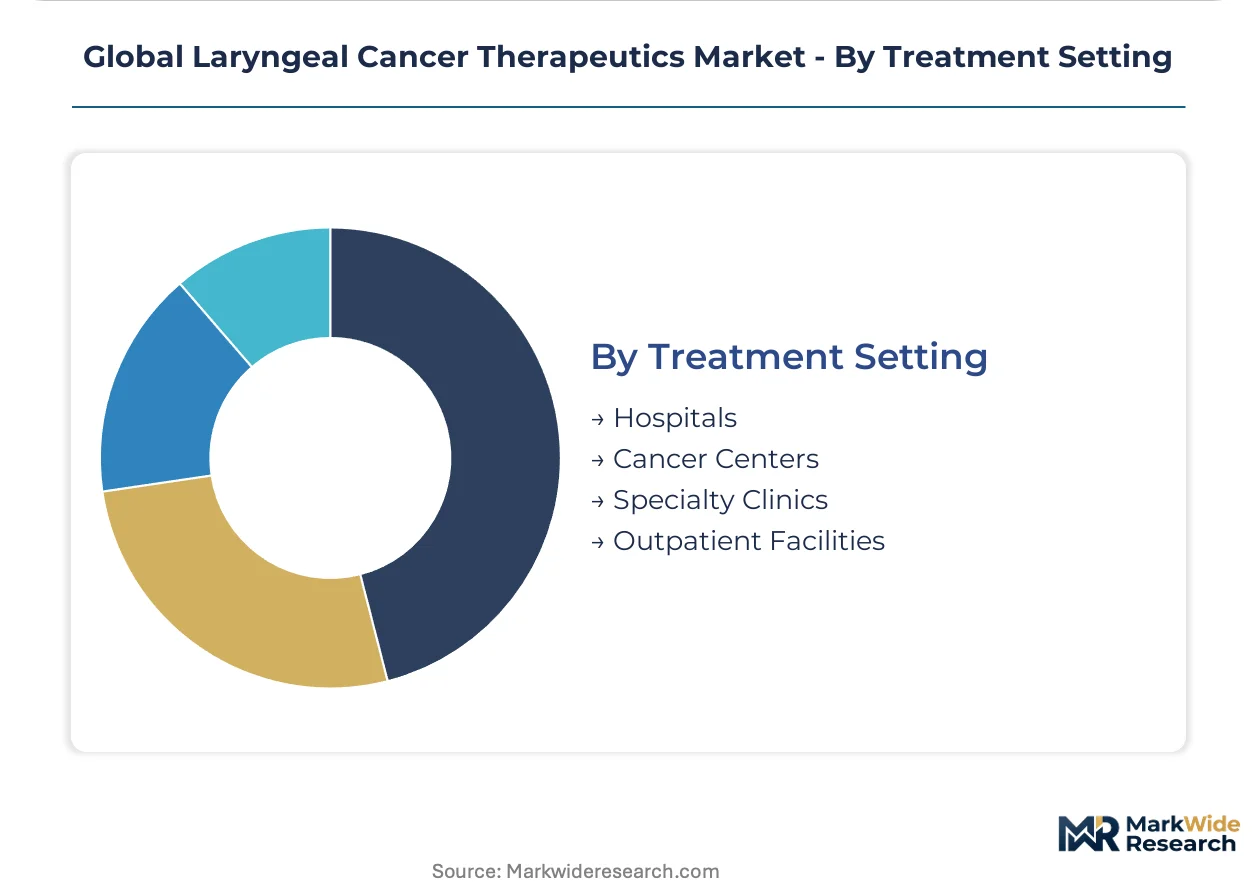
Site-of-care migration reflects reimbursement pressure and technology concentration, with complex procedures consolidating while stable patients shift ambulatory.
- Cancer Centers:NCI-designated comprehensive cancer centers in the United States anchor phase I-III trial enrollment. Dedicated head and neck oncology nursing specialization attracts disproportionate patient flows from community settings.
- Hospitals:Tertiary academic medical centers retain surgical volume and emergency airway management. Germany's university hospitals coordinate larynx-preserving multimodal protocols.
- Specialty Clinics:Private otolaryngology practices with in-office laryngoscopy capture early-stage diagnosis and surveillance. Japan's clinic-based chemotherapy administration reduces hospital bed utilization.
- Outpatient Facilities:Ambulatory infusion centers and radiation therapy suites extend reach into suburban United States markets. Telemedicine triage integration supports remote monitoring.
Hospitals command the established base. Cancer centers are expanding most quickly as trial access and specialized nursing concentrate patient preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes organ-preserving immunotherapy combinations, while Germany and Japan maintain stronger reliance on surgical intervention rates for locally advanced disease.
United States
Medicare reimbursement frameworks sustain demand for larynx-preserving protocols among senior citizens with long-duration tobacco exposure. FDA breakthrough therapy designations compress clinical trial enrollment timelines for novel checkpoint inhibitors. NCI-designated comprehensive cancer centers in Boston and Houston anchor phase I-III trial infrastructure.
Germany
Statutory health insurance funds favor oral tyrosine kinase regimens to reduce hospitalization expenditure. EMA priority medicines schemes reward domestic clinical data generation for antibody-drug conjugate candidates. University hospitals in Munich and Heidelberg coordinate multimodal larynx-preserving protocols.
Japan
Aging female population demographics sustain patient volume in East Asian markets. PMDA accelerated review tracks unlock priority status for novel checkpoint inhibitor combinations. Tokyo and Osaka metropolitan areas concentrate tertiary oncology centers with dedicated head and neck nursing specialization.
United Kingdom
NHS England cancer waiting time targets pressure rapid diagnostic pathway completion for laryngeal malignancies. NICE technology appraisals determine reimbursement eligibility for epidermal growth factor receptor inhibitors. London and Manchester academic medical centers deploy artificial intelligence-powered histopathology analysis.
India
Rising tobacco and smokeless tobacco use drives incident case growth among adult male cohorts. CDSCO accelerated approval pathways for oncology compounds shorten time-to-market for biosimilar checkpoint inhibitors. Mumbai and Delhi tertiary hospitals expand biomarker testing infrastructure for targeted therapy eligibility.
Global Laryngeal Cancer Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in laryngeal cancer therapeutics. Large-cap pharmaceutical conglomerates with immuno-oncology platforms command premium positioning through checkpoint inhibitor portfolios. Mid-tier biotech specialists concentrate on antibody-drug conjugate pipelines and companion diagnostic partnerships. Generic manufacturers anchor platinum-based chemotherapy supply. Dominant competitive moves include strategic portfolio diversification into voice-preservation protocols and geographic expansion through clinical trial network licensing.
Within the integrated leader tier, Bristol-Myers Squibb and Merck occupy positions defined by broad immuno-oncology infrastructure. AstraZeneca represents the antibody-drug conjugate specialization archetype with epidermal growth factor receptor pathway investments. These three companies exemplify how platform breadth versus targeted depth shapes competitive positioning in recurrent and metastatic disease settings.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb |
| Merck |
| Eli Lilly |
| Sanofi |
| AbbVie |
| Pfizer |
| AstraZeneca |
| Novartis |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between United States cancer centers and monoclonal antibody manufacturers lock in cold-chain capacity and price visibility across multi-year horizons, insulating procurement from spot-market volatility in biologic inputs while anchoring reimbursement negotiations with Medicare administrative contractors.
Pricing Analysis
Value-based framework agreements dominate United States procurement, bundling checkpoint inhibitor acquisition with companion diagnostic service contracts. Price differentiation hinges on biomarker testing integration and volume scale across integrated delivery networks. Cost compression in platinum-based chemotherapy intensifies because generic cisplatin and carboplatin face Indian and Chinese API oversupply. Community oncology practices in rural United States regions exhibit highest price sensitivity due to Medicare reimbursement caps, while NCI-designated comprehensive cancer centers leverage trial access to command premium positioning.
Supply Chain Analysis
Antibody cold-chain inventory cycles run 15-25 percent longer than small-molecule alternatives due to temperature-controlled logistics requirements. Active pharmaceutical ingredient production concentrates in China and India for platinum compounds, while biologic drug substance manufacturing clusters in United States, Germany, and Switzerland. Supply chain risk centers on single-source vulnerability for monoclonal antibody drug substance from contract manufacturing organizations. Distribution runs through hospital-based infusion centers and specialty pharmacy networks with validated cold-chain handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic service layers expand faster than pharmaceutical formulations in laryngeal cancer therapeutics, creating service-attach opportunities that extend customer lifetime value beyond drug procurement alone.
For Market Incumbents: Secure biomarker testing infrastructure partnerships to defend against biosimilar checkpoint inhibitor entrants from Indian and Chinese manufacturers. Backward integration into cold-chain logistics capabilities protects margin erosion from third-party distribution markups. Lock in long-term offtake agreements with United States integrated delivery networks before Medicare reimbursement compression accelerates. For New Entrants and Emerging Players: Anchor in Japan's PMDA accelerated review pathway for novel checkpoint inhibitor combinations, where domestic clinical data requirements create defensible positioning against global portfolio players. Target community oncology practices in underserved United States rural markets lacking next-generation sequencing capacity, offering turnkey biomarker testing bundles with therapy procurement. For Investors and Strategic Acquirers: Mid-cap biotech specialists with antibody-drug conjugate pipelines and companion diagnostic partnerships represent the most attractive acquisition archetype for platform expansion. Long-term viability hinges on voice-preservation protocol data generation that unlocks early-stage disease reimbursement. Watch for FDA breakthrough therapy designation announcements as inflection indicators for portfolio valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Bundled testing and therapy access streamlines United States payer reimbursement pathways for EGFR inhibitors. |
| Japan PMDA Clinical Trial Investment | Domestic data generation unlocks priority review status for novel checkpoint inhibitor combinations in recurrent disease. |
| Cold-Chain Logistics Integration | In-house temperature-controlled distribution reduces per-dose delivery costs and insulates against third-party capacity constraints. |
| Voice Preservation Protocol Development | Functional outcomes data expands reimbursement eligibility for organ-sparing immunotherapy in early-stage glottic disease. |
| Community Oncology Biomarker Infrastructure | Next-generation sequencing deployment in rural United States practices identifies previously missed targeted therapy candidates. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions underlying therapeutic demand projections. Primary fieldwork with formulary directors at NCI-designated cancer centers and EMA rapporteurs supplemented secondary validation against FDA filings, ClinicalTrials.gov enrollment data, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up patient volume estimates triangulated with top-down pharmaceutical revenue analytics.
Segmentation dimensions modeled span therapy type, delivery method, patient demographic, and treatment setting across the analysis window. Treatment line progression and biomarker eligibility status served as industry-specific forecast inputs. CAGRs were derived from patient incidence trajectories, protocol adoption curves, and reimbursement framework evolution throughout the forecast period.
Material uncertainties — regulatory approval delays, biomarker testing infrastructure buildout pace, and cold-chain logistics disruption — sit outside the modeled envelope. Forecasts reflect assumptions about FDA breakthrough therapy designation velocity and Medicare reimbursement stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market