
 Inherited Retinal Diseases Treatment Market | 2026-2036
Inherited Retinal Diseases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Inherited Retinal Diseases Treatment Market Foresight
US gene therapy manufacturing capacity is broadening as commercial-scale viral vector production comes online. Spark Therapeutics leverages its Philadelphia-based manufacturing infrastructure to anchor domestic supply of Luxturna. Novartis AG sustains European production networks while competing in North American distribution. Roche Holding AG differentiates through diagnostic-therapy pairing in inherited retinal disease portfolios.
Inherited retinal diseases treatment encompasses therapeutic interventions targeting monogenic retinal dystrophies, primarily delivered via adeno-associated viral vectors engineered to 4.7 kilobase payload capacity for precise photoreceptor transduction. These interventions aim to halt or reverse progressive vision loss in conditions caused by single-gene mutations affecting retinal pigment epithelium or photoreceptor function. Gene therapy occupies the highest-margin tier within product type segmentation, while stem cell therapy represents the fastest-advancing pipeline category. Application demand clusters around retinitis pigmentosa given its prevalence, though Stargardt disease therapies are gaining regulatory momentum. End user dynamics favor ophthalmology clinics for initial diagnosis, with hospitals retaining complex surgical and gene therapy administration.
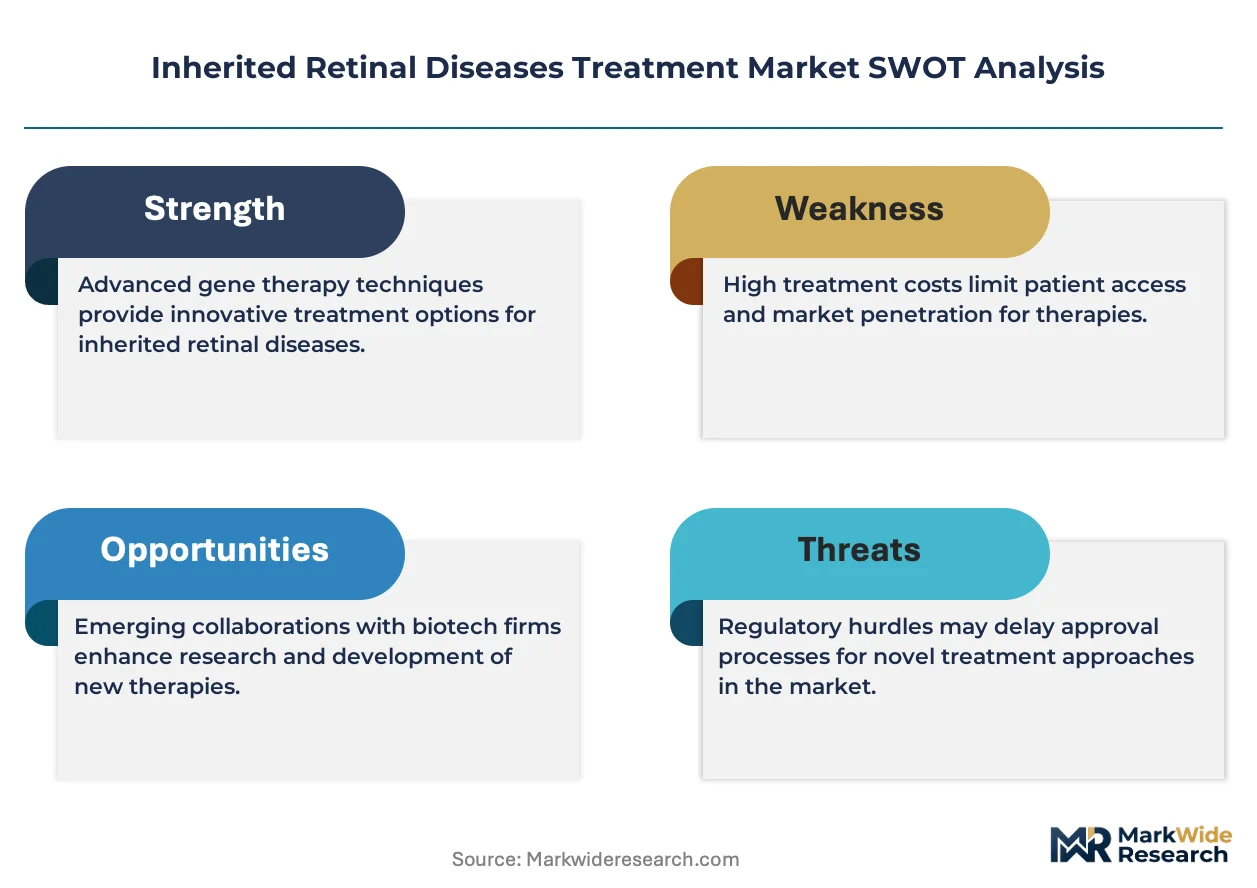
FDA breakthrough therapy designation and EMA PRIME eligibility shape clinical development timelines and reimbursement negotiations for developers. The EU AI Act and GDPR impose data governance requirements on retinal imaging datasets used for patient stratification in gene therapy trials. Stakeholders must monitor how CMS gene therapy payment models evolve alongside state-level Medicaid carve-outs for million-dollar single-administration treatments.
Market Dynamics
Gene therapy manufacturing capacity constraints are reshaping competitive positioning in inherited retinal disease treatment, as viral vector production bottlenecks force developers to secure captive supply or risk clinical trial delays.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress commercial timelines for single-administration gene therapies targeting RPE65 mutations, reducing time-to-reimbursement negotiations.
- Retinal imaging AI:Machine learning algorithms stratify patient eligibility for gene therapy trials, expanding addressable populations beyond genotype-confirmed cohorts.
- Academic medical center clustering:Specialized treatment hubs in Philadelphia, Boston, and Basel concentrate surgical expertise for subretinal injection procedures.
Market Restraints
- Plasmid DNA supply concentration:Contract manufacturers in Belgium and California control critical raw material inputs for AAV production, creating single-source vulnerability.
- 4.7 kilobase payload ceiling:AAV vector cargo limits exclude larger genes like ABCA4 from monogenic correction approaches, constraining Stargardt disease pipeline viability.
- Medicaid carve-out variability:State-level coverage decisions for million-dollar single-administration therapies create reimbursement access fragmentation across patient populations.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA's conditional approval pathway for stem cell therapies offers earlier commercial entry for photoreceptor replacement candidates.
- Diagnostic-therapy pairing:Genetic testing integration with treatment protocols creates value-capture opportunities in patient identification and monitoring.
- CRISPR base editing convergence:Precision nucleotide correction without double-strand breaks addresses dominant-negative mutations inadmissible to conventional gene supplementation.
Industry Challenges
- Vitreoretinal surgical capacity:Subretinal injection technique requires specialized training unavailable at community ophthalmology practices, limiting administration site expansion.
- Long-term durability monitoring:Decade-plus follow-up obligations for gene therapy efficacy and safety strain post-market surveillance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inherited Retinal Diseases Treatment Market |
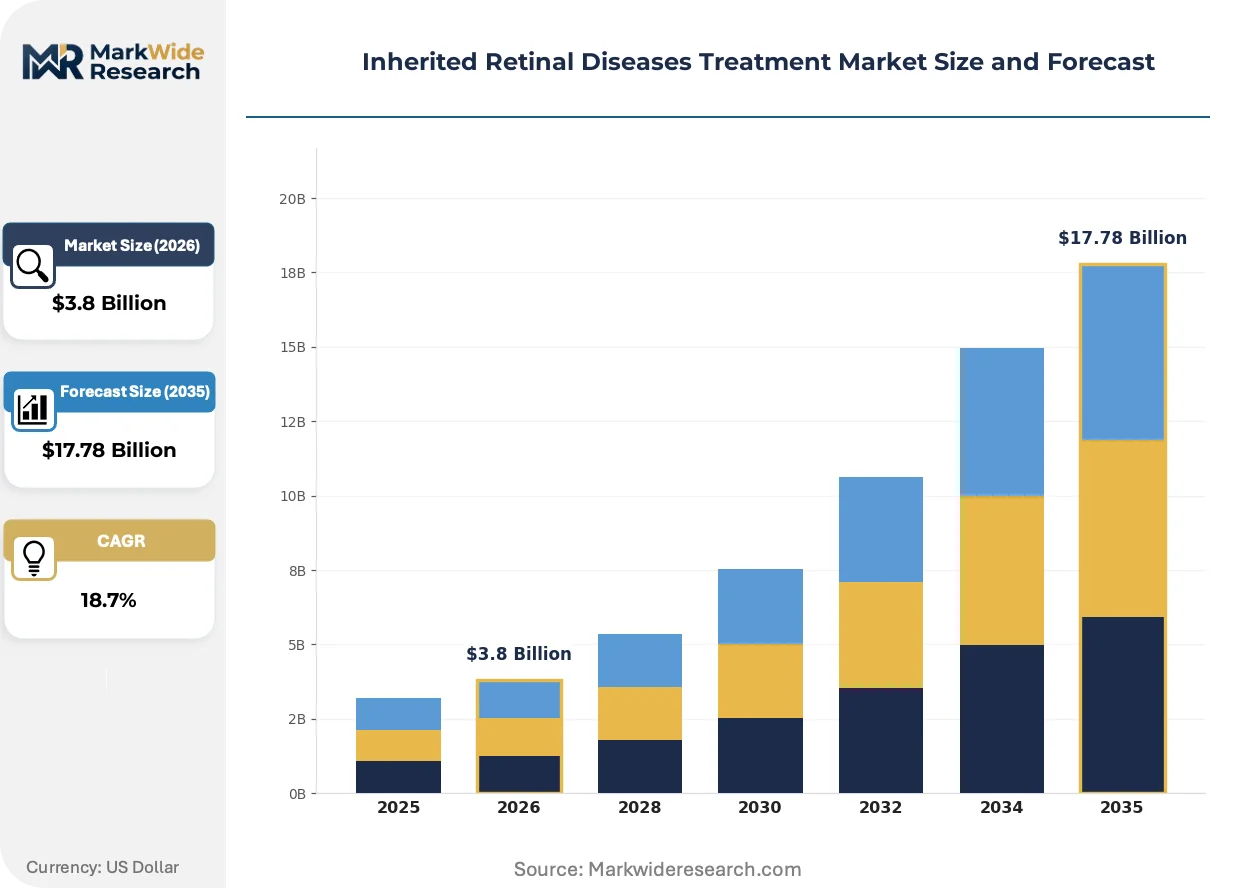
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Stem Cell Therapy, Pharmacotherapy, Surgery Application: Retinitis Pigmentosa, Stargardt Disease, Usher Syndrome, Choroideremia End User: Hospitals, Ophthalmology Clinics, Research Institutions, Home Care Settings Treatment Approach: Symptomatic Management, Curative Intervention, Gene Editing, Visual Rehabilitation |
| Companies Covered | Spark Therapeutics, Novartis AG, Johnson & Johnson, Regeneron Pharmaceuticals, Roche Holding AG, Biogen Inc., Astellas Pharma Inc., Ocugen Inc., ProQR Therapeutics NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inherited Retinal Diseases Treatment Market Shifts & Advancements
Next-generation delivery modalities and regulatory science advances are compressing development timelines while expanding the universe of addressable genetic targets in inherited retinal disease.
Dual AAV vector systems are converging with oversized gene delivery requirements, splitting therapeutic cassettes across two particles that reconstitute within target cells. Academic research groups and contract developers in Switzerland and Massachusetts are advancing these platforms toward clinical translation. The approach is converging with previously inaccessible targets like ABCA4, compressing the competitive timeline for Stargardt disease intervention.
EMA's PRIME eligibility criteria are expanding regulatory engagement for advanced therapy medicinal products, offering accelerated scientific advice and accelerated assessment pathways. Developers gain earlier alignment on quality, non-clinical, and clinical requirements. Gene therapy sponsors with inherited retinal disease portfolios are responding by front-loading manufacturing characterization and comparability protocols.
Patient advocacy organizations are consolidating procurement influence, negotiating managed access programs and outcomes-based arrangements directly with developers. Hospital pharmacy and therapeutics committees face pressure to accelerate gene therapy formulary inclusion timelines. This behavioral shift is most visible in United States academic medical centers, where foundation-sponsored patient registries feed real-world evidence generation requirements.
Inherited Retinal Diseases Treatment Market Segmentation
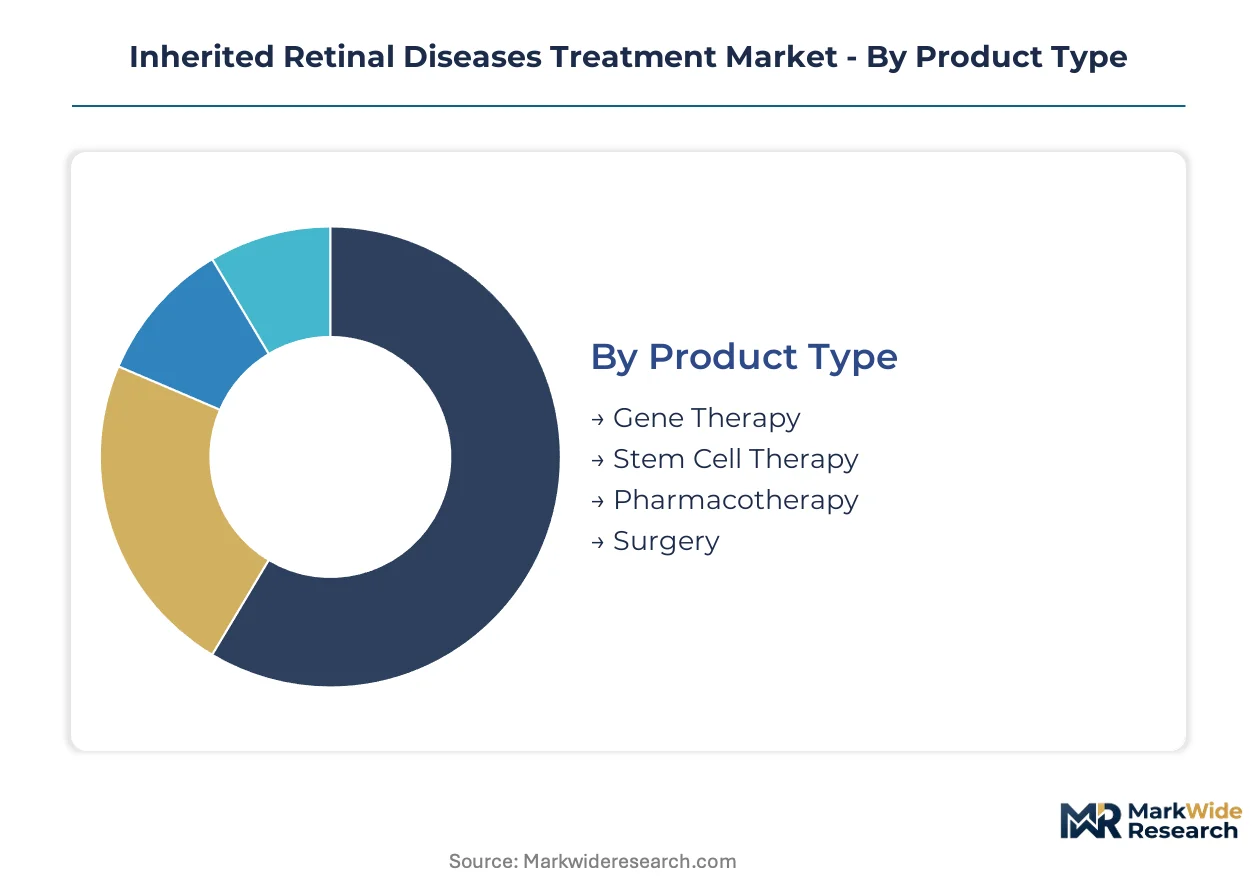
Segmentation in inherited retinal diseases treatment reveals how therapeutic modality, disease target, and care setting intersect to determine access patterns and reimbursement pathways. Product type and application segmentation carry the strongest pricing implications, while end user distribution shapes commercial strategy for gene therapy launch planning.
Product Type:
Payload capacity and manufacturing complexity differentiate margins across therapeutic modalities, with viral vector scale-up costs creating tiered commercial barriers.
- Gene Therapy:Adeno-associated viral vectors deliver functional gene copies via subretinal injection, with 4.7 kilobase payload constraints limiting target selection. United States academic medical centers concentrate demand for approved RPE65 therapies, while pipeline expansion targets larger genes through dual-vector systems.
- Stem Cell Therapy:Photoreceptor progenitor transplantation and retinal pigment epithelium replacement approaches require specialized surgical infrastructure. Japan's PMDA conditional approval pathway accelerates commercial timelines for allogeneic cell products, creating early-mover advantages in Asia-Pacific access.
- Pharmacotherapy:Small-molecule neuroprotection and visual cycle modulators address symptoms without genetic correction. Oral delivery expands community ophthalmology access beyond surgical centers.
- Surgery:Vitreoretinal procedures including submacular surgery and retinal prosthesis implantation retain role for advanced structural complications. Technique-dependent outcomes limit standardization.
Gene therapy leads on scale; stem cell therapy leads on momentum.
Application:
Disease prevalence and genetic target size determine addressable population and technical feasibility for curative approaches.
- Retinitis Pigmentosa:Heterogeneous genetic etiology spanning over 80 identified genes fragments development into mutation-specific programs. Clinical trial enrollment concentrates at United States and European sites with established natural history cohorts.
- Stargardt Disease:ABCA4 gene size exceeds standard AAV capacity, requiring dual-vector or alternative delivery platforms. EMA PRIME eligibility supports accelerated assessment for programs addressing this high-unmet-need pediatric population.
- Usher Syndrome:Dual sensory impairment (vision and hearing) creates distinct regulatory and reimbursement pathways. Patient advocacy organizations drive trial awareness in European and North American rare disease networks.
- Choroideremia:X-linked inheritance pattern enables clear genetic testing and male-targeted trial recruitment. CHM gene size permits single-vector gene supplementation approaches.
Retinitis pigmentosa dominates patient volume; Stargardt disease shows steepest expansion trajectory.
End User:
Care setting determines reimbursement capture, with hospital-based administration required for surgical and gene therapy delivery.
- Hospitals:Academic medical centers with vitreoretinal surgical expertise anchor gene therapy administration. CMS payment models and state Medicaid carve-outs shape access at major United States treatment hubs.
- Ophthalmology Clinics:Community and specialty clinics manage diagnosis, genetic counseling, and referral coordination. Diagnostic-therapy pairing creates value capture in patient identification.
- Research Institutions:Natural history study sites and clinical trial centers concentrate longitudinal data generation. Real-world evidence infrastructure supports post-market surveillance obligations.
- Home Care Settings:Limited current relevance for invasive therapies; future oral pharmacotherapy or sustained-release formulations may shift delivery location.
Hospitals capture highest-value procedures; ophthalmology clinics dominate patient touchpoints.
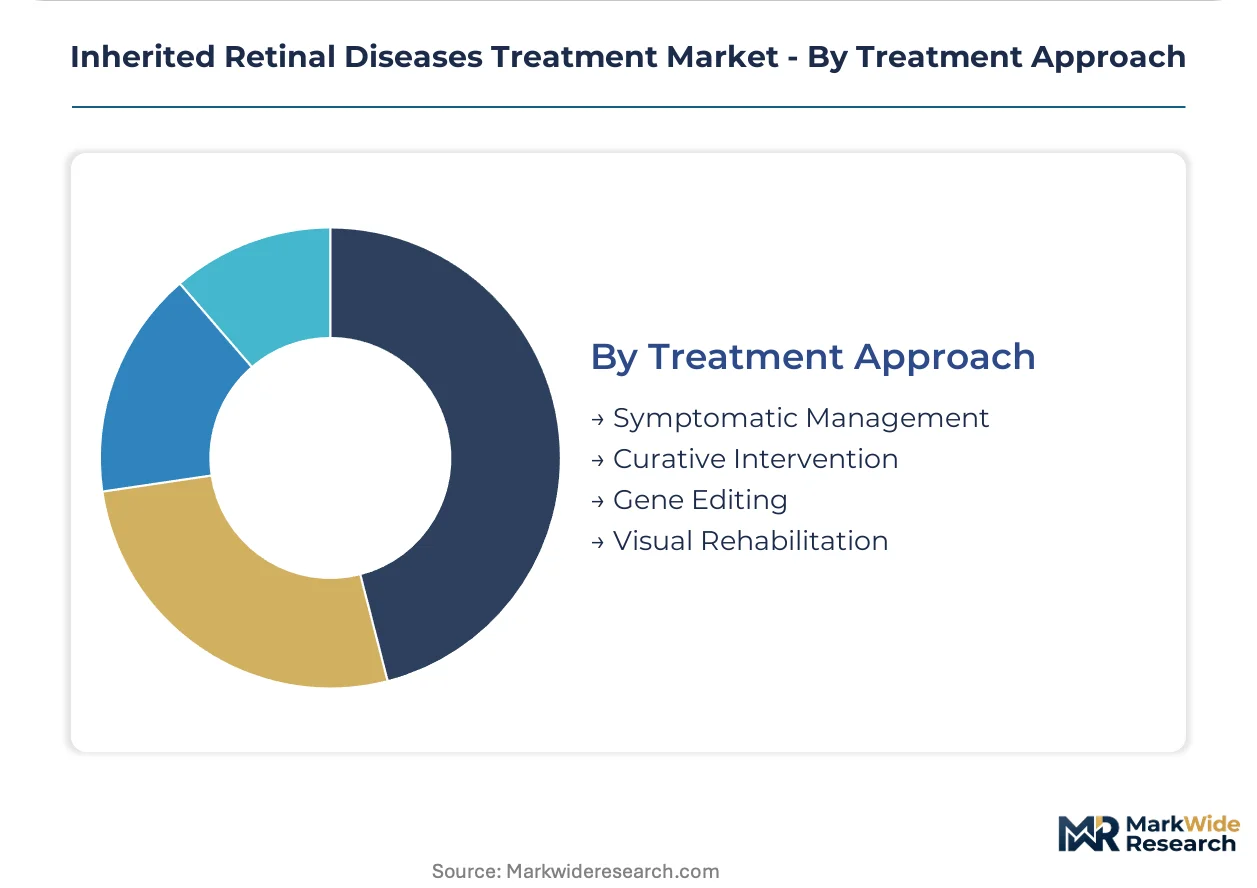
Treatment Approach:
Curative intent versus symptom management defines regulatory pathway, pricing architecture, and durability evidence requirements.
- Symptomatic Management:Low-vision aids, nutritional supplementation, and light avoidance counseling retain role across all disease stages. Cost containment focus limits pricing power.
- Curative Intervention:Single-administration gene or cell therapies command million-dollar price points with outcomes-based payment structures. Long-term durability monitoring obligations extend post-market commitments.
- Gene Editing:CRISPR base editing and prime editing address dominant-negative mutations inadmissible to supplementation. Preclinical programs target specific alleles with precision nucleotide correction.
- Visual Rehabilitation:Retinal prostheses and optogenetic approaches restore light perception in end-stage disease. FDA breakthrough device designation supports regulatory acceleration.
Curative intervention commands premium economics; gene editing represents the frontier of technical possibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing gravitates toward jurisdictions with streamlined ATMP approval pathways and concentrated academic medical infrastructure, creating cost-of-compliance arbitrage between established hubs and emerging biotech clusters.
United States
FDA breakthrough therapy designation compresses commercial timelines for RPE65-targeted interventions, accelerating reimbursement negotiations. CMS gene therapy payment models and state Medicaid carve-outs shape access at specialized treatment centers. Philadelphia and Boston anchor vitreoretinal surgical expertise, with Spark Therapeutics leveraging captive manufacturing infrastructure to secure domestic viral vector supply.
Switzerland
Swissmedic alignment with EMA PRIME eligibility supports accelerated assessment for advanced therapy medicinal products targeting pediatric populations. Basel concentrates gene therapy development and diagnostic-therapy pairing capabilities. Roche Holding AG sustains European production networks while competing in North American distribution channels.
Japan
PMDA's conditional approval pathway for regenerative medicine products accelerates commercial entry for photoreceptor replacement candidates. METI funding programs support allogeneic cell therapy scale-up. Tokyo and Osaka academic medical centers concentrate surgical expertise for subretinal injection procedures, creating early-mover advantages in Asia-Pacific access.
Germany
EMA centralized procedures and national reimbursement frameworks for orphan drugs stabilize pricing architecture for million-dollar single-administration therapies. Berlin and Heidelberg anchor natural history study infrastructure and clinical trial enrollment for retinitis pigmentosa cohorts. Federal research funding supports dual AAV vector platform development.
United Kingdom
MHRA post-Brexit regulatory autonomy enables tailored ATMP assessment timelines, though alignment with EMA scientific advice persists. London and Cambridge concentrate retinal imaging AI development for patient stratification. NHS England specialized commissioning frameworks negotiate outcomes-based arrangements for gene therapy access.
Inherited Retinal Diseases Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue CRISPR base editing and dual-vector delivery platforms to circumvent payload constraints. The market structures around three tiers: integrated pharmaceutical conglomerates with diagnostic-therapy pairing capabilities, mid-cap gene therapy specialists with captive manufacturing, and preclinical-stage platform technology developers. Strategic moves concentrate on securing plasmid DNA supply agreements and acquiring vitreoretinal surgical capacity through academic medical center partnerships.
Among US-based gene therapy developers, Spark Therapeutics and Regeneron Pharmaceuticals exemplify the integrated development-and-manufacturing archetype, while Novartis AG occupies a position bridging European production networks with North American commercial infrastructure. Roche Holding AG represents the diagnostic-therapy pairing model through ophthalmology portfolio integration. These anchors illustrate how competitive positioning depends on manufacturing sovereignty and surgical site access rather than molecule differentiation alone.
| Leading Market Players |
|---|
| Spark Therapeutics |
| Novartis AG |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| Roche Holding AG |
| Biogen Inc. |
| Astellas Pharma Inc. |
| Ocugen Inc. |
| ProQR Therapeutics NV |
| Others |
Supply & Pricing Matrix
EMA's PRIME eligibility and FDA breakthrough therapy designation gate qualified supply access and premium-tier pricing authorization for million-dollar single-administration gene therapies. Developers lacking these regulatory endorsements face reimbursement exclusion regardless of clinical merit.
Pricing Analysis
Distributor margins for viral vector supply concentrate at contract manufacturers in Belgium and California, compressing downstream pricing flexibility for gene therapy developers. Three-tier pricing structure across premium gene supplementation, standard pharmacotherapy, and economy symptomatic management reflects manufacturing scale and regulatory qualification depth. Cost compression in the standard tier intensifies as oral neuroprotective agents commoditize. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity; specialized academic medical centers with foundation-sponsored access programs demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for plasmid DNA inputs mandate multi-supplier qualification at AAV producers, yet contract manufacturers in Belgium and California retain effective single-source control. Viral vector production draws from recombinant plasmid DNA, HEK293 cell banks, and transfection reagents sourced from Switzerland and the United States. Single-source vulnerability in plasmid DNA supply creates concentration risk for clinical trial timelines. Distribution runs through cold-chain logistics networks terminating at hospital-based ophthalmology departments with subretinal injection capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's PMDA conditional approval pathway offers cost-of-time arbitrage against FDA and EMA timelines, enabling earlier commercial entry for regenerative medicine products with reduced clinical data packages.
For Market Incumbents: Acquire captive plasmid DNA manufacturing capacity to secure AAV vector supply against Belgian and Californian contract manufacturer bottlenecks. Deepen backward integration into HEK293 cell line production to reduce transfection reagent dependency. CRISPR base editing platforms threaten gene supplementation approaches; prioritize diagnostic-therapy pairing capabilities to lock patient identification channels.
For New Entrants and Emerging Players: Dual AAV vector systems for oversized gene delivery offer technology-first entry against established RPE65-targeted therapies. White-space concentration sits with Stargardt disease dual-vector approaches and Usher syndrome combination programs. Japan's regenerative medicine framework provides the most penetrable regulatory geography. Go-to-market positioning through academic medical center surgical partnerships bypasses hospital formulary committee resistance.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap gene therapy specialists with captive manufacturing because viral vector production scale barriers prevent rapid competitive replication. Five-to-ten-year viability hinges on durability data from decade-plus follow-up obligations. Target acquisition archetype: developers with EMA PRIME eligibility and front-loaded manufacturing characterization protocols. Watch CMS gene therapy payment model expansion as inflection indicator for US reimbursement access.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Commercial-scale AAV production at Spark Therapeutics' Philadelphia facility anchors domestic supply security. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses scientific advice timelines for pediatric Stargardt disease programs. |
| Diagnostic-Therapy Pairing | Roche Holding AG's ophthalmology portfolio integration captures value in patient identification and monitoring. |
| Academic Medical Center Partnership | Surgical site access at Boston and Philadelphia hubs limits administration expansion to qualified vitreoretinal specialists. |
| Pipeline Diversification | Dual-vector ABCA4 programs address payload constraints excluding monogenic correction approaches. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at EMA and FDA, hospital formulary directors, and payer access specialists with secondary validation. Sources included FDA breakthrough therapy designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov inherited retinal disease protocol registrations, and CMS gene therapy payment model documentation. Bottom-up patient population estimates and top-down market sizing triangulated across viral vector production capacity and treatment center penetration data.
Segment-weighting approaches applied differential growth assumptions across gene therapy, stem cell therapy, pharmacotherapy, and surgery modalities. Modeling incorporated treatment line, genetic target size, administration route, and regional regulatory cluster dimensions. CAGRs derived from natural history study enrollment trajectories, manufacturing capacity expansion announcements, and reimbursement framework adoption curves. Forecast inputs included subretinal injection surgical site growth and dual AAV vector clinical translation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS payment model evolution, Medicaid carve-out variability, and decade-plus durability data emergence. Forecasts reflect documented assumptions regarding regulatory pathway success rates and manufacturing scale-up execution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Retina Health Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Laser Indirect Ophthalmoscope Market