
 Interventional Neurology Market | 2026-2036
Interventional Neurology Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Neurology Market Outlook
The EU Medical Device Regulation is pivoting conformity assessment requirements toward stricter clinical evidence for neurovascular implants. Medtronic leverages its integrated stroke care platform to sustain hospital system partnerships across North America. Stryker Corporation anchors its competitive position through specialized thrombectomy device portfolios that dominate emergency procedural workflows.
Interventional neurology encompasses catheter-based minimally invasive procedures to diagnose and treat cerebrovascular conditions including ischemic stroke, intracranial aneurysms, and arterial stenosis, utilizing fluoroscopic guidance with biocompatible nitinol and platinum-iridium alloy devices delivered through femoral or radial access. Thrombectomy procedures occupy the largest procedural volume segment as acute ischemic stroke protocols standardize mechanical clot retrieval within six-hour windows. Robotics technology leads growth trajectory among imaging modalities as remote catheter navigation systems reduce operator radiation exposure and enable telesurgical applications in underserved regions.
FDA premarket approval pathways and EU MDR conformity assessments shape neurovascular device commercialization timelines and clinical trial investment requirements. CMS national coverage determinations directly influence hospital capital allocation toward thrombectomy-capable stroke centers in the United States. Stakeholders must monitor evolving robotics reimbursement codes and telesurgical liability frameworks as procedural automation expands beyond traditional academic medical centers.
Market Dynamics
Mechanical thrombectomy protocol standardization is compressing door-to-puncture timelines across hospital systems, forcing device manufacturers to optimize catheter deliverability and clot engagement mechanics for emergency workflows rather than incremental feature differentiation.
Growth Catalysts
- CMS Reimbursement Expansion:National coverage determinations for thrombectomy procedures are accelerating capital deployment toward stroke center certification in United States hospital networks.
- Nitinol Alloy Advances:Superelastic nickel-titanium compositions enable smaller-profile delivery catheters that navigate tortuous intracranial vasculature with reduced vessel trauma.
- Germany's Neuroradiology Networks:Specialized departments in Munich, Berlin, and Hamburg coordinate prehospital stroke triage with emergency medical services to minimize treatment delays.
Market Restraints
- Platinum-Iridium Supply Concentration:Electrode and coil manufacturing depends on concentrated refining capacity in South Africa and Russia, exposing device makers to geopolitical input volatility.
- EU MDR Clinical Evidence Burden:Neurovascular implants now require extended follow-up data and notified body scrutiny, extending commercialization timelines by 18-36 months.
- Fluoroscopy Dose Limitations:Operator radiation exposure caps restrict procedural volumes per specialist, constraining throughput in high-volume stroke centers.
Strategic Opportunities
- Telesurgical Robotics:Remote catheter navigation systems are integrating 5G latency compensation to enable specialist-guided thrombectomy in rural and underserved regions.
- Radial Access Conversion:Transradial approaches reduce femoral access complications and accelerate patient ambulation, creating preference differentiation for device platforms optimized for wrist entry.
- India Stroke Infrastructure:Government-funded hub-and-spoke stroke networks in Maharashtra, Tamil Nadu, and Karnataka are creating first-mover advantages for thrombectomy device suppliers.
Industry Challenges
- Neurointerventionalist Training Pipeline:Fellowship positions produce fewer qualified operators than expanding stroke center capacity requires, creating procedural bottlenecks.
- FDA Premarket Approval Timelines:Breakthrough device designation pathways still demand extensive clinical trials for novel thrombectomy mechanisms, consuming R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Neurology Market |
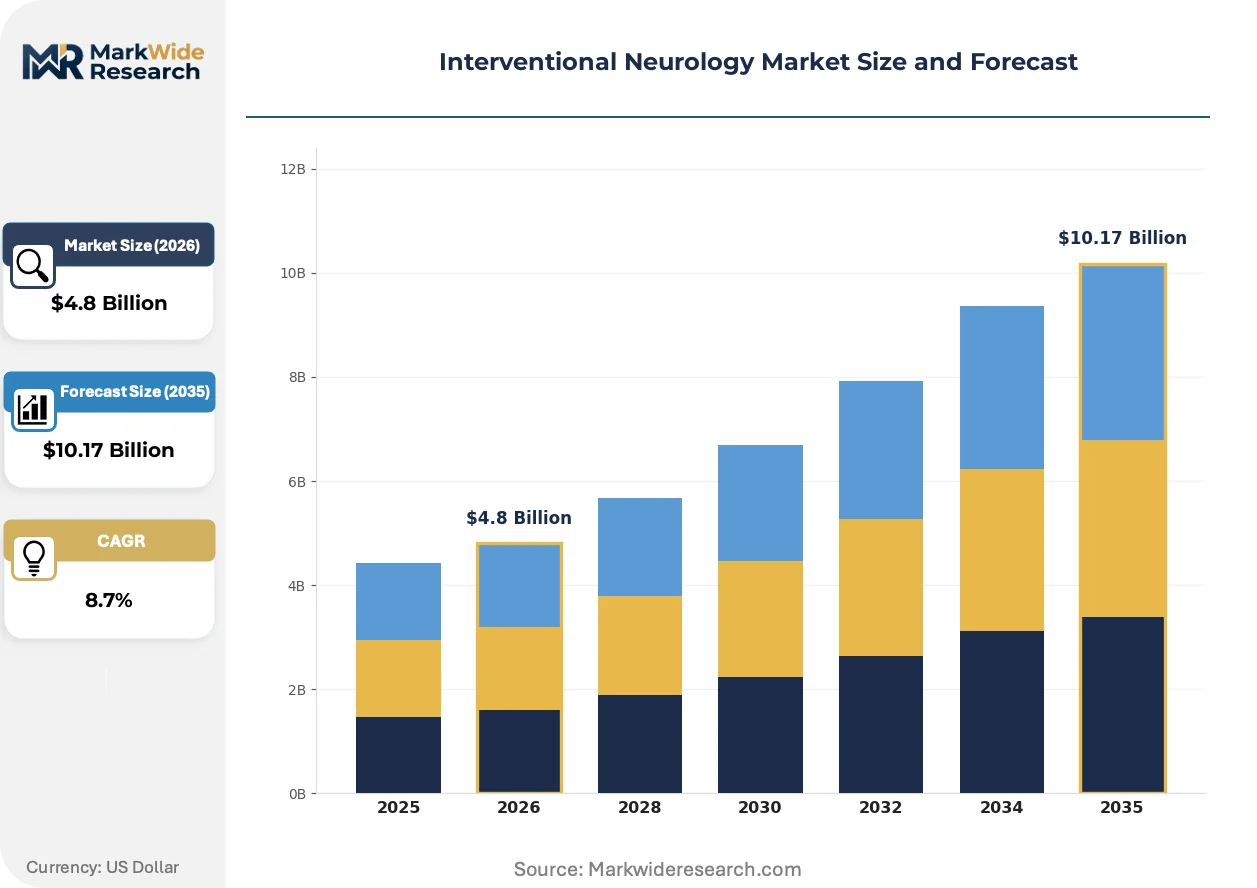
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intracranial Stents, Catheters, Guidewires, Balloons End User: Hospitals, Neurology Clinics, Research Institutions, Outpatient Facilities Procedure Type: Thrombectomy, Aneurysm Coiling, Angioplasty, Embolization Technology: Fluoroscopy, MRI, CT Imaging, Robotics |
| Companies Covered | Stryker Corporation, Medtronic, Johnson & Johnson, Penumbra Inc., Terumo Corporation, Abbott Laboratories, MicroPort Scientific Corporation, Boston Scientific Corporation, W. L. Gore & Associates Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Neurology Market Strategic Shifts
Artificial intelligence is embedding into procedural workflows, reshaping how clot characterization, device selection, and outcome prediction occur before catheter insertion.
Robotic catheter systems are integrating haptic feedback and automated navigation algorithms to reduce operator radiation exposure during complex intracranial procedures. Academic medical centers in Boston, Toronto, and Heidelberg are piloting these platforms for middle cerebral artery interventions. The technology is integrating remote surgical capabilities that extend specialist reach beyond traditional tertiary referral boundaries.
EU MDR conformity assessment requirements are tightening clinical evidence standards for neurovascular implants, mandating extended follow-up registries and post-market surveillance. Device manufacturers must now allocate substantial resources to notified body negotiations and clinical data generation. High-risk implantable categories face the most significant timeline extensions and documentation burdens.
Hospital procurement committees are consolidating vendor relationships around integrated stroke care platforms rather than discrete device purchases. Comprehensive service contracts bundle thrombectomy devices, imaging equipment, and training support into multi-year agreements. This concentration is most pronounced in United States integrated delivery networks seeking to standardize protocols across multiple facilities.
Interventional Neurology Market Segmentation
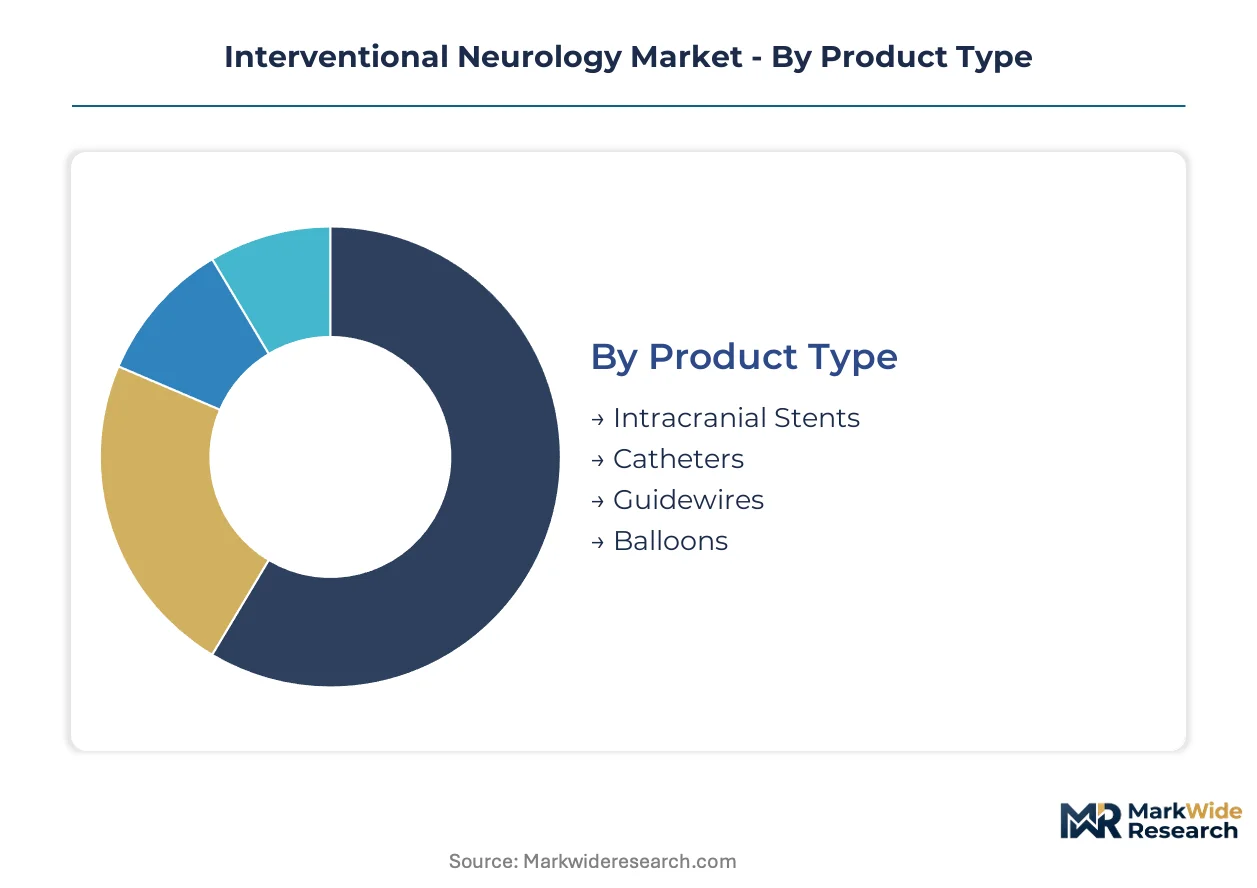
Interventional neurology device procurement follows distinct patterns across clinical settings and procedural applications. Understanding these segment boundaries enables suppliers to align R&D investment with upgrade cycles and replacement demand trajectories.
Product Type:
Device replacement cycles vary sharply across product categories, with stent platforms requiring longer validation timelines than disposable catheters.
- Intracranial Stents:Nitinol and cobalt-chromium alloy constructions provide radial force for intracranial atherosclerotic disease. Demand clusters in comprehensive stroke centers across Germany and the United States where carotid and intracranial stenosis protocols have matured.
- Catheters:Aspiration and stent-retriever delivery systems dominate procedural volumes. Japan's neuroradiology departments in Tokyo and Osaka drive preference for trackable distal access platforms that reduce vessel perforation risk.
- Guidewires:Hydrophilic-coated nitinol cores enable submillimeter navigation through tortuous cerebral vasculature.
- Balloons:Compliant and semi-compliant designs support angioplasty in intracranial and cervical applications.
Volume placements concentrate in catheters; the faster expansion belongs to intracranial stents as flow diversion indications broaden.
End User:
Capital allocation patterns diverge between integrated hospital networks and specialized outpatient operators.
- Hospitals:Comprehensive stroke centers command the highest device throughput. CMS reimbursement frameworks in the United States direct capital toward thrombectomy-capable facilities, while NHS England's stroke network consolidation drives similar concentration.
- Neurology Clinics:Ambulatory settings concentrate diagnostic angiography and follow-up procedures. India's hub-and-spoke stroke networks in Maharashtra and Tamil Nadu are expanding clinic-based triage capacity.
- Research Institutions:Academic medical centers in Boston, Toronto, and Heidelberg pilot robotic platforms and AI-integrated workflows.
- Outpatient Facilities:Standalone centers capture elective aneurysm screening and post-procedural monitoring.
Procurement authority centralizes in hospital systems; neurology clinics are gaining share fastest as radial access enables same-day discharge protocols.
Procedure Type:
Clinical guideline evolution is reweighting procedure mix toward acute interventions.
- Thrombectomy:Mechanical clot retrieval for acute ischemic stroke occupies the largest procedural volume. Extended time window approvals in the United States and European Union are expanding eligible patient populations.
- Aneurysm Coiling:Endovascular embolization with platinum coils and flow diverters challenges surgical clipping. Demand concentrates in tertiary referral centers with 24/7 neurointerventional coverage.
- Angioplasty:Balloon and stent-assisted revascularization addresses intracranial stenosis.
- Embolization:Liquid embolic agents and microcoils treat arteriovenous malformations and tumors.
Thrombectomy claims the steepest expansion trajectory as prehospital triage networks compress treatment delays.
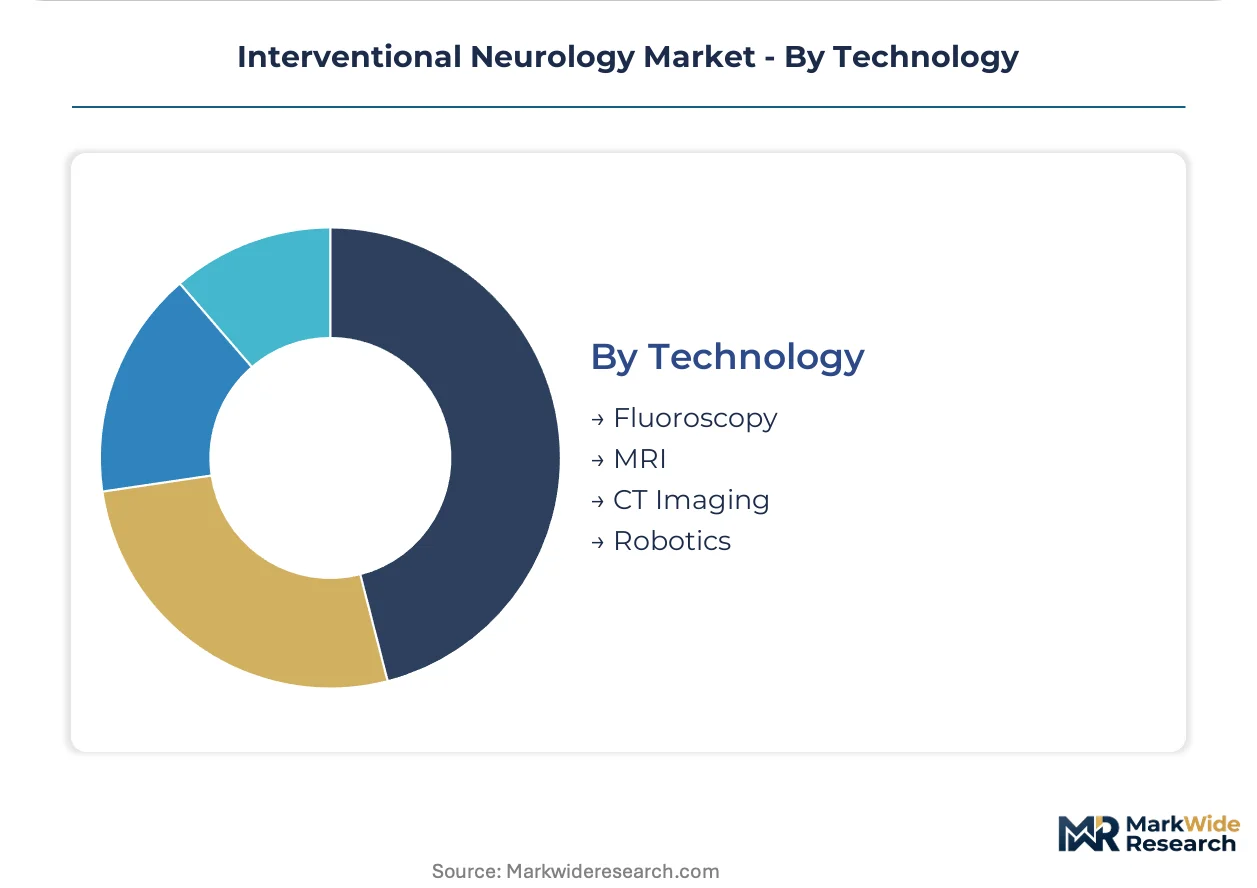
Technology:
Imaging modality selection determines capital expenditure profiles and operator training requirements.
- Fluoroscopy:Digital subtraction angiography remains the procedural backbone. Radiation dose management constraints in the United States and European Union are accelerating flat-panel detector upgrades.
- Robotics:Remote catheter navigation systems reduce operator exposure and enable telesurgical applications. Academic centers in Canada and Switzerland are validating 5G-integrated platforms for rural extension.
- MRI:Intraoperative magnetic resonance supports complex aneurysm and AVM procedures.
- CT Imaging:Perfusion CT guides patient selection for thrombectomy beyond standard time windows.
Installed fluoroscopy bases dominate current revenue; robotics platforms are climbing the fastest as liability frameworks for remote surgery crystallize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American interventional neurology innovation through Massachusetts General Hospital and Brigham and Women's Hospital, where robotic thrombectomy platforms undergo clinical validation. Device procurement concentrates in metropolitan corridors with comprehensive stroke center density.
United States
CMS national coverage determinations for mechanical thrombectomy accelerate hospital capital deployment toward stroke center certification. FDA premarket approval pathways shape neurovascular device commercialization timelines and clinical trial investment requirements. The Cleveland Clinic and Mayo Clinic anchor device evaluation networks in Ohio and Minnesota.
Germany
Specialized neuroradiology departments in Munich, Berlin, and Hamburg coordinate prehospital stroke triage with emergency medical services to compress door-to-puncture times. EU MDR conformity assessments mandate extended follow-up data for neurovascular implants, extending commercialization timelines. The Heidelberg University Hospital pilots robotic catheter navigation systems for middle cerebral artery interventions.
Japan
Neuroradiology departments in Tokyo and Osaka drive preference for trackable distal access platforms that reduce vessel perforation risk. PMDA regulatory frameworks govern biocompatibility testing for nitinol and platinum-iridium alloy devices. The University of Tokyo Hospital integrates AI-assisted clot characterization into emergency procedural workflows.
India
Government-funded hub-and-spoke stroke networks in Maharashtra, Tamil Nadu, and Karnataka create first-mover advantages for thrombectomy device suppliers. CDSCO medical device registration requirements govern import and local manufacturing pathways. Mumbai's Kokilaben Dhirubhai Ambani Hospital anchors private-sector stroke infrastructure expansion.
Canada
Academic medical centers in Toronto validate 5G-integrated robotic platforms for rural thrombectomy extension. Health Canada premarket licensing requirements align with FDA breakthrough device pathways for neurovascular innovations. The University Health Network coordinates telesurgical trials extending specialist reach to Northern Ontario.
Interventional Neurology Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with integrated stroke care platforms. Hospital procurement committees consolidate vendor relationships around comprehensive service contracts rather than discrete device purchases. Three archetypes dominate: diversified conglomerates with full neurovascular portfolios, specialized thrombectomy device manufacturers, and emerging robotics platform developers. Dominant competitive moves include strategic partnerships for integrated care platforms and geographic expansion into underpenetrated stroke networks.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions exemplifying the integrated platform archetype. Stryker anchors competitive positioning through specialized thrombectomy device portfolios, while Medtronic leverages hospital system partnerships across North America. Johnson & Johnson represents the diversified healthcare conglomerate model with cross-segment resource allocation capabilities. These three entities collectively illustrate how scale and integration define competitive positioning in device procurement consolidation.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medtronic |
| Johnson & Johnson |
| Penumbra Inc. |
| Terumo Corporation |
| Abbott Laboratories |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| W. L. Gore & Associates Inc. |
| Others |
Value Chain & Pricing Dynamics
EU MDR extended follow-up mandates for neurovascular implants gate qualified supply access, restricting premium-tier pricing to manufacturers with notified body certification and post-market surveillance infrastructure. Device procurement committees in United States hospital systems concentrate purchasing power around integrated stroke care platforms, compressing margins for standalone catheter suppliers while rewarding comprehensive service bundling.
Pricing Analysis
Value-based pricing anchored to door-to-puncture time reduction and stroke outcome metrics dominates comprehensive stroke center procurement. Three-tier pricing structure across premium, standard, and economy levels separates robotic-integrated platforms from conventional catheter systems and basic guidewire portfolios. Cost compression in economy-tier disposable catheters is intensifying because of India's hub-and-spoke network volume aggregation. Academic medical centers exhibit lowest price sensitivity due to training and research bundling requirements.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and local-content preferences in Maharashtra and Tamil Nadu are reshaping sourcing patterns for multinational suppliers. Nitinol alloy refining concentrates in China and Germany, while platinum-iridium electrode production draws from South African and Russian refining capacity. Single-source vulnerability in superelastic nickel-titanium compositions exposes device makers to geopolitical input disruption. Distribution runs through specialized neuroradiology distributors with GPO contract management capabilities in United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where neurointerventionalist fellowship output limits procedural throughput, propping pricing power for thrombectomy-capable centers and their preferred device suppliers.
For Market Incumbents: Deploy integrated stroke care platform consolidation to capture multi-year hospital system contracts before robotics entrants fragment procurement authority. Stryker and Medtronic anchor positioning through specialized thrombectomy portfolios that dominate emergency workflows. Threat substitution from telesurgical robotics platforms demands preemptive partnership with academic medical centers piloting remote catheter navigation.
For New Entrants and Emerging Players: Launch via telesurgical equipment leasing models targeting rural stroke network extension in Canada and Northern Ontario. India's government-funded hub-and-spoke networks in Karnataka and Tamil Nadu represent the most penetrable geography for first-mover thrombectomy device suppliers. Go-to-market angle should emphasize radial access platform optimization for same-day discharge protocols.
For Investors and Strategic Acquirers: FDA breakthrough device designation for novel thrombectomy mechanisms is the leading indicator that robotics platform developers are approaching commercialization inflection. Long-term viability favors diversified conglomerates with cross-segment resource allocation and hospital system partnership depth. Signal to watch: CMS reimbursement code finalization for remote surgical procedures.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments extend commercialization timelines for neurovascular implants by mandating extended follow-up registries. |
| Hospital System Partnership | Comprehensive stroke center certification in United States networks bundles thrombectomy devices with imaging equipment and training support. |
| Software Companion Development | AI-assisted clot characterization integration at University of Tokyo Hospital reshapes emergency procedural workflows and device selection. |
| Reimbursement Strategy | CMS national coverage determinations directly influence capital allocation toward thrombectomy-capable stroke centers across hospital networks. |
| Geographic Expansion | Heidelberg University Hospital pilots robotic catheter navigation for middle cerebral artery interventions, validating European telesurgical adoption. |
Study Parameters
FDA 510(k) filings, CMS national coverage determination databases, and EU MDR notified body assessment records formed the secondary backbone for neurovascular device commercialization timeline analysis. Primary interviews with neurointerventionalists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation through PMDA regulatory filings and CDSCO registration pathways. Bottom-up procedural volume modeling and top-down market sizing triangulation anchored the analytical framework.
Historical trendline analysis of thrombectomy procedure volumes, stent placement rates, and robotic platform installations informed the projection methodology across the analysis window. Segmentation dimensions modeled include product type, end user category, procedure type, and technology modality with regional regulatory cluster differentiation. CAGRs were derived from weighted average growth contributions across segment trajectories, incorporating nitinol alloy supply constraints and neurointerventionalist training pipeline bottlenecks as limiting inputs.
Platinum-iridium supply disruption, EU MDR timeline extensions, and telesurgical liability framework uncertainty are the dominant revision risks to forecast assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Multiple Sclerosis Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Arachnoiditis Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Cognitive Neuroscience Market
Neurology
Intracranial Aneurysm Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Neurology Services Market
Neurology
3D Neuroscience Market
Neurology
United States Neurology Devices Market
Neurology
Arachnoiditis Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
China Neurology Devices Market