
 Neurology Digital Therapeutics Market | 2026-2036
Neurology Digital Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Neurology Digital Therapeutics Market Foresight
The direct-to-patient channel is narrowing as neurology digital therapeutics migrate toward clinician-mediated reimbursement pathways. Akili Inc anchors its position through FDA-cleared pediatric ADHD interventions that require physician oversight. Mindmaze competes in stroke rehabilitation by leveraging immersive neurotechnology platforms deployed through hospital systems. Omada Health Inc extends its reach via payer contracts that integrate behavioral neurology modules into chronic disease management programs.
Neurology digital therapeutics encompass software-driven interventions that deliver evidence-based therapeutic content through mobile applications, wearable peripherals, and cloud-connected platforms to treat or manage neurological and neuropsychiatric conditions. These systems employ real-time biometric feedback, adaptive algorithms, and structured cognitive protocols to modulate neural pathways and patient-reported outcomes. Software platforms command the deepest margin pools due to recurring subscription economics and lower per-unit distribution costs than wearable hardware. Mobile apps for depression and anxiety represent the fastest-expanding application cluster as payers recognize their scalability for mild-to-moderate cases. Subscription-based delivery models dominate enterprise contracting with healthcare providers, while pay-per-use structures gain traction in pilot programs seeking utilization-linked outcomes validation.
FDA regulates these products as Software as a Medical Device under 21 CFR quality system requirements, with breakthrough device designations compressing review timelines for novel neurology indications. The EU MDR and CE marking framework impose clinical evidence standards that favor platforms with randomized controlled trial data, filtering out lower-validity entrants. Japan's PMDA has established a fast-track pathway for digital therapeutics addressing dementia and stroke sequelae, aligning reimbursement with functional outcome metrics. Stakeholders must monitor evolving payer coverage determinations that will separate reimbursed prescription-grade platforms from wellness applications excluded from formal care pathways.
Market Dynamics
Clinician-mediated reimbursement pathways are compressing direct-to-consumer channels as payers demand physician oversight for software-based neurological interventions. FDA breakthrough designations and EU MDR CE marking timelines now determine competitive entry sequencing.
Growth Catalysts
- Breakthrough Device Designation:FDA's compressed review pathway accelerates market entry for novel ADHD and migraine platforms, reducing time-to-revenue by 12-18 months versus standard 510(k) routes.
- Payer Contract Integration:Chronic disease management programs in the United States now embed behavioral neurology modules, creating institutional demand pull through employer-sponsored health plans.
- Adaptive Algorithm Maturation:Real-time biometric feedback systems enable personalized cognitive protocol adjustment, improving patient-reported outcomes and strengthening formulary inclusion arguments.
Market Restraints
- Clinical Evidence Thresholds:EU MDR randomized controlled trial requirements filter out lower-validity entrants, raising capital requirements for platform developers seeking CE marking.
- Reimbursement Fragmentation:Inconsistent coverage determinations across German statutory health insurers and Japanese prefectural health authorities create geographic revenue volatility.
- Hardware Margin Compression:Wearable peripheral costs concentrate in semiconductor and sensor supply chains, squeezing gross margins for integrated platform vendors.
Strategic Opportunities
- Japan Fast-Track Pathway:PMDA's accelerated authorization for dementia and stroke sequelae platforms aligns reimbursement with functional outcomes, rewarding outcome-validated entrants.
- Stroke Rehabilitation Convergence:Immersive neurotechnology paired with cloud-connected physiotherapy protocols opens hospital system contracting channels previously closed to software-only vendors.
- Subscription Model Migration:Enterprise healthcare providers prefer recurring revenue structures over perpetual licenses, enabling multi-year contract values and predictable cash flows.
Industry Challenges
- Interoperability Architecture:Integration with legacy electronic health record systems requires FHIR-compliant middleware development, extending implementation timelines for hospital deployments.
- Specialized Talent Scarcity:Computational neuroscientists and regulatory affairs specialists with Software as a Medical Device experience command premium compensation, constraining R&D velocity for mid-stage developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurology Digital Therapeutics Market |
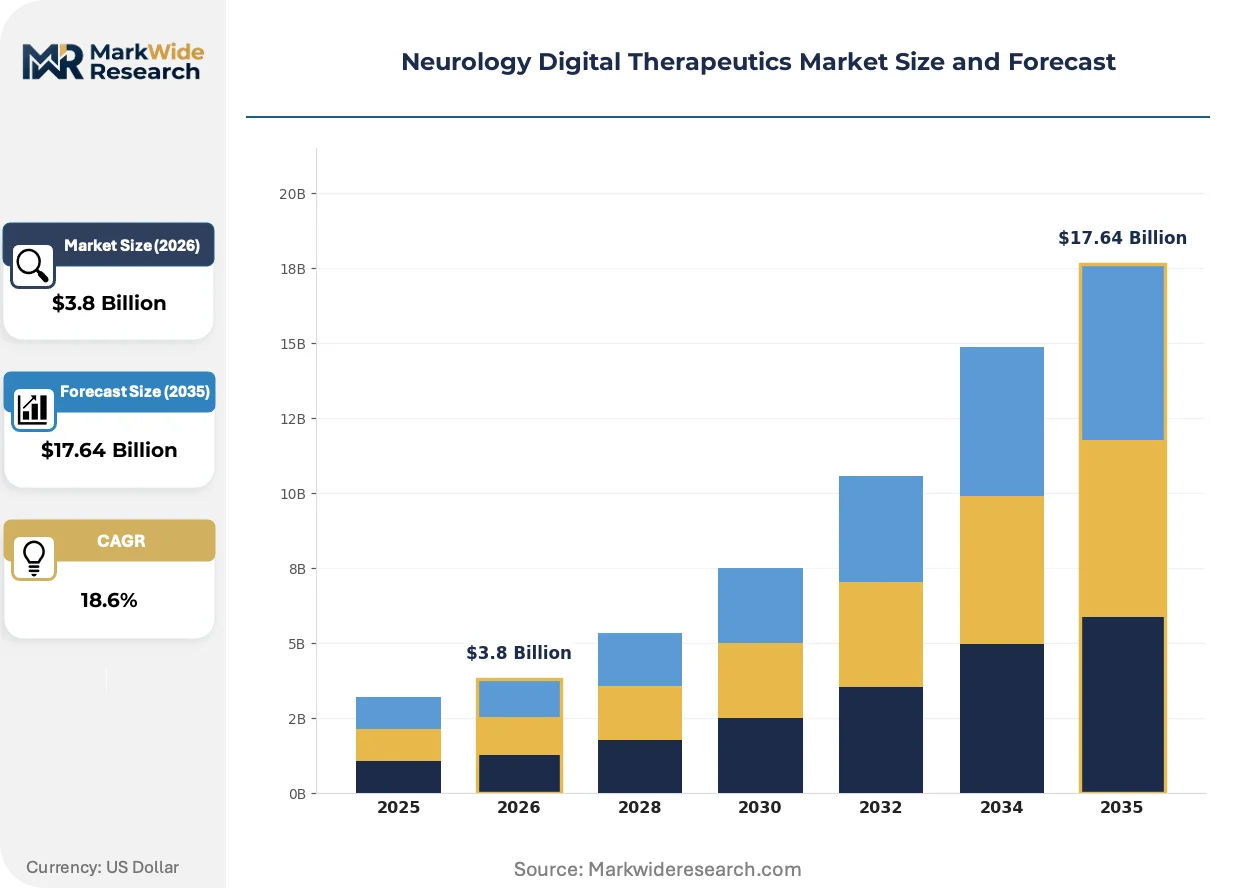
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Wearable Devices, Software Platforms, IoT Solutions Application: Depression, Anxiety, ADHD, Migraine End User: Patients, Healthcare Providers, Caregivers, Payers Delivery Model: Subscription-Based, Pay-Per-Use, One-Time Purchase, Free Trial |
| Companies Covered | Neofect Co Ltd, Omada Health Inc, Akili Inc, Blackrock Neurotech, nyra health, BigHealth, Mindmaze, Cognivive Inc, AppliedVR Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurology Digital Therapeutics Market Shifts & Advancements
Evidence-generation protocols are reshaping competitive positioning as platforms compete on randomized trial publication volume rather than feature differentiation alone. Three developments are restructuring market entry economics.
Adaptive cognitive training algorithms are migrating from research-grade installations to scalable cloud architectures. Academic medical centers in Germany and the United States piloted these systems for stroke rehabilitation. Hospital procurement committees now demand SaaS-deployable versions that eliminate on-premise infrastructure costs.
EU MDR Article 61 clinical evidence requirements are tightening post-market surveillance obligations for neurology software platforms. Manufacturers must submit periodic safety updates and real-world performance data to notified bodies. CE-marked ADHD and depression applications face the steepest compliance cost escalation.
Employer-sponsored health plans in the United States now require outcomes-linked contracting for behavioral neurology modules. Payers withhold portions of subscription fees pending validated symptom improvement metrics. This purchasing pattern concentrates demand among platforms with published efficacy data in peer-reviewed journals.
Neurology Digital Therapeutics Market Segmentation
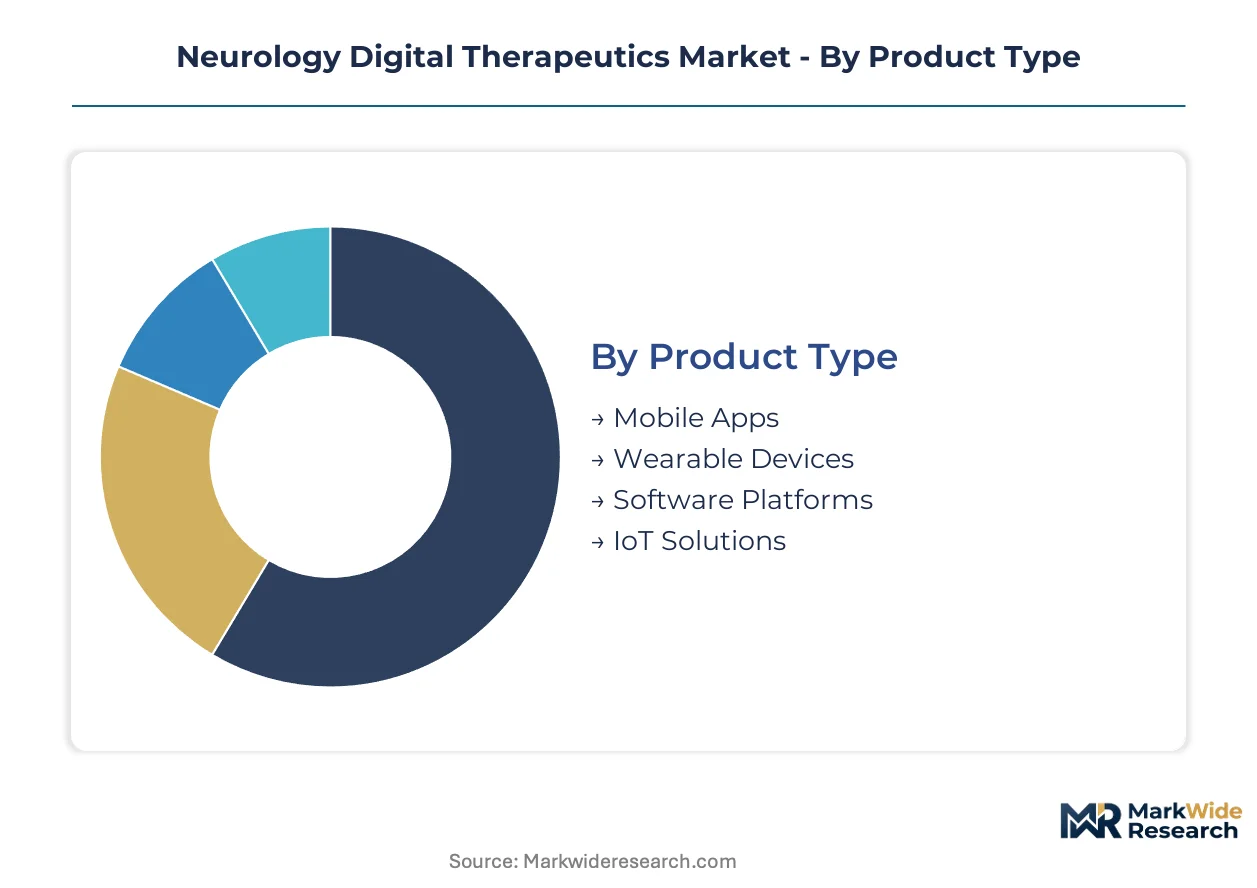
Neurology digital therapeutics segment along four intersecting dimensions that determine reimbursement eligibility, clinical validation requirements, and contracting economics. Product architecture and delivery model choices directly shape margin profiles and regulatory pathways.
Product Type:
Cost tier separates prescription-grade platforms from wellness applications, with software commanding premium economics over hardware-dependent systems.
- Software Platforms:Cloud-deployed therapeutic engines with adaptive algorithms and real-time biometric integration. Demand concentrates in United States hospital systems seeking SaaS-deployable stroke rehabilitation tools that eliminate on-premise infrastructure costs. Recurring subscription economics and near-zero marginal distribution costs sustain the deepest margin pools in the category.
- Mobile Apps:Smartphone-delivered cognitive behavioral protocols for depression and anxiety management. German statutory health insurers and Japanese prefectural authorities are expanding reimbursement coverage for these applications as payer pilot programs validate outcomes metrics. The segment is climbing the fastest share rankings among mild-to-moderate case management tools.
- Wearable Devices:Peripheral hardware capturing neural signals, movement patterns, or physiological biomarkers for feedback-driven therapy adjustment.
- IoT Solutions:Connected sensor networks deployed in clinical or home environments for continuous monitoring and intervention triggering.
Software Platforms hold installed capacity. Mobile Apps are rotating up the share rankings.
Application:
Clinical indication determines regulatory scrutiny intensity and evidence-generation burden for platform developers.
- ADHD:Pediatric and adult attention deficit protocols requiring FDA 510(k) or breakthrough device designation for prescription status. United States demand anchors on clinician-mediated reimbursement pathways that mandate physician oversight. The segment's steepest expansion trajectory reflects FDA's compressed review timelines reducing time-to-revenue by 12-18 months.
- Migraine:Neuromodulation and cognitive behavioral interventions for episodic and chronic headache conditions. Japan's PMDA fast-track pathway for neurological sequelae is accelerating authorization for platforms demonstrating functional outcome improvements. European CE marking under EU MDR imposes randomized controlled trial requirements that filter lower-validity entrants.
- Depression:Mood disorder applications leveraging adaptive cognitive training and behavioral activation protocols.
- Anxiety:Generalized and social anxiety interventions delivered through structured exposure and mindfulness-based modules.
Migraine commands regulatory attention. Depression is gaining share fastest.
End User:
Customer type dictates purchasing authority, contract structure, and outcomes validation requirements.
- Healthcare Providers:Hospital systems and physician practices prescribing software-based interventions as part of formal care pathways. United States academic medical centers and German university hospitals are piloting immersive neurotechnology platforms for stroke rehabilitation, creating institutional demand pull through procurement committees.
- Payers:Insurance carriers and employer-sponsored health plans integrating behavioral neurology modules into chronic disease management programs. Outcomes-linked contracting now withholds portions of subscription fees pending validated symptom improvement metrics, concentrating demand among platforms with peer-reviewed efficacy data.
- Patients:Individual end-users accessing direct-to-consumer channels, though this pathway is narrowing as reimbursement frameworks mature.
- Caregivers:Family members and professional care coordinators managing therapy adherence and monitoring patient-reported outcomes.
Healthcare Providers hold installed capacity. Payers are rotating up the share rankings.
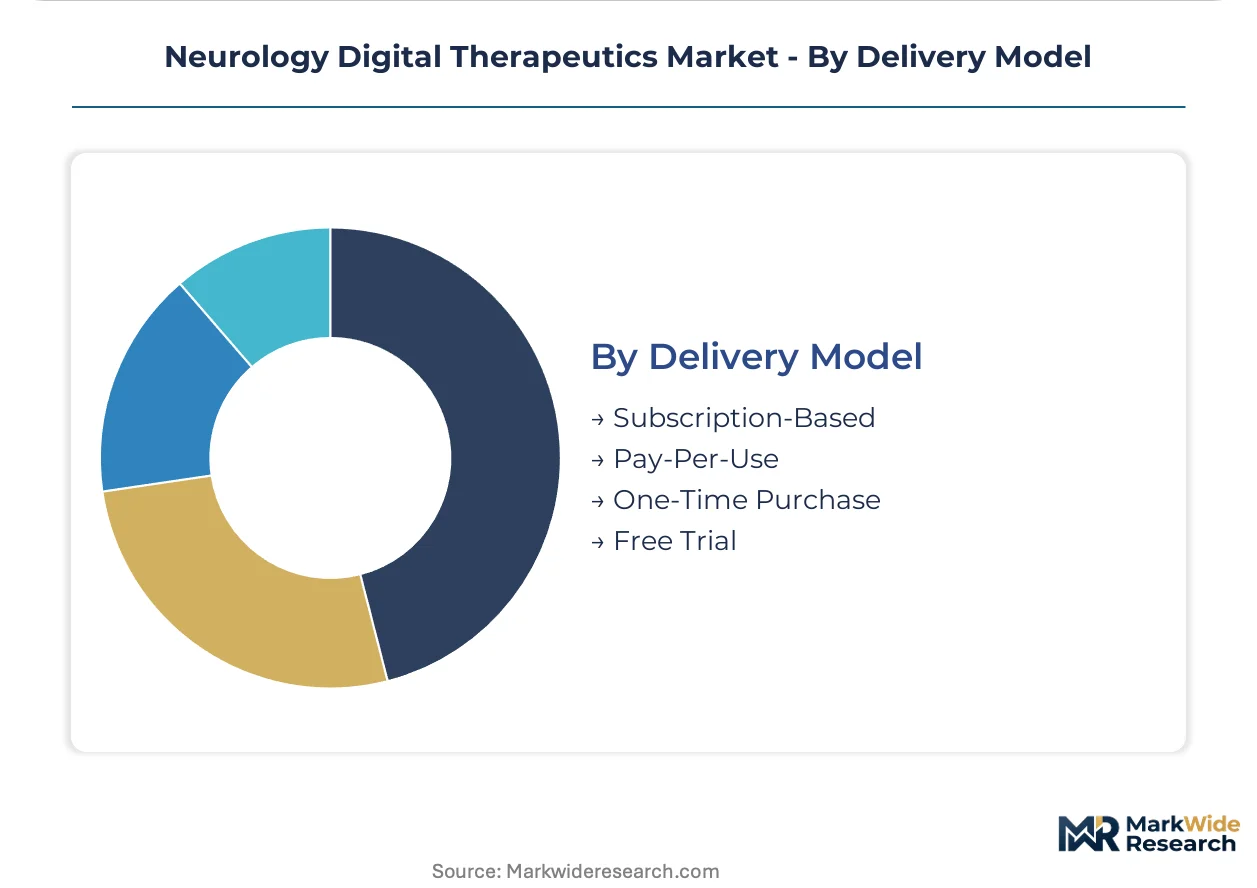
Delivery Model:
Revenue recognition and cash flow predictability vary sharply across contracting structures.
- Subscription-Based:Recurring revenue structures preferred by enterprise healthcare providers for multi-year contract values and predictable cash flows. United States hospital systems and German rehabilitation clinics favor this model for budget planning certainty.
- Pay-Per-Use:Utilization-linked pricing gaining traction in pilot programs seeking outcomes validation before formulary inclusion. Japanese prefectural health authorities and United States employer plans are testing this structure for behavioral neurology module deployment.
- One-Time Purchase:Perpetual licensing for on-premise software installations, increasingly displaced by cloud architectures.
- Free Trial:Limited-duration access for clinical evaluation and patient onboarding, common in direct-to-patient channels.
Subscription-Based holds installed capacity. Pay-Per-Use is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device pathways and Japan's PMDA fast-track authorization are compressing time-to-market for neurology software platforms. Reimbursement frameworks in Germany and the United States are maturing fastest, concentrating demand pull in these markets. Developers prioritize regulatory jurisdictions where physician-mediated prescription pathways offer sustainable revenue models.
United States
Employer-sponsored health plans now mandate outcomes-linked contracting for behavioral neurology modules, withholding subscription fees pending validated symptom metrics. FDA breakthrough designations for ADHD and migraine platforms reduce review timelines by 12-18 months versus standard 510(k) routes. Academic medical centers in Boston and the San Francisco Bay Area pilot immersive neurotechnology for stroke rehabilitation, creating institutional procurement demand.
Germany
Statutory health insurers are expanding reimbursement coverage for mobile depression and anxiety applications following payer pilot program validations. EU MDR Article 61 imposes randomized controlled trial requirements that filter lower-validity entrants from CE marking pathways. University hospitals in Berlin and Munich lead adoption of cloud-deployed cognitive training systems for post-stroke care.
Japan
PMDA's accelerated authorization pathway for dementia and stroke sequelae platforms ties reimbursement directly to functional outcome improvements. Prefectural health authorities in Tokyo and Osaka are testing pay-per-use structures for behavioral neurology module deployment. METI funding programs support domestic development of adaptive algorithm platforms for age-related cognitive decline.
United Kingdom
NICE technology appraisals are establishing evidence thresholds for digital therapeutic inclusion in NHS formularies, favoring platforms with peer-reviewed efficacy data. MHRA Software as a Medical Device guidance aligns with FDA quality system requirements, easing dual-market authorization strategies. London's digital health cluster hosts multiple developers pursuing ADHD and migraine indications through clinician-mediated pathways.
Switzerland
Swissmedic's streamlined review for prescription-grade neurology software attracts developers seeking European market entry with reduced regulatory friction. Cantonal health systems in Zurich and Geneva contract for subscription-based cognitive rehabilitation platforms. The country's reimbursement framework distinguishes prescription-grade interventions from wellness applications, concentrating demand among validated platforms.
Neurology Digital Therapeutics Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: FDA-cleared prescription platforms, immersive neurotechnology systems, and payer-integrated behavioral health modules. Developers compete on regulatory authorization velocity, clinical evidence publication volume, and hospital system contracting relationships. Dominant competitive moves include pursuit of breakthrough device designations and outcomes-linked payer contracts that validate platform efficacy before formulary inclusion.
Within the prescription-platform tier, Akili Inc and Mindmaze exemplify contrasting positioning strategies. Akili anchors the pediatric ADHD segment through FDA-cleared interventions requiring physician oversight. Mindmaze occupies a position in stroke rehabilitation via immersive neurotechnology deployed through hospital procurement channels. Omada Health Inc represents the payer-integrated archetype, embedding behavioral neurology modules within chronic disease management contracts.
| Leading Market Players |
|---|
| Neofect Co Ltd |
| Omada Health Inc |
| Akili Inc |
| Blackrock Neurotech |
| nyra health |
| BigHealth |
| Mindmaze |
| Cognivive Inc |
| AppliedVR Inc |
| Others |
Supply & Pricing Matrix
Semiconductor fabrication capacity in Taiwan and South Korea feeds directly into wearable peripheral cost structures, concentrating margin capture among software platform vendors who decouple from hardware dependencies through cloud-native architectures.
Pricing Analysis
Volume-discount tiering structures separate enterprise healthcare providers securing multi-year SaaS contracts from pilot programs testing pay-per-use arrangements. Price differentiation rests on clinical validation grade—FDA breakthrough designation and EU MDR CE marking command premium positioning—while hardware-integrated platforms face margin compression from sensor supply chain concentration. Pricing pressure intensifies in wearable-dependent segments as MEMS component costs fluctuate. Hospital systems exhibit lowest price sensitivity due to budget planning certainty requirements; direct-to-consumer channels face highest sensitivity as reimbursement pathways mature.
Supply Chain Analysis
Upstream feedstock for neurology digital therapeutics draws from semiconductor foundries in Taiwan, South Korea, and the United States for neural signal processing chips, plus biomedical sensor manufacturers in Germany and Japan for movement-tracking peripherals. Cloud infrastructure dependencies center on hyperscaler compute capacity in Virginia, Frankfurt, and Tokyo data center clusters. Single-source vulnerability concentrates in FDA-designated contract manufacturing organizations for SaMD quality system compliance. Distribution runs through hospital procurement committees and payer formulary managers rather than traditional device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from wellness applications masquerading as clinical-grade platforms as payer coverage determinations harden around prescription-grade validation requirements.
For Market Incumbents: Harden regulatory moats through parallel FDA breakthrough designation and EU MDR CE marking pursuit, compressing entrant authorization timelines. Deepen hospital system integration via FHIR-compliant middleware investments that extend implementation timelines for challengers. Prioritize backward integration into adaptive algorithm development to reduce dependency on scarce computational neuroscience talent pools.
For New Entrants and Emerging Players: Build out presence in Japanese prefectural health authority pilot programs where PMDA fast-track pathways reward functional outcome validation over entrenched relationships. Target pay-per-use contracting structures in German statutory health insurer pilot programs as the most penetrable reimbursement entry point. Lead go-to-market with published randomized controlled trial data that satisfies EU MDR Article 61 evidence requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward platforms holding dual FDA-EU authorization with established hospital procurement relationships and recurring subscription revenue visibility. Long-term viability favors developers whose clinical evidence portfolios span multiple neurological indications, reducing single-asset risk. Watch for inflection in CMS national coverage determination signals for digital therapeutics as the indicator of institutional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compressed review timelines reduce time-to-revenue by 12-18 months versus standard 510(k) routes. |
| EU MDR CE Marking Pathway | Randomized controlled trial requirements filter lower-validity entrants, protecting validated platform margins. |
| Hospital System Partnership | Academic medical center pilots in Boston and Munich create institutional procurement demand pull. |
| Software Companion Development | Adaptive algorithm maturation enables personalized cognitive protocol adjustment and formulary inclusion. |
| Reimbursement Strategy | Outcomes-linked payer contracts withhold fees pending validated symptom improvement metrics. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs specialists, hospital procurement managers, payer formulary directors, and digital health platform engineers anchors the qualitative findings against secondary sources including FDA 510(k) and breakthrough device filings, EU MDR notified body documentation, PMDA authorization records, and hospital GPO contract databases. Bottom-up demand modeling triangulates against top-down market sizing through clinician prescription volume estimates and payer coverage expansion trajectories.
Calibration against historical authorization timelines and reimbursement adoption curves informs the projection framework across product type, application, end user, and delivery model segmentation dimensions. CAGRs derive from fitted growth curves adjusted for regulatory pathway velocity and payer coverage elasticity. Forecast inputs incorporate breakthrough designation approval rates, CE marking cycle times, and prefectural health authority pilot program expansion metrics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized technology platforms or pharmaceutical incumbents entering via acquisition would shift outcomes beyond modeled ranges. Cross-checking against CMS national coverage determination timelines and EU MDR notified body capacity constraints is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Status Epilepticus Treatment Market
Neurology
Global Vertigo Treatment Market
Neurology
China Neurology Devices Market
Neurology
Brazil Neurology Devices Market
Neurology
Moyamoya Disease Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Labyrinthitis Market
Neurology
Spinal Laminoplasty Market
Neurology
Global Neuromarketing Market
Neurology
Cluster Headache Syndrome Market
Neurology
Interventional Neurology Market
Neurology
Nerve Repair Market
Neurology
Narcolepsy Treatment Market
Neurology
Brain Ischemia Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
South Korea Neurology Devices Market