
 Occipital Nerve Block Treatment Market | 2026-2036
Occipital Nerve Block Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Occipital Nerve Block Treatment Market Analytics
The capital-intensity divergence between integrated device manufacturers and pure-play pharmaceutical suppliers is unwinding competitive stability in occipital nerve block provision. Medtronic leverages its neuromodulation infrastructure to bundle diagnostic and therapeutic workflows for headache specialists. Fresenius Kabi anchors hospital formulary contracts through multi-source anesthetic supply agreements. Abbott Laboratories differentiates via ultrasound-compatible needle portfolios that target ambulatory surgical centers.
Occipital nerve block treatment entails the percutaneous injection of local anesthetics, often combined with corticosteroids, into the greater or lesser occipital nerve territory under image guidance to interrupt pain signaling in cervicogenic headache and occipital neuralgia. The procedure typically employs 25-gauge needles with 2-5 mL injectate volumes, performed at the superior nuchal line with real-time visualization to avoid vascular puncture. Anesthetics command the largest product-type revenue pool due to recurring consumption, while ultrasound-guided technology captures the fastest expansion as point-of-care imaging becomes standard in pain clinics. Hospitals retain the dominant end-user position for complex cases, though specialty clinics are building dedicated headache intervention units that concentrate margin-rich repeat procedures.
FDA oversight of device biocompatibility and EPA regulations on pharmaceutical waste disposal shape product development and clinical site compliance requirements in the United States. The Centers for Medicare & Medicaid Services reimbursement determinations for Category III CPT codes directly influence provider adoption velocity for emerging guidance technologies. Stakeholders must monitor evolving prior-authorization criteria from commercial payers as they integrate ultrasound documentation requirements into coverage policies.
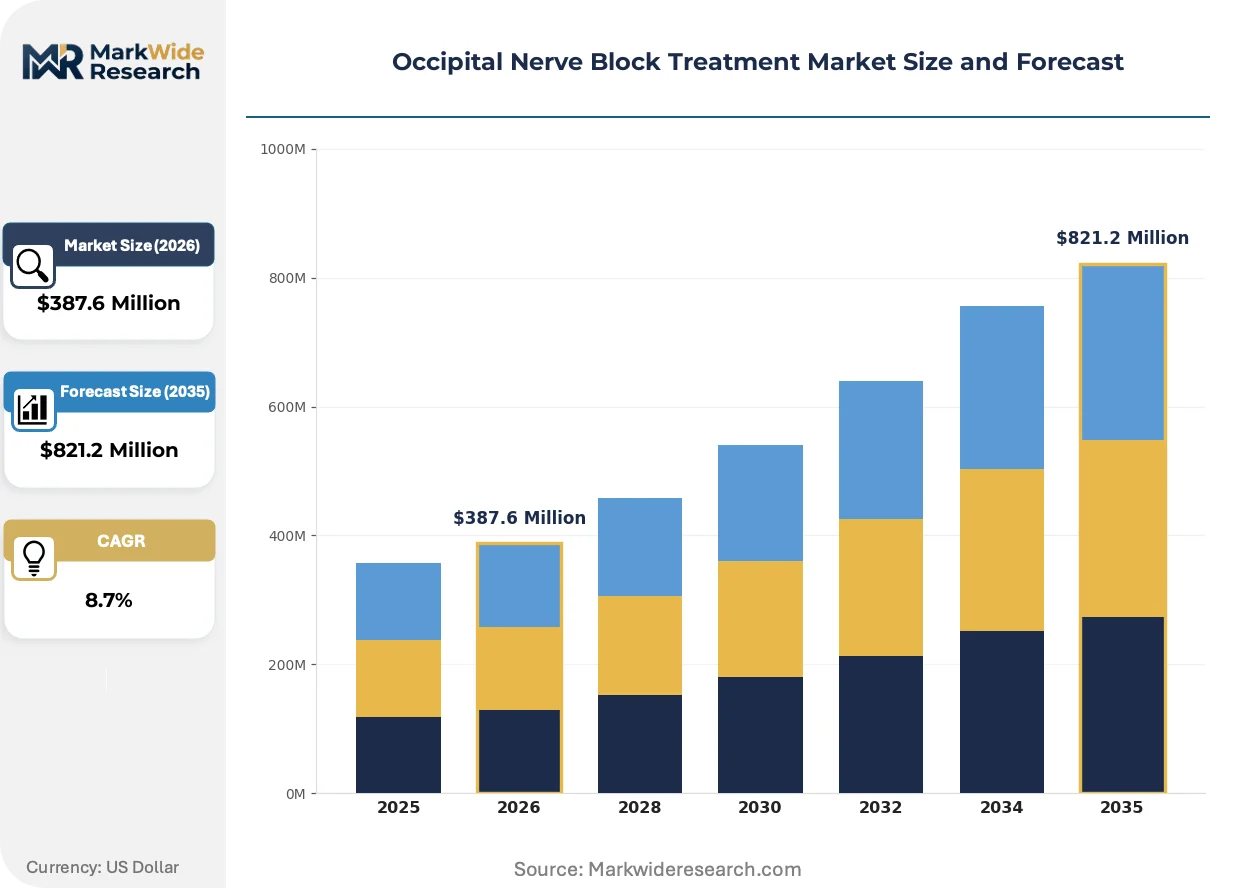
Market Dynamics
Ultrasound-guided injection protocols are consolidating procedural control in the occipital nerve block market, compressing the window for landmark-based techniques and redistributing value toward imaging-capable providers.
Growth Catalysts
- CMS Category III CPT code expansion:Reimbursement clarity for image-guided interventions accelerates capital deployment in United States pain clinics.
- Outpatient procedural migration:Ambulatory surgical centers capture complex headache cases previously routed to inpatient settings.
- Real-time visualization technology:Point-of-care ultrasound reduces vascular puncture risk and expands treatable patient populations.
Market Restraints
- Local anesthetic supply concentration:Hospital formulary dependence on multi-source injectable vendors creates procurement vulnerability during manufacturing shortages.
- EPA pharmaceutical waste mandates:Corticosteroid disposal compliance adds operational cost layers to high-volume injection practices.
- Non-invasive neuromodulation substitution:Transcutaneous electrical nerve stimulation devices compete for chronic migraine patients seeking drug-free alternatives.
Strategic Opportunities
- Underpenetrated European markets:Germany and France lack mature reimbursement pathways for interventional headache procedures, creating first-mover positioning potential.
- Telemedicine-integrated follow-up:Remote monitoring platforms enable post-procedure outcome tracking and repeat visit scheduling.
- Biologic-anesthetic combination therapies:CGRP antagonist co-formulation extends duration of occipital nerve block efficacy.
Industry Challenges
- Interventional pain specialist scarcity:Fellowship-trained physicians capable of ultrasound-guided cervical procedures remain concentrated in major metropolitan clusters.
- Equipment amortization pressure:Portable ultrasound systems require high procedural throughput to justify capital outlay in independent practice settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Occipital Nerve Block Treatment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needles, Catheters, Anesthetics, Imaging Devices End User: Hospitals, Pain Clinics, Rehabilitation Centers, Specialty Clinics Application: Chronic Pain Management, Surgical Procedures, Diagnostic Procedures, Migraine Treatment Technology: Ultrasound-Guided, Fluoroscopy, CT-Guided, Landmark-Based |
| Companies Covered | Johnson & Johnson, Medtronic, Astellas, Biogen, Eli Lilly, Fresenius Kabi, APP Pharmaceuticals, DPT Laboratories, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Occipital Nerve Block Treatment Market Evolving Landscape
Procedural standardization and imaging integration are compressing technique variability while elevating outcome documentation requirements across headache intervention practices.
Ultrasound-guided needle navigation is supplanting anatomical landmark palpation as the default approach for greater occipital nerve localization. Pain medicine fellows now train predominantly on sonoanatomy recognition rather than surface anatomy estimation. Academic medical centers are phasing out blind injection protocols entirely, collapsing the training pipeline for legacy techniques.
FDA biocompatibility testing requirements for single-use injection kits are tightening material selection standards for device manufacturers. The agency's updated guidance on 510(k) substantial equivalence for neural access devices extends review timelines for new entrants. Manufacturers are responding by pre-submission engagement with the Center for Devices and Radiological Health to clarify polymer coating acceptability.
Episode-based bundled payments are restructuring how United States providers contract with commercial payers for occipital neuralgia treatment sequences. Hospitals are consolidating anesthesia, imaging, and professional fees into single price points that shift risk to the delivering institution. This compression is most advanced in Florida and Texas, where large employer plans have piloted prospective payment models for chronic headache management.
Occipital Nerve Block Treatment Market Segmentation
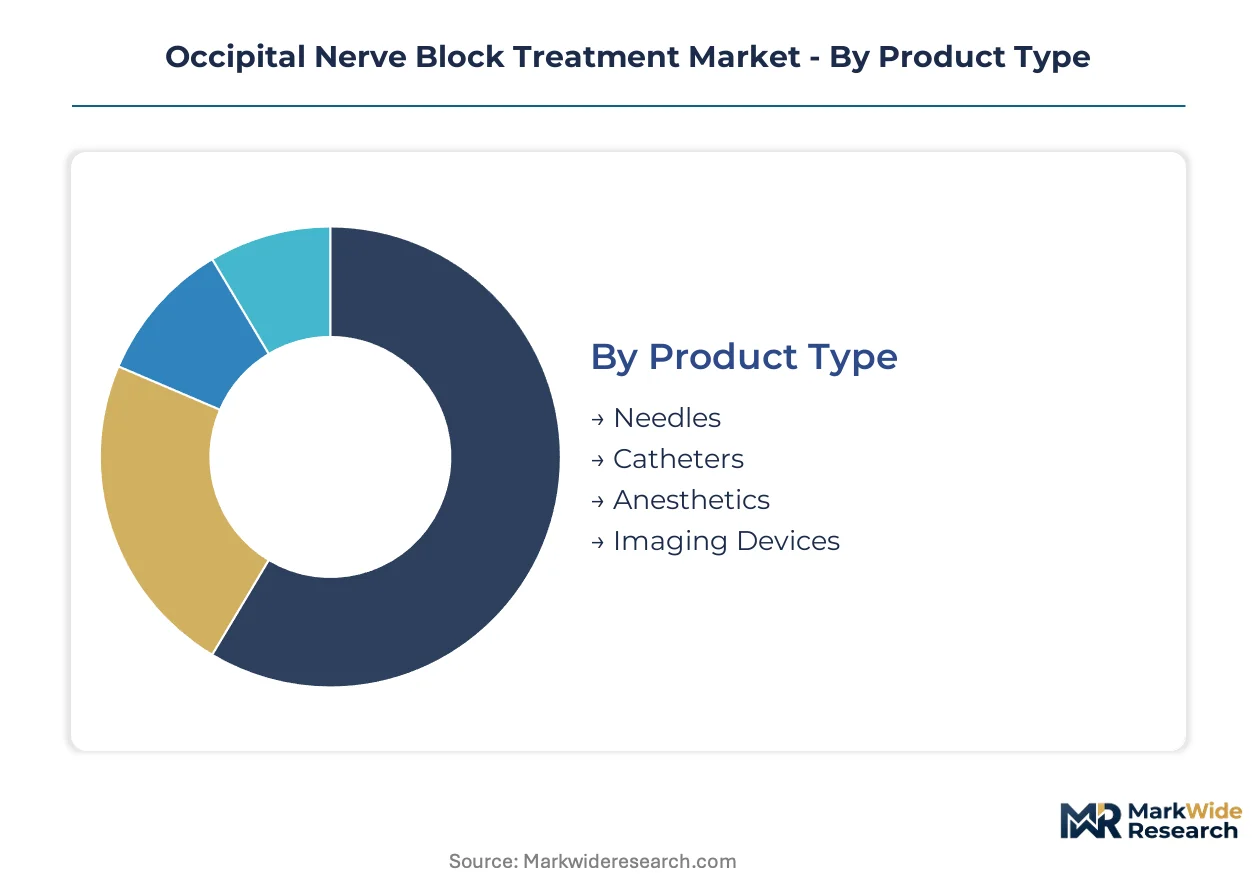
Segmentation in occipital nerve block treatment reveals distinct procurement and reimbursement pathways that channel capital toward imaging-capable providers while consumable volumes concentrate in high-throughput outpatient settings. Understanding these segment boundaries clarifies where margin pools accumulate versus where commoditization pressures intensify.
Product Type:
Channel mix varies sharply across product types, with capital equipment flowing through specialized distributors while consumables route through hospital formulary contracts and group purchasing organizations.
- Anesthetics:Local anesthetic formulations—typically bupivacaine or lidocaine combined with corticosteroids—constitute the recurring revenue backbone of occipital nerve block practice. Pain clinics in the United States absorb the highest volumes as CMS reimbursement clarity for Category III CPT codes drives procedural expansion.
- Imaging Devices:Portable ultrasound systems with high-frequency linear transducers enable real-time needle visualization and vascular avoidance. Ambulatory surgical centers in Florida and Texas represent the fastest-expanding customer base as bundled payment pilots concentrate capital deployment in these states.
- Needles:25-gauge, 1.5-inch needles with echogenic coatings dominate disposable procurement schedules.
- Catheters:Continuous infusion catheters serve refractory cases requiring prolonged anesthetic delivery.
Anesthetics dominate installed base volumes. Imaging devices represent where expansion concentrates most steeply.
End User:
Customer type segmentation maps directly to case complexity and reimbursement tier, with academic medical centers handling neuromodulation-eligible referrals while independent practices capture routine diagnostic blocks.
- Pain Clinics:Dedicated headache intervention units within pain medicine practices now perform the majority of elective occipital nerve blocks. These facilities in the United States leverage ultrasound guidance to differentiate from hospital-based competitors and capture facility fees under evolving payer contracts.
- Hospitals:Tertiary centers retain complex cases involving concurrent cervical spine pathology or failed prior interventions. Operating room overhead and anesthesia support requirements compress margins despite higher technical fees.
- Specialty Clinics:Neurology-focused practices with interventional capabilities build repeat-visit revenue through scheduled block series.
- Rehabilitation Centers:Physical medicine departments integrate blocks into multimodal cervicogenic headache protocols.
Hospitals retain the dominant installed base for complex cases. Pain clinics concentrate expansion activity.
Application:
Application segmentation tracks how diagnostic specificity and outcome measurement requirements vary across clinical indications, shaping documentation burdens and prior authorization success rates.
- Chronic Pain Management:Cervicogenic headache and occipital neuralgia represent the core therapeutic application, with blocks serving both diagnostic and therapeutic purposes. United States pain specialists increasingly require positive diagnostic response before proceeding to permanent neuromodulation implants.
- Migraine Treatment:Occipital nerve blocks for chronic migraine occupy a contested reimbursement territory as payers scrutinize evidence bases against CGRP antagonist alternatives. Academic headache centers in major metropolitan clusters drive protocol development.
- Diagnostic Procedures:Prognostic blocks predict response to subsequent radiofrequency ablation or peripheral nerve stimulation.
- Surgical Procedures:Perioperative adjunctive use in posterior cervical surgery remains limited to specific institutional protocols.
Chronic pain management anchors installed base utilization. Migraine treatment represents the application gaining share fastest.
Technology:
Technology segmentation captures a fundamental modality transition, with capital investment and training pipelines increasingly favoring image-guided approaches over anatomical estimation.
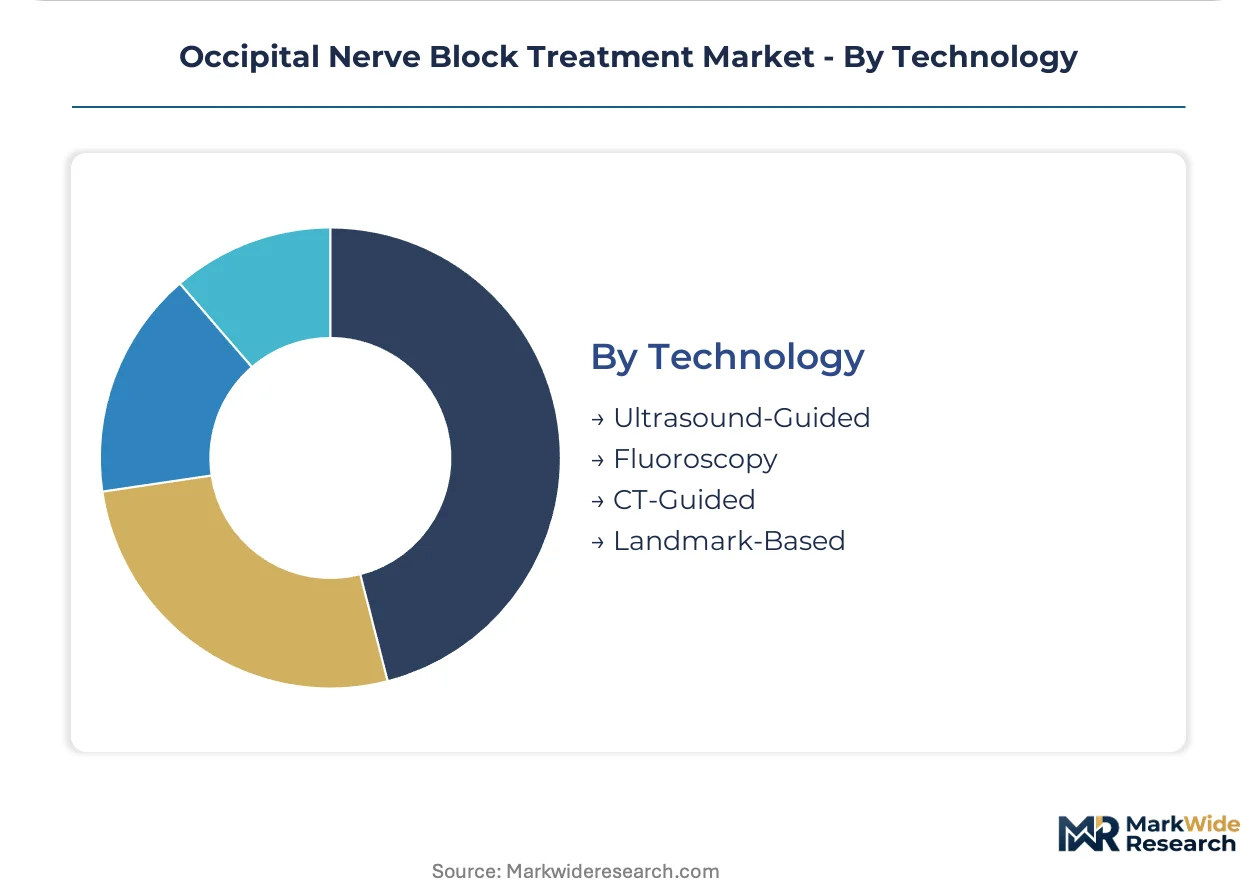
- Ultrasound-Guided:Real-time sonoanatomy visualization enables precise needle placement relative to the greater occipital nerve and occipital artery. Pain medicine fellowship programs in the United States now train exclusively on ultrasound protocols, collapsing the pipeline for legacy techniques.
- Landmark-Based:Palpation-guided injection at the superior nuchal line persists in resource-constrained settings and urgent care contexts where imaging capital is unavailable. Reimbursement compression and liability exposure accelerate its displacement.
- Fluoroscopy:C-arm guidance serves cervical medial branch blocks performed concurrently with occipital procedures.
- CT-Guided:Computed tomography navigation remains reserved for atypical anatomy or failed prior attempts.
Landmark-based techniques retain residual installed base in undercapitalized settings. Ultrasound-guided approaches concentrate all meaningful expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows concentrate in the United States while European markets rely on cross-border pharmaceutical distribution networks. The United States absorbs the majority of ultrasound-guided device imports from German and Japanese manufacturers. Export-oriented suppliers in Switzerland and Ireland ship anesthetic formulations to pain clinic networks across North America and Asia-Pacific.
United States
Reimbursement clarity through CMS Category III CPT codes drives capital deployment into ambulatory surgical centers. FDA biocompatibility requirements for single-use injection kits shape device manufacturer compliance strategies. Pain medicine fellowship programs in academic medical centers now train exclusively on ultrasound-guided protocols.
Germany
Hospital formulary contracts with multi-source anesthetic vendors stabilize procurement for interventional headache procedures. The national pharmaceutical regulator enforces strict waste disposal mandates for corticosteroid-containing injectates. Medical device clusters in Baden-Württemberg produce echogenic needle coatings for export to North American pain clinics.
Japan
Aging demographics expand the addressable population for cervicogenic headache interventions in tertiary care settings. PMDA review timelines for neural access devices extend market entry cycles for foreign manufacturers. Tokyo-based academic headache centers pilot ultrasound-guided training curricula for regional pain specialists.
United Kingdom
NHS England commissioning frameworks for chronic pain services channel procedure volumes toward specialist centers. The national pharmaceutical regulator maintains pharmacovigilance requirements for local anesthetic adverse event reporting. London headache clinics concentrate interventional capacity while regional trusts develop telemedicine-integrated follow-up protocols.
Australia
Private health insurance coverage for image-guided nerve blocks outpaces public reimbursement expansion. TGA medical device regulations align with ISO standards for neural access kit sterilization validation. Sydney and Melbourne pain medicine practices import portable ultrasound systems from United States and South Korean manufacturers.
Occipital Nerve Block Treatment Market Competitive Landscape
Concentration sits with diversified medtech conglomerates that leverage neuromodulation infrastructure to bundle diagnostic and therapeutic workflows. The market structure fragments across pharmaceutical suppliers, device manufacturers, and imaging technology providers. Strategic archetypes include integrated device manufacturers, pure-play anesthetic suppliers, and ultrasound-compatible needle specialists. Dominant competitive moves encompass formulary contract consolidation and point-of-care imaging capability acquisition.
Among diversified healthcare conglomerates, Johnson & Johnson and Medtronic occupy positions that exemplify vertical integration across the headache intervention continuum. Abbott Laboratories represents the ultrasound-compatible device archetype, while Fresenius Kabi anchors the pharmaceutical supply tier through hospital formulary relationships. These three entities collectively illustrate how capital intensity divergence between device and drug paradigms reshapes competitive stability.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Astellas |
| Biogen |
| Eli Lilly |
| Fresenius Kabi |
| APP Pharmaceuticals |
| DPT Laboratories |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
FDA biocompatibility testing requirements for single-use injection kits gate both supplier qualification and price differentiation simultaneously, forcing device manufacturers into pre-submission engagement with the Center for Devices and Radiological Health before polymer coating selections can proceed. This regulatory overlay concentrates pricing power among incumbents with established 510(k) clearance histories while elevating compliance costs for new entrants.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with echogenic needle coatings and ultrasound-compatible portfolios commanding brand premiums. Price differentiation rests on FDA clearance tier and volume scale, with hospital formulary contracts compressing margins for multi-source anesthetic suppliers. Cost compression in the standard tier is intensifying because bundled payment pilots in Florida and Texas shift risk to delivering institutions. Ambulatory surgical centers exhibit highest price sensitivity due to capital amortization pressure, while academic medical centers prioritize outcome documentation over unit cost.
Supply Chain Analysis
Just-in-time inventory preferences dominate consumable procurement for local anesthetics, though strategic stockpiling persists for imaging devices given extended PMDA and FDA review timelines. Manufacturing concentrates in the United States, Germany, and Japan, with Swiss and Irish facilities feeding anesthetic formulations to North American networks. Raw material dependencies center on medical-grade polymers, echogenic coating substrates, and corticosteroid active pharmaceutical ingredients. Single-source vulnerability runs through concentrated bupivacaine supply agreements. Distribution runs through specialized device distributors for capital equipment and group purchasing organizations for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as CMS Category III CPT code expansion drives reimbursement clarity and capital deployment velocity in United States pain clinics.
For Market Incumbents: Fortify formulary contract positions through multi-source anesthetic supply agreements that lock hospital procurement schedules. Deepen backward integration into echogenic needle coating production to capture margin pools migrating from pure-play pharmaceutical suppliers. Non-invasive neuromodulation substitution from transcutaneous electrical nerve stimulation devices threatens chronic migraine revenue streams.
For New Entrants and Emerging Players: Lead with ultrasound-compatible needle portfolios targeting ambulatory surgical centers in underpenetrated European markets where Germany and France lack mature reimbursement pathways. Germany and France represent the most penetrable geographies given absent interventional headache procedure coverage frameworks. A go-to-market angle centered on telemedicine-integrated follow-up platforms enables remote outcome tracking and repeat visit scheduling.
For Investors and Strategic Acquirers: CMS reimbursement determinations for emerging guidance technologies reshape the acquisition landscape by accelerating provider adoption velocity for ultrasound-capable platforms. The five-to-ten year viability window favors targets with established neuromodulation infrastructure capable of bundling diagnostic and therapeutic workflows. Acquisition target archetype: diversified medtech conglomerates with pain medicine fellowship training program relationships. The signal to watch is commercial payer prior-authorization criteria evolution as ultrasound documentation requirements integrate into coverage policies.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasound Guidance Technology Acquisition | Portable system portfolios capture ambulatory surgical center expansion in bundled payment pilot states. |
| FDA 510(k) Pre-Submission Engagement | Early Center for Devices and Radiological Health consultation accelerates polymer coating clearance timelines. |
| Hospital Formulary Contract Consolidation | Multi-source anesthetic agreements lock recurring revenue against manufacturing shortage vulnerability. |
| Telemedicine-Integrated Follow-Up Platform | Remote monitoring enables post-procedure outcome tracking and repeat visit scheduling for pain clinics. |
| Pain Medicine Fellowship Training Partnership | Exclusive ultrasound protocol curricula collapse the training pipeline for legacy landmark-based techniques. |
Research Methodology
A spread of perspectives from pain medicine specialists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers converged on the working assumptions driving procedural volume and technology adoption trajectories. Primary interview insights combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and pain clinic procedural registries. Bottom-up facility-level capacity modeling and top-down epidemiological prevalence estimates triangulated on addressable market boundaries.
Segmentation dimensions modeled span product type, end user, application, and technology modality across the projection horizon. Anesthetics, imaging devices, needles, and catheters formed the product architecture, while pain clinics, hospitals, specialty clinics, and rehabilitation centers defined the customer landscape. CAGRs derived from procedural volume expansion rates weighted by reimbursement tier evolution and technology substitution curves. Forecast inputs incorporated ultrasound guidance adoption velocity and interventional pain specialist fellowship training pipeline constraints.
The analysis sits within stated boundaries; outcomes outside sustained CMS Category III CPT code reimbursement clarity and EPA pharmaceutical waste compliance stability would require recalibration. Forecasts reflect documented assumptions regarding procedural migration to outpatient settings and imaging technology capital deployment patterns. Revision becomes warranted when commercial payer prior-authorization criteria stringency crosses thresholds that compress provider adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Moyamoya Disease Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Neurology Software Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Cervical Dystonia Treatment Market
Neurology
US Optic Neuritis Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Tourette Syndrome Market
Neurology
Netherlands Neurology Devices Market
Neurology
Cluster Headache Syndrome Market
Neurology
Acute Repetitive Seizures Market
Neurology
Pediatric Neurology Device Market
Neurology
White Matter Injury Treatment Market