
 Pediatric Neurology Device Market | 2026-2036
Pediatric Neurology Device Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Neurology Device Market Analysis
Class II and Class III device certification tiers is bifurcating the competitive landscape into specialists and generalists. Medtronic Plc leverages its deep neurostimulation portfolio to dominate vagus nerve stimulation for pediatric epilepsy. Abbott Laboratories anchors its position through specialized pediatric catheter-based neuromodulation systems. Boston Scientific Corporation competes on R&D intensity with focused investments in responsive neurostimulation platforms.
Pediatric neurology devices comprise instrumented systems engineered for diagnostic evaluation and therapeutic intervention in developing nervous systems, typically operating at lower power thresholds and reduced physical dimensions calibrated for neonatal through adolescent anatomies. EEG devices lead procedural volume in seizure management, while AI-powered systems represent the fastest-expanding technology tier as cloud-based platforms mature into regulatory-validated clinical workflows. Neurostimulation devices command premium positioning due to implant longevity requirements and specialized surgical training ecosystems.
FDA's Humanitarian Device Exemption and EMA's Paediatric Investigation Plan shape trial design and market access timelines for novel pediatric neurology interventions, while ISO 14155 governs clinical investigation standards across jurisdictions. Stakeholders must monitor evolving reimbursement pathways for wearable seizure detection systems and anticipate how FDA breakthrough device designation criteria will reshape competitive entry dynamics.
Market Dynamics
AI-powered EEG interpretation is compressing diagnostic timelines from days to hours, forcing incumbent device manufacturers to restructure R&D roadmaps around cloud-native architectures rather than standalone hardware.
Growth Catalysts
- FDA Breakthrough Device Designation:The streamlined pathway accelerates pediatric neurostimulation trials by reducing premarket review cycles for devices addressing unmet seizure disorders.
- German epilepsy surgery referral networks:Concentrated clusters of pediatric neurosurgical expertise in Heidelberg and Berlin generate sustained demand for intraoperative neuromonitoring systems.
- Neonatal ICU expansion:Level IV NICU construction across the United States drives procurement of amplitude-integrated EEG systems for hypoxic-ischemic encephalopathy surveillance.
Market Restraints
- Pediatric-specific component sourcing:Biocompatible materials for chronic neural implants face supply concentration among three European polymer suppliers.
- EMA Paediatric Investigation Plan compliance costs:Mandatory pediatric study requirements for adult-indicated neuromodulation devices extend development timelines by 18-24 months.
- Neurosurgical workforce limitations:Fellowship-trained pediatric epilepsy surgeons number fewer than 200 across all OECD markets, constraining implantable device adoption velocity.
Strategic Opportunities
- Japan's aging demographic inversion:Shrinking adult patient pools redirect manufacturer focus toward pediatric indications as sustainable volume anchors.
- Remote seizure monitoring platforms:Cloud-connected wearable EEG systems enable home-based diagnostic workflows previously confined to epilepsy monitoring units.
- ISO 14155 harmonization with FDA 21 CFR Part 812:Converging clinical investigation standards reduce redundant trial design costs for multinational pediatric device sponsors.
Industry Challenges
- Pediatric neurophysiology technician shortages:Specialized EEG technologists require 12-18 month certification programs that training institutions struggle to scale.
- Legacy EMR integration complexity:Proprietary data formats from established EEG manufacturers resist interoperability with hospital-wide electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Neurology Device Market |
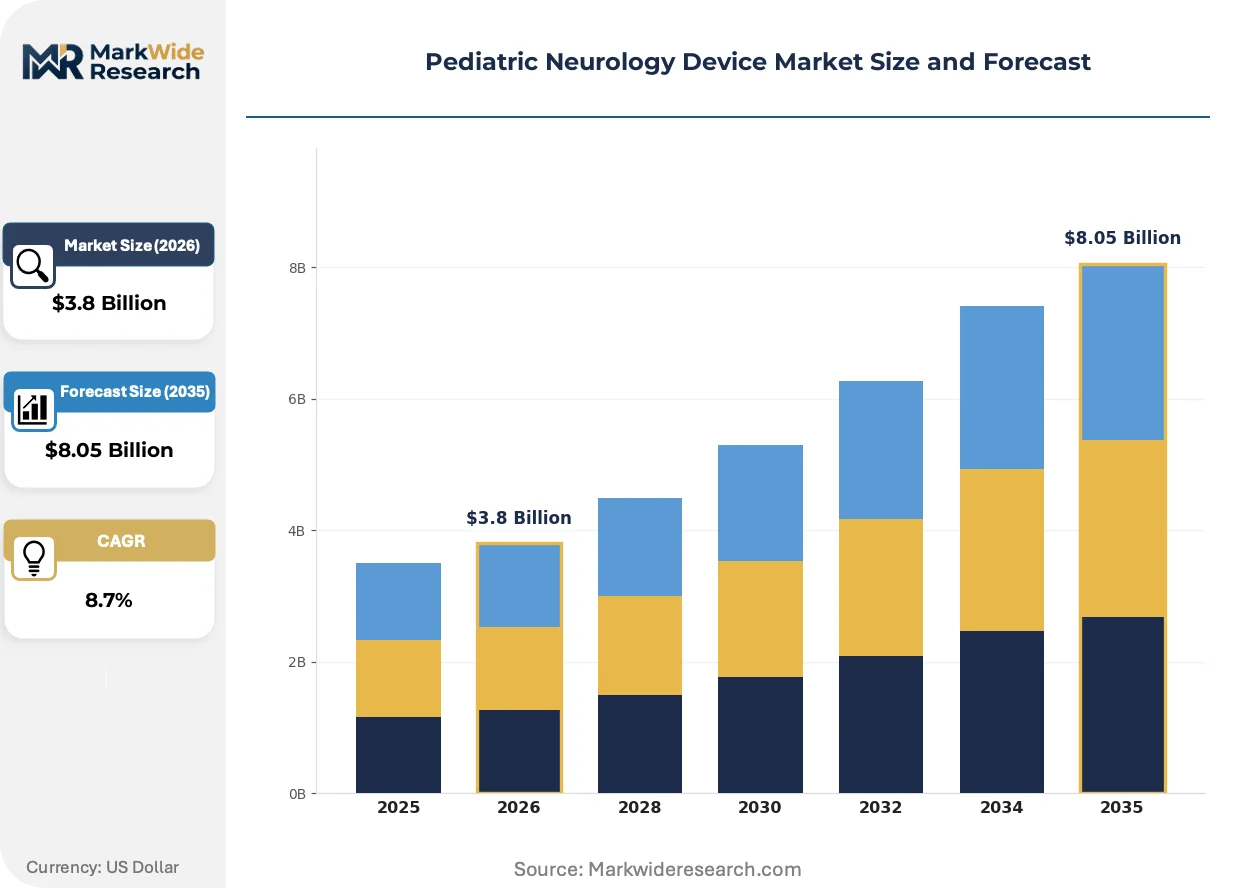
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: EEG Devices, Neurostimulation Devices, Monitoring Systems, Imaging Devices Application: Seizure Management, Cognitive Rehabilitation, Neurodiagnostics, Pain Management End User: Pediatric Hospitals, Outpatient Clinics, Research Institutions, Home Care Technology: Wearable Devices, Intrusive Sensors, Cloud-Based Platforms, AI-Powered Systems |
| Companies Covered | Medtronic Plc, Abbott Laboratories, Boston Scientific Corporation, Stryker Corporation, Natus Medical Incorporated, Integra LifeSciences Holdings Corp., LivaNova PLC, Johnson & Johnson Co, NeuroPace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Neurology Device Market Emerging Trajectories
Computational biomarker extraction is displacing visual EEG interpretation as the primary diagnostic modality, while regulatory frameworks scramble to validate algorithmic decision-support tools for clinical deployment.
Subdermal seizure detection electrodes are miniaturizing from 4mm to sub-2mm footprints while maintaining signal fidelity. Pediatric epilepsy centers in the United States are piloting these reduced-dimension implants for infants under 12 months. This dimensional compression is miniaturizing surgical access requirements and expanding candidacy for responsive neurostimulation to patient cohorts previously excluded by anatomical constraints.
EMA's Medical Device Regulation (MDR) Article 61 is tightening clinical evidence requirements for legacy pediatric neurology devices grandfathered under prior directives. Manufacturers must now generate post-market clinical follow-up data for devices with decades of unmonitored use. Implantable neurostimulation systems face the steepest compliance burden, with notified bodies demanding prospective pediatric registries for CE mark renewal.
Epilepsy monitoring unit directors are consolidating vendor relationships around single-platform ecosystems that bundle hardware, cloud analytics, and long-term service contracts. Independent device distributors in Germany and Japan are losing share to manufacturer-direct sales organizations with embedded clinical specialists. This channel restructuring is most pronounced in academic medical centers with consolidated procurement authority over neurodiagnostic capital equipment.
Pediatric Neurology Device Market Segmentation
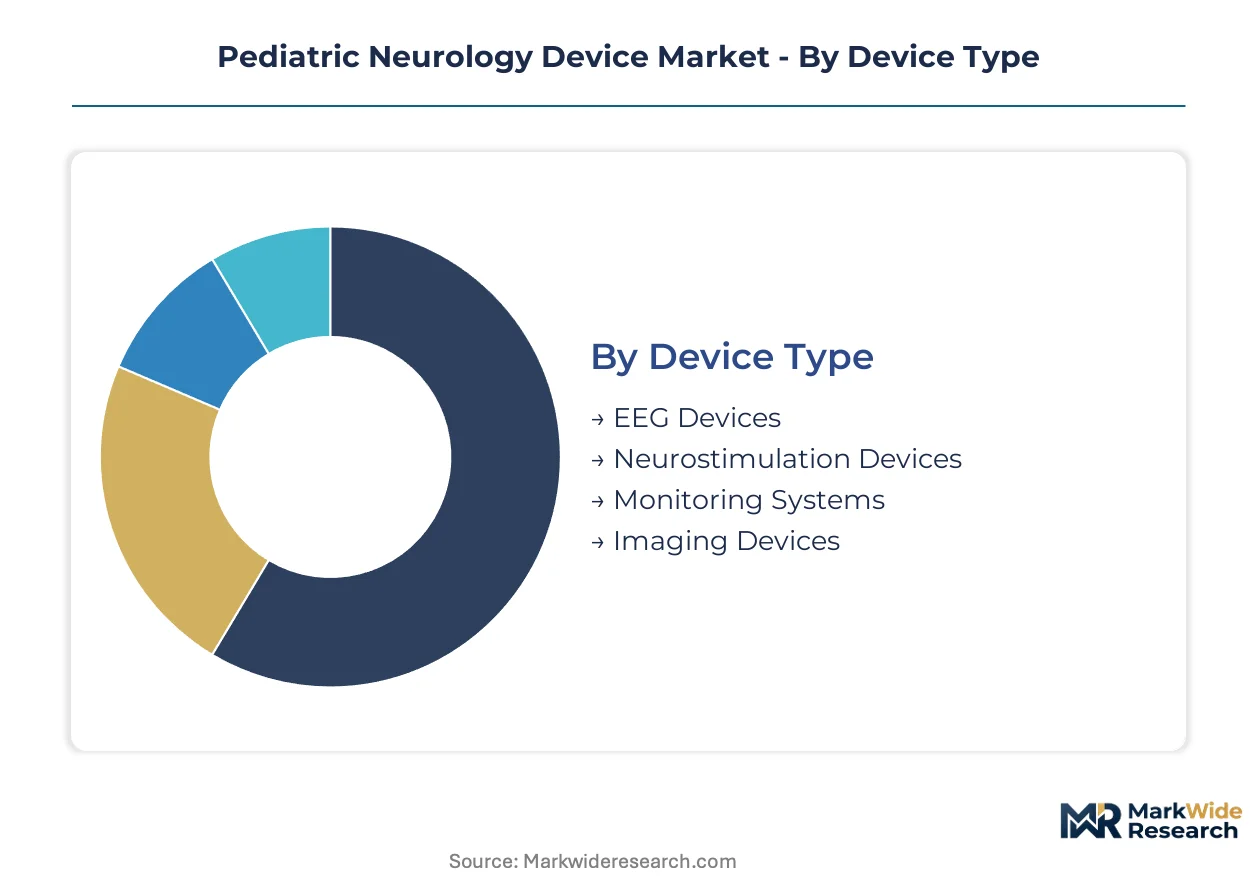
Pediatric neurology devices serve anatomically constrained patient populations with power-calibrated specifications. Segmentation reveals how manufacturers balance miniaturization requirements against diagnostic fidelity across neonatal through adolescent cohorts.
Device Type:
EEG devices dominate domestic procurement in the United States and Germany, while neurostimulation systems drive export revenue from Swiss and Irish manufacturing hubs.
- EEG Devices:Amplitude-integrated systems for NICU hypoxic-ischemic encephalopathy surveillance operate at microvolt sensitivity thresholds. Demand clusters in Level IV neonatal intensive care units across Texas, California, and Ohio where Medicaid reimbursement covers prolonged monitoring.
- Neurostimulation Devices:Implantable pulse generators for vagus nerve and responsive neurostimulation require biocompatible polymer encapsulation rated for 10-year longevity. German epilepsy surgery centers in Heidelberg and Berlin generate concentrated demand for intraoperative neuromonitoring-compatible systems.
- Monitoring Systems:Continuous bedside devices track intracranial pressure and cerebral oxygenation in post-surgical pediatric patients.
- Imaging Devices:Pediatric-dedicated MRI coils and SPECT systems accommodate smaller head circumferences with customized receiver arrays.
EEG devices hold the largest share; momentum sits with neurostimulation devices.
Application:
Cost tier stratification separates capital-intensive surgical interventions from diagnostic workflows with faster depreciation schedules.
- Seizure Management:Accounts for the majority of device utilization across epilepsy monitoring units and surgical implantation programs.
- Cognitive Rehabilitation:Transcranial direct current stimulation and neurofeedback systems target attention deficit and learning disorder populations.
- Neurodiagnostics:High-resolution EEG and magnetoencephalography platforms command premium pricing for pre-surgical epilepsy localization. Academic medical centers in Japan and the United States drive procurement of MEG systems with pediatric dewar configurations.
- Pain Management:Peripheral nerve stimulation for complex regional pain syndrome in adolescents requires smaller lead gauges and lower amplitude programming.
Seizure management commands dominant revenue; cognitive rehabilitation is climbing the fastest.
End User:
Customer type determines purchasing authority structure and service contract complexity.
- Pediatric Hospitals:Consolidated procurement departments at freestanding children's hospitals negotiate multi-year enterprise agreements. Texas Children's Hospital and Cincinnati Children's anchor demand for integrated neurodiagnostic suites with embedded AI interpretation.
- Outpatient Clinics:Independent pediatric neurology practices favor portable EEG systems with subscription-based cloud analytics over capital purchases.
- Research Institutions:NIH-funded epilepsy centers acquire experimental devices through investigator-initiated protocols outside standard reimbursement.
- Home Care:Wearable seizure detection wearables with caregiver alert functionality expand addressable population beyond hospital-monitored patients.
Pediatric hospitals hold the largest share; home care shows steepest expansion trajectory.
Technology:
Supply concentration in semiconductor fabrication shapes availability of miniaturized components for pediatric form factors.
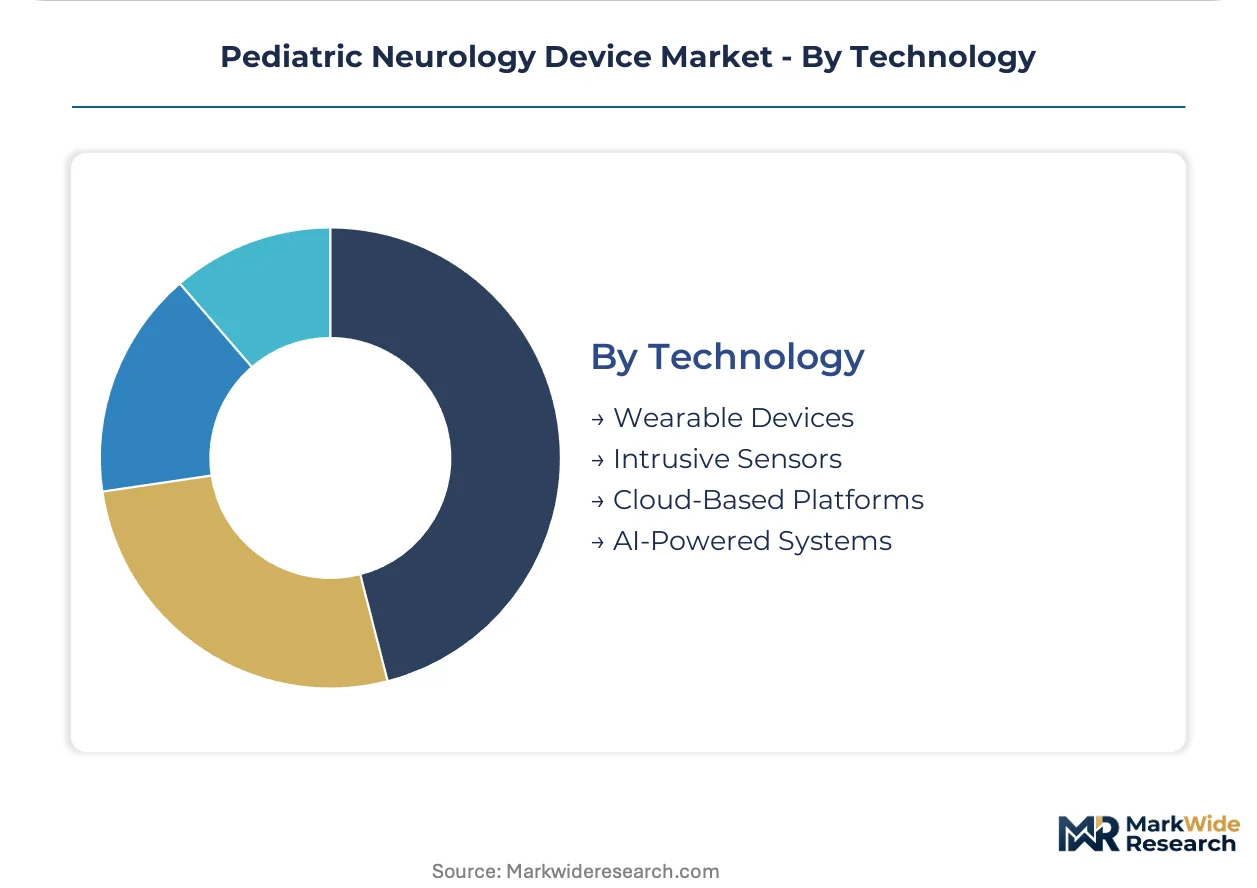
- Wearable Devices:Dry electrode EEG headsets and subdermal seizure monitors eliminate conductive gel requirements for ambulatory pediatric use.
- Intrusive Sensors:Depth electrodes and subdural grids for intracranial EEG require neurosurgical implantation with stereotactic guidance.
- Cloud-Based Platforms:HIPAA-compliant data architectures enable remote review by epileptologists at centralized reading centers. FDA 510(k) clearance for cloud-native EEG interpretation is accelerating competitive entry from software-native vendors.
- AI-Powered Systems:Convolutional neural networks trained on pediatric seizure pattern libraries reduce inter-rater variability in EEG interpretation. EMA's Medical Device Regulation Article 61 is tightening clinical evidence requirements for algorithmic decision-support tools.
Cloud-based platforms hold the largest share; AI-powered systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export revenue from Swiss and Irish manufacturing hubs supplies German and Japanese epilepsy centers, while the United States runs a substantial trade deficit in implantable neurostimulation systems. Import dependence concentrates in biocompatible polymer encapsulation rated for pediatric longevity requirements.
United States
Level IV NICU construction across Texas, California, and Ohio drives procurement of amplitude-integrated EEG systems for hypoxic-ischemic encephalopathy surveillance. FDA's Breakthrough Device Designation streamlines premarket review cycles for pediatric neurostimulation addressing unmet seizure disorders. Texas Children's Hospital and Cincinnati Children's anchor demand for integrated neurodiagnostic suites with embedded AI interpretation.
Germany
Concentrated clusters of pediatric neurosurgical expertise in Heidelberg and Berlin generate sustained demand for intraoperative neuromonitoring systems. EMA's Paediatric Investigation Plan mandates pediatric study requirements that extend adult-indicated neuromodulation development timelines. Freiburg and Tübingen university hospitals pilot sub-2mm subdermal seizure detection electrodes for infants under 12 months.
Japan
Shrinking adult patient pools redirect manufacturer focus toward pediatric indications as sustainable volume anchors. PMDA's streamlined review pathways for orphan neurological devices accelerate market access for novel interventions. Tokyo and Osaka academic medical centers drive procurement of MEG systems with pediatric dewar configurations.
Switzerland
Specialized polymer suppliers in Basel and Zurich dominate biocompatible material sourcing for chronic neural implants facing supply concentration. Swissmedic's alignment with EMA MDR Article 61 tightens clinical evidence requirements for legacy device CE mark renewal. Lausanne and Geneva research institutions acquire experimental devices through investigator-initiated protocols outside standard reimbursement.
Pediatric Neurology Device Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and R&D intensity. Class II and Class III device certification bifurcates the competitive landscape into specialists and generalists. Three archetypes dominate: diversified medtech conglomerates with deep neurostimulation portfolios, specialized neuromodulation pure-plays, and software-native vendors leveraging cloud-native architectures. Competitive moves center on M&A for pediatric-specific component sourcing and strategic partnerships for AI-powered EEG interpretation platforms.
Within the diversified medtech tier, Medtronic Plc and Abbott Laboratories occupy positions shaped by neurostimulation depth and catheter-based specialization respectively. Boston Scientific Corporation exemplifies R&D-intensive competition focused on responsive neurostimulation platforms. These three entities represent distinct strategic postures: scale-driven portfolio breadth, targeted pediatric form factor engineering, and algorithm-centric diagnostic acceleration.
| Leading Market Players |
|---|
| Medtronic Plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Stryker Corporation |
| Natus Medical Incorporated |
| Integra LifeSciences Holdings Corp. |
| LivaNova PLC |
| Johnson & Johnson Co |
| NeuroPace |
| Others |
Supply Flow & Price Mechanics
Scale economies in biocompatible polymer encapsulation for chronic neural implants concentrate manufacturing capacity among three European suppliers, creating dual price floors for Class III neurostimulation devices while compressing margins for manufacturers lacking captive material sourcing or long-term offtake agreements with Basel and Zurich specialty chemical producers.
Pricing Analysis
Pediatric hospital procurement committees anchor pricing negotiations through multi-year enterprise agreements that bundle hardware, cloud analytics, and service contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA Breakthrough-designated neurostimulation systems from CE-marked equivalents and unbundled diagnostic hardware. Pricing pressure stems from Medicaid reimbursement compression for amplitude-integrated EEG systems in Level IV NICU settings. Outpatient clinics and independent neurology practices exhibit highest price sensitivity, favoring subscription-based SaaS models over capital purchases.
Supply Chain Analysis
Extended lead times for pediatric-specific biocompatible polymers—currently stretching 18-24 months for chronic implant encapsulation—force manufacturers to carry strategic inventory buffers that inflate working capital requirements. Supply concentrates in Switzerland, Germany, and Ireland for polymer encapsulation, with Taiwan and South Korea supplying miniaturized semiconductor components for implantable pulse generators. Single-source vulnerability in European polymer feedstock creates exposure to EMA MDR Article 61 compliance disruptions. Distribution runs through manufacturer-direct sales organizations with embedded clinical specialists, displacing independent distributors in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement authority at freestanding children's hospitals, with Texas Children's Hospital and Cincinnati Children's negotiating multi-year enterprise agreements that compress vendor margins and privilege integrated platform vendors over point-solution specialists.
For Market Incumbents: Compound defensive positioning through backward integration into biocompatible polymer supply chains and captive production of sub-2mm subdermal electrodes, countering supply concentration risk among Basel and Zurich specialty chemical producers while securing CE mark renewal pathways under tightening EMA MDR Article 61 evidence requirements. For New Entrants and Emerging Players: Anchor in cloud-native EEG interpretation platforms with FDA 510(k) clearance for algorithmic decision-support, exploiting interoperability gaps in legacy EMR systems at academic medical centers and capturing share from hardware-centric incumbents through subscription-based SaaS pricing that aligns with outpatient clinic budget constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-native vendors with regulatory-validated AI platforms over hardware-dependent device manufacturers facing component sourcing bottlenecks; acquisition targets should demonstrate FDA breakthrough pathway progress or PMDA orphan device designation. Monitor PMDA streamlined review pathway utilization rates as inflection indicator for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerates premarket review cycles for pediatric neurostimulation addressing unmet seizure disorders at Texas Children's and Cincinnati Children's. |
| Backward Integration into Polymer Supply | Secures captive sourcing of biocompatible encapsulation materials from Basel and Zurich specialty chemical producers. |
| Cloud-Native Platform Development | Enables subscription-based SaaS pricing that aligns with independent outpatient clinic procurement preferences. |
| PMDA Orphan Device Pathway Engagement | Captures Japanese volume anchors as adult patient pools shrink and pediatric indications become sustainable demand centers. |
| Hospital System Partnership Consolidation | Bundles hardware, AI interpretation, and long-term service contracts around single-platform ecosystems at academic medical centers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pediatric epilepsy centers, neonatal intensive care units, and neurodiagnostic device manufacturers. Primary interviews captured perspectives from pediatric neurosurgeons, hospital purchasing committee members, biomedical engineers specializing in implantable systems, and GPO contracts managers at consolidated children's hospitals. Secondary validation drew from FDA 510(k) and PMA filings, EMA Paediatric Investigation Plan submissions, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up device shipment analysis triangulated against top-down market sizing across the projection horizon.
Across the analysis window, the forecast framework modeled volume and value outputs through segmented projections across device type, application, end user, and technology dimensions, with pediatric-specific calibration for anatomical constraints and power thresholds. CAGRs were derived from trend extrapolation of procedural volumes, pricing trajectories, and technology substitution patterns. Industry-specific inputs included Level IV NICU construction pipelines, fellowship-trained pediatric epilepsy surgeon counts, and FDA breakthrough designation award rates.
Decision-makers should treat outputs as directional under assumptions of sustained Medicaid reimbursement for amplitude-integrated EEG systems and stable EMA MDR enforcement timelines; material deviation in polymer supply availability or pediatric neurosurgical workforce expansion would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Peripheral Neuritis Treatment Market
Neurology
Optic Neuritis Treatment Market
Neurology
Narcolepsy Treatment Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Intracranial Aneurysm Market
Neurology
Neurology Software Market
Neurology
Labyrinthitis Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Neuroprotection Market
Neurology
Global Neuroblastoma Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Italy Neurology Devices Market
Neurology
Movement Disorder Market
Neurology
Spinal Cord Trauma Treatment Market
Neurology
Brain Ischemia Market