
 CNS Treatment and Therapy Market | 2026-2036
CNS Treatment and Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
CNS Treatment and Therapy Market Outlook
Reimbursement-linked outcome guarantees is shifting how pharmaceutical contracts are structured in CNS care. Biogen leverages its specialized neurology infrastructure to sustain dominance in multiple sclerosis and emerging Alzheimer's portfolios. Novartis AG anchors its position through gene therapy platforms targeting rare neurological conditions. Eli Lilly and Company differentiates via early-stage investments in disease-modifying approaches for neurodegenerative disorders.
CNS treatment and therapy encompasses pharmacological interventions, neuromodulation devices, and biologic delivery systems designed to alter neurotransmitter pathways, synaptic plasticity, or immune-mediated neural damage, typically administered through oral, injectable, or implantable routes to manage psychiatric and neurological conditions. The primary commercial purpose centers on reducing disease progression, managing symptom burden, and restoring functional capacity in patients with disorders affecting the brain and spinal cord. Antidepressants and antipsychotics represent mature revenue pools with established prescribing patterns, while mood stabilizers command premium positioning in bipolar disorder management where treatment resistance drives switching behavior. Intravenous and injectable delivery modes capture higher per-dose economics but face utilization constraints from site-of-care requirements and infusion capacity limitations.
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress development timelines and reshape payer negotiation leverage for novel CNS entrants. The FDA's risk evaluation and mitigation strategies impose distribution controls that limit commercial flexibility for certain antipsychotics and antidepressants with safety profiles requiring monitoring. Stakeholders must weigh portfolio concentration in oral formulations against the capital requirements and reimbursement complexity of building injectable or infusion-based service capabilities.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress development timelines and reshape payer negotiation leverage for novel CNS entrants. The FDA's risk evaluation and mitigation strategies impose distribution controls that limit commercial flexibility for certain antipsychotics and antidepressants with safety profiles requiring monitoring. Stakeholders must weigh portfolio concentration in oral formulations against the capital requirements and reimbursement complexity of building injectable or infusion-based service capabilities.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation compresses clinical trial timelines for disease-modifying neurological candidates. EMA PRIME eligibility delivers parallel regulatory momentum in European markets.
- Gene Therapy Platforms:Viral vector delivery systems targeting rare neurological conditions unlock premium pricing corridors previously inaccessible to small-molecule developers. Manufacturing scale-up for adeno-associated virus production is absorbing capital from multiple therapeutic areas.
- Specialty Pharmacy Networks:United States integrated delivery systems consolidate patient access channels for complex neurological therapies. Site-of-care expansion into hospital outpatient departments captures higher reimbursement rates for infused CNS biologics.
Market Restraints
- Reimbursement Complexity:Medicare Part B infusion reimbursement cuts compress margins for intravenous neurological therapies administered in hospital settings. Prior authorization requirements for novel antipsychotics extend time-to-therapy initiation.
- Clinical Trial Failure Rates:CNS drug candidates demonstrate higher Phase III attrition than oncology or cardiovascular portfolios due to surrogate endpoint validation challenges. Amyloid-targeting Alzheimer's programs illustrate target-related efficacy uncertainties.
- Active Pharmaceutical Ingredient Concentration:Contract manufacturing for controlled-substance CNS APIs concentrates among a limited FDA-registered supplier base. Geopolitical exposure in Indian and Chinese intermediate sourcing creates supply continuity risk.
Strategic Opportunities
- Disease-Modifying Indications:Tau-targeting approaches for progressive supranuclear palsy and frontotemporal dementia represent untapped addressable populations. Early biomarker validation partnerships with academic medical centers accelerate patient identification.
- Neuromodulation-Digital Convergence:Closed-loop deep brain stimulation systems integrating real-time neural feedback algorithms differentiate implantable devices from static programming protocols. Software-enabled feature expansion extends product lifecycle value capture.
- Orphan Neurological Designations:FDA rare pediatric disease priority review vouchers attached to gene therapies for spinal muscular atrophy variants create secondary monetization pathways. European conditional marketing authorizations under exceptional circumstances accelerate revenue recognition timelines.
Industry Challenges
- Specialized Clinical Workforce Scarcity:Board-certified neuropsychiatrists and movement disorder specialists concentrate in academic medical centers. Community hospital systems struggle to recruit sufficient prescriber capacity for complex CNS therapy initiation.
- Real-World Evidence Generation:Payer demands for post-market outcome data require investment in patient registries and digital monitoring infrastructure. Data interoperability between electronic health record systems fragments longitudinal outcome tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNS Treatment and Therapy Market |
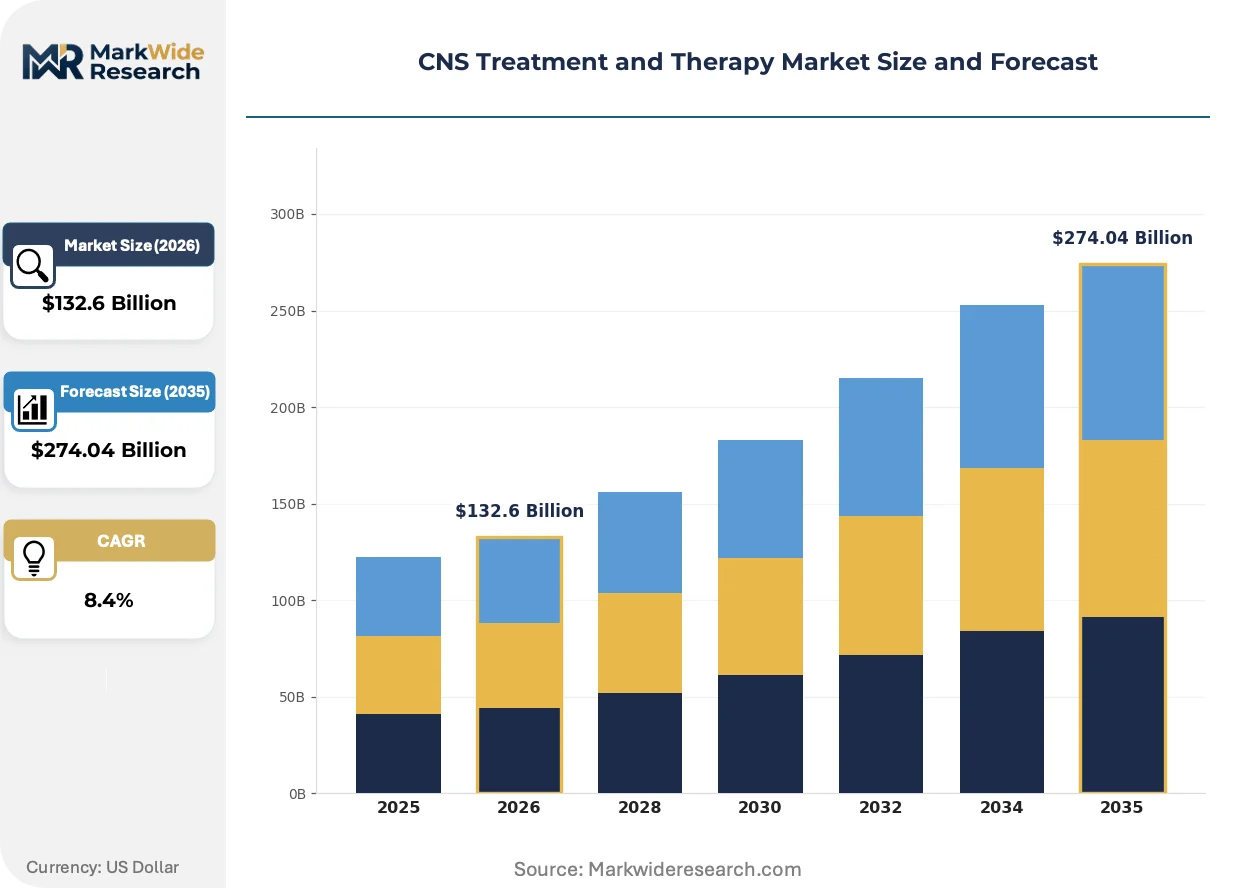
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $274.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Antipsychotics, Mood Stabilizers, Anxiolytics Therapy Area: Major Depression, Schizophrenia, Bipolar Disorder, Anxiety Disorders Delivery Mode: Intravenous, Oral, Injectable, Transdermal End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care |
| Companies Covered | Biogen, Novartis AG, Eli Lilly and Company, Johnson & Johnson Services, Inc., Merck & Co., Inc., AstraZeneca, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Otsuka Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNS Treatment and Therapy Market Strategic Shifts
Biomarker-driven patient stratification is fragmenting historically homogeneous diagnostic categories into addressable molecular subtypes. This molecular decomposition is reshaping trial design, regulatory submissions, and commercial targeting across neurodegenerative and psychiatric indications.
Antisense oligonucleotide platforms targeting superoxide dismutase 1 in familial amyotrophic lateral sclerosis demonstrate CNS penetration capabilities previously considered unattainable for nucleic acid therapeutics. Biogen and Ionis Pharmaceuticals advanced tofersen through accelerated approval based on cerebrospinal fluid neurofilament light chain reduction. The technology is absorbing development resources from traditional small-molecule neurodegeneration programs as sponsors recalibrate portfolio risk profiles.
EMA's orphan drug regulation revisions tighten maintenance requirements for market exclusivity in neurological indications with evolving diagnostic criteria. Sponsors must now demonstrate continued medical plausibility of orphan status as patient populations expand through biomarker inclusion. Rare disease gene therapy developers in Europe are responding with natural history study investments to defend designation integrity against regulatory challenge.
Integrated delivery networks in the United States are consolidating specialty pharmacy dispensing for oral CNS therapies under captive PBM arrangements. Hospital-owned specialty pharmacies capture margin previously retained by independent dispensing channels. This vertical integration concentrates in California, Texas, and Florida health systems with sufficient patient volume to justify 340B program compliance infrastructure.
CNS Treatment and Therapy Market Segmentation
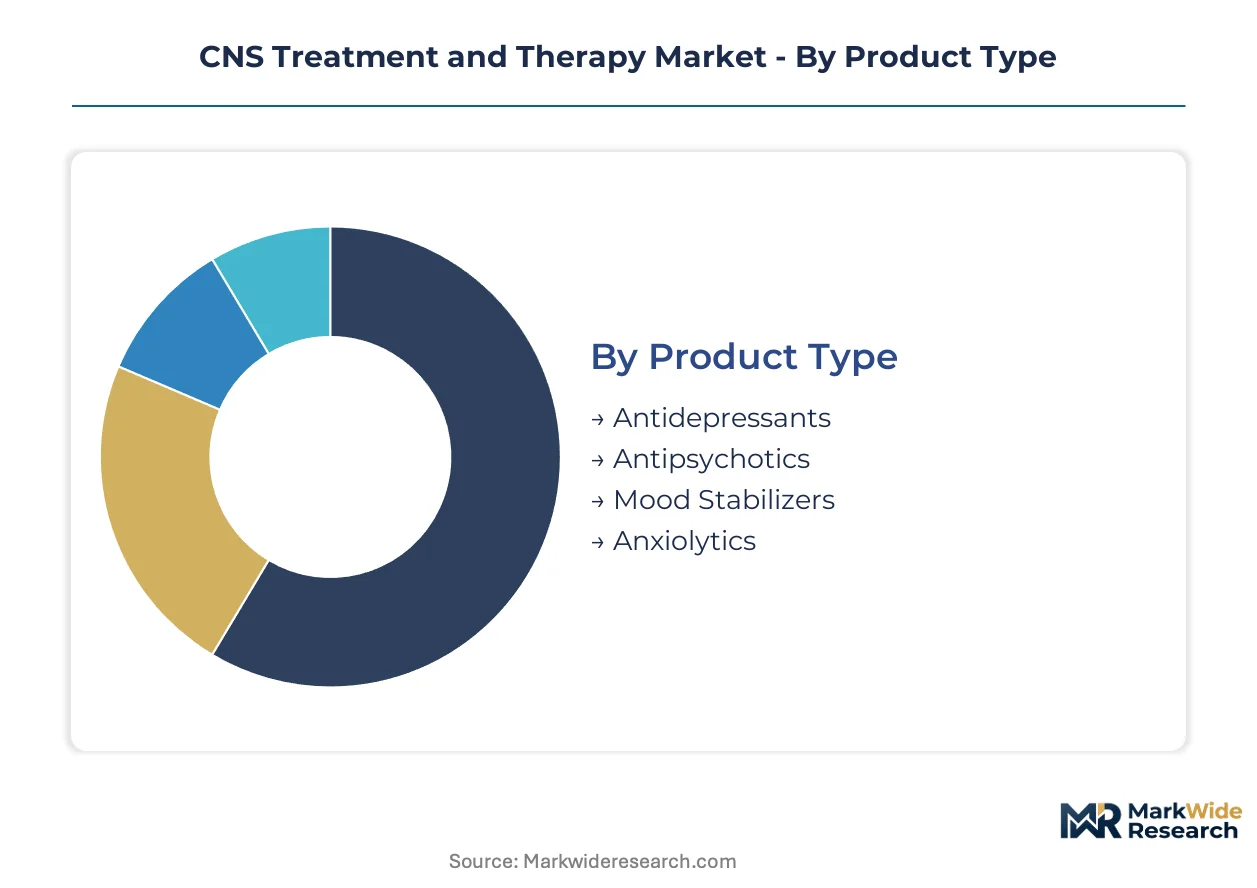
Segmentation in CNS therapeutics reveals how formulation decisions, site-of-care economics, and prescriber specialization fragment commercial pathways. Pharmaceutical manufacturers align portfolio investments with specific delivery infrastructure and reimbursement mechanics rather than treating neurological conditions as uniform demand pools.
Product Type:
Mechanism of action and receptor selectivity define competitive positioning across pharmacological classes, with serotonin modulation and dopamine pathway targeting representing distinct development and manufacturing competencies.
- Antidepressants:Selective serotonin reuptake inhibitors and dual-acting agents dominate prescription volume through primary care channels. United States commercial formularies favor genericized selective serotonin reuptake inhibitors while novel multimodal mechanisms command prior authorization requirements.
- Antipsychotics:Second-generation dopamine antagonists with metabolic risk profiles require REMS-linked distribution. Long-acting injectable formulations concentrate revenue in schizophrenia maintenance where adherence failure drives hospitalization costs.
- Mood Stabilizers:Lithium carbonate and anticonvulsant derivatives anchor bipolar disorder maintenance protocols.
- Anxiolytics:Benzodiazepine schedules and non-benzodiazepine alternatives face DEA quota constraints and tapering protocols.
Antidepressants lead on scale; antipsychotics lead on momentum through long-acting injectable conversion.
Therapy Area:
Diagnostic specificity and biomarker availability determine trial design complexity and regulatory pathway selection for disease-modifying versus symptomatic approaches.
- Major Depression:Treatment-resistant subpopulations drive demand for rapid-acting glutamatergic interventions and psychedelic-derived protocols. FDA breakthrough designations concentrate in ketamine-class mechanisms where traditional selective serotonin reuptake inhibitor failure rates exceed 30%.
- Schizophrenia:Negative symptom domains and cognitive impairment represent unmet need beyond positive symptom control. European markets emphasize functional recovery metrics in health technology assessment submissions.
- Bipolar Disorder:Mania-depression cycle management requires polypharmacy tolerance and metabolic monitoring infrastructure.
- Anxiety Disorders:Generalized anxiety and panic indications face diagnostic overlap with depression in primary care prescribing.
Major Depression leads on scale; Schizophrenia leads on momentum through long-acting formulation adoption.
Delivery Mode:
Pharmacokinetic profile and site-of-care requirements create distinct margin structures and supply chain configurations across administration routes.
- Intravenous:Infusion center capacity and Medicare Part B reimbursement mechanics determine commercial viability for monoclonal antibodies and gene therapies. Hospital outpatient departments capture margin through 340B program participation in the United States.
- Oral:Immediate-release and extended-release formulations dominate prescription volume through retail pharmacy channels. Specialty pharmacy consolidation into integrated delivery networks is reshaping dispensing economics.
- Injectable:Subcutaneous and intramuscular routes enable self-administration or clinic-based delivery for biologics.
- Transdermal:Patch delivery systems address adherence barriers and first-pass metabolism limitations.
Oral leads on scale; Intravenous leads on momentum through gene therapy pipeline expansion.
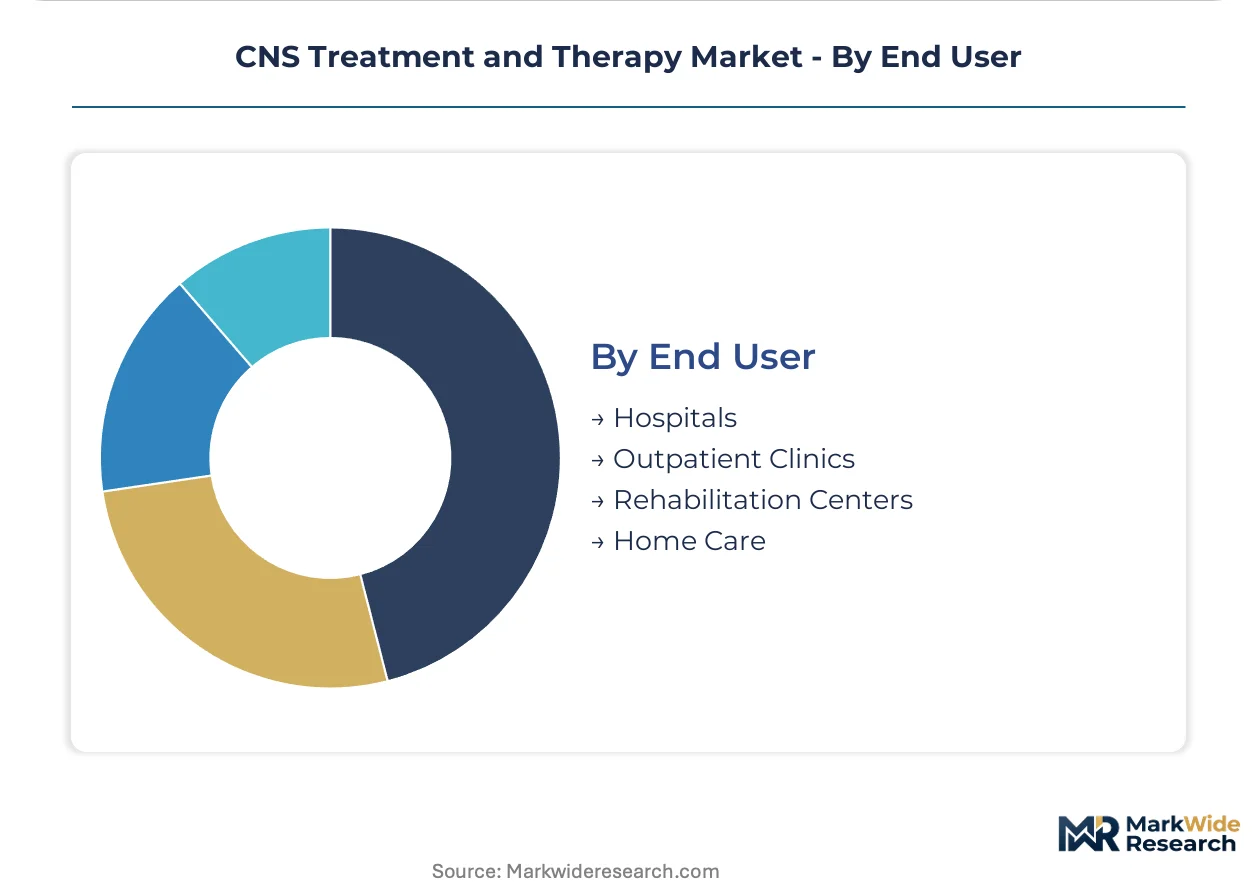
End User:
Prescriber specialization and care coordination intensity vary across institutional settings, determining therapy initiation protocols and monitoring requirements.
- Hospitals:Academic medical centers concentrate movement disorder specialists and deep brain stimulation programming capacity. Emergency department psychiatric holds drive acute antipsychotic utilization where intramuscular administration dominates.
- Outpatient Clinics:Community mental health centers and private psychiatric practices manage chronic medication regimens. Telepsychiatry expansion into outpatient settings is reshaping prescriber reach for oral maintenance therapies.
- Rehabilitation Centers:Subacute neurological recovery programs integrate pharmacological and physical therapy protocols.
- Home Care:Home infusion services and visiting nurse administration enable outpatient intravenous therapy completion.
Hospitals lead on scale; Outpatient Clinics lead on momentum through telehealth platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement mechanics diverge sharply from German statutory health insurance protocols, creating distinct commercialization pathways for intravenous neurological therapies. Japan's centralized pricing negotiations compress margins differently than India's fragmented private-pay landscape. The analysis examines five countries where regulatory frameworks and care delivery infrastructure shape market access.
United States
Medicare Part B infusion reimbursement cuts and 340B program participation drive hospital outpatient department consolidation for biologic administration. FDA breakthrough therapy designation accelerates timelines for disease-modifying candidates in Alzheimer's and ALS. The Greater Boston corridor anchors gene therapy development clusters, with Massachusetts General Hospital and Brigham and Women's Hospital hosting early-phase trial networks.
Germany
Statutory health insurance (GKV) binding price negotiations under AMNOG legislation limit launch premiums for novel antipsychotics and antidepressants. EMA centralized procedures enable simultaneous EU market access, though German health technology assessment (IQWiG) imposes additional evidence requirements. The Rhine-Main region concentrates CNS clinical trial infrastructure, with Frankfurt and Heidelberg academic medical centers coordinating multinational studies.
Japan
PMDA sakigake designation provides priority review for CNS innovations addressing unmet neurological need, compressing approval timelines versus standard pathways. Centralized drug pricing under Chuikyo negotiations caps reimbursement for oral mood stabilizers and injectable antipsychotics. The Kanto region around Tokyo hosts the majority of domestic Phase III sites for neurology indications.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that filter CNS therapies with incremental benefit profiles. NHS England's specialized commissioning frameworks concentrate access to gene therapies and neuromodulation devices in designated treatment centers. The Cambridge-London corridor houses antisense oligonucleotide development operations and biomarker validation partnerships.
India
CDSCO accelerated approval pathways for orphan neurological conditions attract contract research organization investment from multinational sponsors. Private hospital chains in Mumbai and Delhi-NCR build neuropsychiatric service lines targeting medical tourism for deep brain stimulation. Domestic API manufacturing for controlled-substance CNS intermediates concentrates in Hyderabad and Ahmedabad chemical clusters.
CNS Treatment and Therapy Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies commanding disease-modifying portfolios while regional players supply mature oral formulations. The structure tiers across three levels: multinational innovators with gene therapy platforms, mid-cap neurology-focused developers, and generic manufacturers serving price-sensitive markets. Strategic moves concentrate on M&A for CNS-targeted biotech assets and capacity expansion for viral vector manufacturing.
Among multinational innovators, Biogen, Novartis AG, and Eli Lilly and Company occupy positions exemplifying distinct archetypes. Biogen represents the specialized neurology infrastructure model sustaining multiple sclerosis and emerging Alzheimer's franchises. Novartis AG anchors the gene therapy platform approach targeting rare neurological conditions through viral vector delivery. Eli Lilly and Company exemplifies early-stage disease-modifying investment strategies in neurodegenerative disorders. These three structures illustrate how portfolio concentration decisions separate premium-positioned players from diversified competitors.
| Leading Market Players |
|---|
| Biogen |
| Novartis AG |
| Eli Lilly and Company |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| AstraZeneca |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Board-certified neuropsychiatrist concentration in the Greater Boston and San Francisco Bay corridors drives labor-cost differentials that widen pricing-tier spreads between academic medical center-administered gene therapies and community clinic-dispensed oral formulations. FDA REMS-linked distribution requirements for long-acting injectable antipsychotics impose site-of-care premiums that compound these geographic wage disparities.
Pricing Analysis
Capacity additions in South Korea and Singapore for viral vector manufacturing are reshaping price floors for gene therapy platforms targeting rare neurological conditions. Three-tier pricing structure across premium, standard, and economy levels separates disease-modifying biologics with breakthrough designation from established oral antidepressants and genericized mood stabilizers. Pricing pressure stems from Medicare Part B infusion reimbursement compression and 340B program margin capture by hospital outpatient departments. Community mental health centers exhibit highest price sensitivity due to state Medicaid formulary constraints, while integrated delivery networks with captive specialty pharmacies demonstrate lowest sensitivity through captive margin retention.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for active pharmaceutical ingredients are reshaping sourcing patterns for controlled-substance CNS intermediates. Manufacturing concentration centers on India, China, and the United States for API production, with viral vector bioreactor capacity clustering in Massachusetts, North Carolina, and Switzerland. Supply chain risk rests on single-source vulnerability for adeno-associated virus serotype production and DEA quota limitations for scheduled anxiolytic precursors. Distribution runs through hospital-owned specialty pharmacies capturing 340B margin, independent retail channels for oral maintenance therapies, and home infusion services for subcutaneous biologic administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CNS treatment market presents a late-cycle quality story as prescriber demand concentrates in disease-modifying candidates with biomarker-validated efficacy endpoints rather than symptomatic relief alone.
For Market Incumbents: Acquire antisense oligonucleotide platform capabilities to offset amyloid-targeting Alzheimer's program attrition risk. Secure backward integration into viral vector manufacturing through capacity investments in Research Triangle Park or Swiss biotech corridors. Consolidate prescriber relationships through movement disorder specialist fellowship sponsorships defending against emerging gene therapy developers. For New Entrants and Emerging Players: Treatment-resistant depression populations in community mental health centers represent underserved buyer archetypes with limited access to ketamine-class rapid-acting interventions. Frontotemporal dementia and progressive supranuclear palsy indications offer white-space entry with reduced competitive intensity versus Alzheimer's. Partner with telepsychiatry platforms for oral therapy initiation bypassing traditional specialist referral bottlenecks. For Investors and Strategic Acquirers: Mid-cap neurology-focused biotechs with Phase II biomarker data are the most active acquirer targets in this space for large pharmaceutical companies seeking disease-modifying pipeline replenishment. Long-term viability hinges on successful translation of tau-targeting mechanisms from orphan indications to broader neurodegenerative populations. Watch FDA breakthrough therapy designation density in neurodegeneration as inflection indicator for platform validation and premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-driven patient stratification in tau-targeting programs accelerates regulatory pathway selection. |
| Manufacturing Scale-Up | Viral vector bioreactor capacity expansion in Research Triangle Park addresses AAV supply constraints for gene therapies. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses timelines for disease-modifying candidates in ALS and frontotemporal dementia. |
| Pipeline Diversification | Antisense oligonucleotide platforms targeting SOD1 in familial ALS reduce reliance on small-molecule neurodegeneration risk. |
| Reimbursement Strategy | Outcome-based contracts with CMS and commercial payers align pricing with functional recovery metrics in schizophrenia maintenance. |
Study Parameters
Multiple input streams — regulatory filing analysis, formulary database review, and clinical trial registry monitoring — were reconciled with primary interviews. Conversations with drug development executives, regulatory affairs leads, formulary directors at integrated delivery networks, and payer access specialists informed demand-side assumptions. Secondary validation drew from FDA filings, EMA centralized procedure documents, ClinicalTrials.gov outcome disclosures, and CMS Medicare Part B claims data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Data-stream reconciliation across the projection horizon applied treatment-line stratification, dosage-form differentiation, administration-route economics, and regional regulatory cluster variations. CAGRs were derived from epidemiological trend extrapolation, pricing trajectory analysis, and therapy-adoption curve modeling. Forecast inputs incorporated FDA breakthrough therapy designation velocity, EMA PRIME eligibility patterns, and site-of-care shift dynamics between hospital outpatient departments and home infusion services.
Underlying measurement precision varies by segment; gene therapy and neuromodulation device categories carry tighter precision than oral antidepressant and anxiolytic markets due to concentrated prescriber populations and transparent pricing. Forecasts reflect assumptions regarding biomarker validation timelines, reimbursement policy stability, and manufacturing scale-up success. Regulatory pathway delays, amyloid-targeting efficacy controversies, and neuropsychiatrist workforce scarcity constitute trigger factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurology Software Market
Neurology
Neurological Biomarkers Market
Neurology
North America Neurology Monitoring Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Arachnoiditis Market
Neurology
White Matter Injury Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Italy Neurology Devices Market
Neurology
Global Vertigo Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Spain Neurology Devices Market
Neurology
Neuro Critical Care Market
Neurology
Movement Disorder Market