
 Network Point-Of-Care Glucose Testing Market | 2026-2036
Network Point-Of-Care Glucose Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Network Point-Of-Care Glucose Testing Market Intelligence
FDA software-as-a-medical-device guidance is broadening the cost-of-entry calculus for glucose meter manufacturers seeking hospital contracts. Abbott leverages its vertically integrated sensor manufacturing to sustain pricing power across integrated delivery networks. Danaher competes through its diagnostics platform density, anchoring recurring revenue from consumable test strips in high-throughput hospital laboratories.
Network point-of-care glucose testing encompasses connected diagnostic devices that transmit quantitative blood glucose measurements directly to electronic health records, laboratory information systems, or cloud analytics platforms via wired or wireless interfaces, typically achieving measurement precision within ISO 15197 accuracy standards of plus or minus fifteen percent at glucose concentrations above one hundred milligrams per deciliter. These systems eliminate manual transcription errors while enabling real-time glycemic surveillance across distributed care settings. Electrochemical technology dominates current installed bases due to proven enzymatic specificity and low per-test economics, though continuous glucose monitors capture the fastest expansion as closed-loop insulin delivery protocols migrate from critical care into step-down units. Hospitals represent the most concentrated margin pool, given their procurement volume and infection-control requirements that favor sealed, network-authenticated devices over consumer-grade alternatives.
FDA 510(k) clearance pathways and CLIA waiver classifications shape product development timelines and commercial access for network-enabled glucose systems in the United States, while the EU MDR and IVDR frameworks impose stricter post-market surveillance obligations on manufacturers serving European healthcare providers. The Centers for Medicare & Medicaid Services increasingly ties reimbursement integrity to device connectivity, pressuring holdout facilities toward infrastructure upgrades. Stakeholders must weigh the capital burden of enterprise middleware deployment against the operational risk of remaining in disconnected, audit-vulnerable workflows.
Market Dynamics
Hospital value-based care penalties and FDA software-as-a-medical-device mandates are compressing procurement timelines for connected glucose infrastructure, forcing integrated delivery networks to consolidate vendor relationships around API-native platforms that guarantee seamless electronic health record interoperability.
Growth Catalysts
- CMS Readmission Penalty Framework:United States hospital systems face escalating financial exposure from glycemic mismanagement episodes, driving enterprise-wide deployment of networked point-of-care devices that enable real-time surveillance and automated documentation.
- Closed-Loop Insulin Protocol Migration:Critical care units across tertiary hospitals are expanding continuous glucose monitoring integration into automated insulin delivery workflows, creating demand for network-enabled sensors that feed algorithmic dosing systems.
- Electrochemical Enzymatic Specificity:Proven glucose oxidase chemistry delivers ISO 15197-compliant accuracy at sub-dollar per-test economics, sustaining hospital laboratory preference over optical alternatives in high-throughput screening environments.
Market Restraints
- Enterprise Middleware Capital Burden:Hospital information technology departments confront seven-figure deployment costs for laboratory information system integration, device authentication servers, and cybersecurity hardening required for networked glucose meter fleets.
- Consumable Supply Concentration:Test strip manufacturing concentrates among three dominant suppliers, exposing procurement officers to price volatility when polymer substrate or enzyme reagent supply chains experience disruption.
- Interoperability Standard Fragmentation:Divergent communication protocols between proprietary device firmware and electronic health record platforms create integration friction that delays clinical deployment timelines.
Strategic Opportunities
- Step-Down Unit Penetration:Medical-surgical floors and skilled nursing facilities remain underpenetrated by networked glucose systems, presenting white-space expansion for vendors capable of simplified deployment without dedicated informatics support.
- Remote Patient Monitoring Convergence:Cellular-enabled glucose meters that synchronize with cloud analytics platforms are absorbing home health monitoring demand, blurring traditional boundaries between acute and ambulatory care settings.
- EU MDR Post-Market Surveillance:Stricter European vigilance requirements for in-vitro diagnostic devices are accelerating competitive exits by undercapitalized manufacturers, consolidating market access for compliant platform holders.
Industry Challenges
- Biomedical Informatics Talent Scarcity:Hospital systems struggle to recruit integration specialists capable of bridging clinical workflow design with Health Level Seven Fast Healthcare Interoperability Resources implementation.
- Legacy Device Depreciation Schedules:Capital equipment accounting practices extend replacement cycles for non-networked glucose meters, delaying refresh timelines even where connectivity mandates exist.
- Multi-Site Standardization Complexity:Integrated delivery networks operating dozens of facilities face heterogeneous device fleets that complicate enterprise contract negotiations and training standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Point-Of-Care Glucose Testing Market |
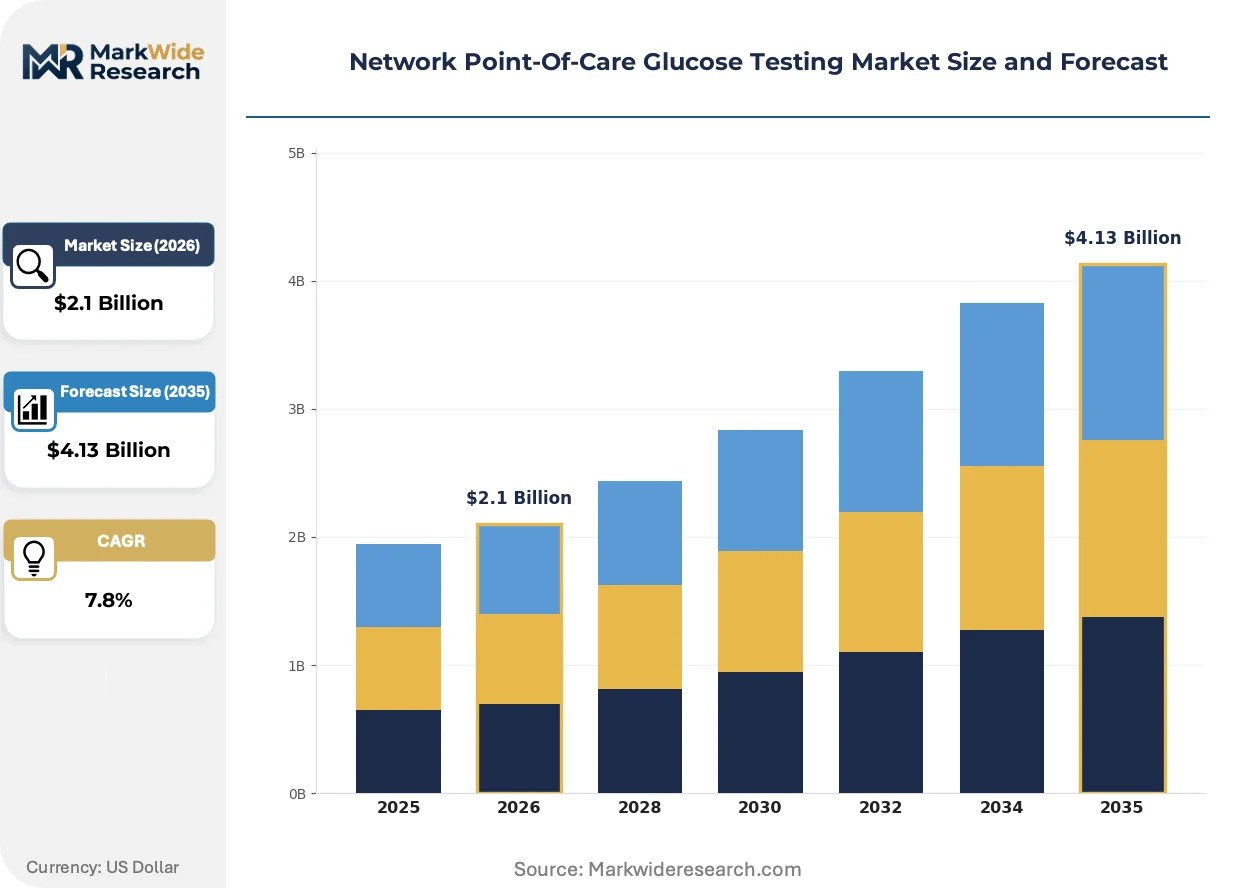
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Meters, Continuous Glucose Monitors, Test Strips, Control Solutions Technology: Electrochemical, Optical, Non-Invasive, Hybrid End User: Hospitals, Laboratories, Homecare, Outpatient Clinics Application: Diabetes Management, Ketoacidosis Monitoring, Clinical Research, Screening |
| Companies Covered | Abbott, Nova Biomedical, Danaher, F. Hoffmann-La Roche Ltd., Ascensia Diabetes Care Holdings AG, Prodigy Diabetes Care, LLC, Nipro Corporation, ACON Laboratories, Inc., i-SENS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Point-Of-Care Glucose Testing Market Strategic Shifts & Innovations
Connected diagnostic architectures are absorbing software-defined functionality that transforms glucose meters from isolated measurement instruments into distributed nodes within hospital data ecosystems, compressing the boundary between device and clinical information system.
Continuous glucose monitoring technology is absorbing algorithmic pattern recognition capabilities that enable predictive hypoglycemia alerts. Intensive care units at academic medical centers are adopting these systems at accelerating pace. The technology is absorbing functionality previously resident in separate clinical decision support platforms, consolidating vendor relationships around integrated sensor-analytics bundles.
REACH chemical registration requirements and EU MDR technical documentation mandates are elevating post-market surveillance burdens for glucose test strip manufacturers serving European healthcare providers. Industrial consequence includes extended product lifecycle management costs and accelerated consolidation among mid-tier suppliers. In-vitro diagnostic device categories with legacy predicate approvals face the steepest compliance recertification timelines.
Buying committees at United States integrated delivery networks are consolidating procurement authority from individual hospital laboratories into centralized supply chain functions. Traditional distributor relationships face displacement by direct manufacturer contracts that bundle device placement with consumable subscription pricing. This concentration is most visible in multi-state health systems operating under unified electronic health record platforms where standardization yields quantifiable informatics labor savings.
Network Point-Of-Care Glucose Testing Market Segmentation
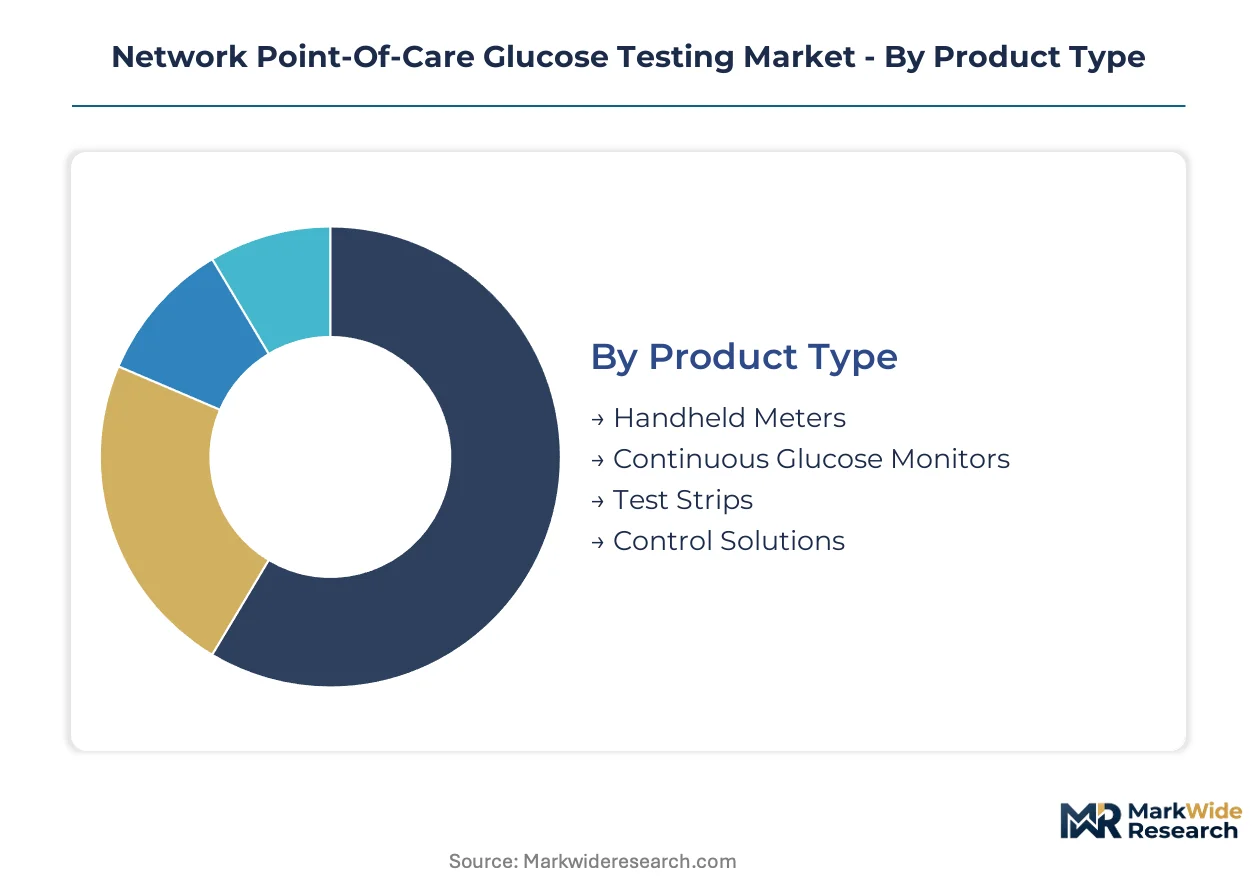
Network point-of-care glucose testing equipment fragments across product architectures, sensing modalities, and care settings. Procurement patterns diverge sharply between acute care systems demanding enterprise connectivity and ambulatory channels prioritizing cost minimization.
Product Type:
Supply concentration in enzyme reagent manufacturing and polymer substrate sourcing shapes competitive dynamics across device categories.
- Handheld Meters:Electrochemical strip-based devices dominate hospital installed bases due to ISO 15197 accuracy compliance and sub-dollar per-test economics. Integrated delivery networks in the United States mandate network-authenticated variants with wireless electronic health record transmission to satisfy CMS documentation requirements.
- Continuous Glucose Monitors:Factory-calibrated sensors with Bluetooth Low Energy connectivity enable real-time glycemic surveillance without fingerstick calibration. Tertiary hospital intensive care units absorb the steepest demand as closed-loop insulin protocols migrate from critical care into step-down units.
- Test Strips:Single-use enzymatic consumables concentrate manufacturing among three dominant suppliers.
- Control Solutions:Quality assurance reagents validate meter accuracy per CLIA waiver protocols.
Handheld meters absorb the bulk of installed capacity; continuous glucose monitors are expanding most quickly.
Technology:
Cost tier differentiation separates premium enzymatic systems from emerging optical alternatives targeting non-invasive measurement.
- Electrochemical:Glucose oxidase chemistry delivers proven specificity with minimal interference from hematocrit or oxygen tension variations. Hospital laboratories prefer this modality for high-throughput screening environments where per-test economics dominate procurement calculus.
- Optical:Near-infrared spectroscopy and photonic crystal sensors promise reduced consumable burden. Development concentrates in academic medical centers seeking alternatives to enzymatic strip dependence.
- Non-Invasive:Transdermal glucose measurement remains pre-commercial despite decades of research investment.
- Hybrid:Multi-sensor fusion architectures combine electrochemical reference measurements with optical pattern recognition.
Electrochemical platforms anchor current revenue; optical approaches are climbing the fastest toward regulatory clearance thresholds.
End User:
Customer type determines connectivity requirements, with acute care facilities demanding enterprise middleware integration unavailable in consumer channels.
- Hospitals:Tertiary medical centers and community hospitals deploy network-authenticated devices with laboratory information system integration. FDA software-as-a-medical-device guidance and CMS value-based care penalties compress procurement timelines toward API-native platforms.
- Laboratories:Central hospital labs and reference laboratories prioritize high-throughput strip-based analyzers with automated quality control tracking.
- Homecare:Cellular-enabled meters synchronize with cloud analytics platforms for remote patient monitoring reimbursement under Medicare chronic care management codes.
- Outpatient Clinics:Federally qualified health centers and specialty endocrinology practices balance device cost against interoperability needs.
Hospitals command the steepest pricing premiums; homecare is gaining share fastest as reimbursement shifts toward ambulatory monitoring.
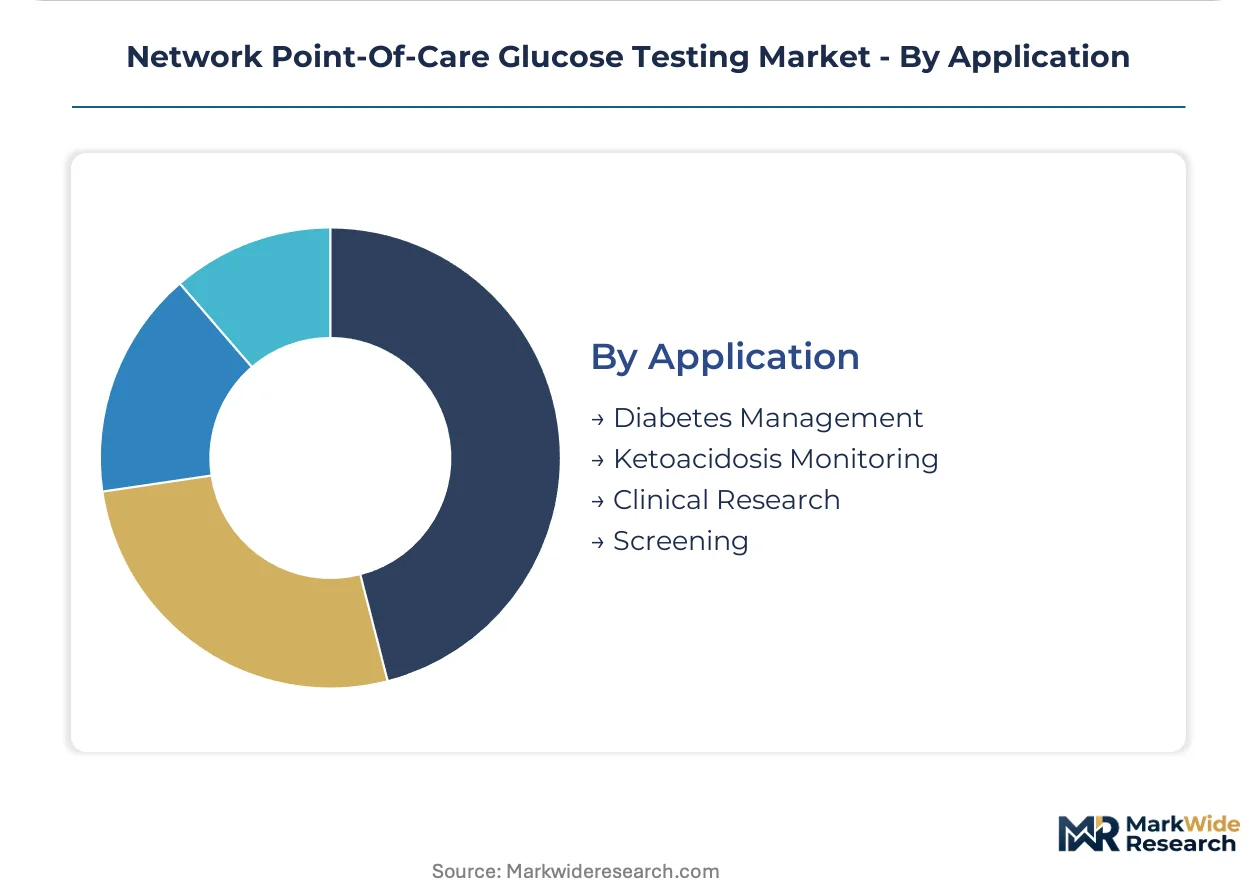
Application:
Volume concentration in diabetes management contrasts with margin concentration in specialized clinical research applications.
- Diabetes Management:Routine glycemic surveillance across inpatient and ambulatory settings represents the foundational use case. Networked point-of-care systems eliminate manual transcription errors while enabling real-time clinical decision support.
- Ketoacidosis Monitoring:Critical care applications demand rapid beta-hydroxybutyrate quantification alongside glucose measurement. Emergency departments absorb specialized meter configurations with ketone testing capability.
- Clinical Research:Pharmaceutical trials and device validation studies require calibrated instruments with audit-trail documentation.
- Screening:Population health initiatives and employer wellness programs deploy lower-cost networked devices for prediabetes detection.
Diabetes management absorbs the bulk of device shipments; ketoacidosis monitoring is expanding most quickly as emergency department throughput pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States integrated delivery networks command procurement scale for enterprise-wide network-enabled glucose device mandates, while European hospital systems absorb compliance costs from stricter post-market surveillance frameworks. Asia-Pacific markets concentrate manufacturing capacity for enzymatic test strip substrates.
United States
CMS readmission penalty frameworks and value-based care contracts drive hospital system investment in networked point-of-care infrastructure. FDA software-as-a-medical-device guidance forces legacy meter manufacturers toward API-native architectures for electronic health record interoperability. The Boston and Minneapolis medical device clusters host headquarters operations for dominant glucose monitoring platform holders.
Germany
EU MDR and IVDR post-market surveillance obligations elevate compliance costs for glucose test strip manufacturers serving European healthcare providers. ECHA REACH chemical registration requirements extend product lifecycle management timelines for enzymatic reagent suppliers. The Baden-Württemberg and Bavaria industrial corridors concentrate precision electrochemical sensor manufacturing for hospital laboratory systems.
Japan
PMDA regulatory pathways and JIS standards compliance shape product development timelines for network-enabled glucose systems in domestic hospital networks. METI industrial policy supports domestic manufacturing of high-precision enzymatic biosensors. The Kanto region around Tokyo anchors headquarters operations for major diagnostic device exporters.
China
NMPA medical device registration requirements and GB standards compliance create market access barriers for imported glucose monitoring platforms. SAMR pricing oversight pressures domestic hospital procurement toward locally manufactured alternatives. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate test strip substrate production and electrochemical sensor assembly capacity.
United Kingdom
NHS England integrated care system procurement frameworks consolidate purchasing authority for networked diagnostic devices across hospital trusts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR vigilance requirements for in-vitro diagnostic devices. The Cambridge-Oxford-London golden triangle concentrates digital health interoperability research and clinical validation trials for continuous glucose monitoring platforms.
Network Point-Of-Care Glucose Testing Market Key Industry Players
United States-based diversified health technology conglomerates anchor one tier; European and Asian specialized diagnostic manufacturers hold differentiated positions in regional procurement channels. Market structure concentrates around three dominant suppliers of enzymatic test strip consumables, with hospital laboratory contracts favoring platform density over point solutions. Strategic archetypes include vertically integrated sensor manufacturers, diagnostics platform conglomerates, and regional strip-based specialists. Competitive dynamics center on direct manufacturer contracting displacing traditional distributor relationships, alongside API-native middleware development for electronic health record interoperability.
Within the diversified health technology tier, Abbott and Danaher exemplify platform-scale positioning through integrated manufacturing and diagnostics density respectively. Abbott leverages captive sensor production to sustain pricing power across integrated delivery network contracts. Danaher anchors recurring revenue through consumable test strip economics in high-throughput hospital laboratory environments. Among specialized European holdings, F. Hoffmann-La Roche Ltd. and Ascensia Diabetes Care Holdings AG occupy positions shaped by regional regulatory compliance capabilities and established clinical chemistry relationships.
| Leading Market Players |
|---|
| Abbott |
| Nova Biomedical |
| Danaher |
| F. Hoffmann-La Roche Ltd. |
| Ascensia Diabetes Care Holdings AG |
| Prodigy Diabetes Care, LLC |
| Nipro Corporation |
| ACON Laboratories, Inc. |
| i-SENS, Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap test strip specialists in South Korea and Japan anchor enzymatic reagent manufacturing, translating polymer substrate scarcity into disciplined pricing power across hospital procurement cycles. Their concentrated ownership structures resist margin erosion even as integrated delivery networks press for volume discounts on network-authenticated meter fleets.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to emergency test strip orders from hospital laboratories facing CLIA audit deadlines, while spot inventory discounts emerge for consolidated integrated delivery network contracts covering twelve-month consumable subscriptions. Three-tier pricing structure across premium FDA-cleared, standard CE-marked, and economy domestic-tier devices separates enterprise middleware bundles from standalone meter sales. Cost compression in economy-tier handheld meters is intensifying because Chinese substrate producers are expanding electrochemical sensor capacity. Federally qualified health centers exhibit the sharpest price sensitivity, whereas tertiary academic medical centers absorb premiums for closed-loop insulin protocol integration.
Supply Chain Analysis
Enzyme reagent supply rests on Japanese specialty chemical producers and German precision polymer substrate manufacturers, with final assembly concentrating in China and Malaysia. Glucose oxidase biocatalysts, polyethylene terephthalate film substrates, and palladium electrode coatings constitute the critical input trinity. Single-source vulnerability in glucose oxidase fermentation capacity exposes procurement officers to disruption when pharmaceutical-grade biocatalyst lots face contamination holds. Distribution runs through regional medical device distributors losing share to direct manufacturer contracts with hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic test strip substrate capacity constraints prop pricing discipline, as three dominant suppliers control polymer film production essential for ISO 15197-compliant accuracy. Hospital procurement officers face limited alternative sourcing when fermentation batch failures interrupt glucose oxidase availability.
For Market Incumbents: Deploy API-native middleware development to lock in electronic health record interoperability contracts before FDA software-as-a-medical-device guidance hardens compliance timelines. Backward integration into captive glucose oxidase fermentation insulates against biocatalyst supply disruption. Consolidate distributor relationships into direct integrated delivery network contracts to capture recurring consumable revenue streams. For New Entrants and Emerging Players: Begin with step-down unit penetration in skilled nursing facilities where simplified deployment without dedicated informatics support creates white-space expansion. Cellular-enabled remote patient monitoring convergence absorbs fastest-growing ambulatory demand under Medicare chronic care management reimbursement codes. Target direct-to-health-system contracting to bypass established distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier strip manufacturers with EU MDR technical documentation already filed, as stricter post-market surveillance accelerates competitive exits. Five-to-ten-year viability hinges on cloud analytics platform integration capabilities rather than standalone device manufacturing. Watch FDA 510(k) clearance backlog duration as inflection indicator for market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Middleware Development | Guarantees electronic health record interoperability for CMS value-based care compliance. |
| Enzymatic Reagent Backward Integration | Captive glucose oxidase fermentation reduces exposure to single-source biocatalyst suppliers. |
| Step-Down Unit Simplified Deployment | Medical-surgical floors lack dedicated informatics support, creating white-space expansion. |
| Cellular-Enabled Remote Monitoring Launch | Medicare chronic care management codes reimburse cloud-synchronized ambulatory glucose tracking. |
| EU MDR Technical Documentation Investment | Accelerates competitive exits by undercapitalized manufacturers consolidating market access. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, CMS readmission penalty rate adjustments, and hospital capital expenditure disclosures anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, biomedical informatics integration specialists, glucose meter platform engineering leads, and group purchasing organization contract managers. Secondary validation drew from FDA device classification databases, CMS Hospital Compare quality metrics, hospital procurement database filings, and CLIA waiver certification records. Bottom-up meter shipment modeling triangulated against top-down integrated delivery network contract value estimates.
Input-output matrices mapped electrochemical test strip production capacity against hospital laboratory consumable demand across product type, technology modality, end-user facility tier, and application severity segments. CAGRs derived from segmented volume projections reconciled to aggregate market value estimates. Forecast inputs incorporated closed-loop insulin protocol adoption curves and EU MDR recertification timeline assumptions.
Underlying measurement precision varies by segment; continuous glucose monitor sensor forecasts carry tighter precision than handheld meter projections due to visible clinical trial pipelines. Forecasts reflect assumptions about FDA guidance finalization timing and CMS penalty framework stability. Supply chain disruption in enzymatic reagents, middleware cybersecurity incidents, and interoperability standard fragmentation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Saudi Arabia Diabetes Care Devices Market
Diabetes Care
India Insulin Infusion Pump Market