
 North America and Europe Artificial Pancreas Systems Market | 2026-2036
North America and Europe Artificial Pancreas Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Artificial Pancreas Systems Market Analytics
Platform licensing revenue from algorithm developers to pump manufacturers is narrowing as device makers build proprietary control software. Medtronic plc sustains one of the broadest installed bases of hybrid closed-loop systems across both regions. Tandem Diabetes Care Inc. differentiates through its interoperable ecosystem strategy, partnering with multiple continuous glucose monitoring suppliers rather than locking users into captive sensor pairings.
Artificial pancreas systems integrate continuous glucose sensors, insulin pumps, and predictive dosing algorithms to automate glycemic management without sustained patient intervention. These systems typically operate on glucose sampling intervals of one to five minutes and adjust basal insulin delivery through proprietary control-to-range or control-to-target algorithms. Closed-loop systems capture the dominant share of current revenue as regulatory approvals for fully automated systems advance faster in Europe than in North America. Algorithm-based systems represent the fastest-expanding technology segment as machine learning models improve hypoglycemia prediction accuracy and reduce alarm fatigue.
FDA premarket approval requirements and EMA medical device regulation (MDR) compliance timelines shape product launch sequencing and clinical trial investment priorities across both regions. The EU AI Act adds emerging scrutiny to adaptive algorithm updates, requiring post-deployment performance monitoring that the FDA does not yet mandate for comparable systems. Stakeholders must track divergence in transatlantic software-as-medical-device classification to avoid duplicative regulatory submissions and delayed market access.
Market Dynamics
Platform consolidation between algorithm developers and pump manufacturers is compressing licensing revenue streams while accelerating proprietary control software development across both regions.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for closed-loop algorithms in the United States are shortening time-to-market for novel insulin delivery systems and attracting venture investment into adaptive control software.
- Home Care Migration:Type 1 diabetes patients are shifting from clinical supervision to autonomous management, creating demand for fully automated glycemic control without sustained physician intervention.
- Reimbursement Parity:Germany's DiGA framework and select US commercial payers now cover automated insulin delivery at parity with conventional pump therapy, removing cost barriers for patient adoption.
Market Restraints
- Sensor Supply Concentration:Continuous glucose monitor manufacturing concentrates among three suppliers, exposing device makers to component allocation constraints and sensor calibration variability.
- EU AI Act Compliance Burden:Post-deployment performance monitoring mandates for adaptive algorithms add recurring validation costs that the FDA does not yet impose on comparable systems.
- Lithium-Ion Battery Dependence:Pump power systems rely on cobalt-intensive cell chemistries subject to price volatility and supply chain disruptions from Central African mining regions.
Strategic Opportunities
- France and Spain:These markets show underpenetration relative to Germany and the United States, with reimbursement frameworks for closed-loop systems still under development by national health technology assessment bodies.
- Algorithm-as-a-Service Models:Subscription-based control software licensing to third-party pump manufacturers creates recurring revenue independent of hardware sales cycles.
- Dual-Hormone Systems:Integration of glucagon delivery alongside insulin represents an emerging application category with limited current competition and distinct regulatory pathways.
Industry Challenges
- Control Systems Engineering Talent:Shortage of specialists in model predictive control and adaptive filtering for biological systems limits algorithm development velocity across both regions.
- MDR Technical Documentation:EMA medical device regulation requires extensive clinical evidence for software updates, slowing iterative improvement cycles for machine learning-based dosing models.
- Legacy Pump Interoperability:Integration complexity with existing patient devices that lack standardized communication protocols forces costly adapter development or patient hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Artificial Pancreas Systems Market |
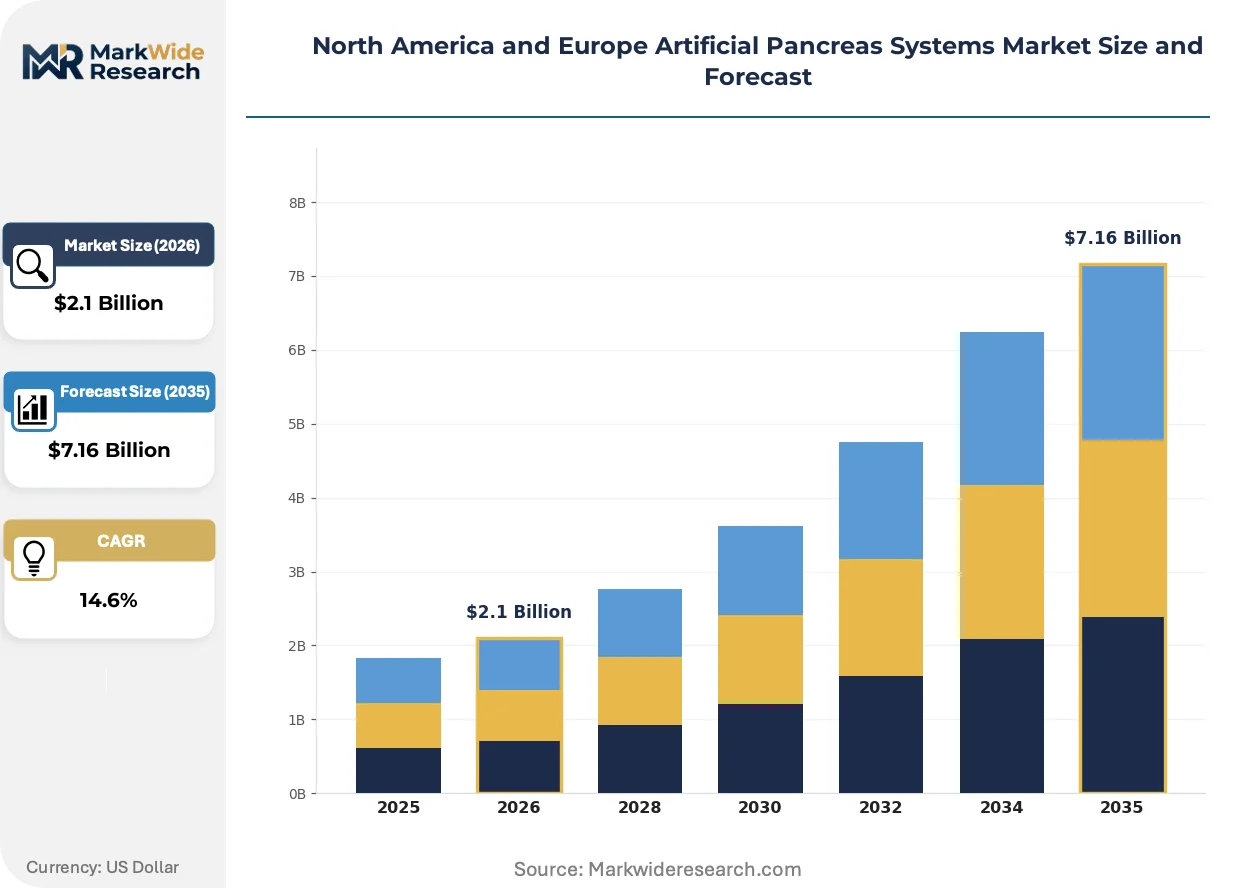
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-loop Systems, Open-loop Systems, Hybrid Systems, Smart Insulin Delivery End User: Hospitals, Clinics, Home Care, Research Centers Technology: Continuous Glucose Monitoring, Insulin Pumps, Algorithm-based Systems, Mobile Applications Application: Type 1 Diabetes, Type 2 Diabetes, Pediatric Diabetes, Postoperative Care |
| Companies Covered | Insulet Corporation, Cellnovo, Medtronic plc, Beta Bionics, Bigfoot Biomedical, Johnson & Johnson Services, Inc., Tandem Diabetes Care Inc., Diabeloop SA, Dexcom Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Artificial Pancreas Systems Market Evolving Landscape
Machine learning is displacing rule-based control architectures while regulatory divergence between FDA and EMA software classification is reshaping product development roadmaps.
Adaptive model predictive control algorithms that sample glucose every one to five minutes are rendering obsolete threshold-based suspend features in first-generation hybrid closed-loop systems. Pediatric endocrinology practices in the United States are adopting these platforms fastest, driven by parental demand for overnight hypoglycemia prevention. The shift is compressing upgrade cycles from five-year device replacement toward software-enabled capability expansion.
The EU AI Act's risk classification for adaptive medical devices is mandating post-market surveillance systems that track algorithm performance across diverse patient phenotypes. European manufacturers must now maintain real-world evidence registries for each software update, creating documentation burdens that FDA-cleared systems currently avoid. This divergence is forcing transatlantic developers to maintain parallel quality management systems or sequence regional launches.
Direct-to-consumer subscription channels are displacing traditional durable medical equipment distribution for sensor and supply replenishment. Young adult patients in Germany and the United States are purchasing continuous glucose monitor consumables through manufacturer apps rather than pharmacy or clinic intermediaries. This channel shift is compressing distributor margins while capturing patient adherence data for algorithm training.
North America and Europe Artificial Pancreas Systems Market Segmentation
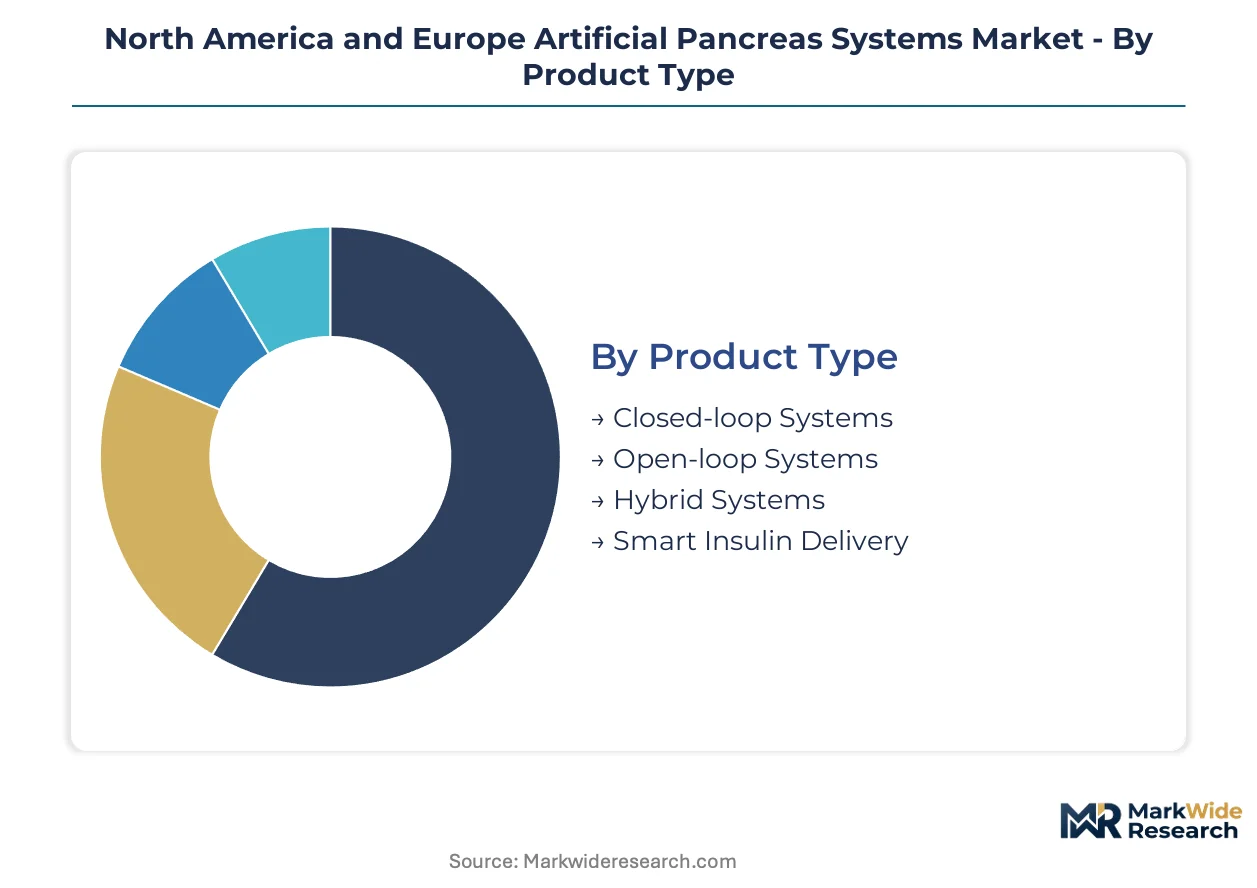
Artificial pancreas systems segment across hardware, software, and care settings with distinct regulatory pathways and reimbursement profiles. Each category reflects divergent patient risk profiles, technology maturity, and clinical evidence requirements across FDA and EMA jurisdictions.
Product Type:
The use-case spectrum spans fully automated glycemic control to physician-supervised open-loop configurations, with reimbursement eligibility tightening around closed-loop performance thresholds.
- Closed-loop Systems:These platforms integrate continuous glucose sensors with algorithm-driven insulin delivery requiring no patient intervention for basal adjustments. Demand concentrates in Germany and the United States where EMA and FDA have established dedicated review pathways for automated insulin delivery.
- Hybrid Systems:Patient meal announcements remain necessary, though basal rates adjust autonomously based on glucose predictions. Home care settings in pediatric diabetes represent the fastest-expanding adopter base as parental overnight monitoring burdens diminish.
- Open-loop Systems:Physician-directed insulin dosing without automated feedback loops persists in postoperative care and research protocols.
- Smart Insulin Delivery:Pen-based connected devices with dose logging and reminder functions serve price-sensitive Type 2 diabetes populations awaiting full automation coverage.
The dominant share belongs to Hybrid Systems, while Closed-loop Systems is closing the gap fastest as regulatory approvals accelerate on both sides of the Atlantic.
End User:
Care setting economics drive divergent procurement patterns, with capital equipment budgets at hospitals contrasting against consumable subscription models in home environments.
- Home Care:Autonomous patient management platforms with remote physician monitoring capture the steepest expansion trajectory as reimbursement frameworks in Germany and select US commercial payers achieve parity with conventional pump therapy.
- Hospitals:Inpatient glycemic management systems require integration with electronic health records and nursing workflow protocols, limiting vendor flexibility.
- Clinics:Outpatient endocrinology practices serve as initial prescription gatekeepers and algorithm training centers for new adopters.
- Research Centers:Academic medical centers conduct pivotal trials for FDA premarket approval and EMA MDR compliance, generating real-world evidence for adaptive algorithm updates.
Home Care commands the dominant share, while Research Centers gain strategic importance as the EU AI Act mandates post-deployment performance monitoring registries.
Technology:
Component interoperability standards determine ecosystem lock-in versus patient choice, with sensor-pump pairing flexibility becoming a key procurement criterion.
- Algorithm-based Systems:Machine learning models for hypoglycemia prediction and personalized insulin sensitivity estimation represent the fastest-growing technology segment as EMA and FDA divergence on software-as-medical-device classification reshapes development roadmaps.
- Continuous Glucose Monitoring:Factory-calibrated sensors with one-to-five-minute sampling intervals supply the glucose data streams upon which automated dosing depends.
- Insulin Pumps:Patch and tethered form factors compete on waterproofing, battery longevity, and occlusion detection sensitivity.
- Mobile Applications:Smartphone-based control interfaces and remote monitoring dashboards enable caregiver oversight and algorithm training data capture.
Continuous Glucose Monitoring holds the dominant share, though Algorithm-based Systems are expanding most quickly as control software displaces hardware as the primary value driver.
Application:
Disease severity and patient age stratify clinical evidence requirements, with pediatric indications demanding extended safety databases.
- Type 1 Diabetes:Absolute insulin deficiency populations with highest hypoglycemia risk drive premium pricing and earliest regulatory approvals for full automation.
- Pediatric Diabetes:Regulatory submissions require dedicated juvenile safety trials under both FDA and EMA frameworks, extending time-to-market despite strong parental demand.
- Type 2 Diabetes:Residual beta-cell function and higher insulin resistance complicate algorithm training, delaying closed-loop coverage expansion.
- Postoperative Care:Temporary insulin requirements in surgical recovery settings utilize open-loop protocols with intensive nursing supervision.
Type 1 Diabetes retains the dominant share, while Pediatric Diabetes climbs fastest as overnight hypoglycemia prevention becomes a reimbursable indication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care adoption patterns diverge sharply between Germany and the United States versus France and Spain, where reimbursement parity for automated insulin delivery remains under construction by national health technology assessment bodies.
United States
Pediatric endocrinology practices and young adult patients drive fastest adoption of hybrid closed-loop systems for overnight hypoglycemia prevention. FDA Breakthrough Device Designation compresses review timelines for novel control algorithms, accelerating venture investment into adaptive software. The Greater Boston corridor anchors concentrated development activity for dual-hormone system startups and machine learning dosing model ventures.
Germany
Type 1 diabetes patients in autonomous home management settings represent the steepest demand trajectory across Europe. The DiGA framework reimburses automated insulin delivery at parity with conventional pump therapy, eliminating cost barriers that persist in neighboring jurisdictions. The Rhine-Ruhr metropolitan region hosts dense clusters of insulin pump manufacturing and continuous glucose monitor distribution logistics.
France
Closed-loop system penetration lags German benchmarks by substantial margins despite comparable diabetes prevalence rates. ANSM and HAS coordinate parallel review processes for software-as-medical-device classification that delay market entry relative to FDA-cleared equivalents. The Paris-Saclay medical technology cluster generates clinical evidence for EMA MDR compliance though commercial rollout remains constrained by reimbursement negotiations.
United Kingdom
NICE technology appraisals for automated insulin delivery concentrate prescribing authority within specialized diabetes centers rather than primary care gatekeepers. MHRA post-Brexit regulatory divergence from EMA MDR timelines creates submission sequencing complexity for transatlantic developers. The Cambridge-London corridor sustains algorithm development talent pools drawn from computational biology and control systems engineering programs.
Spain
Regional health system fragmentation produces uneven access to closed-loop therapy across autonomous communities. AEMPS medical device regulation aligns with EMA MDR though reimbursement authorization proceeds through seventeen distinct regional assessment processes. The Barcelona metropolitan area concentrates Mediterranean clinical trial activity for pediatric diabetes indications and algorithm training data collection.
North America and Europe Artificial Pancreas Systems Market Competitive Landscape
Capability concentration sits with algorithm developers possessing adaptive control software expertise; scale advantage sits with established pump manufacturers commanding installed base migration pathways. The competitive structure bifurcates between vertically integrated device makers and interoperable ecosystem orchestrators. Three archetypes dominate: proprietary closed-loop stack owners, sensor-agnostic platform licensors, and dual-hormone system pioneers. Consolidation pressure manifests through algorithm acquisition activity and exclusive CGM partnership negotiations.
Within the integrated-device tier, Medtronic plc and Insulet Corporation occupy positions exemplifying contrasting hardware form factor strategies. Tandem Diabetes Care Inc. anchors the interoperable ecosystem archetype through multi-sensor pairing flexibility. Among European specialists, Diabeloop SA and Cellnovo represent algorithm-centric development models prioritizing control software over captive pump manufacturing.
| Leading Market Players |
|---|
| Insulet Corporation |
| Cellnovo |
| Medtronic plc |
| Beta Bionics |
| Bigfoot Biomedical |
| Johnson & Johnson Services, Inc. |
| Tandem Diabetes Care Inc. |
| Diabeloop SA |
| Dexcom Inc. |
| Others |
Value Network & Pricing Analysis
Cobalt mining concentration in the Democratic Republic of Congo and lithium extraction bottlenecks in Chile concentrate battery cell pricing power among three East Asian suppliers, compressing margins for European and North American pump assemblers while algorithm developers capture recurring software subscription value.
Pricing Analysis
Long-term offtake contracts for CGM sensors dominate procurement, with three-tier pricing structure across premium, standard, and economy levels tied to calibration accuracy and factory-automation certification. Price differentiation hinges on FDA breakthrough device tier and EMA MDR compliance status, with German DiGA reimbursement eligibility commanding material premiums. Pricing pressure stems from direct-to-consumer subscription channels displacing distributor markups. Pediatric endocrinology practices show lowest price sensitivity; Type 2 diabetes pen users exhibit highest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for lithium-ion cell procurement, forcing dual-sourcing strategies across South Korea and Japan. Pump manufacturing draws from Taiwanese semiconductor foundries, Malaysian sensor packaging facilities, and German precision molding suppliers. Single-source vulnerability concentrates in factory-calibrated glucose oxidase enzyme coatings. Distribution runs through durable medical equipment distributors in the United States and pharmacy-benefit-manager networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Breakthrough Device Designation and EMA MDR compression timelines are accelerating closed-loop algorithm commercialization, creating a high-growth disruption window where control software capabilities determine competitive survival.
For Market Incumbents: Entrench proprietary algorithm stacks through exclusive CGM partnerships and backward integration into continuous glucose monitor manufacturing, neutralizing the interoperable ecosystem threat from sensor-agnostic platform licensors. Prioritize pediatric indication expansion to capture parental overnight monitoring demand and extend replacement cycles through software-enabled capability upgrades rather than hardware refresh. For New Entrants and Emerging Players: France and Spain reimbursement underpenetration offers white-space entry before national health technology assessment bodies finalize automated insulin delivery coverage. Target dual-hormone system development with distinct glucagon regulatory pathways, avoiding direct competition with established insulin-only closed-loop installed bases. Pursue algorithm-as-a-service licensing to third-party pump manufacturers lacking in-house control software expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed adaptive control software ventures holding FDA pre-submission feedback but lacking manufacturing scale. Five-to-ten year viability depends on post-deployment performance monitoring infrastructure for EU AI Act compliance. Watch EMA-FDA software-as-medical-device classification divergence as the signal for which regulatory pathway offers faster monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Hormone System Development | Glucagon delivery integration addresses hypoglycemia rescue with limited current competition and distinct FDA-EMA review pathways. |
| Algorithm-as-a-Service Licensing | Subscription-based control software to third-party pump manufacturers creates recurring revenue independent of hardware replacement cycles. |
| Pediatric Indication Expansion | Overnight hypoglycemia prevention in juvenile diabetes commands premium pricing and accelerates parental-driven prescription decisions. |
| EU AI Act Compliance Infrastructure | Post-market surveillance systems for adaptive algorithms satisfy EMA MDR mandates that FDA-cleared competitors currently avoid. |
| Direct-to-Consumer Channel Buildout | Manufacturer app-based sensor replenishment captures patient adherence data for algorithm training while compressing distributor margins. |
Research Methodology
Operator-level perspectives from endocrinologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base, triangulated against FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov records, and DiGA reimbursement databases. Bottom-up patient population estimates and top-down device shipment analysis cross-validated market sizing across the analysis window.
Scenario-bracketing framed the analytical approach across product type, end user setting, technology maturity, and application severity segmentation dimensions. CAGRs derived from fitted growth curves incorporating reimbursement expansion trajectories, regulatory approval velocity differentials, and sensor-pump interoperability adoption curves. Machine learning algorithm performance benchmarks and real-world evidence registry completion rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by CGM-dominant suppliers or dual-hormone system pioneers would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market