
 Latin America Oral Anti-Diabetic Drug Market | 2026-2036
Latin America Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Oral Anti-Diabetic Drug Market Outlook
ANVISA's bioequivalence protocol is decoupling low-cost generic producers from premium formulation competitors in Brazil. Sanofi leverages its established insulin portfolio to anchor distribution across Latin American hospital networks. AstraZeneca competes through SGLT-2 inhibitor specialization, while Novo Nordisk dominates GLP-1 receptor agonist positioning despite oral delivery limitations.
Oral anti-diabetic drugs comprise pharmaceutical formulations administered perorally to reduce blood glucose in metabolic disorders, with active ingredients ranging from metformin hydrochloride to empagliflozin synthesized through multi-step organic chemistry and validated for dissolution profiles under pharmacopeial standards. These agents serve as first-line or adjunct therapy in Type 2 Diabetes management, targeting hepatic glucose output, insulin secretion, or renal glucose reabsorption pathways. SGLT-2 Inhibitors represent the fastest-expanding product category as cardiorenal outcome data drives payer preference, while Biguanides retain volume leadership through metformin's entrenched formulary position and minimal cost. Retail Pharmacies capture the dominant delivery channel share due to prescription refill frequency, though Online Pharmacies are gaining structural traction where regulatory frameworks permit remote dispensing.
Brazil's ANVISA, Mexico's COFEPRIS, and Argentina's ANMAT collectively govern market access through divergent bioequivalence, GMP inspection, and import licensing requirements that fragment registration timelines and elevate compliance expenditure for multinational sponsors. The EU-MDR alignment pressure and local pharmacovigilance mandates further constrain product lifecycle management. Stakeholders must monitor regulatory reciprocity negotiations and local manufacturing incentives to optimize portfolio prioritization across the region's heterogeneous approval pathways.
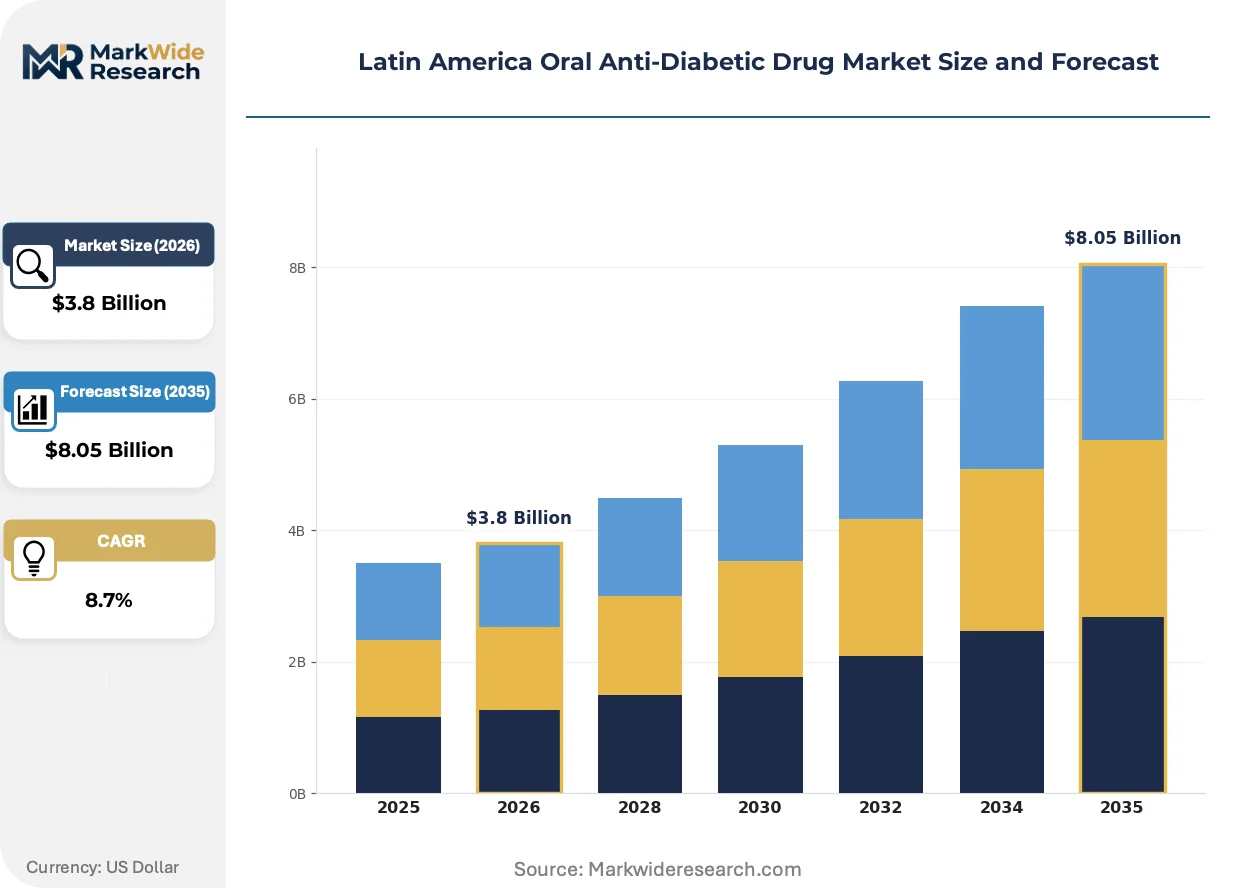
Market Dynamics
ANVISA's updated bioequivalence protocol is fragmenting Brazil's generic manufacturing base, forcing low-cost producers to absorb compliance costs that premium formulation competitors already amortized. This regulatory recalibration concentrates procurement power within centralized hospital purchasing agreements.
Growth Catalysts
- SGLT-2 Inhibitor Cardiorenal Data:Outcome studies from Brazil's public hospital system are redirecting physician prescribing toward agents with proven renal protection, expanding reimbursable indications beyond glycemic control.
- COFEPRIS Fast-Track Pathways:Mexico's regulator is compressing review timelines for therapies addressing unmet metabolic needs, accelerating market entry for novel oral formulations.
- Urban Diabetes Clinic Concentration:Mexico City's specialized endocrinology centers generate prescription volume that justifies dedicated sales force deployment and localized formulary negotiation.
Market Restraints
- API Import Dependency:Latin American manufacturers rely on Chinese and Indian active pharmaceutical ingredient suppliers, exposing production schedules to shipping cost volatility and customs clearance delays.
- ANVISA GMP Inspection Backlog:Brazil's regulator maintains a queue of facility certifications that extends manufacturing authorization timelines for new market entrants.
- Insulin Analog Substitution:Injectable GLP-1 receptor agonists capture physician preference for patients requiring significant HbA1c reduction, limiting oral therapy to earlier disease stages.
Strategic Opportunities
- Argentina's ANMAT Harmonization:Regulatory alignment discussions with MERCOSUR partners could streamline multi-country registration, reducing duplicate stability studies and clinical bridging requirements.
- Online Pharmacy Dispensing:Brazil's evolving telemedicine framework permits remote prescription validation, creating direct-to-patient channels for chronic medication refills.
- Fixed-Dose Combination Formulations:Metformin-SGLT-2 inhibitor combinations address polypharmacy adherence gaps in Colombia's fragmented primary care network.
Industry Challenges
- Bioanalytical Method Development:Generic sponsors struggle to validate dissolution profiles for complex modified-release formulations under ANVISA's tightened pharmacokinetic equivalence standards.
- Cold Chain Infrastructure Gaps:Last-mile distribution in Brazil's northern states lacks temperature-controlled logistics capacity, compromising stability for heat-sensitive oral agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Oral Anti-Diabetic Drug Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biguanides, Sulfonylureas, DPP-4 Inhibitors, SGLT-2 Inhibitors End User: Hospitals, Retail Pharmacies, Clinics, Online Pharmacies Delivery Mode: Tablet, Film-Coated Tablet, Extended-Release Tablet, Powder Indication: Type 2 Diabetes, Prediabetes, Gestational Diabetes, Insulin Resistance |
| Companies Covered | Sanofi, Astellas Pharma, AstraZeneca, Eli Lilly and Company, Janssen Pharmaceuticals, Boehringer Ingelheim, Merck and Co., Takeda, Novo Nordisk, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Oral Anti-Diabetic Drug Market Strategic Shifts
Formulation science and regulatory science are converging to reshape competitive positioning across Latin America's oral anti-diabetic segment. Manufacturers now compete on bioequivalence execution as much as molecular innovation.
Multilayer tablet technology is modularizing manufacturing workflows for combination therapies. Brazilian contract development organizations are adopting continuous processing equipment that separates active ingredient incorporation from controlled-release coating steps. This modularity permits mid-batch formulation adjustments without full process validation, compressing development timelines for sponsors targeting ANVISA's abbreviated new drug application pathway.
COFEPRIS is implementing post-market surveillance mandates that require real-world evidence submission for pharmacovigilance signal detection. Mexican sponsors must now integrate patient registries into commercialization planning, elevating data infrastructure costs but creating differentiation for manufacturers with existing health economics capabilities. The urban diabetes clinic segment is responding by consolidating purchasing around suppliers with demonstrated risk management systems.
Physician prescribing in São Paulo's hospital networks is rotating toward agents with cardiovascular outcome trial data, displacing legacy sulfonylurea preferences. Endocrinologists now prioritize SGLT-2 inhibitors and DPP-4 inhibitors in treatment algorithms, forcing sales organizations to retrain representatives on cardiometabolic narrative rather than glycemic efficacy alone. This behavioral shift is most visible in Brazil's southeast region, where academic medical centers influence community practice patterns through residency training programs.
Latin America Oral Anti-Diabetic Drug Market Segmentation
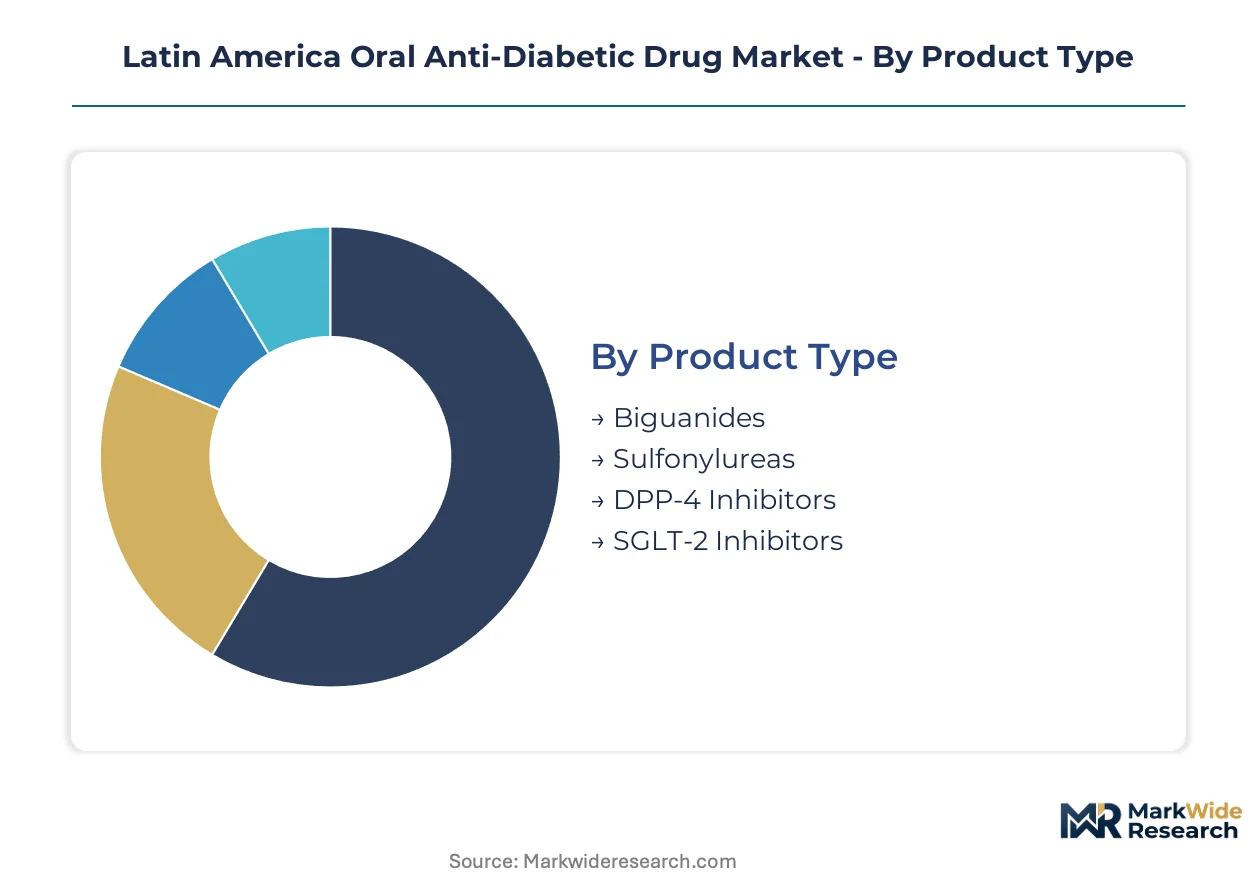
Segmentation in Latin America's oral anti-diabetic market reveals divergent procurement economics across public hospital systems and private retail channels. Product category splits track directly against cardiorenal outcome data availability and ANVISA reimbursement tiering.
Product Type:
Volume leadership clusters around legacy molecules with minimal manufacturing complexity, while premium positioning attaches to agents with cardiovascular outcome trial backing.
- SGLT-2 Inhibitors:Sodium-glucose cotransporter-2 blockers including empagliflozin and dapagliflozin demonstrate renal protective effects in Brazil's public hospital outcome studies. Physician prescribing in São Paulo's academic medical centers now prioritizes these agents for patients with established cardiovascular disease, displacing sulfonylurea preferences in treatment algorithms.
- Biguanides:Metformin hydrochloride formulations dominate prescription volume through entrenched first-line positioning in Mexican and Brazilian treatment guidelines. Mexico City's urban diabetes clinics generate refill density that justifies dedicated distribution infrastructure, though margin compression limits manufacturer investment in novel formulations.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors occupy a middle tier in Colombian and Argentine formularies, favored for weight-neutral profiles.
- Sulfonylureas:Glimepiride and glipizide persist in Brazil's northern states where cost minimization drives procurement.
Mature deployment sits with Biguanides. Newer deployment is concentrated in SGLT-2 Inhibitors.
End User:
Channel selection tracks against prescription frequency, cold chain requirements, and telemedicine regulatory maturity across national jurisdictions.
- Retail Pharmacies:Brick-and-mortar dispensaries capture recurring metformin and sulfonylurea prescriptions through established loyalty programs in Mexico's metropolitan zones. COFEPRIS-permitted remote validation is gradually integrating these locations into chronic disease management networks.
- Hospitals:Brazil's SUS centralized purchasing agreements concentrate SGLT-2 inhibitor procurement within public hospital networks, with ANVISA bioequivalence requirements filtering supplier pools. Southeast region academic centers influence community prescribing through residency training exposure.
- Clinics:Specialized endocrinology practices in Buenos Aires and Santiago generate concentrated demand for combination therapies.
- Online Pharmacies:Brazil's evolving telemedicine framework permits prescription validation for stable chronic medications, though last-mile cold chain gaps constrain penetration in northern states.
Volume concentration remains with Retail Pharmacies. Structural expansion is accelerating fastest through Online Pharmacies.
Delivery Mode:
Formulation complexity determines manufacturing qualification requirements and stability validation costs under ANVISA pharmacopeial standards.
- Extended-Release Tablet:Modified-release metformin formulations reduce gastrointestinal adverse events, commanding price premiums in Brazil's private insurance segment. Multilayer tablet technology adoption by São Paulo contract manufacturers compresses development timelines for sponsors targeting abbreviated new drug applications.
- Tablet:Immediate-release formulations dominate Argentina's price-controlled public procurement through minimal production cost.
- Film-Coated Tablet:Moisture-protective coatings address stability concerns in humid distribution corridors.
- Powder:Reconstitutable formulations serve pediatric and geriatric populations with swallowing difficulties.
Standard tablets anchor public procurement. Extended-release coatings are gaining fastest in private reimbursement tiers.
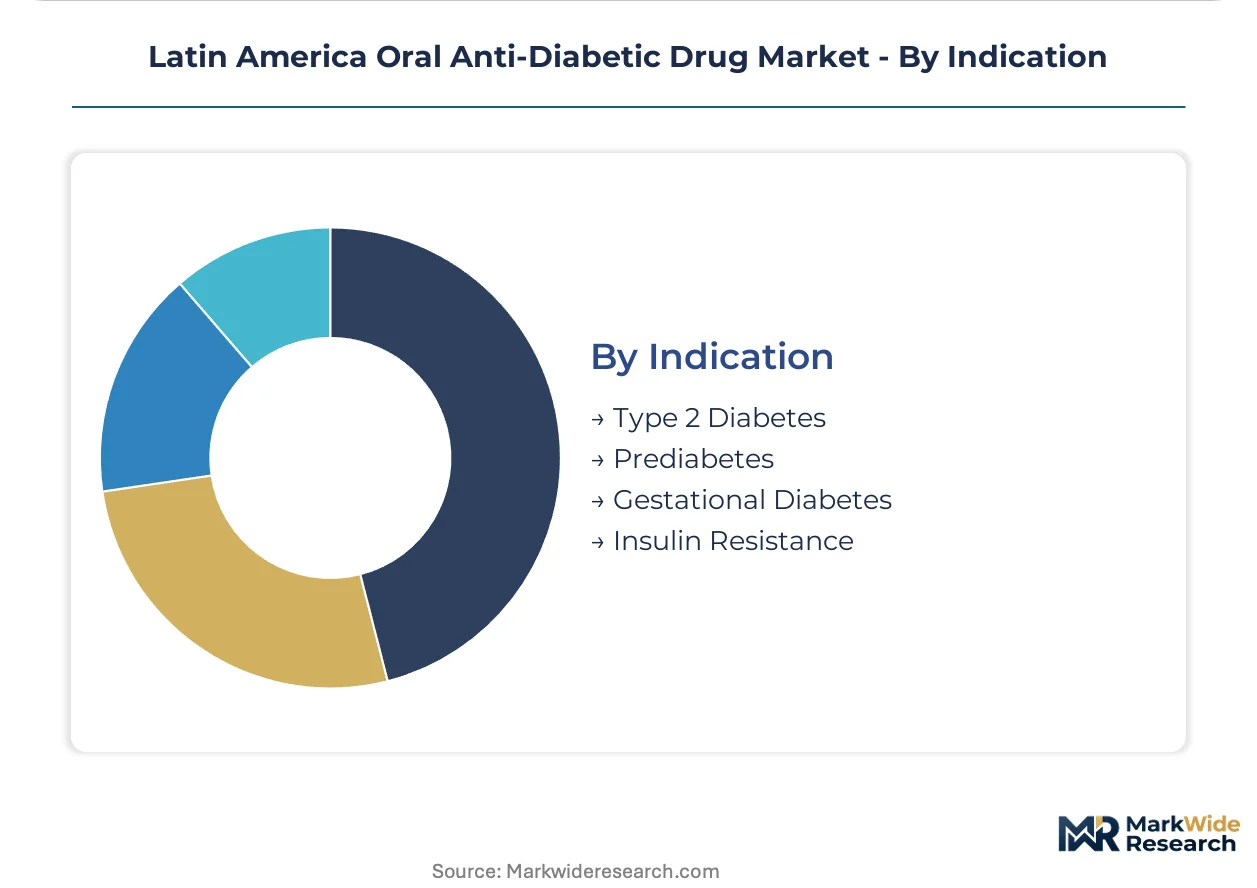
Indication:
Addressable patient populations diverge across disease severity, with reimbursement intensity scaling toward complication-prone cohorts.
- Type 2 Diabetes:Established disease stage drives the majority of prescription volume across Latin American formularies, with HbA1c targets determining therapy intensification sequences. Brazilian endocrinologists now prioritize cardiorenal protection alongside glycemic control in treatment selection.
- Prediabetes:Pre-diagnostic metabolic dysfunction represents an emerging prescription opportunity in Mexico's employer-sponsored wellness programs.
- Gestational Diabetes:Pregnancy-specific glycemic management relies on insulin in most jurisdictions, limiting oral agent penetration.
- Insulin Resistance:Polycystic ovary syndrome and metabolic syndrome indications occupy niche positioning in Argentine private practice.
Established therapy concentrates in Type 2 Diabetes. Prescription expansion is emerging fastest in Prediabetes screening programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone pharmaceutical incentives concentrate API formulation activity in Brazil's northern corridor. Mexican maquiladora tax advantages draw secondary packaging operations to border states. Argentine pharmaceutical clusters leverage MERCOSUR tariff preferences for regional distribution.
Brazil
São Paulo's academic medical centers generate concentrated prescription volume for SGLT-2 inhibitors with cardiorenal outcome data. ANVISA's updated bioequivalence protocol filters generic manufacturer participation in public hospital tenders. The Manaus Free Trade Zone attracts formulation facilities serving northern state distribution networks.
Mexico
Mexico City's specialized endocrinology clinics drive demand for fixed-dose combination therapies addressing polypharmacy adherence. COFEPRIS fast-track pathways compress review timelines for novel oral formulations targeting unmet metabolic needs. Nuevo León's pharmaceutical manufacturing corridor supplies northern border retail chains.
Argentina
Buenos Aires private endocrinology practices generate concentrated demand for DPP-4 inhibitors with weight-neutral profiles. ANMAT's ongoing MERCOSUR harmonization discussions promise streamlined multi-country registration timelines. The Buenos Aires metropolitan area anchors import-dependent distribution for heat-sensitive formulations.
Colombia
Bogotá's fragmented primary care network creates adherence gaps that fixed-dose metformin-SGLT-2 combinations address. The national pharmaceutical regulator maintains pharmacovigilance mandates requiring localized adverse event reporting. Medellín's pharmaceutical cluster supplies Andean region retail pharmacy chains.
Chile
Santiago's private insurance segment commands price premiums for extended-release metformin formulations reducing gastrointestinal adverse events. The national health technology assessment agency evaluates cardiorenal outcome data for formulary inclusion decisions. Valparaíso's port infrastructure facilitates API import logistics from Asian suppliers.
Latin America Oral Anti-Diabetic Drug Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Latin America's oral anti-diabetic segment. Market structure tilts toward consolidation among established insulin portfolios anchoring hospital network distribution, while SGLT-2 inhibitor specialization creates focused positioning. Three archetypes dominate: diversified pharmaceutical conglomerates with metabolic franchise breadth, cardiovascular-outcome-focused specialists, and regional generic manufacturers navigating ANVISA bioequivalence compliance. Competitive moves center on centralized hospital purchasing agreement capture and formulation technology licensing for multilayer tablet production.
Among diversified metabolic franchise holders, Sanofi and Novo Nordisk occupy positions leveraging established insulin portfolio relationships to anchor oral agent cross-selling across hospital networks. AstraZeneca exemplifies the cardiovascular-outcome specialist archetype, with SGLT-2 inhibitor positioning aligned to Brazil's public hospital cardiorenal data requirements.
| Leading Market Players |
|---|
| Sanofi |
| Astellas Pharma |
| AstraZeneca |
| Eli Lilly and Company |
| Janssen Pharmaceuticals |
| Boehringer Ingelheim |
| Merck and Co. |
| Takeda |
| Novo Nordisk |
| Others |
Value Chain & Pricing Dynamics
Brazil's SUS centralized hospital purchasing agreements concentrate procurement volume for SGLT-2 inhibitors, compressing margins for generic metformin suppliers while sustaining premium pricing for cardiorenal-validated formulations. This buyer concentration fragments pricing power across formulation tiers.
Pricing Analysis
Short lead-time premiums for ANVISA-registered SGLT-2 inhibitors command price separation from spot-imported generic sulfonylureas awaiting bioequivalence validation. Three-tier pricing structure across cardiorenal-validated, standard bioequivalent, and economy unbranded generics tracks certification grade and cold-chain handling requirements. Cost compression in Brazil's northern states intensifies because Manaus Free Trade Zone logistics gaps force air-freight premiums for heat-sensitive formulations. Public hospital procurement committees demonstrate highest price sensitivity, while São Paulo's private insurance segments absorb extended-release metformin premiums for gastrointestinal tolerability.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised oral agents remain underdeveloped across Brazil's northern distribution corridors, forcing write-offs that inflate effective procurement costs. Active pharmaceutical ingredient supply draws from India, China, and Switzerland for metformin hydrochloride, empagliflozin intermediates, and DPP-4 inhibitor precursors. Single-source vulnerability concentrates in Chinese KSM suppliers for SGLT-2 inhibitor synthesis. Distribution runs through São Paulo pharmaceutical wholesalers serving southeast region retail chains, with direct-to-hospital contracts bypassing intermediaries for SUS tender fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API import bottlenecks and ANVISA GMP inspection backlogs constrain manufacturing authorization velocity, sustaining pricing leverage for incumbent sponsors with validated supply chains.
For Market Incumbents: Anticipate regulatory reciprocity negotiations between ANVISA and MERCOSUR partners by pre-positioning multi-country stability documentation. Consolidate backward integration into Indian API sourcing relationships before customs clearance delays intensify. Lock in exclusive distribution terms with São Paulo academic medical centers to anchor residency training influence against AstraZeneca's SGLT-2 specialization. For New Entrants and Emerging Players: Telemedicine-integrated online pharmacy channels in Brazil offer the most penetrable route for chronic medication refill capture without cold-chain infrastructure investment. Target Colombia's fragmented primary care networks with fixed-dose metformin-SGLT-2 combinations addressing polypharmacy adherence gaps. Lead with COFEPRIS fast-track pathway engagement for novel oral formulations in Mexico City's urban diabetes clinics. For Investors and Strategic Acquirers: The window for entry favors Brazilian contract development organizations with multilayer tablet technology capabilities and existing ANVISA abbreviated new drug application track records. Long-term viability hinges on formulation science differentiation as bioequivalence execution supersedes molecular innovation. Monitor ANVISA bioequivalence protocol amendments as inflection indicators for generic manufacturer consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Bioequivalence Compliance Investment | Upgraded dissolution validation capabilities filter competitor pools in Brazil's public tenders. |
| MERCOSUR Regulatory Harmonization | Streamlined multi-country registration reduces duplicate stability study expenditure for regional sponsors. |
| Fixed-Dose Combination Pipeline Expansion | Metformin-SGLT-2 formulations address adherence gaps in Colombia's primary care networks. |
| Telemedicine Pharmacy Integration | Remote prescription validation in Brazil creates direct-to-patient channels bypassing wholesale intermediaries. |
| Cardiorenal Outcome Data Generation | Brazilian public hospital studies redirect physician prescribing toward reimbursable SGLT-2 indications. |
Study Parameters
Independent corroboration across ANVISA registration filings, COFEPRIS approval databases, and Brazilian hospital procurement records underwrites the qualitative findings on prescribing pattern shifts. Primary interviews with regulatory affairs leads at multinational sponsors, formulary directors within SUS purchasing committees, and hospital procurement managers in São Paulo's academic medical centers combined with secondary validation from ClinicalTrials.gov cardiorenal outcome studies and MERCOSUR trade harmonization documentation. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure reconciliation triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume expansion from mix-shift effects as SGLT-2 inhibitors displace sulfonylureas in Brazil's treatment algorithms. Segmentation dimensions span product category, delivery mode complexity, end-user channel, and regional regulatory cluster. CAGRs derive from patient population growth, therapy intensification rates, and reimbursement tier migration assumptions. Forecast inputs incorporate ANVISA bioequivalence approval timelines and COFEPRIS fast-track utilization rates for novel oral formulations.
The model holds under sustained ANVISA enforcement of updated bioequivalence protocols and stable API import logistics; deviation in Chinese customs clearance disruptions or MERCOSUR harmonization delays would shift manufacturer competitive positioning. Forecasts reflect documented assumptions on regulatory reciprocity and cold-chain infrastructure investment trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Blood Glucose Monitoring Market