
 Asia Pacific Continuous Glucose Monitoring (CGM) Market | 2026-2036
Asia Pacific Continuous Glucose Monitoring (CGM) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Continuous Glucose Monitoring (CGM) Market Insights
Market Context
Modular sensor-and-transmitter bundling is expanding choice architecture for Asia Pacific buyers, letting patients separate hardware purchases from data subscription tiers. Dexcom leverages integrated insulin pump partnerships to anchor premium positioning across Japanese and Australian channels. Abbott Laboratories competes on manufacturing scale, sustaining cost advantages in flash glucose monitoring strips. Medtronic navigates regulatory complexity through dedicated country-level compliance teams.
Technical Definition and Segment Structure
Continuous Glucose Monitoring comprises wearable electrochemical sensors that interstitial fluid glucose levels through enzymatic reactions, transmitting data to receivers or smartphones for real-time metabolic management. The primary commercial purpose is reducing hypoglycemic episodes while enabling precise insulin dosing for diabetes patients outside clinical settings. Real-time monitoring technology leads installed base volumes across the region, while cloud-based solutions capture fastest growth as telemedicine protocols mature. Homecare patients dominate end-user demand, though hospitals retain stronger margin pools through bulk procurement of traditional CGM devices.
Regulatory Framework and Outlook
Japan's PMDA, China's NMPA, and Australia's TGA each enforce distinct clinical evidence requirements for wearable sensor approvals, fragmenting market access timelines. India's CDSCO and South Korea's MFDS are tightening software validation standards for mobile application-linked systems, raising compliance costs for new entrants. Stakeholders must monitor divergence between national digital health data governance regimes to anticipate reimbursement eligibility shifts.
Market Dynamics
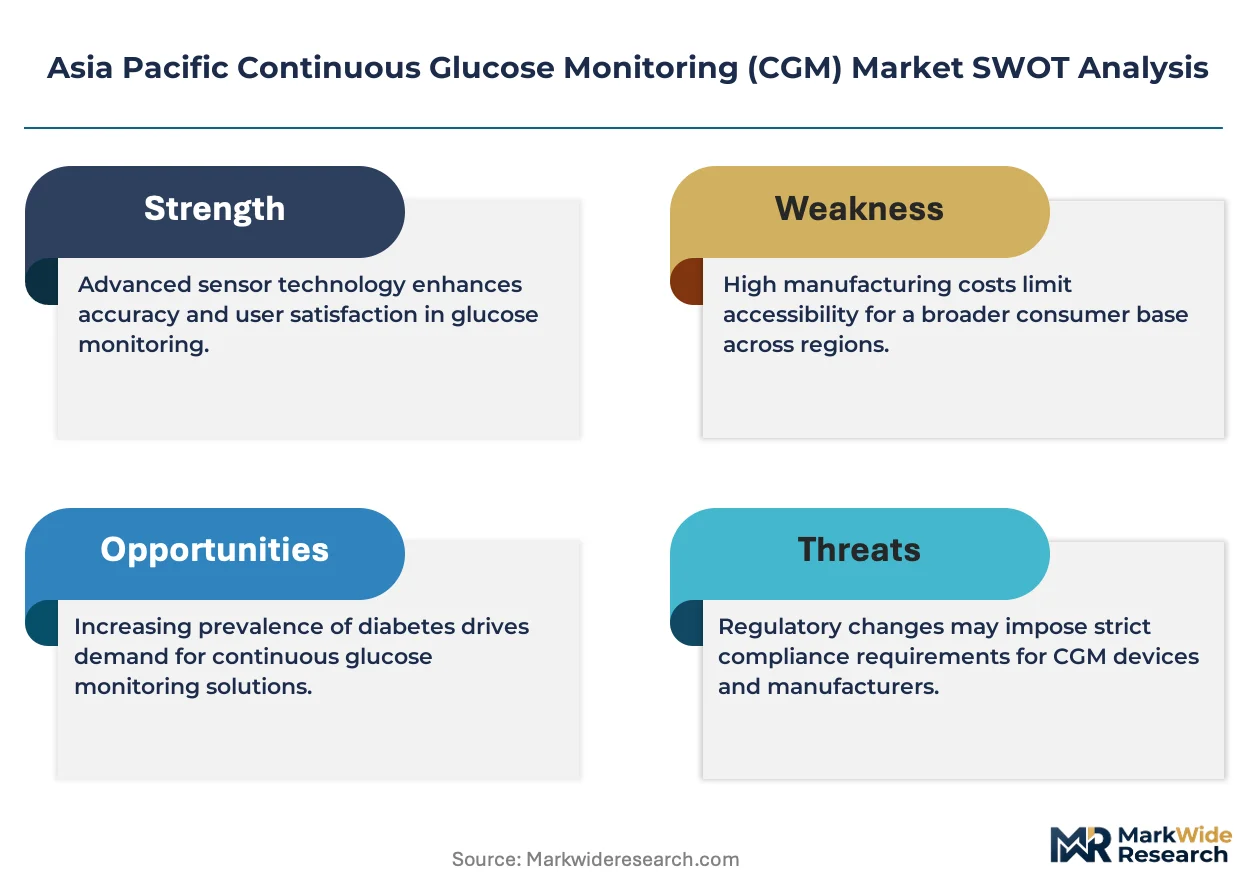
Reimbursement pathway fragmentation across Asia Pacific jurisdictions is forcing manufacturers to maintain parallel regulatory compliance architectures, elevating fixed costs for sensor platform commercialization.
Growth Catalysts
- Japan's PMDA fast-track designation:Accelerated approval channels for wearable glucose sensors are compressing time-to-market for next-generation enzymatic platforms. Domestic distributors are expanding dedicated diabetes device salesforces.
- Homecare patient migration:Post-acute care protocols across South Korea and Australia are shifting glucose management from hospital wards to residential settings. Remote monitoring infrastructure investments are following patient volume.
- Interoperability mandates:China's NMPA is requiring standardized data exchange protocols for connected medical devices. Open API requirements are enabling third-party application ecosystems around core sensor hardware.
Market Restraints
- Precious metal electrode costs:Platinum and palladium price volatility in sensor manufacturing is compressing gross margins for disposable components. Suppliers are locked into long-term offtake agreements with limited hedging coverage.
- Calibration enzyme supply concentration:Glucose oxidase production clusters in Western European contract manufacturers create single-source dependencies. Regional inventory buffers remain thin across Asia Pacific distribution networks.
- Skin adhesion chemistry limitations:Extended wear duration beyond 14 days requires novel biocompatible adhesive formulations. Current polymer platforms exhibit failure rates above acceptable thresholds in humid climates.
Strategic Opportunities
- India's CDSCO emerging pathway:Regulatory harmonization efforts with IMDRF standards are opening streamlined market access for previously approved US and EU devices. Domestic manufacturing incentives under PLI schemes are attracting contract assembly investment.
- Pharmacy channel direct distribution:Retail pharmacy networks in Thailand and Vietnam are developing specialized diabetes care counters. Bypassing hospital procurement committees is reducing sales cycle friction for patient-funded purchases.
- AI-enabled predictive hypoglycemia:Machine learning algorithms layered atop raw glucose trajectories are enabling anticipatory insulin dosing recommendations. Integration with insulin pump control systems is creating closed-loop automation demand.
Industry Challenges
- Biomedical sensor engineering talent scarcity:Electrochemistry and MEMS fabrication expertise concentrates in legacy semiconductor hubs. Recruitment for wearable biosensor R&D commands premium compensation in Singapore and Shanghai talent markets.
- Software-as-medical-device validation timelines:Mobile application updates trigger re-certification requirements under evolving MFDS and TGA guidance documents. Continuous deployment pipelines conflict with staged regulatory submission protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Continuous Glucose Monitoring (CGM) Market |
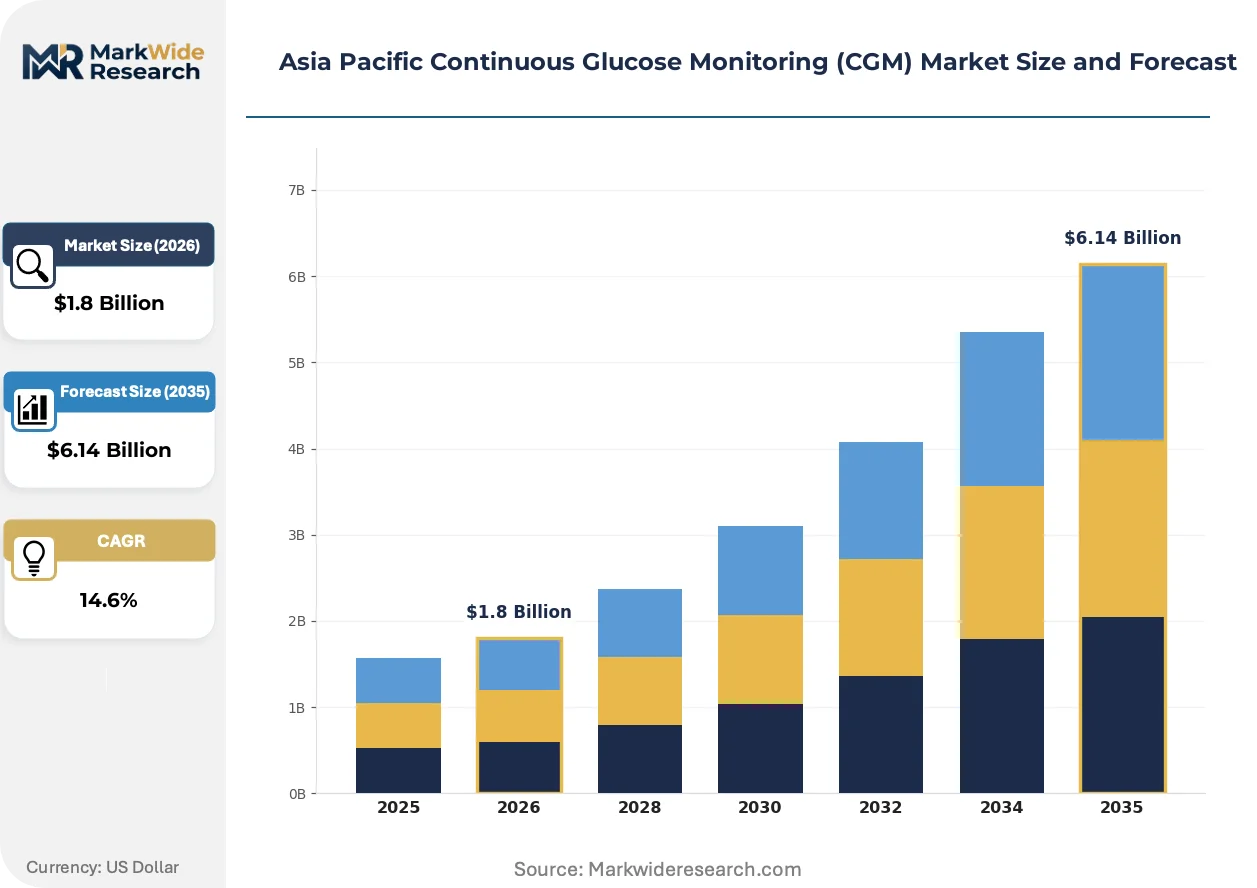
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitoring, Traditional CGM Devices, Wearable Sensors, Integrated Insulin Pumps Technology: Real-Time Monitoring, Intermittently Scanned Systems, Mobile Applications, Cloud-Based Solutions End User: Homecare Patients, Hospitals, Clinics, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Direct Sales, Distributors |
| Companies Covered | Dexcom, Abbott Laboratories, Medtronic, Senseonics, Ascensia, i-SENS, Medtrum Technologies, Sinocare, Ypsomed Holding, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Continuous Glucose Monitoring (CGM) Market Trends and Innovations
Sensor miniaturization and algorithmic glucose prediction are converging to redefine patient self-management workflows across Asia Pacific healthcare systems.
Factory-calibrated sensor technology is consolidating market preference around zero-fingerstick operation. Homecare patients in Japan and Australia are rejecting legacy systems requiring daily calibration inputs. This capability compression is marginalizing first-generation CGM platforms that demand patient-performed reference measurements.
Australia's TGA and South Korea's MFDS are tightening cybersecurity validation standards for cloud-connected glucose monitors. Manufacturers must now submit penetration testing documentation alongside clinical efficacy data. Premium sensor vendors are absorbing compliance costs into subscription pricing, while budget entrants face extended review timelines.
Subscription-based data service unbundling is separating hardware ownership from analytics access. Patients in China and Thailand are purchasing sensors outright while selecting tiered software packages for family sharing and physician dashboard integration. This consumption-pattern shift is visible most acutely in urban centers where digital payment infrastructure supports micro-transaction billing.
Asia Pacific Continuous Glucose Monitoring (CGM) Market Segmentation
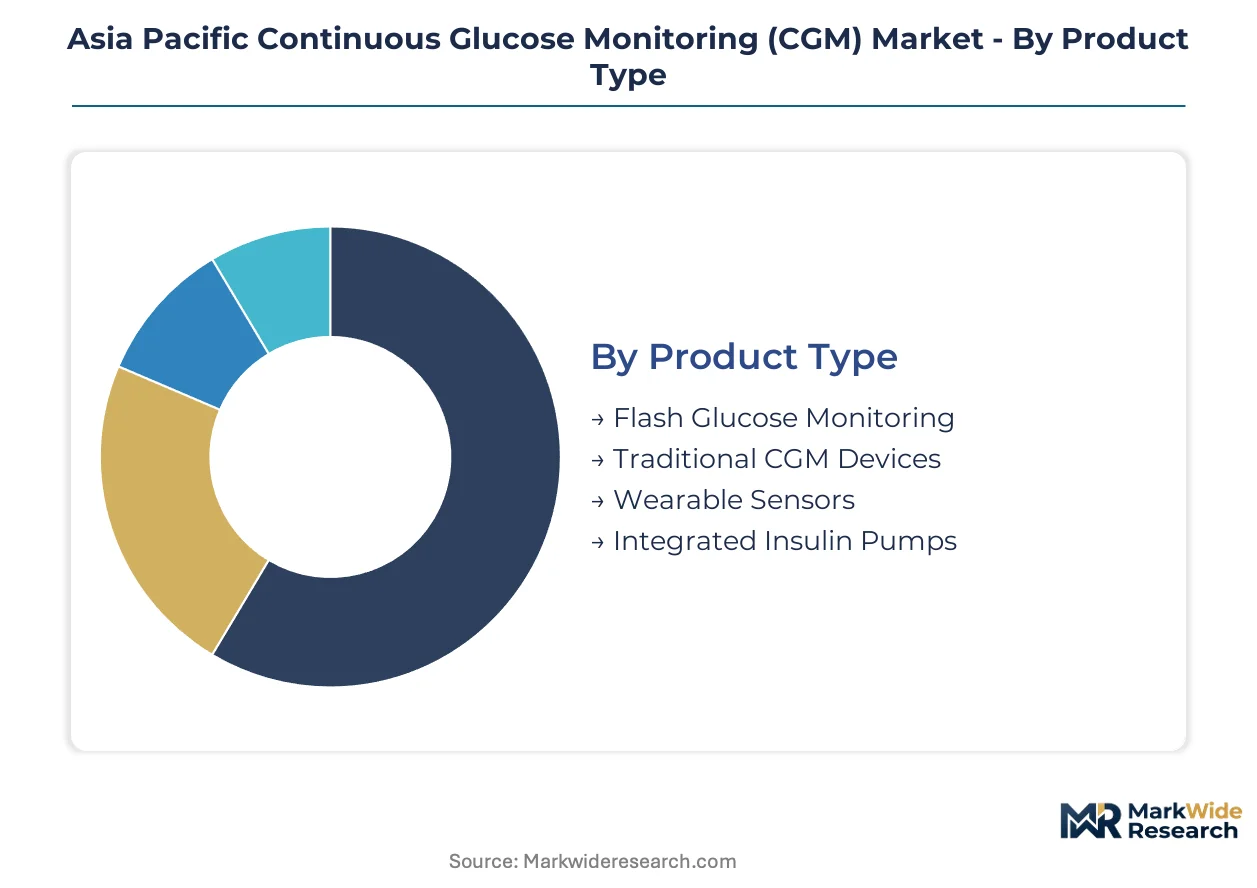
CGM market segmentation in Asia Pacific reveals distinct capital allocation patterns across hardware manufacturing, software development, and distribution infrastructure. Each category carries specific investment thresholds that shape competitive entry and margin sustainability.
Product Type:
Capital intensity varies sharply across product categories, with integrated systems demanding the highest upfront manufacturing investment while disposable components require continuous working capital deployment.
- Wearable Sensors:Electrochemical glucose oxidase electrodes embedded in biocompatible polymers transmit interstitial readings via Bluetooth Low Energy. Japanese and Australian homecare patients drive volume as factory-calibrated designs eliminate fingerstick requirements.
- Integrated Insulin Pumps:Closed-loop systems combine sensor input with algorithmic insulin delivery, demanding MEMS fabrication and precision dosing mechanics. South Korean hospitals anchor procurement for these premium platforms despite reimbursement complexity.
- Flash Glucose Monitoring:Disposable strip-based systems with lower per-unit sensor costs.
- Traditional CGM Devices:Earlier-generation platforms requiring patient-performed calibration.
Wearable sensors absorb the bulk of installed capacity; integrated insulin pumps are expanding most quickly.
Technology:
Technology selection determines recurring revenue potential versus one-time hardware capture, with cloud architectures enabling subscription monetization that pure hardware cannot match.
- Real-Time Monitoring:Continuous data streams with predictive alerts for hypoglycemic events. China's NMPA interoperability mandates are accelerating adoption across tier-1 urban hospitals.
- Cloud-Based Solutions:Aggregated glucose databases enabling population health analytics and remote physician oversight. Australian telemedicine protocols are driving fastest uptake among rural patient populations.
- Intermittently Scanned Systems:Patient-initiated data retrieval without continuous transmission.
- Mobile Applications:Smartphone-linked visualization and family sharing capabilities.
Real-time monitoring commands the largest installed base; cloud-based solutions are gaining share fastest.
End User:
Customer type segmentation maps directly to procurement pathway complexity, with institutional buyers leveraging volume leverage against individual patient price sensitivity.
- Homecare Patients:Self-managed diabetes outside clinical settings, purchasing through retail pharmacy or direct channels. Post-acute care protocols in South Korea are accelerating migration from hospital wards.
- Hospitals:Bulk procurement of traditional CGM devices for inpatient glycemic control. Japanese medical institutions retain stronger margin pools through centralized purchasing committees.
- Clinics:Outpatient facilities with mixed diagnostic and therapeutic service models.
- Healthcare Professionals:Individual practitioner prescribing and monitoring workflows.
Homecare patients represent the dominant demand volume; hospitals maintain the steepest expansion trajectory for premium integrated systems.
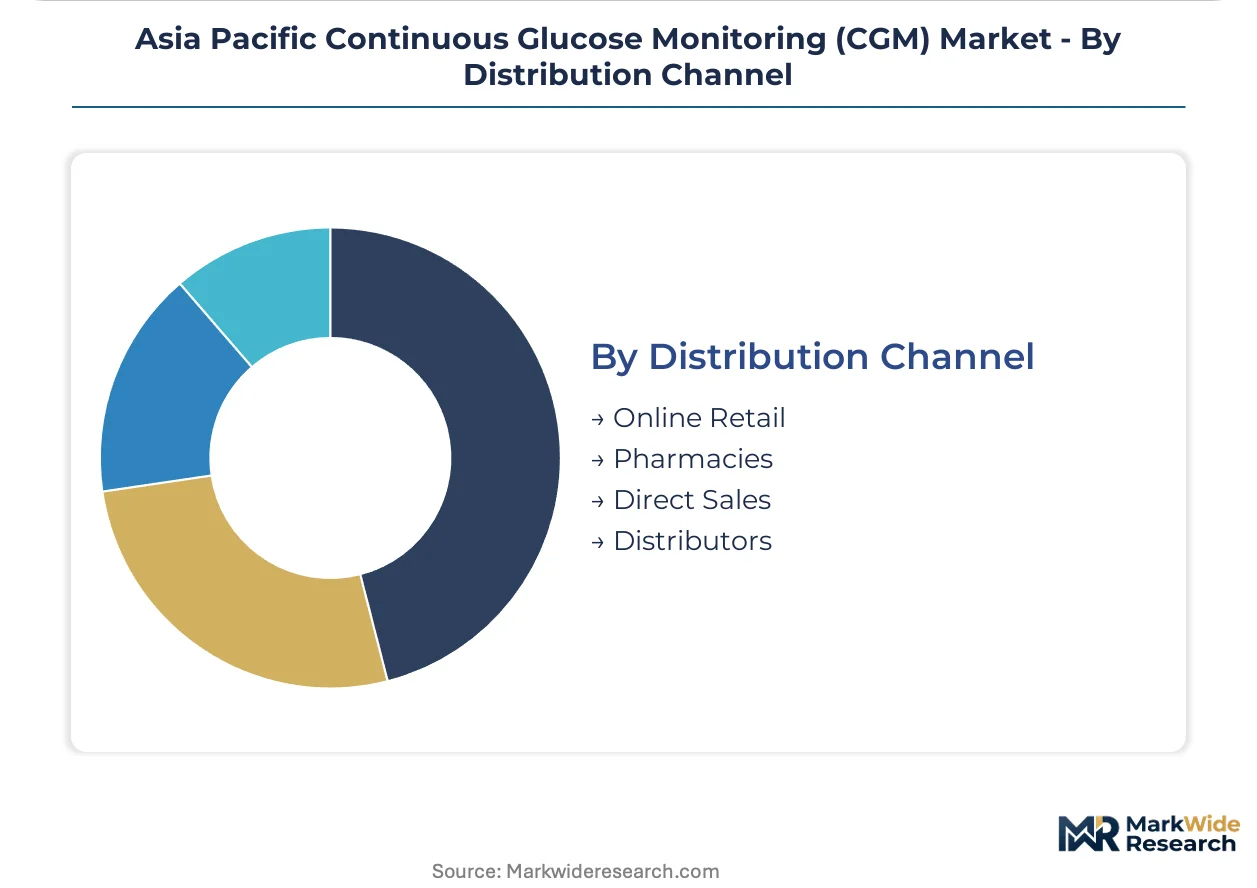
Distribution Channel:
Channel selection reflects regulatory pathway completion status and patient out-of-pocket capacity, with direct models bypassing traditional procurement friction.
- Pharmacies:Specialized diabetes care counters in Thailand and Vietnam enabling patient-funded purchases without hospital committee approval.
- Online Retail:E-commerce platforms with subscription billing integration for sensor replenishment.
- Direct Sales:Manufacturer-to-patient models for premium platform onboarding.
- Distributors:Third-party logistics networks covering fragmented geographic markets.
Pharmacies capture the largest transaction volume; online retail is climbing the fastest as digital payment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of CGM sensors and transmitters concentrates in coastal Chinese industrial zones, while patient demand spreads across aging populations in Japan, South Korea, and Australia. This production-consumption mismatch shapes logistics networks and regulatory submission strategies for device vendors.
China
Domestic sensor assembly lines in Shenzhen and Suzhou are scaling factory-calibrated output for both local consumption and export to Southeast Asian markets. NMPA's interoperability mandates for connected medical devices are accelerating software validation investments. The Yangtze River Delta hosts the densest cluster of electrochemical sensor foundries serving regional OEM contracts.
Japan
PMDA fast-track designations for next-generation enzymatic platforms are compressing approval timelines for wearable glucose sensors. Homecare patients in Tokyo and Osaka are rejecting legacy calibration-requiring systems. Kanto region distributors are expanding dedicated diabetes device salesforces to capture aging demographic demand.
South Korea
Post-acute care protocols are shifting glucose management from Seoul hospital wards to residential settings, driving remote monitoring infrastructure investment. MFDS software validation standards for mobile-linked systems are raising compliance costs for new entrants. The Seoul Capital Area anchors both device procurement committees and telemedicine platform development.
Australia
TGA cybersecurity validation requirements for cloud-connected monitors are extending review timelines for budget sensor vendors. Rural patient populations are adopting cloud-based solutions fastest under telemedicine reimbursement expansion. Sydney and Melbourne medical device distributors are absorbing compliance costs into subscription pricing tiers.
India
CDSCO harmonization with IMDRF standards is streamlining market access for US and EU-approved devices. PLI scheme incentives are attracting contract assembly investment to Gujarat and Karnataka. Pharmacy channel direct distribution in Maharashtra and Tamil Nadu is bypassing hospital procurement friction for patient-funded purchases.
Asia Pacific Continuous Glucose Monitoring (CGM) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia Pacific CGM markets, creating tiered competitive dynamics. Sensor manufacturing scale advantages cluster with diversified medical technology groups, while algorithm development concentrates in specialized diabetes care vendors. Three archetypes dominate: integrated pump-sensor system providers, disposable sensor scale manufacturers, and software-centric remote monitoring platforms. Capacity expansion in Chinese contract foundries and strategic partnerships with insulin pump OEMs represent the dominant competitive moves.
Among US-based diversified medical technology groups, Dexcom and Abbott Laboratories anchor premium and mass-market positioning respectively. Dexcom exemplifies the integrated partnership archetype through Japanese and Australian channel anchoring. Abbott Laboratories occupies the manufacturing scale position, sustaining cost advantages in sensor production. Medtronic represents the dedicated compliance architecture approach, navigating fragmented regulatory pathways through country-level specialization. These three entities collectively illustrate how geographic regulatory complexity shapes organizational design in Asia Pacific medical device markets.
| Leading Market Players |
|---|
| Dexcom |
| Abbott Laboratories |
| Medtronic |
| Senseonics |
| Ascensia |
| i-SENS |
| Medtrum Technologies |
| Sinocare |
| Ypsomed Holding |
| Others |
Pricing and Supply Chain Analysis
Homecare patient migration toward factory-calibrated sensors is forcing manufacturers to absorb software validation costs into subscription tiers, compressing hardware margins while elevating recurring revenue dependence. China's NMPA interoperability mandates and Australia's TGA cybersecurity requirements are accelerating this pricing model shift across Asia Pacific distribution networks.
Pricing Analysis
Margin tightening in wearable sensors reflects platinum electrode cost volatility and glucose oxidase supply concentration. Three-tier pricing structure across premium integrated pumps, standard real-time monitors, and economy flash systems stratifies by certification grade and calibration requirement. Cost-down pressure on disposable components accelerates because long-term offtake agreements limit hedging coverage. Hospital procurement committees show least price sensitivity; self-funded homecare patients in Thailand and Vietnam drive hardest bargain.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Singapore, and Sydney anchor hub-and-spoke patterns for sensor replenishment across Southeast Asian markets. Manufacturing concentrates in China's Yangtze River Delta, with glucose oxidase enzymes drawing from Western European contract manufacturers. Single-source vulnerability in enzyme supply creates inventory risk during geopolitical disruption. Distribution runs through pharmacy direct channels and manufacturer-to-patient models for premium platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific CGM markets function as a cost-of-compliance story where NMPA's interoperability mandates and MFDS software validation standards erect barrier-to-entry moats favoring players with dedicated country-level regulatory infrastructure.
For Market Incumbents: Lock in sensor manufacturing scale through backward integration into electrochemical foundry capacity in Shenzhen and Suzhou industrial zones. Deepen software companion development for closed-loop insulin pump integration to defend against emerging algorithm-centric entrants. Prioritize CDSCO pre-certification under IMDRF harmonization to capture India's pharmacy channel expansion. For New Entrants and Emerging Players: Enter via India's streamlined regulatory pathway for US and EU-approved devices, leveraging PLI scheme incentives for domestic assembly in Gujarat. Target Vietnam's specialized diabetes care counters at retail pharmacy networks, where hospital procurement committee bypass reduces sales cycle friction. Lead with AI-enabled predictive hypoglycemia features to differentiate against legacy calibration-requiring systems. For Investors and Strategic Acquirers: The window for entry favors software-centric remote monitoring platforms with cloud architecture and subscription monetization capability. Long-term viability hinges on algorithm development talent concentration in Singapore and Shanghai. Watch for MFDS guidance document updates on mobile application re-certification as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Parallel pathway development across Japan's PMDA, China's NMPA, and Australia's TGA accelerates patient access. |
| Software Companion Development | Machine learning integration with insulin pump control systems enables closed-loop automation demand capture. |
| Hospital System Partnership | Bulk procurement agreements with Seoul Capital Area medical institutions anchor premium integrated system volumes. |
| Manufacturing Scale-Up | Factory-calibrated sensor capacity expansion in Shenzhen serves both domestic Chinese and Southeast Asian export demand. |
| Regulatory Harmonization | CDSCO alignment with IMDRF standards opens streamlined market access for previously approved US and EU devices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and diabetes care clinicians combined with NMPA submission databases, PMDA approval records, and CMS Medicare reimbursement data. Bottom-up sensor shipment estimates and top-down healthcare expenditure triangulation validated market sizing.
Granularity-level modeling tracked wearable sensors, integrated insulin pumps, flash glucose monitors, and traditional CGM devices across real-time monitoring, cloud-based solutions, intermittently scanned systems, and mobile application technologies. End-user segmentation captured homecare patients, hospitals, clinics, and healthcare professionals through pharmacy, online retail, direct sales, and distributor channels. CAGRs derived from patient population growth, reimbursement expansion timelines, and technology substitution curves across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA guidance document revisions or platinum price spike scenarios. Outputs reflect documented assumptions on regulatory approval timelines and patient migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Global Diabetes Pen Market