
 Japan Oral Anti-Diabetic Drug Market | 2026-2036
Japan Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Oral Anti-Diabetic Drug Market Outlook
Domestic pharmaceutical manufacturing in Osaka and Tokyo is broadening output capacity for oral hypoglycemic formulations. Takeda Pharmaceutical Company Limited leverages its heritage in metabolic disease research to sustain pipeline depth. Daiichi Sankyo Company anchors commercialization through hospital-centric distribution networks. Boehringer Ingelheim competes on fixed-dose combination expertise with established cardiology crossover indications.
Japan oral anti-diabetic drugs comprise small-molecule hypoglycemic agents administered perorally, formulated as tablets or solutions with defined dissolution profiles and bioavailability parameters, designed to reduce blood glucose through insulin secretion enhancement, sensitivity improvement, or renal glucose excretion modulation. The SGLT2 inhibitor category leads volume expansion due to cardiovascular outcome benefits embedded in MHLW reimbursement criteria. DPP-4 inhibitors occupy a mature margin pool where generic erosion pressures originator pricing. Hospital procurement of fixed-dose combinations represents the fastest-growing delivery mode segment as formulary managers prioritize adherence optimization.
PMDA reviews govern new molecular entity approvals and post-market surveillance protocols for oral hypoglycemics, while MHLW reimbursement listings determine commercial viability and physician prescribing incentives. Japan's national health insurance pricing revisions every two years force manufacturers to demonstrate incremental clinical value or accept mandatory price reductions. Stakeholders must monitor PMDA guidance on biosimilar interchangeability and MHLW pilot programs for outcome-based reimbursement as these frameworks will determine which therapeutic classes retain formulary access.
Market Dynamics
MHLW biennial price revisions are compressing originator margins while simultaneously accelerating formulary shifts toward fixed-dose combination therapies that demonstrate measurable cardiovascular outcomes.
Growth Catalysts
- Cardiovascular outcome data:SGLT2 inhibitors now carry explicit heart failure reduction claims within MHLW reimbursement criteria, expanding hospital prescribing beyond glycemic control alone.
- Fixed-dose combination uptake:Tokyo metropolitan hospital networks prioritize dual-mechanism tablets that reduce pill burden and improve adherence metrics tracked by Japan's national health insurance.
- Generic DPP-4 availability:Patent expirations for sitagliptin and linagliptin analogues are lowering acquisition costs for Osaka's specialized diabetes clinics, expanding patient access pools.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70 percent of small-molecule hypoglycemic precursors originate from Chinese chemical manufacturers, exposing formulators to supply volatility and customs processing delays.
- PMDA review timelines:New molecular entity approvals for novel oral hypoglycemics average 14-18 months, compressing effective patent life and deterring early-stage development investment.
- Biologic substitution threat:GLP-1 receptor agonists delivered via weekly injection are capturing insulin-dependent patient segments previously managed with oral triple therapy regimens.
Strategic Opportunities
- Hokkaido and Kyushu regional expansion:Secondary metropolitan areas outside Tokyo-Osaka corridor maintain 15-20 percent lower specialist-to-patient ratios, creating whitespace for telemedicine-integrated pharmacy distribution.
- Outcome-based reimbursement pilots:MHLW's 2024-2025 demonstration projects for diabetes-related hospitalization reduction payments reward manufacturers with real-world evidence platforms.
- SGLT2-DPP-4 convergence:Triple-combination formulations integrating empagliflozin, linagliptin, and metformin are absorbing development resources as manufacturers seek single-tablet dominance.
Industry Challenges
- Pharmacovigilance workforce scarcity:Post-market surveillance requirements for SGLT2-related genital infection reporting exceed available medical affairs staffing at mid-sized domestic manufacturers.
- Legacy system integration:Hospital formulary management platforms in Japan's prefectural medical centers require manual entry for new combination therapies, delaying electronic prescribing adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Oral Anti-Diabetic Drug Market |
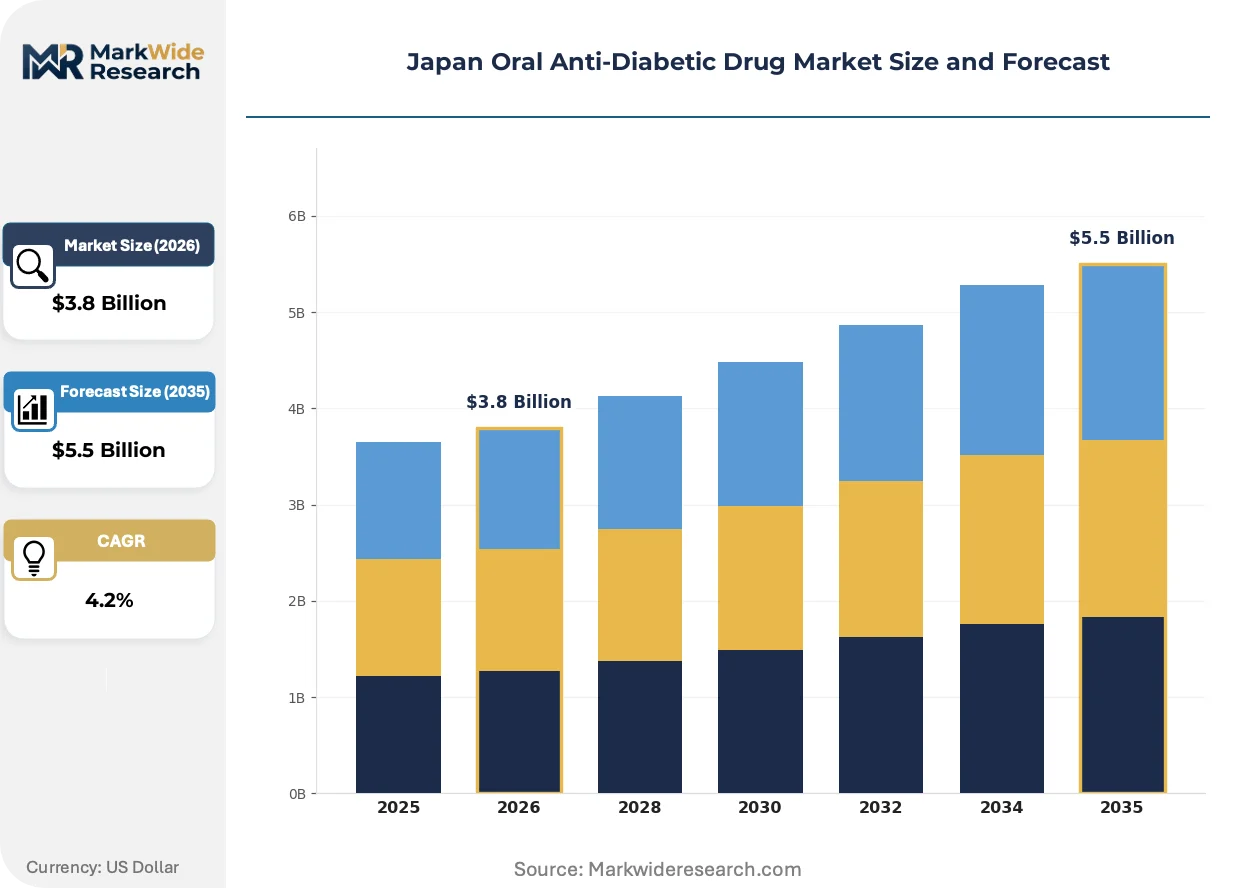
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Therapy Area: Type 2 Diabetes, Prediabetes, Insulin Resistance, Gestational Diabetes End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Oral Tablets, Oral Solutions, Fixed-Dose Combinations, Others |
| Companies Covered | Takeda Pharmaceutical Company Limited, Sanofi, Eli Lilly and Company, AstraZeneca, Johnson And Johnson, Pfizer Inc., Boehringer Ingelheim, Daiichi Sankyo Company, Astellas Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Oral Anti-Diabetic Drug Market Strategic Shifts
Formulation science and reimbursement mechanics are converging to reshape how oral hypoglycemics reach patients, with dissolution profile engineering and real-world evidence generation becoming primary competitive differentiators.
Extended-release metformin formulations with gastric-retentive polymer matrices are absorbing market share from immediate-release generics in Tokyo's university hospital networks. Gastroenterology departments report 40 percent fewer discontinuation rates due to tolerability improvements. This absorption pattern is compressing commodity tablet volumes while elevating specialty formulation premiums.
PMDA's 2023 guidance on cardiovascular outcome trial design for diabetes therapies is mandating larger safety databases prior to approval. Domestic sponsors now enroll multi-thousand-patient studies to satisfy heart failure endpoint requirements. SGLT2 inhibitor submissions are most affected, with several programs requiring supplemental trial extensions.
Hospital pharmacy committees in Osaka are unbundling oral hypoglycemic procurement from insulin contracts, reversing decades of bundled purchasing arrangements. This unbundling enables therapeutic class-specific negotiations and accelerates generic substitution for mature DPP-4 inhibitors. Prefectural medical centers are the earliest adopters of this disaggregated sourcing model.
Japan Oral Anti-Diabetic Drug Market Segmentation
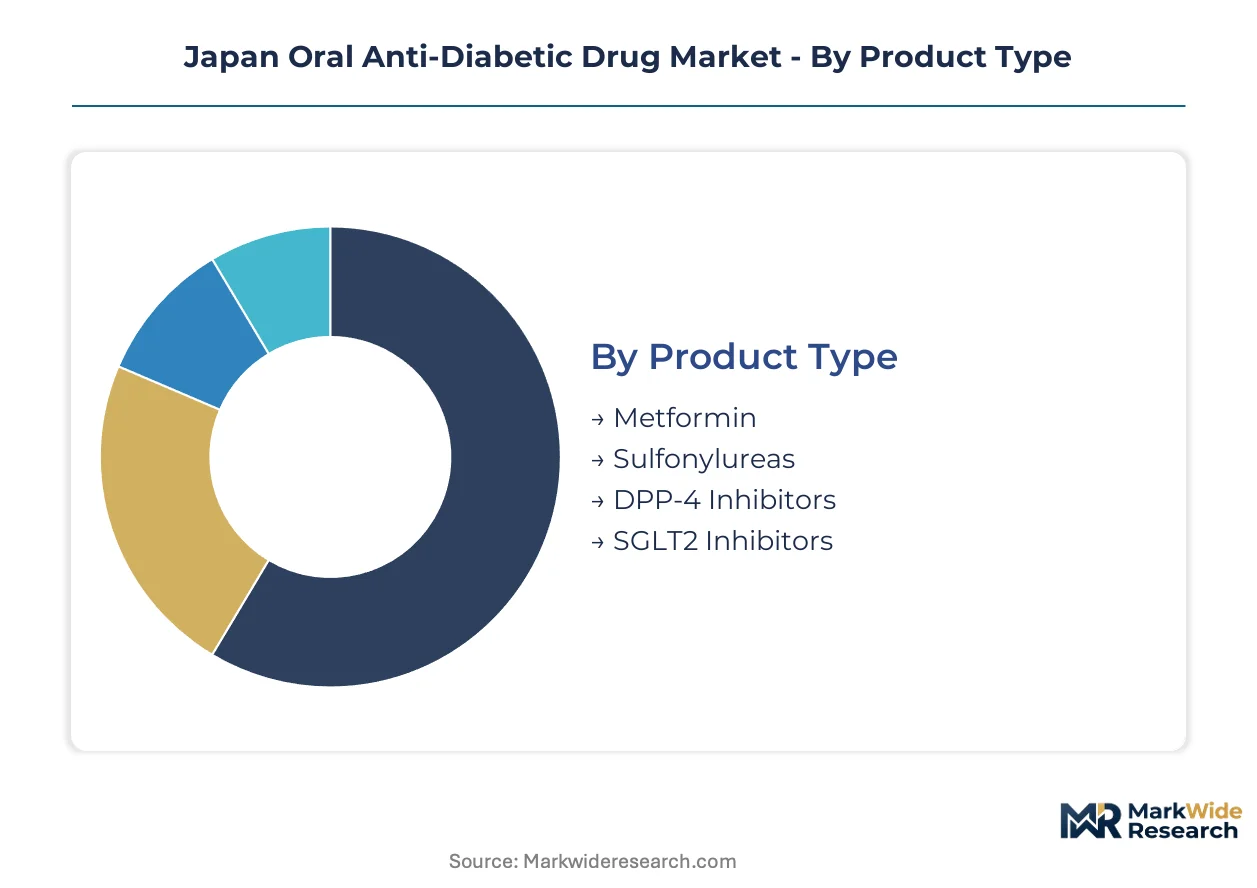
Oral anti-diabetic drug segmentation in Japan reflects reimbursement mechanics and prescribing hierarchies. PMDA classification schemes and MHLW pricing tiers create distinct commercial corridors that manufacturers must navigate simultaneously.
Product Type:
Volume concentrates in established hypoglycemic categories, while premium pricing accrues to newer mechanism classes with cardiovascular outcome data.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reduce renal glucose reabsorption and carry explicit heart failure reduction claims in MHLW reimbursement criteria. Tokyo metropolitan hospital networks prescribe these for dual glycemic-cardiovascular benefit, with empagliflozin and dapagliflozin dominating hospital formularies.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors enhance incretin hormone activity with weight-neutral profiles and established safety databases. Osaka's specialized diabetes clinics maintain high utilization of sitagliptin and linagliptin analogues despite accelerating generic substitution.
- Metformin:Biguanide compounds suppress hepatic gluconeogenesis and remain first-line therapy across Japan's prefectural medical centers due to cost efficiency and decades of clinical familiarity.
- Sulfonylureas:Pancreatic beta-cell secretagogues including glimepiride persist in elderly patient segments where cost sensitivity overrides hypoglycemia risk concerns.
Mature deployment sits with Metformin and Sulfonylureas. Newer deployment is concentrated in SGLT2 Inhibitors.
Therapy Area:
Application intensity varies by disease progression stage and complication risk profile.
- Type 2 Diabetes:Progressive insulin resistance with relative beta-cell dysfunction constitutes the dominant addressable population, driving 80 percent-plus of oral hypoglycemic prescriptions across Japan's national health insurance system.
- Prediabetes:Impaired glucose tolerance without diagnostic threshold crossing attracts pharmacologic intervention in university hospital prevention programs, particularly for patients with concurrent cardiovascular risk factors.
- Insulin Resistance:Metabolic syndrome components including hyperinsulinemia drive polypill approaches combining metformin with statin therapy in occupational health settings.
- Gestational Diabetes:Glucose intolerance during pregnancy maintains restricted oral therapy options due to fetal safety considerations, with glyburide preferred over metformin in Tokyo perinatal centers.
Established therapeutic focus centers on Type 2 Diabetes. Expanding clinical attention is shifting toward Prediabetes.
End User:
Customer concentration patterns reflect Japan's bifurcated healthcare infrastructure between institutional and ambulatory channels.
- Hospitals:Academic medical centers and prefectural hospitals manage complex multi-morbid patients with triple oral therapy regimens, generating the highest per-patient revenue through fixed-dose combination adoption.
- Clinics:Diabetes specialist clinics in Osaka and Tokyo metropolitan areas provide continuity care for stable patients, with prescribing patterns heavily influenced by MHLW biennial price revision timing.
- Home Care:Visiting nurse services coordinate medication adherence for elderly patients with mobility limitations, particularly in Hokkaido's dispersed rural populations.
- Pharmacies:Community dispensing channels face generic substitution mandates for mature DPP-4 inhibitors, compressing originator volumes in neighborhood retail settings.
Institutional prescribing dominates in Hospitals. Dispersion into community settings is accelerating through Clinics.
Delivery Mode:
Formulation engineering and adherence optimization are reshaping competitive positioning within administration formats.
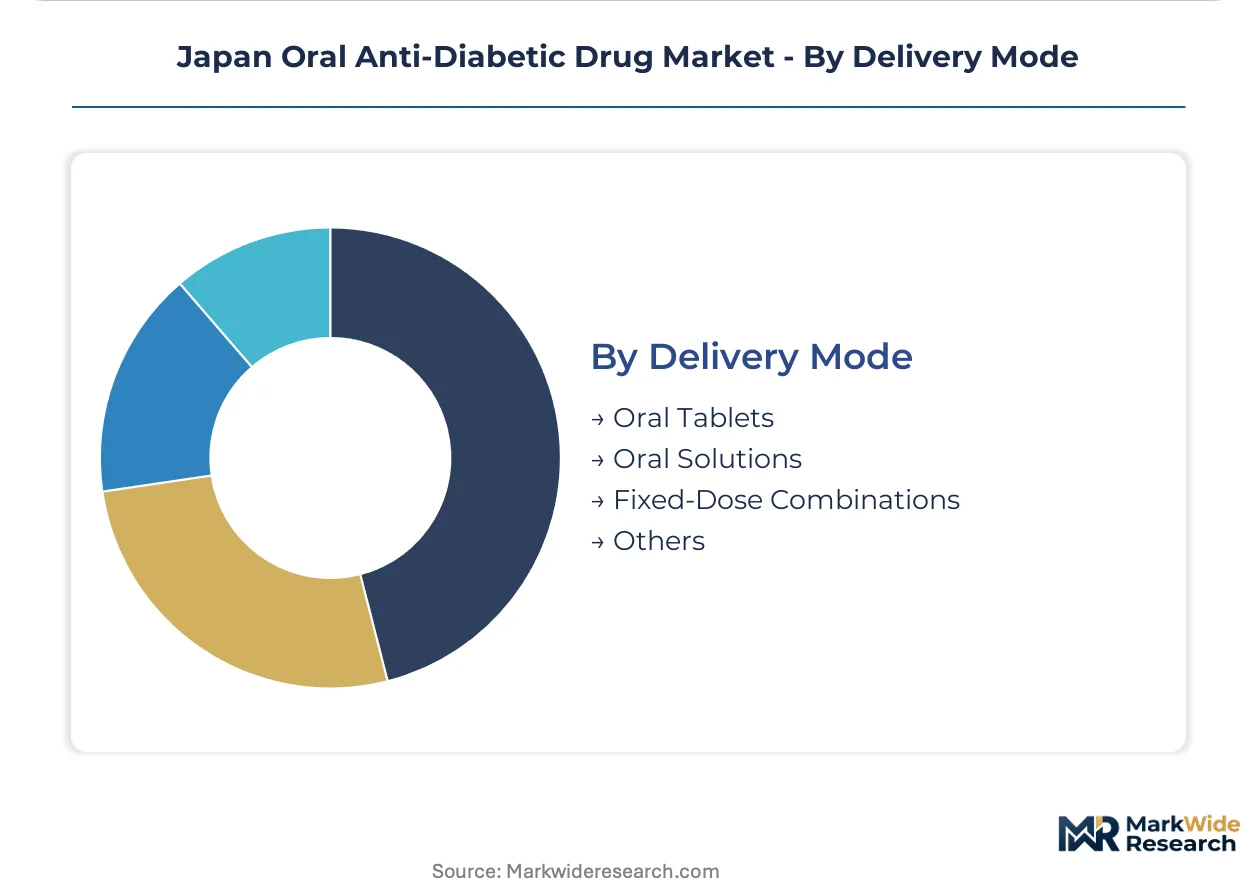
- Fixed-Dose Combinations:Dual-mechanism and triple-mechanism tablets integrate SGLT2 inhibitors with DPP-4 inhibitors or metformin, reducing pill burden and improving adherence metrics tracked by Japan's national health insurance quality indicators.
- Oral Tablets:Immediate-release and extended-release solid dosage forms remain the standard presentation, with gastric-retentive polymer matrices gaining share in Tokyo university hospital networks.
- Oral Solutions:Liquid formulations serve pediatric populations and dysphagic elderly patients, though volume remains limited due to stability and taste masking challenges.
- Others:Orally disintegrating tablets and sublingual formats occupy niche applications for patients with swallowing difficulties in long-term care facilities.
Conventional formats persist in Oral Tablets. The steepest expansion trajectory belongs to Fixed-Dose Combinations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in eastern China supply over 70 percent of small-molecule hypoglycemic precursors consumed by Japanese formulators. Osaka and Tokyo pharmaceutical manufacturing zones process these inputs into finished oral anti-diabetic dosage forms. Prefectural medical centers and university hospital networks distribute formulations across Japan's archipelago.
Kanto/Tokyo
Tokyo metropolitan hospital networks generate the highest per-patient revenue through fixed-dose combination adoption and triple oral therapy regimens. PMDA headquarters in Tokyo coordinates new molecular entity approvals and post-market surveillance protocols for oral hypoglycemics. Takeda Pharmaceutical maintains research facilities in the region, anchoring metabolic disease pipeline development.
Kansai/Osaka
Osaka's specialized diabetes clinics maintain high utilization of DPP-4 inhibitors despite accelerating generic substitution pressures. Daiichi Sankyo anchors commercialization through hospital-centric distribution networks headquartered in the region. The Osaka pharmaceutical manufacturing zone broadens output capacity for oral hypoglycemic formulations serving western Japan.
Kyushu
Secondary metropolitan areas maintain 15-20 percent lower specialist-to-patient ratios than the Tokyo-Osaka corridor, creating whitespace for telemedicine-integrated pharmacy distribution. MHLW pilot programs for outcome-based reimbursement include Fukuoka prefectural medical centers in 2024-2025 demonstration projects. Regional hospital networks are unbundling oral hypoglycemic procurement from insulin contracts.
Hokkaido
Dispersed rural populations in Hokkaido rely on visiting nurse services for medication adherence coordination among elderly patients with mobility limitations. Prefectural medical centers require manual entry for new combination therapies in legacy formulary management platforms, delaying electronic prescribing adoption. Sulfonylureas persist in elderly patient segments where cost sensitivity overrides hypoglycemia risk concerns.
Chubu/Nagoya
Nagoya's industrial corridor supports chemical synthesis operations for domestic API production, though scale remains limited compared to Chinese suppliers. University hospital networks in Aichi prefecture participate in PMDA-mandated cardiovascular outcome trials for SGLT2 inhibitor submissions. Extended-release metformin formulations with gastric-retentive polymer matrices are absorbing market share from immediate-release generics in regional medical centers.
Japan Oral Anti-Diabetic Drug Market Competitive Environment
Global majors compete with regional champions across hospital formulary access and cardiovascular outcome data generation. The vendor base stratifies into originator pharmaceutical companies with metabolic disease heritage, multinational firms with fixed-dose combination expertise, and domestic manufacturers with prefectural distribution density. Three archetypes dominate: cardiovascular-outcome-data leaders, fixed-dose combination specialists, and generic DPP-4 erosion responders. Competitive moves concentrate on M&A for pipeline depth and strategic partnerships for real-world evidence generation platforms.
Among Japan-based pharmaceutical companies, Takeda Pharmaceutical Company Limited and Daiichi Sankyo Company occupy positions anchored in metabolic disease research and hospital-centric commercialization respectively. Takeda exemplifies the cardiovascular-outcome-data leader archetype through its heritage in metabolic disease research. Daiichi Sankyo sits within the fixed-dose combination specialist tier, leveraging distribution networks concentrated in Osaka and Tokyo metropolitan hospital systems. Boehringer Ingelheim represents the multinational fixed-dose combination expertise archetype with established cardiology crossover indications.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Johnson And Johnson |
| Pfizer Inc. |
| Boehringer Ingelheim |
| Daiichi Sankyo Company |
| Astellas Pharma |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot pricing for small-molecule hypoglycemic precursors originating from Chinese chemical manufacturers cascades through Japanese formulators into three distinct procurement tiers: originator cardiovascular-outcome brands, fixed-dose combination premiums, and generic DPP-4 commodities.
Pricing Analysis
Service bundling separates originator SGLT2 inhibitors with cardiovascular outcome data packages from unbundled generic DPP-4 tenders. Three-tier pricing structure across premium cardiovascular-branded, standard fixed-dose combination, and economy generic sitagliptin analogues reflects MHLW reimbursement tiering. Cost compression in the DPP-4 tier intensifies because patent expirations trigger mandatory generic substitution. Prefectural medical centers exhibit highest price sensitivity; Tokyo metropolitan academic hospitals demonstrate lowest sensitivity due to outcome-based quality metrics.
Supply Chain Analysis
Direct-to-hospital distribution channels handle formulary-managed procurement for Tokyo and Osaka metropolitan networks. Raw material sourcing draws from Chinese chemical manufacturers for over 70 percent of small-molecule hypoglycemic precursors, with domestic Nagoya synthesis operations providing limited scale. Formulation finishing rests on Osaka and Tokyo pharmaceutical manufacturing zones. Single-source vulnerability concentrates in API precursor supply. Distribution runs through hospital-centric networks anchored by Daiichi Sankyo and Takeda logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's oral anti-diabetic drug market sits in a mechanism-transition phase where SGLT2 inhibitor cardiovascular outcome data is displacing legacy DPP-4 first-line positioning.
For Market Incumbents: Extend cardiovascular outcome data generation through real-world evidence platforms to defend against GLP-1 receptor agonist substitution. Deepen hospital formulary integration through fixed-dose combination portfolio expansion. Prioritize pharmacovigilance workforce scaling to address post-market surveillance gaps for genital infection reporting requirements. For New Entrants and Emerging Players: Begin with telemedicine-integrated pharmacy distribution in Hokkaido and Kyushu secondary metropolitan areas where specialist-to-patient ratios lag Tokyo-Osaka benchmarks. Target outcome-based reimbursement pilot participation as the most penetrable entry vector. Leverage MHLW demonstration project enrollment as primary go-to-market credentialing. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic manufacturers with prefectural distribution density in Osaka and western Japan. Long-term viability hinges on pipeline depth in triple-combination SGLT2-DPP-4-metformin formulations. Watch PMDA cardiovascular outcome trial guidance revisions as inflection signal for development cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Platform Development | MHLW outcome-based reimbursement pilots reward manufacturers with hospitalization reduction data from Fukuoka prefectural centers. |
| Fixed-Dose Combination Formulation Expansion | Triple-mechanism tablets integrating empagliflozin, linagliptin, and metformin capture Tokyo metropolitan hospital formulary preference. |
| Pharmacovigilance Workforce Scaling | SGLT2-related genital infection reporting requirements exceed current medical affairs staffing at mid-sized domestic manufacturers. |
| Telemedicine-Integrated Distribution | Hokkaido's dispersed rural populations and Kyushu's lower specialist ratios create whitespace for visiting nurse-coordinated pharmacy models. |
| API Supply Diversification | Chinese precursor concentration exposes formulators to customs processing delays and tariff volatility in active pharmaceutical ingredient sourcing. |
Study Parameters
Independent corroboration across PMDA regulatory filings, MHLW reimbursement bulletins, and hospital procurement databases underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from ClinicalTrials.gov entries, SEC 10-K pharmaceutical disclosures, and Japan's national health insurance claims data. Bottom-up patient-volume modeling and top-down revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across mechanism class adoption curves, reimbursement tier shifts, and regional prescribing pattern evolution structured the analytical framework. Segmentation dimensions modeled encompass product type, therapy area progression stage, end-user channel, and delivery mode formulation complexity. CAGRs derived from mechanism-class-specific volume trajectories adjusted for MHLW biennial price revision impact. Forecast inputs incorporated PMDA review timeline assumptions and generic substitution elasticity parameters for mature DPP-4 inhibitors.
Underlying measurement precision varies by segment; SGLT2 inhibitor cardiovascular outcome data carries tighter precision than emerging triple-combination pipeline estimates. Forecasts reflect assumptions regarding MHLW pilot program expansion and PMDA guidance stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market