
 Canada Self-Monitoring Blood Glucose Market | 2026-2036
Canada Self-Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Self-Monitoring Blood Glucose Market Outlook
Home care patients are reorganizing procurement priorities within the Canada Self-Monitoring Blood Glucose Market as provincial programs shift reimbursement toward outpatient management. Abbott Diabetes Care leverages its FreeStyle platform to dominate pharmacy and direct-to-patient channels across Ontario and British Columbia. Roche Diabetes Care sustains hospital and clinic relationships through integrated glucose data systems that anchor its institutional presence. Ascensia Diabetes Care competes on meter accuracy standards and wireless connectivity features that appeal to tech-enabled patient segments.
Self-monitoring blood glucose encompasses portable electrochemical or photometric devices that measure capillary glucose concentration from whole blood samples, typically requiring test strips with enzyme-coated electrodes and lancing devices producing microliter blood volumes for diabetic metabolic tracking. Blood glucose meters and test strips constitute the core revenue pool where repeat consumable purchases generate recurring margin, while continuous glucose monitoring and smart devices represent the fastest-expanding technology tier as Bluetooth-enabled systems and smartphone integration attract younger patient demographics seeking real-time glycemic visibility without manual logging.
Health Canada regulates glucose monitoring devices as Class II or III medical devices under the Medical Devices Regulations, requiring pre-market licensing and ISO 15197 accuracy compliance before commercial distribution. The country's national pharmaceutical regulator enforces post-market surveillance and adverse event reporting that shapes product liability exposure and design iteration cycles for manufacturers. Provincial formularies and reimbursement schedules from Ontario's Assistive Devices Program and comparable Quebec frameworks determine patient out-of-pocket costs and brand accessibility. Stakeholders must monitor evolving digital health integration standards and interoperability requirements as remote patient monitoring expands beyond traditional clinic boundaries.
Market Dynamics
Provincial reimbursement frameworks are accelerating the migration of glucose monitoring from institutional settings to home-based care, restructuring procurement flows and channel economics across Canadian healthcare networks.
Growth Catalysts
- Ontario's Assistive Devices Program:Expanded coverage for blood glucose meters and test strips reduces patient out-of-pocket costs and stimulates volume demand in Canada's most populous province.
- Bluetooth-enabled meter adoption:Wireless data transmission to smartphone applications attracts younger diabetic patients seeking seamless glycemic tracking without manual logbooks.
- Quebec's aging demographic concentration:Elevated Type 2 diabetes prevalence among seniors aged 65-plus sustains recurring consumable purchases across retail pharmacy networks.
Market Restraints
- Test strip cost structure:Enzyme-coated electrode materials and precision manufacturing requirements maintain elevated per-unit pricing that constrains patient compliance among uninsured segments.
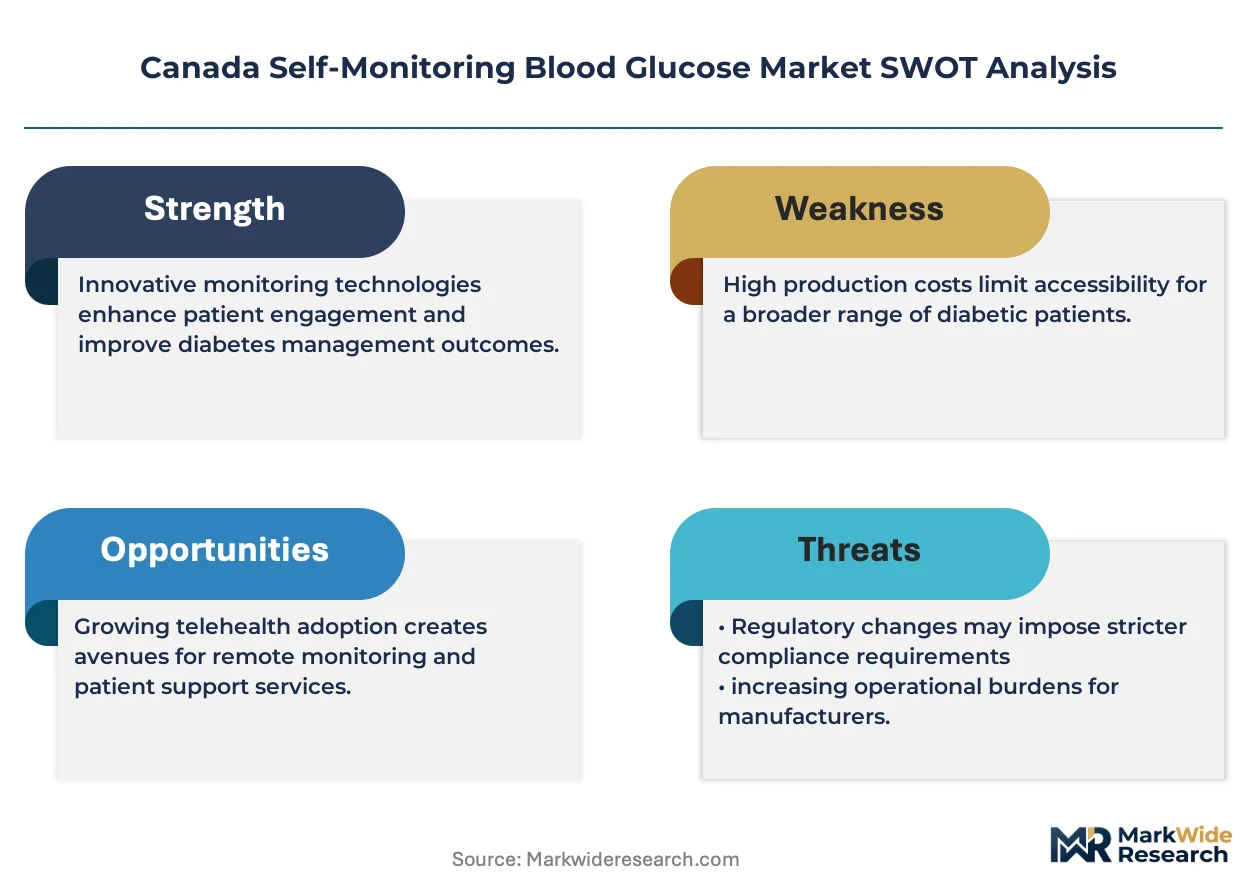
- Continuous glucose monitoring substitution:Factory-calibrated CGM systems eliminate fingerstick requirements for many Type 1 patients, compressing addressable market for traditional SMBG in high-dependency user groups.
- Health Canada Class II/III licensing timelines:Pre-market submission requirements and ISO 15197 accuracy validation extend product commercialization cycles by 18-24 months for novel meter entrants.
Strategic Opportunities
- British Columbia's underpenetrated rural corridors:Remote patient monitoring integration creates whitespace for pharmacy-delivered glucose management programs outside Vancouver and Victoria metropolitan zones.
- Remote patient monitoring convergence:Integration of SMBG data with provincial electronic health records enables population-level glycemic surveillance and value-based reimbursement pilots.
- Direct-to-patient subscription channels:Recurring strip delivery models bypass traditional pharmacy procurement and capture patient lifetime value through automated replenishment workflows.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in electrochemical biosensor design and miniaturization concentrates among a limited pool of Ontario and Quebec research institutions.
- Legacy hospital information system integration:Proprietary data formats from established glucose meter manufacturers create interoperability friction with emerging cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Self-Monitoring Blood Glucose Market |
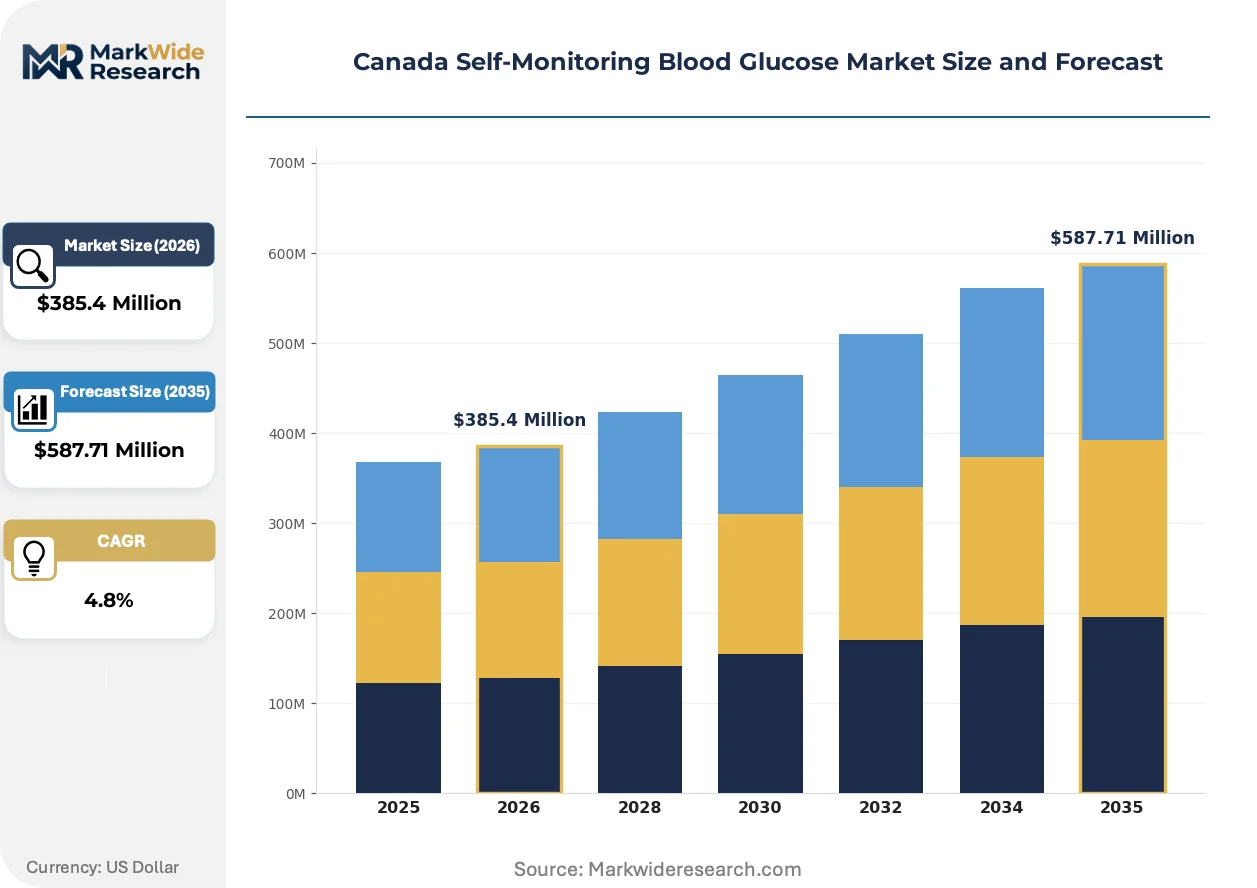
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Test Strips, Control Solutions, Lancing Devices Application: Home Care, Hospitals, Clinics, Diabetes Management Centers End User: Patients, Healthcare Professionals, Caregivers, Pharmacies Technology: Continuous Glucose Monitoring, Smart Devices, Conventional Meters, Wireless Connectivity |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, Ascensia Diabetes Care, LifeScan, Arkray, Trividia Health, Bionime Corporation, Agamatrix, Acon Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Self-Monitoring Blood Glucose Market Strategic Shifts
Digital health infrastructure investments are reconfiguring how glucose data flows between patients, clinicians, and payers, creating new value capture points beyond device hardware.
Connected meter ecosystems are fragmenting traditional market boundaries. Bluetooth-enabled devices transmit capillary glucose readings to paired smartphone applications, enabling real-time pattern recognition and automated insulin dosing recommendations. Younger Type 1 diabetic patients in urban Ontario and Quebec centers are adopting these systems at rates exceeding older demographics, compressing demand for standalone meters without wireless capabilities and forcing incumbents to retrofit legacy product lines with connectivity modules.
Health Canada's evolving guidance on software-as-a-medical-device is tightening oversight of glucose management applications. Regulatory clarification on algorithm-driven insulin dose calculators imposes additional validation requirements for manufacturers integrating decision-support features into companion apps. Companies pursuing AI-enabled glycemic prediction tools face extended licensing timelines, prompting some to segregate basic data logging from advanced analytics to accelerate market entry.
Pharmacy benefit managers in Ontario and Alberta are consolidating formulary decisions for provincial reimbursement programs. Centralized procurement of preferred meter brands reduces patient choice but secures volume commitments from manufacturers willing to accept compressed margins. Independent community pharmacies in Atlantic provinces resist this concentration by emphasizing clinical counseling services and personalized device training, differentiating on service intensity rather than product selection breadth.
Canada Self-Monitoring Blood Glucose Market Segmentation
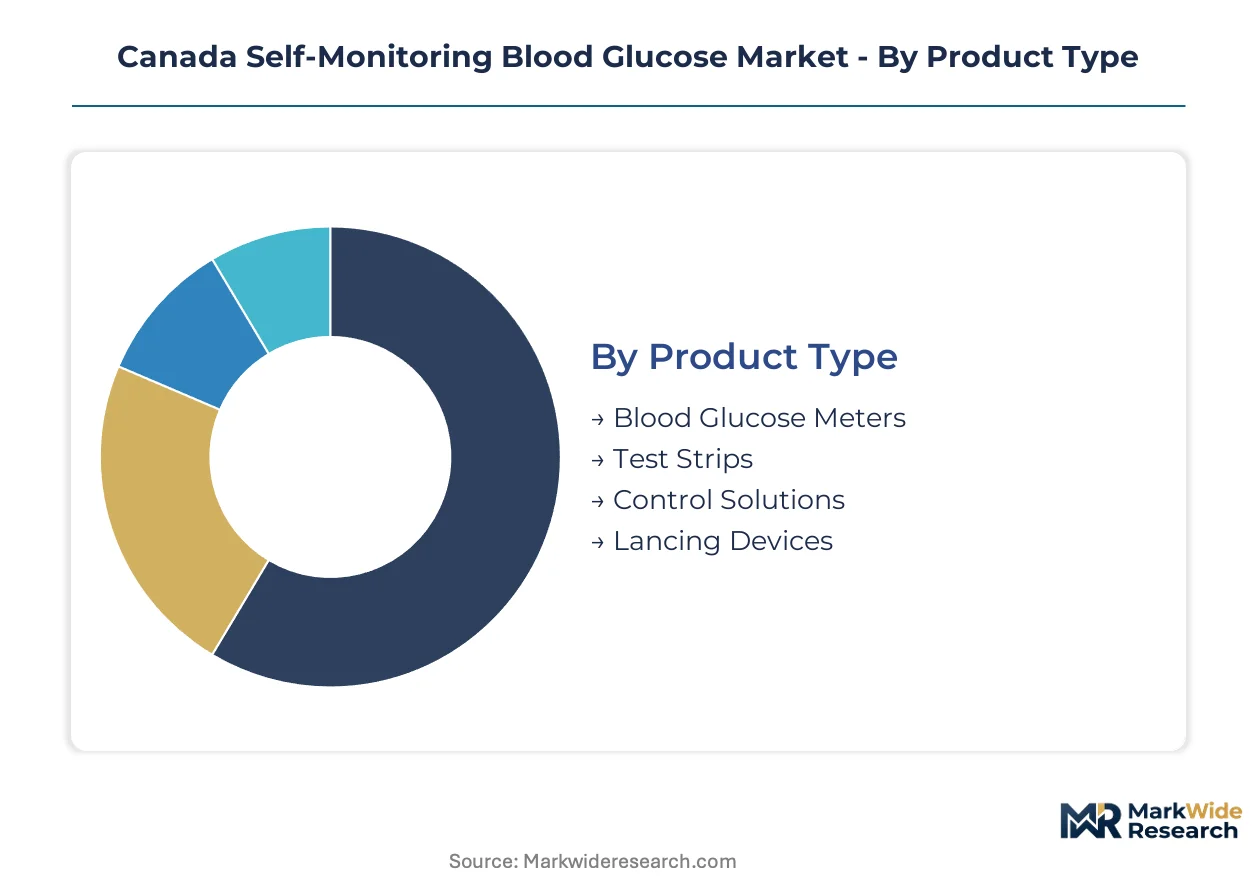
Segmentation in the Canada Self-Monitoring Blood Glucose Market reveals how provincial reimbursement structures and technology substitution pressures reshape competitive priorities across hardware, software, and service layers.
Product Type:
Continuous glucose monitoring systems exert the strongest substitution pressure on electrochemical consumables, forcing traditional meter manufacturers to defend strip-based revenue through connectivity retrofits and formulary lock-in contracts.
- Blood Glucose Meters:Portable electrochemical or photometric analyzers requiring ISO 15197 accuracy validation under Health Canada Class II licensing. Demand concentrates in Ontario's Assistive Devices Program channels where provincial procurement favors established brands with proven reimbursement codes. Bluetooth-enabled models from Abbott and Roche now dominate new prescriptions as pharmacies push connected ecosystems over standalone hardware.
- Test Strips:Enzyme-coated electrode consumables generating recurring revenue through repeat purchases tied to specific meter platforms. Quebec's aging demographic sustains the highest per-capita consumption rates among Canadian provinces, though CGM adoption among Type 1 patients under 40 compresses long-term volume trajectories in urban centers.
- Control Solutions:Glucose-specific calibrants verifying meter accuracy within clinical and home settings. Hospital laboratories in Toronto and Montreal anchor institutional demand for high-precision reference materials.
- Lancing Devices:Spring-loaded mechanisms producing microliter blood volumes for capillary sampling. Pain-minimizing designs from Ascensia and LifeScan retain loyalty among pediatric and geriatric segments despite CGM alternatives.
Test strips anchor the volume base while blood glucose meters gain share at the steepest rate through connectivity-enabled replacement cycles.
Application:
Cost tier stratification separates institutional procurement—where integrated data systems command premium pricing—from home care segments driven by provincial out-of-pocket subsidies and pharmacy discounting.
- Home Care:Patient-managed glucose monitoring supported by provincial reimbursement frameworks and pharmacy-delivered consumable programs. Ontario and Quebec lead adoption as expanded Assistive Devices Program coverage reduces financial barriers to daily testing compliance.
- Hospitals:Acute care settings requiring networked glucose data integration with electronic health records. Vancouver General Hospital and McGill University Health Centre anchor demand for enterprise-scale meter connectivity and centralized glycemic surveillance platforms.
- Clinics:Outpatient diabetes management facilities balancing point-of-care testing efficiency with patient education throughput. Endocrinology practices in Calgary and Ottawa prioritize meters with automated logbook generation to compress consultation documentation time.
- Diabetes Management Centers:Specialized facilities combining device training with nutritional counseling and insulin titration support. British Columbia's rural expansion of telemedicine-linked centers creates whitespace for remote glucose data interpretation services.
Home care settings anchor the volume base while diabetes management centers expand most quickly through provincial remote patient monitoring pilots.
End User:
Customer type fragmentation splits procurement authority between patients exercising formulary-constrained choice, healthcare professionals prescribing specific platforms, and pharmacies controlling fulfillment economics.
- Patients:Individual diabetics selecting meters based on provincial coverage, out-of-pocket strip costs, and smartphone integration preferences. Younger Type 1 patients in Toronto and Vancouver prioritize Bluetooth-enabled systems with automated insulin dose logging.
- Healthcare Professionals:Endocrinologists, primary care physicians, and diabetes educators prescribing specific meter brands through formulary relationships. Prescription influence concentrates in Quebec where mandatory physician involvement in Assistive Devices Program applications shapes brand selection.
- Caregivers:Family members and home health aides managing glucose testing for elderly or disabled patients. Simplified meter interfaces with large displays and audio feedback dominate this segment in Atlantic Canada where informal care networks are strongest.
- Pharmacies:Retail dispensaries controlling meter distribution and strip fulfillment through preferred vendor contracts. Shoppers Drug Mart and London Drugs anchor centralized procurement in Ontario and British Columbia, respectively.
Patients anchor the volume base while pharmacies climb the fastest as direct-to-patient subscription models bypass traditional clinic prescribing channels.
Technology:
Maturity gradients separate factory-calibrated continuous systems from electrochemical meters requiring manual intervention, with wireless connectivity serving as the pivot point for generational replacement demand.
- Continuous Glucose Monitoring:Factory-calibrated interstitial glucose sensors eliminating fingerstick requirements for many Type 1 patients. Dexcom and Medtronic systems face Health Canada Class III licensing timelines but capture insulin-dependent users in Alberta and Ontario seeking real-time trend alerts.
- Smart Devices:Bluetooth-enabled meters and smartphone-integrated platforms automating data logging and pattern recognition. Abbott's FreeStyle Libre ecosystem dominates this tier through pharmacy-direct patient acquisition in British Columbia and Quebec.
- Conventional Meters:Standalone electrochemical analyzers without wireless connectivity or app integration. Rural Atlantic Canada and uninsured patient segments sustain residual demand for low-cost, no-friction testing hardware.
- Wireless Connectivity:Data transmission modules enabling cloud-based glucose surveillance and remote clinician consultation. Provincial electronic health record integration pilots in Ontario and Alberta accelerate adoption among tech-enabled patient cohorts.
Conventional meters anchor the volume base while continuous glucose monitoring gains share at the steepest rate through Type 1 patient conversion and expanded private insurance coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway and CP Rail corridors bind provincial healthcare procurement networks, enabling glucose monitoring device distribution from Ontario manufacturing hubs to Atlantic and Prairie markets.
Ontario
Toronto's concentration of endocrinology practices and the Assistive Devices Program expansion drive meter procurement volumes. Health Canada's Class II medical device licensing requirements filter product entry through Ottawa's regulatory review pipelines. The Kitchener-Waterloo medical technology cluster anchors domestic distribution logistics for national pharmacy chains.
Quebec
Montreal's aging demographic profile sustains elevated Type 2 diabetes prevalence and recurring test strip consumption. The province's mandatory physician involvement in assistive device applications shapes brand prescribing patterns through McGill University Health Centre networks. Laval's pharmacy benefit consolidation centralizes formulary decisions for retail meter distribution.
British Columbia
Vancouver General Hospital's enterprise glucose data integration anchors institutional demand for networked monitoring systems. The province's rural telemedicine expansion creates procurement whitespace beyond Lower Mainland metropolitan zones. Victoria's diabetes management centers pilot remote patient monitoring linkages with provincial electronic health records.
Alberta
Calgary's outpatient endocrinology practices prioritize meters with automated logbook generation to compress clinical documentation workflows. The province's pharmacy benefit manager consolidation reduces patient choice while securing manufacturer volume commitments. Edmonton's remote patient monitoring pilots integrate SMBG data with value-based reimbursement frameworks.
Canada Self-Monitoring Blood Glucose Market Competitive Environment
Concentration sits with multinational medical device conglomerates that leverage integrated glucose data systems and pharmacy channel control to defend market position. The vendor base organizes around three strategic archetypes: platform ecosystem builders capturing direct-to-patient subscriptions, accuracy-focused specialists competing on ISO 15197 validation standards, and hospital-system integrators anchoring institutional procurement through electronic health record connectivity. Dominant competitive moves include formulary lock-in contracts with provincial pharmacy benefit managers and connectivity retrofits to legacy meter lines.
Among the platform ecosystem builders, Abbott Diabetes Care and Roche Diabetes Care occupy positions defined by wireless-enabled product architectures and pharmacy-direct patient acquisition channels. Ascensia Diabetes Care exemplifies the accuracy-specialist archetype through its positioning around meter precision standards and Bluetooth connectivity features. These three entities collectively represent the competitive core where provincial reimbursement frameworks and digital health integration requirements determine relative market access.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| Ascensia Diabetes Care |
| LifeScan |
| Arkray |
| Trividia Health |
| Bionime Corporation |
| Agamatrix |
| Acon Laboratories |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles for enzyme-coated electrode materials concentrate procurement leverage among three multinational suppliers, amplifying pricing power for test strip manufacturers while compressing margins for meter assemblers lacking backward integration into biosensor production. Health Canada's Class II/III licensing timelines extend supplier qualification periods, locking device makers into premium pricing for validated input streams.
Pricing Analysis
Volume-discount tiering structures stratify across provincial procurement contracts, pharmacy-direct subscriptions, and uninsured cash purchases. Pricing separates Bluetooth-enabled connected systems from conventional standalone meters based on software integration depth and Health Canada licensing tier. Cost compression in conventional meter segments intensifies as pharmacy benefit managers consolidate Ontario and Alberta formularies around preferred brands. Uninsured patients in Atlantic Canada exhibit highest price sensitivity, while hospital systems with integrated data requirements accept premium positioning for enterprise-scale glucose management platforms.
Supply Chain Analysis
Precision electrochemical sensor manufacturing concentrates in Germany, Japan, and the United States, creating single-source vulnerability for Canadian device assemblers seeking ISO 15197-validated electrode inputs. Test strip production draws from specialized polymer substrates, noble metal catalysts, and sterile packaging materials vulnerable to logistics chokepoints at Vancouver and Montreal port terminals. Distribution runs through pharmacy benefit manager networks in Ontario and Quebec, with Shoppers Drug Mart and London Drugs anchoring downstream fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Self-Monitoring Blood Glucose Market is recovering from CGM substitution pressure as provincial reimbursement frameworks stabilize demand for hybrid monitoring approaches. Cyclical recovery momentum rests on Ontario's Assistive Devices Program expansion and Quebec's aging demographic concentration.
For Market Incumbents: Secure formulary lock-in contracts with British Columbia's consolidating pharmacy networks before rural telemedicine expansion accelerates. Defend test strip revenue through connectivity retrofits that tether consumable purchases to proprietary data ecosystems, offsetting continuous glucose monitoring substitution among Type 1 patient segments. For New Entrants and Emerging Players: Differentiate on remote patient monitoring integration for Alberta's value-based reimbursement pilots. Target diabetes management centers in Atlantic Canada where informal caregiver networks sustain demand for simplified, large-display meter interfaces. Pursue direct-to-patient subscription channels bypassing pharmacy procurement concentration in Ontario and Quebec. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates seeking to divest non-core diabetes device portfolios amid CGM platform consolidation. Long-term viability favors accuracy-specialist manufacturers with Health Canada licensing momentum and Bluetooth-enabled product architectures. Watch for inflection signals in provincial electronic health record integration mandates that would accelerate smart device adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Licensing Pathway | Abbott's FreeStyle Libre ecosystem expansion depends on interstitial sensor validation timelines. |
| Provincial Reimbursement Strategy | Ontario's Assistive Devices Program coverage expansion directly determines addressable patient volumes. |
| Hospital System Partnership | Vancouver General Hospital's enterprise glucose data integration anchors institutional procurement decisions. |
| Software Companion Development | Bluetooth-enabled meter ecosystems require validated insulin dose calculator algorithms under Health Canada guidance. |
| Backward Integration into Biosensor Production | Ascensia's electrode manufacturing investments reduce dependency on German and Japanese precision sensor suppliers. |
Study Parameters
Cross-validation between hospital procurement database analysis and provincial formulary documentation anchors the qualitative findings on reimbursement-driven demand patterns. Primary interviews with endocrinologists, biomedical engineers, pharmacy benefit managers, and GPO contracts managers combined with secondary validation from Health Canada medical device licensing records, Ontario Assistive Devices Program utilization data, and hospital glucose management system procurement filings. Bottom-up patient population modeling and top-down provincial expenditure triangulation produced convergent volume estimates.
Sensitivity analysis across Bluetooth adoption curves, CGM substitution rates, and provincial reimbursement expansion scenarios tested forecast robustness. The analytical framework models product type, application setting, end user archetype, and technology tier dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by provincial demographic and reimbursement intensity differentials, with continuous glucose monitoring penetration curves and connected meter replacement cycles as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained provincial reimbursement commitment or accelerated Health Canada software-as-a-medical-device enforcement would require recalibration. Forecasts reflect documented assumptions regarding aging demographic trajectories and technology substitution elasticities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Thailand Diabetes Care Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Continuous Glucose Monitoring Market