
 Vaginal Inserts Market | 2026-2036
Vaginal Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Inserts Market Analytics
Subscription-based patient support programs is broadening what manufacturers sell beyond the physical insert. Bayer AG leverages its endocrinology heritage to sustain brand loyalty among gynecologists prescribing hormonal therapies. TherapeuticsMD, Inc. specializes in bioadhesive formulations that anchor its position in the menopausal health segment. Pfizer Inc. competes through manufacturing scale that controls unit economics across multiple delivery modes.
Vaginal inserts are solid or semi-solid dosage forms designed for intravaginal administration, typically comprising active pharmaceutical ingredients embedded in polymer matrices or bioadhesive gels that release drugs over controlled durations for local or systemic therapeutic effects. Hormonal inserts command the largest current revenue pool due to established menopausal and contraceptive applications, while bioadhesive materials represent the fastest-expanding material category as patients seek residue-free, comfort-optimized options. Gynecological clinics remain the dominant end-user channel for initial prescription and fitting, though home care delivery is gaining structural traction as telehealth protocols reduce in-person follow-up requirements.
The FDA's Center for Drug Evaluation and Research oversees insert safety and efficacy benchmarks, while the EMA's Committee for Medicinal Products for Human Use shapes parallel standards in Europe that manufacturers must satisfy for cross-border market access. The EPA's evolving scrutiny of polymer manufacturing byproducts is pressing suppliers toward greener synthesis pathways. Stakeholders must monitor how regulatory divergence between the FDA and EMA on sustained-release characterization could fragment development timelines and force geography-specific formulation investments.
Market Dynamics
Telehealth protocols are compressing the traditional gynecological clinic channel for initial fitting and follow-up, forcing manufacturers to redesign patient onboarding workflows and reimbursement documentation around remote care models.
Growth Catalysts
- EMA's MDR compliance pathways:The European Medicines Agency's streamlined device-drug combination reviews are accelerating cross-border approvals for polymer-based inserts, reducing redundant clinical trials across member states.
- Home care delivery infrastructure:Direct-to-patient fulfillment networks built around temperature-controlled logistics are expanding access routes beyond traditional pharmacy and clinic channels.
- Bioadhesive polymer platforms:Advanced mucoadhesive hydrogels that eliminate residue complaints are converting patients from conventional pessary and suppository formats.
Market Restraints
- Specialized polymer feedstock concentration:Medical-grade polycaprolactone and silicone suppliers cluster in Germany and the United States, creating single-source vulnerability for sustained-release matrix production.
- FDA's evolving characterization requirements:The Center for Drug Evaluation and Research's tightening dissolution profile standards for local delivery systems are extending reformulation cycles for existing products.
- Hormonal substitute competition:Transdermal patches and oral combination therapies retain formulary preference in several European national health systems, limiting insert penetration.
Strategic Opportunities
- India's CDSCO fast-track pathway:The Central Drugs Standard Control Organization's accelerated approval for menopausal therapies with established US or EU precedent creates a reduced-timeline entry route for hormonal inserts.
- Fertility preservation applications:Cryopreservation support protocols using luteal-phase hormonal support represent an emerging clinical use case beyond menopause management.
- Subscription-based adherence programs:Automated refill and telehealth check-in bundles are creating recurring revenue streams that decouple manufacturer economics from pure unit sales.
Industry Challenges
- Specialized formulation talent scarcity:Polymer scientists with combined expertise in controlled-release kinetics and vaginal mucosa biocompatibility command premium compensation, constraining R&D team scaling.
- Legacy ERP integration friction:Patient-specific lot tracking requirements for combination products clash with existing pharmaceutical manufacturing software architectures, forcing costly system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Inserts Market |
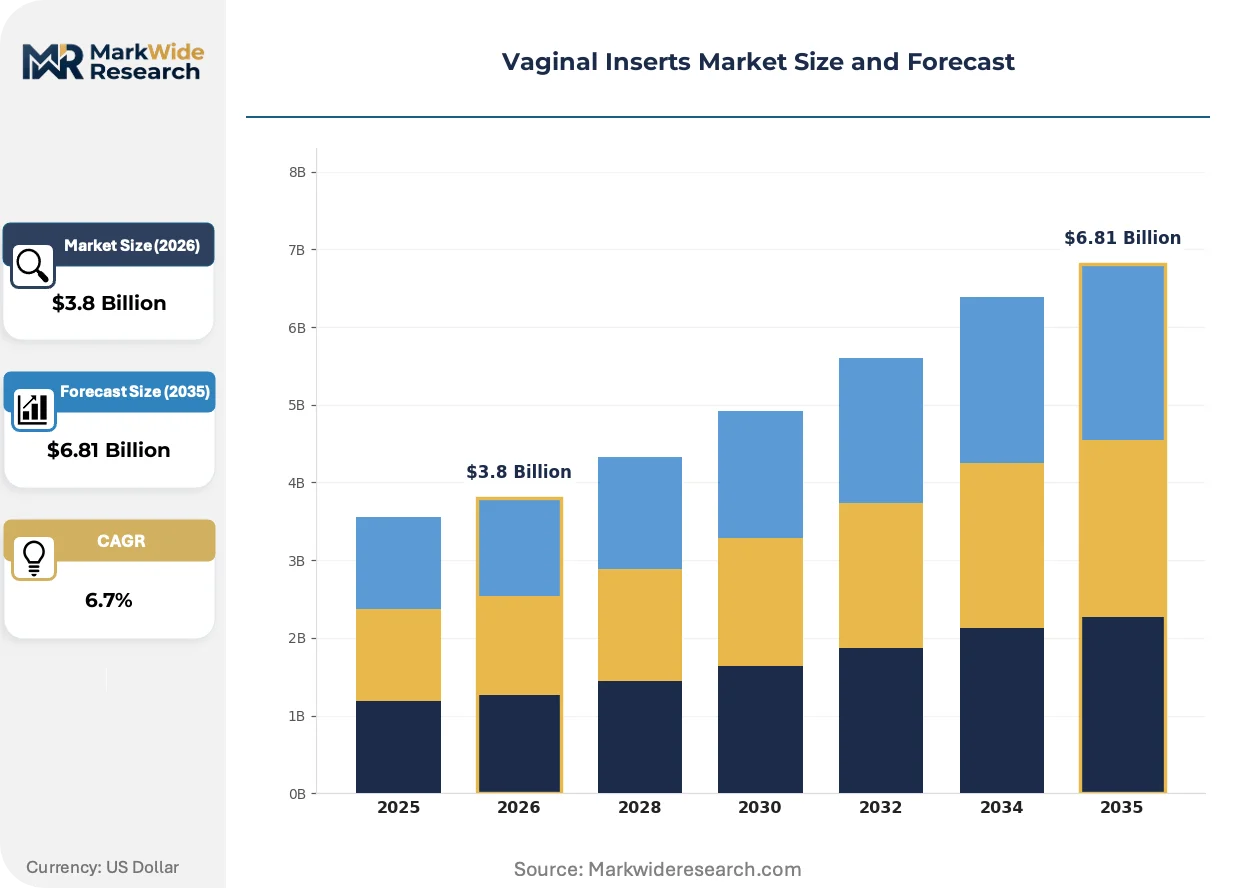
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotic Inserts, Hormonal Inserts, Antifungal Inserts, Moisturizing Inserts End User: Gynecological Clinics, Home Care, Pharmacies, Hospitals Delivery Mode: Intravaginal, Subdermal, Topical, Sustained Release Material: Ceramic, Polymer, Gel, Bioadhesive |
| Companies Covered | AbbVie Inc., Bayer AG, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Endo Pharmaceuticals Inc., TherapeuticsMD, Inc., Johnson & Johnson, Ferring Pharmaceuticals, Glenmark Pharmaceuticals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Inserts Market Evolving Landscape
Manufacturers are converging on patient-centric design priorities that prioritize comfort, discretion, and self-administration capability over purely clinical efficacy metrics, reshaping competitive differentiation.
Smart polymer matrices with embedded pH-responsive release triggers are unifying the functions of drug delivery and environmental sensing within single-insert architectures. Gynecological clinics in the United States are piloting these platforms for personalized estradiol dosing. This convergence is unifying previously separate diagnostic and therapeutic product categories into integrated menopausal management systems.
REACH authorization requirements for novel polymer monomers are tightening the toxicological data burden for European market entry. Manufacturers must now submit extended migration studies for all extractable compounds. Hormonal insert developers with legacy formulations face retrospective compliance costs that favor incumbents with established dossiers.
Patients are self-directing toward residue-free and odor-masking formulations, compressing tolerance for traditional suppository bases. Retail pharmacy channels in France and Germany report rising requests for bioadhesive alternatives that eliminate the need for nighttime dosing. This preference shift is most visible in private-pay segments where out-of-pocket sensitivity to product experience quality runs highest.
Vaginal Inserts Market Segmentation
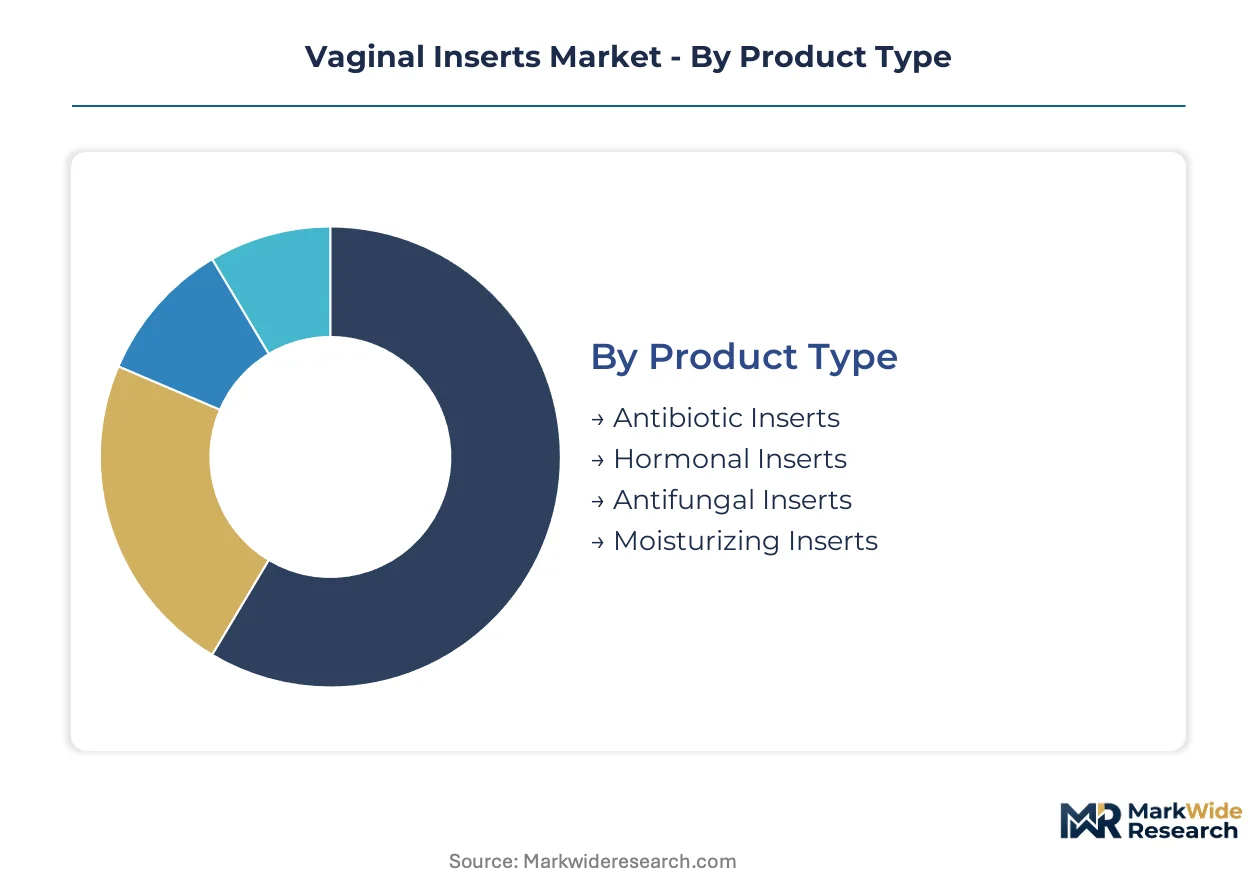
Segmentation in the vaginal inserts market reveals how supply chain configuration, clinical workflow integration, and patient self-administration preferences create distinct competitive arenas. Manufacturers must align formulation expertise, regulatory dossiers, and distribution infrastructure to specific segment requirements rather than pursuing undifferentiated coverage.
Product Type:
Supply concentration around polymer synthesis capabilities and hormonal API sourcing heavily favors established pharmaceutical manufacturers with captive endocrinology pipelines.
- Hormonal Inserts:Estradiol and progesterone matrices embedded in polycaprolactone or silicone platforms enable controlled systemic absorption for menopausal symptom management. Gynecological clinics in the United States prescribe these most frequently where reimbursement clarity supports sustained-release therapy adoption. FDA dissolution profile standards are tightening reformulation cycles for legacy products.
- Antibiotic Inserts:Clindamycin and metronidazole formulations target bacterial vaginosis with localized drug delivery that minimizes systemic exposure. Pharmacies in France and Germany stock these as first-line alternatives to oral regimens where patient compliance concerns arise. EMA MDR compliance pathways are accelerating cross-border approvals for polymer-based antibiotic platforms.
- Antifungal Inserts:Miconazole and clotrimazole matrices address recurrent vulvovaginal candidiasis through prolonged mucosal contact.
- Moisturizing Inserts:Hyaluronic acid and glycerin-based hydrators serve non-pharmacological vaginal atrophy management without prescription requirements.
Hormonal inserts absorb the bulk of installed capacity; moisturizing inserts are expanding most quickly as over-the-counter channels broaden access.
End User:
Cost tier differentiation separates premium clinical-fitted inserts from economy self-administered alternatives, with reimbursement status determining channel viability.
- Gynecological Clinics:Specialized fitting services and initial prescription authority for combination drug-device products concentrate patient acquisition here. Telehealth protocols are compressing traditional follow-up workflows and forcing manufacturers to redesign remote care documentation.
- Home Care:Direct-to-patient fulfillment networks with temperature-controlled logistics are expanding beyond traditional pharmacy channels. Subscription-based adherence programs with automated refill bundles are creating recurring revenue streams that decouple manufacturer economics from pure unit sales.
- Pharmacies:Retail pharmacy channels in France and Germany report rising patient requests for bioadhesive alternatives that eliminate nighttime dosing residue complaints.
- Hospitals:Acute care settings utilize inserts for perioperative antimicrobial prophylaxis and post-surgical hormonal support in oncology patients.
Gynecological clinics retain the dominant prescription volume; home care delivery is climbing the fastest as telehealth reduces in-person dependency.
Delivery Mode:
Application requirements dictate formulation complexity, with sustained-release platforms commanding premium pricing against immediate-release alternatives.
- Sustained Release:pH-responsive polymer matrices with embedded environmental sensing unify drug delivery and diagnostic functions within single-insert architectures. Gynecological clinics in the United States pilot these for personalized estradiol dosing.
- Intravaginal:Direct mucosal administration enables local therapeutic effects with minimized systemic exposure for hormone-sensitive patients.
- Subdermal:Pellet implants provide extended-duration hormonal delivery through alternative anatomical sites, competing for overlapping menopausal indications.
- Topical:Cream and gel formulations serve patients with insert tolerance issues or preference for external application.
Sustained release absorbs the bulk of R&D investment; intravaginal delivery is gaining share fastest as patient self-administration preferences strengthen.
Material:
Volume concentration in medical-grade polymer feedstock clusters in Germany and the United States, creating single-source vulnerability for sustained-release matrix production.
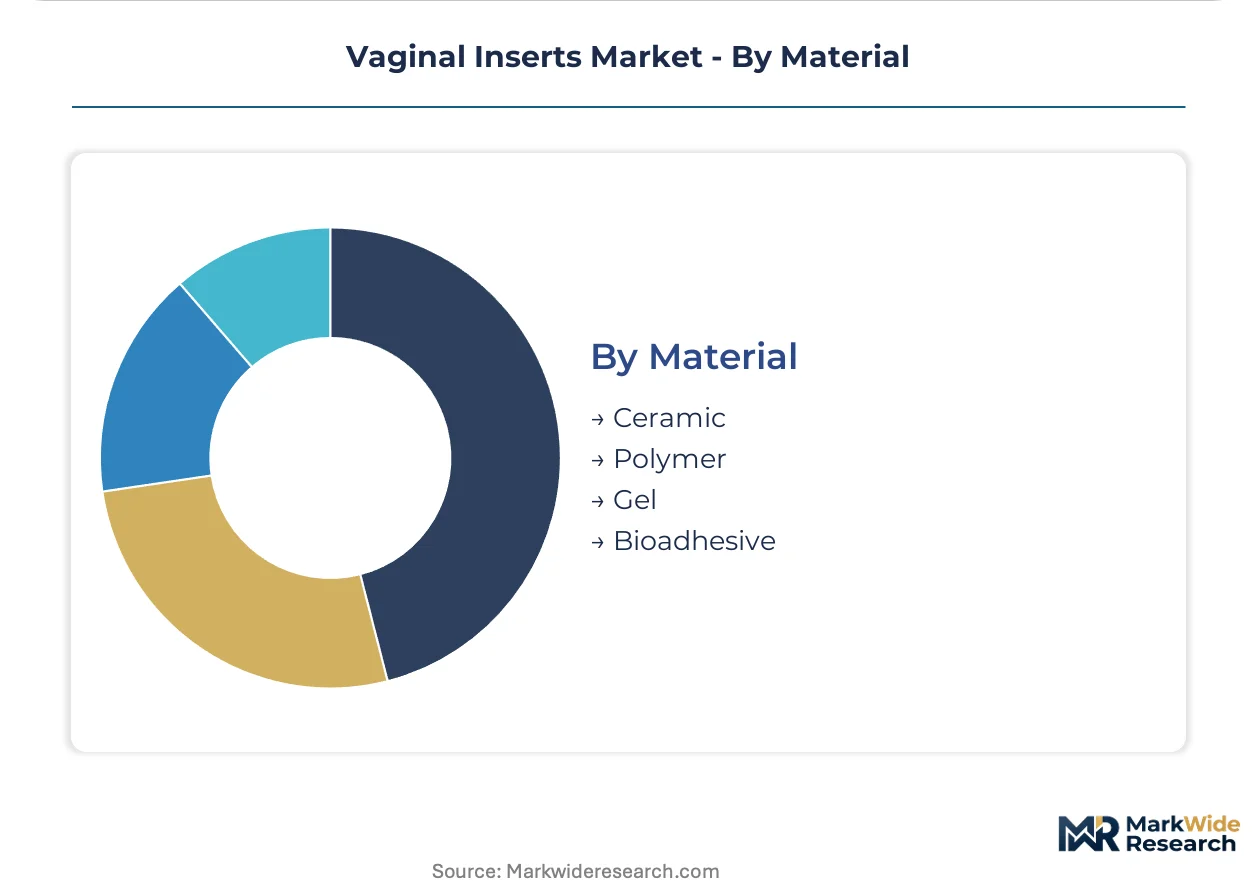
- Polymer:Polycaprolactone and silicone matrices dominate sustained-release hormonal applications with established biocompatibility dossiers. REACH authorization requirements for novel monomers are tightening toxicological data burdens for European market entry.
- Bioadhesive:Advanced mucoadhesive hydrogels eliminate residue complaints and convert patients from conventional pessary formats. Patients in private-pay segments self-direct toward these odor-masking, comfort-optimized alternatives.
- Gel:Semi-solid platforms enable rapid drug release and easier self-administration for acute symptom relief.
- Ceramic:Inert mineral matrices serve niche applications requiring extreme chemical stability or radio-opacity for imaging compatibility.
Polymer materials command the dominant production volume; bioadhesive platforms are expanding most quickly as residue-free formulations capture patient preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer synthesis clusters in Germany and the United States, while prescription volume concentrates in aging populations across North America and Western Europe. Consumption patterns diverge sharply between reimbursed clinical channels and private-pay direct-to-patient segments.
United States
Gynecological clinics in the United States generate the dominant prescription volume for sustained-release hormonal inserts as reimbursement clarity supports clinical uptake. The FDA's Center for Drug Evaluation and Research tightens dissolution profile standards for local delivery systems, extending reformulation cycles for legacy products. Boston and San Francisco medical corridors pilot pH-responsive polymer matrices with embedded environmental sensing for personalized estradiol dosing.
Germany
Medical-grade polycaprolactone and silicone suppliers cluster in Germany, creating feedstock concentration for sustained-release matrix production. REACH authorization requirements for novel polymer monomers tighten toxicological data burdens for European market entry, favoring incumbents with established dossiers. Frankfurt and Munich pharmaceutical corridors anchor polymer synthesis capabilities serving cross-border EMA MDR compliance pathways.
France
Retail pharmacy channels in France report rising patient requests for bioadhesive alternatives that eliminate nighttime dosing residue complaints. ANSM oversight of drug-device combination products shapes national formulary placement for hormonal therapies. Paris and Lyon metropolitan clusters concentrate gynecological specialist practices driving initial prescription authority.
India
The Central Drugs Standard Control Organization's accelerated approval pathway for menopausal therapies with established US or EU precedent creates reduced-timeline entry routes for hormonal inserts. Mumbai and Hyderabad pharmaceutical corridors expand contract manufacturing capacity for polymer-based formulations targeting export markets.
United Kingdom
Telehealth protocols compress traditional gynecological clinic channels for initial fitting and follow-up, forcing manufacturers to redesign remote care documentation. MHRA post-Brexit regulatory divergence from EMA standards creates parallel compliance requirements for sustained-release characterization. London and Cambridge medical technology clusters pilot subscription-based patient adherence programs with automated refill bundles.
Vaginal Inserts Market Competitive Landscape
Capital-heavy producers with captive polymer synthesis capabilities compete with asset-light formulation specialists outsourcing feedstock procurement. The market structure consolidates around pharmaceutical conglomerates with endocrinology heritage and mid-cap specialists with bioadhesive platform expertise. Three archetypes dominate: integrated polymer-to-pharma conglomerates, menopausal health specialists, and contract manufacturing organizations with controlled-release capabilities. Competitive moves concentrate on strategic partnerships for polymer feedstock security and geographic licensing for regulatory dossier leverage.
Within the integrated pharmaceutical tier, Bayer AG and Pfizer Inc. represent capital-scale incumbents leveraging manufacturing depth across multiple delivery modes. Among menopausal health specialists, TherapeuticsMD, Inc. occupies a position exemplifying bioadhesive formulation focus. These three anchors illustrate how competitive positioning splits between conglomerates optimizing unit economics and specialists capturing residue-free formulation preferences.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bayer AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Endo Pharmaceuticals Inc. |
| TherapeuticsMD, Inc. |
| Johnson & Johnson |
| Ferring Pharmaceuticals |
| Glenmark Pharmaceuticals Ltd |
| Others |
Value Network & Pricing Analysis
pH-responsive polymer matrices with embedded environmental sensing are compressing production timelines for legacy silicone-based inserts while concentrating premium pricing power among manufacturers with captive synthesis capabilities in Germany and the United States.
Pricing Analysis
Margin tightening in bioadhesive formulations reflects REACH authorization costs for novel monomers and the premium compensation commanded by polymer scientists with controlled-release expertise. Three-tier pricing structure across premium, standard, and economy levels separates pH-responsive smart matrices from conventional silicone inserts and commodity suppository bases. Cost compression in standard silicone tiers accelerates because of single-source feedstock vulnerability in German polycaprolactone suppliers. Private-pay patients in France and Germany exhibit highest price sensitivity to residue-free formulations, while reimbursed clinical channels in the United States absorb premium pricing for sustained-release hormonal platforms.
Supply Chain Analysis
Direct-to-patient fulfillment networks with temperature-controlled logistics handle growing home care demand, bypassing traditional pharmacy and clinic channels. Medical-grade polymer synthesis clusters in Germany, the United States, and increasingly India, with Mumbai and Hyderabad corridors expanding contract manufacturing for export markets. Production draws from specialized polycaprolactone, silicone, and advanced mucoadhesive hydrogel feedstocks. Single-source vulnerability in German medical-grade polymer suppliers creates structural risk for sustained-release matrix production. Distribution runs through gynecological clinics for initial prescription authority, supplemented by direct-to-patient subscription programs for refill adherence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaginal inserts market is transitioning from conventional silicone matrices to bioadhesive hydrogel platforms, with smart polymer architectures unifying diagnostic and therapeutic functions within single-insert designs.
For Market Incumbents: Anticipate margin compression in legacy silicone formulations as bioadhesive platforms capture patient preference in private-pay segments. Secure captive polymer feedstock through backward integration into German or United States synthesis corridors to defend against single-source vulnerability. Accelerate FDA dissolution profile compliance investments before tightening characterization standards extend reformulation cycles for existing hormonal products.
For New Entrants and Emerging Players: CDSCO's accelerated approval pathway in India opens a window for hormonal inserts with established US or EU precedent, enabling reduced-timeline entry into a high-volume export manufacturing hub. Target fertility preservation applications using luteal-phase hormonal support as an underpenetrated clinical use case beyond menopause management. Pursue subscription-based adherence program partnerships with telehealth platforms to establish recurring revenue streams independent of pure unit sales.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical conglomerates seeking bioadhesive formulation capabilities to complement endocrinology pipelines. Mid-cap specialists with polymer-to-product integration and established EMA MDR dossiers represent the most defensible acquisition archetype. Watch for FDA-EMA regulatory divergence on sustained-release characterization as an inflection signal that would force geography-specific formulation investments and favor incumbents with parallel compliance infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Feedstock Security Partnership | Long-term supply agreements with German polycaprolactone suppliers mitigate single-source vulnerability for sustained-release matrix production. |
| pH-Responsive Platform Development | Smart polymer architectures with embedded environmental sensing unify diagnostic and therapeutic functions for personalized estradiol dosing. |
| CDSCO Fast-Track Registration | Accelerated approval leveraging US or EU precedent reduces timeline for entry into Indian manufacturing and export corridors. |
| Telehealth Integration Infrastructure | Remote patient onboarding workflows and reimbursement documentation adapt to compressed traditional gynecological clinic channels. |
| REACH Retrospective Compliance Investment | Extended migration studies for extractable compounds defend legacy formulations against tightening European toxicological data burdens. |
Research Methodology
Independent corroboration across regulatory filings, hospital procurement databases, and polymer supplier technical disclosures underwrites the qualitative findings in this study. Primary interviews with gynecological clinic administrators, formulary directors at pharmacy benefit managers, regulatory affairs leads at combination product manufacturers, and polymer scientists at medical-grade synthesis suppliers combined with secondary validation from FDA Center for Drug Evaluation and Research guidance documents, EMA MDR submission databases, and REACH authorization records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate demand estimates.
Historical reference periods anchored the forecast window to established menopausal therapy adoption curves and prior regulatory approval timelines for sustained-release platforms. Segmentation dimensions modeled include product type, material composition, delivery mode, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to prescription volume and average selling price trajectories. Industry-specific forecast inputs incorporated telehealth protocol diffusion rates and REACH authorization processing timelines for novel polymer monomers.
The model assumes a particular technology adoption path for bioadhesive hydrogel platforms; alternative pathways favoring conventional silicone matrices would alter the outlook for residue-free formulation penetration. Forecasts reflect assumptions regarding regulatory alignment between FDA and EMA on sustained-release characterization, reimbursement stability for hormonal therapies in United States clinical channels, and polymer feedstock supply continuity from German suppliers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Gum Grafting Market
Medical Devices
Manual Resuscitators Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Breathing Circuits Market
Medical Devices
Syringe Scale Magnifiers Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Indonesia Devices Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Lactate Meter Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Intervertebral Implants Market