
 Polyethersulfone Dialyzer Market | 2026-2036
Polyethersulfone Dialyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethersulfone Dialyzer Market Analysis
Reusable membrane reprocessing services are restructuring procurement economics for dialysis providers. Fresenius Medical Care AG & Co. KGaA leverages captive service networks to lock in multi-year supply contracts. Baxter International Inc. anchors its position through integrated delivery models spanning device and consumable bundles. Nipro Corporation competes on manufacturing scale in membrane fiber production.
Polyethersulfone dialyzers employ hydrophilic asymmetric hollow-fiber membranes with molecular weight cutoffs typically ranging from 10 to 20 kilodaltons, engineered to clear uremic toxins while retaining albumin during extracorporeal blood purification. High flux variants command premium positioning due to superior middle-molecule clearance rates that reduce long-term complication burdens. Dialysis centers represent the most mature end-user channel, whereas home care configurations are expanding fastest as reimbursement frameworks adapt to remote monitoring capabilities.
The FDA governs 510(k) clearance pathways and biocompatibility standards under ISO 10993 for blood-contacting devices, while the European Medicines Agency enforces CE marking under the Medical Device Regulation with enhanced clinical evidence requirements. Japan's Pharmaceuticals and Medical Devices Agency maintains distinct membrane performance benchmarks that shape export qualification protocols. Stakeholders must monitor evolving reimbursement codes for home-based modalities and anticipate how real-world evidence mandates will reshape post-market surveillance obligations.
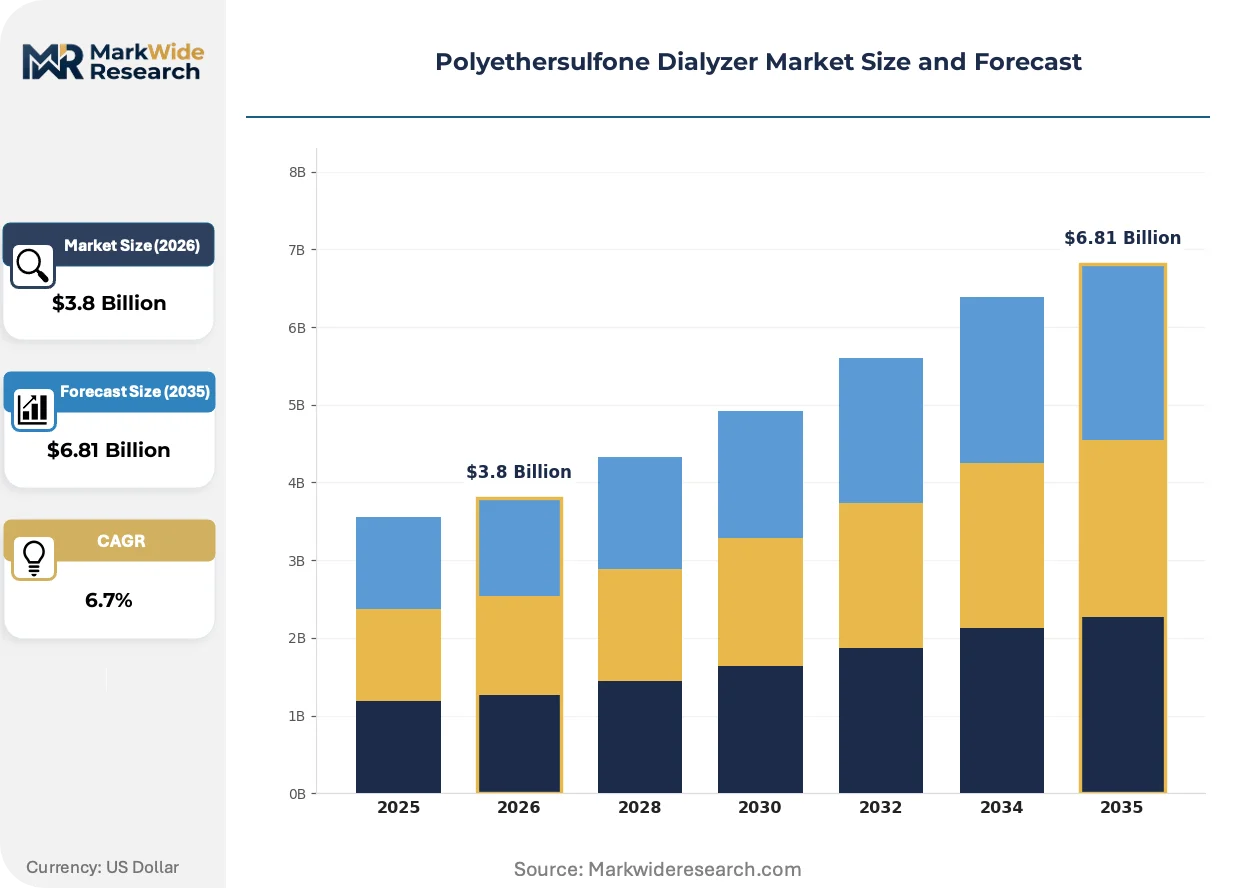
Market Dynamics
Reimbursement pathway maturation for home-based hemodialysis is compressing facility dependency and forcing membrane manufacturers to revalidate performance claims under remote monitoring conditions. This structural shift is rewriting procurement specifications and service bundling requirements across the value chain.
Growth Catalysts
- Remote Patient Monitoring Infrastructure:Telehealth integration for home dialysis is expanding addressable patient populations beyond clinic catchment zones. Medicare reimbursement codes now cover connected device peripherals.
- FDA Biocompatibility Guidance:Updated ISO 10993 testing protocols are accelerating membrane material innovation cycles. Manufacturers must demonstrate enhanced hemocompatibility profiles for 510(k) clearance.
- High-Flux Membrane Performance:Superior middle-molecule clearance specifications are displacing conventional low-flux configurations in incident patient starts. Nephrology practice guidelines increasingly favor beta-2 microglobulin reduction ratios.
Market Restraints
- Polysulfone Raw Material Concentration:Specialty polymer feedstock production concentrates among German and Japanese chemical suppliers. Geopolitical friction threatens just-in-time membrane manufacturing schedules.
- CE Marking Clinical Evidence Burden:EU Medical Device Regulation mandates expanded post-market surveillance datasets. Small manufacturers face disproportionate compliance cost absorption.
- Peritoneal Dialysis Substitution:Automated peritoneal dialysis systems are capturing incident end-stage renal disease patients who might otherwise initiate hemodialysis. Home modality competition intensifies.
Strategic Opportunities
- India Dialysis Infrastructure Buildout:The country's national dialysis program under Ayushman Bharat is expanding facility networks into tier-2 and tier-3 cities. Local manufacturing partnerships can bypass import duty structures.
- Wearable Artificial Kidney Convergence:Portable hemofiltration devices are integrating polyethersulfone membranes into miniaturized cartridge formats. This emerging application demands radically reconfigured fiber packing densities.
- Reuse Service Integration:Reprocessing validation protocols create recurring revenue attachment opportunities. Dialysis providers seek single-source accountability for device lifecycle management.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Specialized expertise in extracorporeal circuit design remains concentrated among aging practitioner cohorts. Training pipeline expansion lags home dialysis modality growth.
- Legacy Water Purification Retrofit Complexity:Clinic infrastructure built for conventional dialysis requires costly ultrapure water system upgrades. Capital allocation conflicts with reimbursement rate compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethersulfone Dialyzer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Flux, Low Flux, Ultra-High Flux, Microfiltration End User: Hospitals, Clinics, Home Care, Dialysis Centers Application: Acute Kidney Injury, Chronic Kidney Disease, Hemodialysis, Peritoneal Dialysis Technology: Semi-Automated, Automated, Continuous, Batch |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., B. Braun Melsungen AG, Nipro Corporation, Asahi Kasei Medical Co., Ltd., Toray Medical Co., Ltd., NxStage Medical, Inc., Medica S.p.A., Farmasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethersulfone Dialyzer Market Emerging Trajectories
Membrane engineering and regulatory evidence requirements are converging to reshape competitive positioning. Manufacturers must now validate performance under real-world home use conditions rather than controlled clinical environments.
Automated fiber spinning control systems are automating pore size distribution consistency in hollow-fiber production. Dialysis membrane foundries in Japan and Germany are deploying machine vision for real-time diameter calibration. This precision manufacturing is automating yield improvements and compressing lot-to-lot variability that previously required extensive post-production testing.
Japan's PMDA has introduced distinct membrane performance benchmarks for protein leakage and endotoxin retention that exceed ISO 13959 baselines. Export qualification protocols now require Japan-specific validation studies regardless of CE marking or FDA clearance status. Manufacturers targeting Japanese procurement tenders must maintain separate quality management system documentation.
Home dialysis patients are demanding unbundled consumable purchasing options separate from device leasing arrangements. Traditional bundled reimbursement models are fragmenting as patients seek direct-to-consumer membrane cartridge subscriptions. This purchasing autonomy is most visible in United States markets where Medicare Advantage plans experiment with point-of-sale flexibility.
Polyethersulfone Dialyzer Market Segmentation
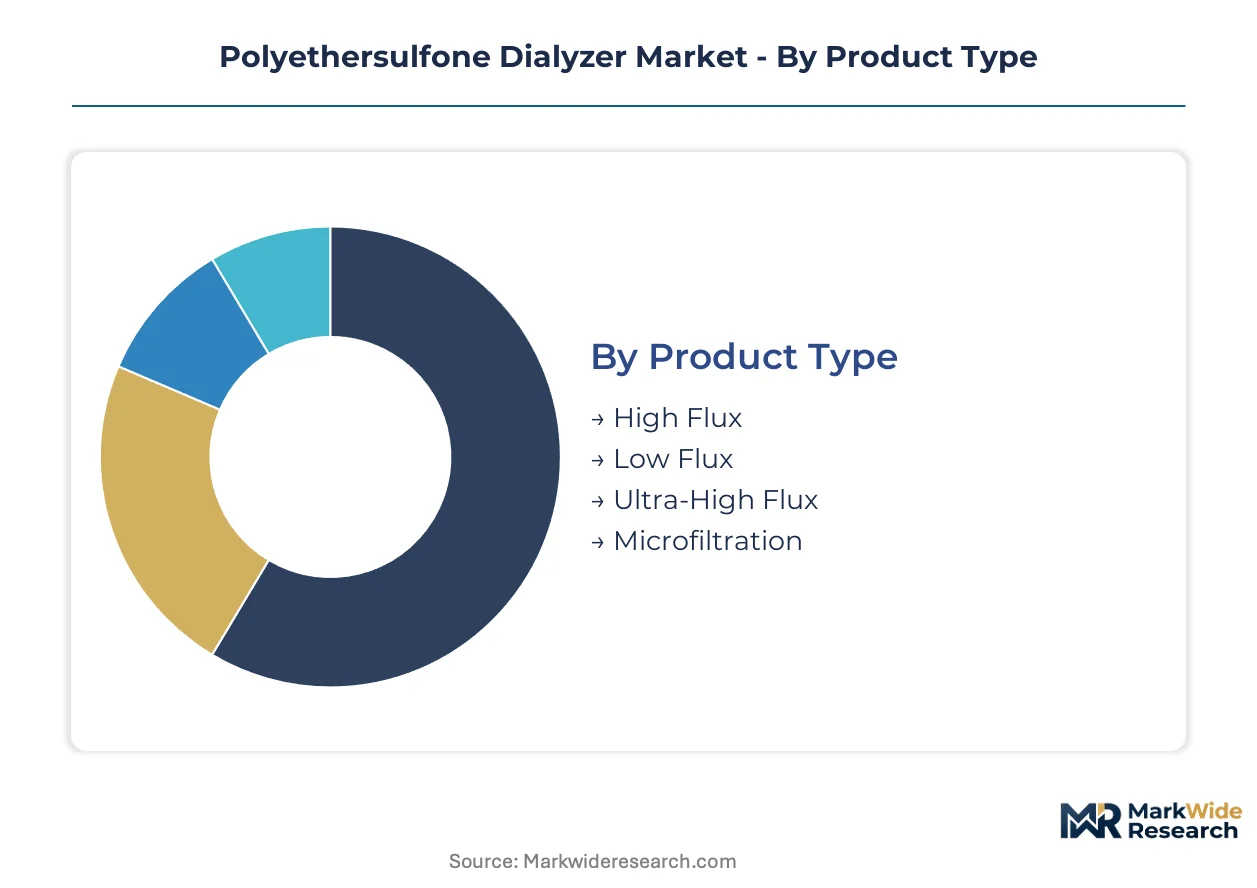
Polyethersulfone dialyzer procurement decisions hinge on clinical workflow integration, reimbursement pathway alignment, and membrane performance specifications. Each segmentation dimension reveals distinct buyer priorities that reshape manufacturing priorities and distribution channel investments.
Product Type:
Flux classification separates buyers by clinical outcome requirements and reimbursement tier positioning.
- High Flux:Asymmetric membranes with enhanced beta-2 microglobulin clearance command premium positioning in incident patient starts. Nephrology practice guidelines in the United States increasingly mandate middle-molecule reduction ratios that only high-flux configurations reliably deliver.
- Low Flux:Conventional hydrophilic hollow-fiber designs retain cost-sensitive procurement slots in established dialysis center networks. Volume concentrates in mature reimbursement markets where capital constraints limit modality upgrades.
- Ultra-High Flux:Experimental membrane architectures targeting myoglobin and inflammatory cytokine clearance in acute settings. Clinical validation remains limited to tertiary hospital systems with research affiliations.
- Microfiltration:Specialized cartridges for plasma separation and therapeutic apheresis applications. Demand clusters in blood bank networks and academic medical centers.
Volume sits with Low Flux; growth tilts toward High Flux.
End User:
Site-of-care economics determine service bundling requirements and membrane replacement frequency.
- Dialysis Centers:High-throughput outpatient facilities generate recurring cartridge demand through thrice-weekly treatment protocols. United States reimbursement codes for facility-based hemodialysis lock in predictable procurement volumes.
- Home Care:Remote monitoring infrastructure expansion is compressing clinic dependency for stable patients. Medicare Advantage plans in the United States now cover connected device peripherals that enable unbundled consumable purchasing.
- Hospitals:Acute dialysis services require rapid cartridge availability for ICU-based continuous renal replacement therapy. Procurement prioritizes supply chain reliability over unit cost optimization.
- Clinics:Satellite facilities in tier-2 and tier-3 cities under India's Ayushman Bharat program drive import substitution pressure. Local manufacturing partnerships bypass duty structures.
Revenue concentrates in Dialysis Centers; Home Care climbs the fastest.
Application:
Disease progression stage dictates membrane performance thresholds and treatment modality selection.
- Chronic Kidney Disease:Maintenance hemodialysis populations require sustained membrane performance over multi-year treatment horizons. Long-term complication reduction drives high-flux specification adoption.
- Acute Kidney Injury:ICU-based continuous therapies demand biocompatible membranes compatible with anticoagulation-sensitive patients. Hospital procurement prioritizes endotoxin retention specifications.
- Hemodialysis:Extracorporeal blood purification remains the dominant application for polyethersulfone membranes. Device-leasing arrangements traditionally bundle cartridges with machine maintenance contracts.
- Peritoneal Dialysis:Competing modality capturing incident end-stage renal disease patients who might otherwise initiate hemodialysis. Automated peritoneal dialysis systems reduce addressable hemodialysis cartridge demand.
Patient volume centers on Hemodialysis; Acute Kidney Injury shows steepest expansion trajectory.
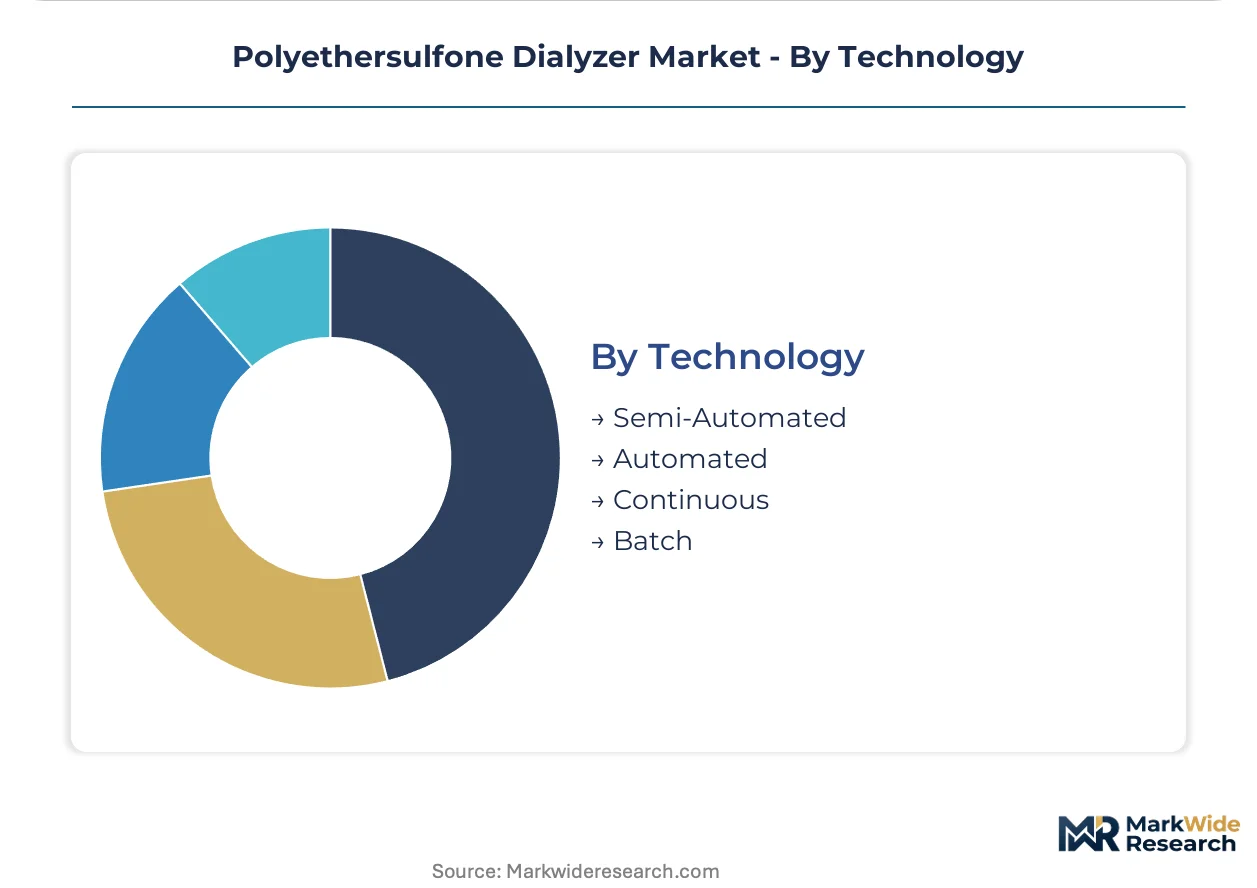
Technology:
Automation level determines labor cost allocation and treatment standardization potential.
- Automated:Closed-system dialysis machines with integrated membrane cartridge recognition reduce operator error in high-turnover clinical environments. FDA 510(k) clearance pathways favor automated platforms with embedded safety interlocks.
- Continuous:Sustained low-efficiency dialysis and continuous venovenous hemofiltration for hemodynamically unstable patients. ICU adoption in the United States drives demand for specialized high-permeability cartridges.
- Semi-Automated:Manual priming and bloodline connection requirements persist in cost-constrained settings. Developing market facility buildouts favor lower capital expenditure configurations.
- Batch:Single-use cartridge designs for intermittent acute treatments. Limited penetration outside emergency backup scenarios.
Installed base favors Semi-Automated; Automated gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate specialty polymer feedstock production, while the United States absorbs the highest dialyzer consumption volumes. This geographic split between upstream membrane manufacturing and downstream clinical deployment shapes trade flows and regulatory alignment priorities.
United States
Medicare reimbursement codes for home-based hemodialysis and connected device peripherals are expanding addressable patient populations beyond traditional clinic catchment zones. The FDA governs 510(k) clearance pathways under ISO 10993 biocompatibility standards. Dialysis procurement concentrates in regional hub networks across the Midwest and Southeast, where facility-based treatment protocols still dominate volume.
Germany
Specialty polysulfone polymer production concentrates among chemical suppliers serving membrane foundries across Baden-Württemberg and North Rhine-Westphalia. The EU Medical Device Regulation enforces CE marking with expanded post-market surveillance datasets. Industrial clusters around Frankfurt and Stuttgart host precision fiber spinning operations with automated pore calibration systems.
Japan
PMDA membrane performance benchmarks for protein leakage and endotoxin retention exceed ISO 13959 baselines, requiring Japan-specific validation studies. The country's national dialysis program maintains distinct procurement specifications. Manufacturing gravity centers on Nagoya and Osaka, where hollow-fiber membrane foundries deploy machine vision for real-time diameter calibration.
India
Ayushman Bharat's national dialysis program is expanding facility networks into tier-2 and tier-3 cities, creating import substitution pressure for membrane cartridges. CDSCO regulates medical device licensing with evolving clinical evidence requirements. Industrial corridors in Maharashtra and Gujarat are attracting local manufacturing partnerships to bypass duty structures on imported dialyzers.
China
NMPA medical device registration pathways are tightening for blood-contacting devices as domestic dialysis infrastructure expands into provincial hospital systems. The country's dual carbon goals are pressuring energy-intensive polymer production. Manufacturing investment clusters in Jiangsu and Zhejiang provinces are scaling membrane fiber capacity for regional supply security.
Polyethersulfone Dialyzer Market Vendor Landscape
Capital-heavy membrane foundries compete with asset-light device integrators across distinct value chain positions. The market structure tilts toward consolidation at the materials tier, where polymer synthesis and fiber spinning require specialized chemical process expertise, while device assembly presents lower barriers to entry. Three archetypes dominate: integrated multinationals with captive membrane production, specialized membrane suppliers selling to third-party device makers, and regional assemblers competing on localized service bundling. Dominant competitive moves include backward integration into polymer feedstock and geographic expansion through local manufacturing partnerships.
Among integrated multinationals, Fresenius Medical Care AG & Co. KGaA and Baxter International Inc. exemplify the full-stack archetype spanning membrane production through clinical service networks. Nipro Corporation occupies a position as a scale-driven membrane specialist with concentrated manufacturing expertise. These three represent the competitive poles around which mid-tier assemblers and regional distributors organize their market participation strategies.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Nipro Corporation |
| Asahi Kasei Medical Co., Ltd. |
| Toray Medical Co., Ltd. |
| NxStage Medical, Inc. |
| Medica S.p.A. |
| Farmasol |
| Others |
Supply Flow & Price Mechanics
Family-owned membrane foundries in Germany and Japan anchor specialty polymer feedstock production, translating concentrated upstream ownership into disciplined pricing power across hollow-fiber supply contracts. This ownership pattern reinforces long-term offtake agreements that insulate pricing from spot-market volatility while locking dialysis providers into multi-year procurement cycles.
Pricing Analysis
Margin tightening in high-flux dialyzer tiers reflects reimbursement rate compression from Medicare Advantage plans and bundled payment pilots. Three-tier pricing structure across premium, standard, and economy levels separates high-flux membranes with enhanced beta-2 microglobulin clearance from conventional low-flux configurations and reuse-validated cartridges. Price differentiation rests on ISO 10993 biocompatibility certification tier and fiber spinning precision grades. Dialysis centers in the United States exhibit highest price sensitivity due to capital allocation conflicts with facility infrastructure upgrades, whereas academic medical centers prioritize endotoxin retention specifications over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from United States dialysis providers mandate qualification of at least two membrane suppliers per cartridge specification, forcing manufacturers to maintain redundant fiber spinning lines. Geographic supply concentrates in Germany, Japan, and China, with specialty polysulfone polymer synthesis anchored in Baden-Württemberg chemical clusters and hollow-fiber membrane foundries clustering around Nagoya and Osaka. Raw material dependencies span medical-grade polysulfone resin, hollow-fiber spinning solvents, and endotoxin-controlled packaging films. Single-source vulnerability threatens just-in-time manufacturing schedules amid geopolitical friction. Distribution runs through regional hub networks across the United States Midwest and Southeast, with GPO contracts consolidating procurement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyethersulfone dialyzer market sits in a technology-transition phase as high-flux membrane architectures displace conventional low-flux configurations in incident patient starts.
For Market Incumbents: Acquire automated fiber spinning control systems to compress lot-to-lot variability and defend against emerging Asian membrane specialists. Lock in backward integration into medical-grade polysulfone resin production to insulate margins from German and Japanese chemical supplier concentration. Expand captive reprocessing service networks to create recurring revenue attachment and raise switching costs for dialysis providers. For New Entrants and Emerging Players: CDSCO medical device licensing pathways in India open a window for local manufacturing partnerships targeting Ayushman Bharat's tier-2 and tier-3 city expansion. White-space concentrates in wearable artificial kidney cartridge formats demanding radically reconfigured fiber packing densities. Penetrate through unbundled consumable subscription models targeting Medicare Advantage plans experimenting with point-of-sale flexibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized membrane suppliers with concentrated manufacturing expertise in Japan and Germany amid CE marking clinical evidence burden pressures. Long-term viability centers on five-to-ten year windows for consolidation at the materials tier where polymer synthesis and fiber spinning require specialized chemical process expertise. Watch FDA guidance evolution on real-world evidence mandates for home-based modalities as inflection indicator for post-market surveillance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for high-flux membranes with enhanced hemocompatibility profiles under updated ISO 10993 protocols. |
| CE Marking Pathway | Unlocks European procurement access amid expanded post-market surveillance datasets under EU Medical Device Regulation. |
| Hospital System Partnership | Secures rapid cartridge availability contracts for ICU-based continuous renal replacement therapy in tertiary facilities. |
| Reimbursement Strategy | Aligns connected device peripherals with Medicare codes covering home-based hemodialysis remote monitoring infrastructure. |
| Software Companion Development | Enables integrated delivery models spanning device and consumable bundles with embedded safety interlocks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this polyethersulfone dialyzer market assessment. Primary interviews with biomedical engineers, dialysis center procurement managers, GPO contracts specialists, and nephrology practice administrators combined with FDA 510(k) databases, PMDA submission records, CMS Medicare reimbursement codes, and EU MDR technical documentation. Bottom-up membrane production capacity estimates triangulated against top-down dialysis patient population projections.
Granularity-level modeling deployed separate forecasts for high-flux, low-flux, ultra-high flux, and microfiltration product tiers across dialysis center, home care, hospital, and clinic end-user channels. Technology dimensions captured automated, continuous, semi-automated, and batch configurations. Chronic kidney disease, acute kidney injury, hemodialysis, and peritoneal dialysis applications were modeled distinctly. CAGRs derived from patient population growth rates, modality shift assumptions, and membrane replacement frequency patterns across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for wearable artificial kidney convergence would alter the outlook for miniaturized cartridge demand. Forecasts reflect assumptions on reimbursement pathway maturation for home-based modalities and real-world evidence mandate evolution. Deviation in FDA biocompatibility guidance timing or Medicare Advantage bundling experiment outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Walking Aids Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Global Venous Stents Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Portable OT Light Market
Medical Devices
Cervical Fusion Market