
 Epilepsy Devices Market | 2026-2036
Epilepsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Epilepsy Devices Market Analysis
Buyer concentration among integrated hospital networks and specialized epilepsy centers is realigning procurement patterns across the epilepsy devices landscape. Medtronic leverages its long-standing FDA approvals for vagus nerve stimulation to sustain institutional relationships with major academic medical centers. Abbott competes through its directional deep brain stimulation portfolio, while NeuroPace specializes in responsive neurostimulation systems that anchor its position in drug-resistant epilepsy segments.
Epilepsy devices comprise implantable neurostimulators, external monitoring hardware, and wearable sensors designed to detect, interrupt, or record seizure activity through electrical modulation or electrophysiological measurement. These systems typically operate at frequencies between 1-250 Hz for intracranial recording and deliver therapeutic pulses at programmable amplitudes up to 10.5 V in implantable configurations, serving primarily to reduce seizure burden in patients unresponsive to pharmacological intervention. Vagal nerve stimulators and responsive neurostimulation devices occupy the highest-margin tier of the device type segmentation, while wearable devices represent the fastest-expanding category as Empatica and others advance seizure detection algorithms for home care deployment. EEG monitoring systems dominate hospital and neurology clinic settings where diagnostic precision requirements favor multi-channel acquisition over portability trade-offs.
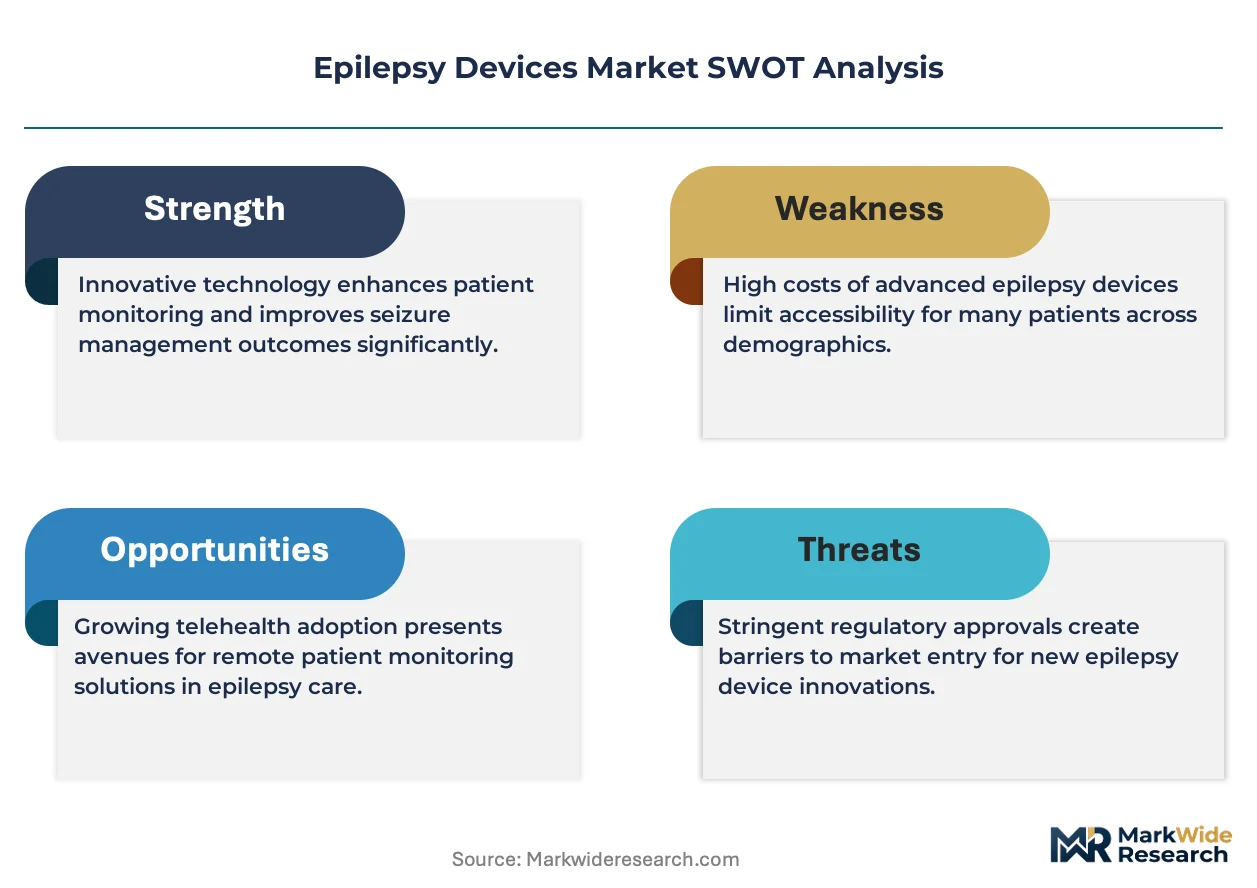
FDA premarket approval and the EU MDR clinical evaluation requirements shape market access timelines and evidence generation costs for implantable epilepsy technologies, with ISO 14155 governing clinical investigation standards across jurisdictions. The FCC regulates wireless telemetry frequencies in connected monitoring devices, constraining transmission protocols for remote patient data flows. Stakeholders must monitor evolving reimbursement decisions by CMS and comparable national health technology assessment bodies, as coverage determinations for closed-loop implantable systems will dictate commercial scalability irrespective of technical validation milestones.
Market Dynamics
Integrated hospital networks are consolidating procurement authority for implantable neurostimulators, shifting purchasing decisions from individual physicians to centralized value-analysis committees that prioritize total cost of care over device acquisition price alone.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services is broadening coverage determinations for responsive neurostimulation therapy, enabling patient access across Medicare Advantage networks and catalyzing hospital investment in surgical implant programs.
- Closed-loop algorithm advancement:Machine learning-driven seizure detection is improving therapeutic response rates in drug-resistant epilepsy populations, creating clinical justification for earlier surgical intervention.
- Japan's aging demographic:The Ministry of Health, Labour and Welfare is accelerating PMDA review timelines for neuromodulation devices as epilepsy incidence rises among patients over 65 years.
Market Restraints
- EU MDR clinical evidence requirements:The Medical Device Regulation mandates extended follow-up periods for active implantable devices, extending time-to-market by 18-24 months and elevating trial costs for manufacturers.
- Lithium-ion battery supply concentration:Cell production for implantable pulse generators concentrates among East Asian suppliers, exposing device makers to input cost volatility and qualification delays.
- Pharmacological substitution:Next-generation antiseizure medications from Novartis and UCB are demonstrating efficacy in previously refractory patients, compressing the addressable surgical population.
Strategic Opportunities
- Germany's DiGA pathway:The Federal Institute for Drugs and Medical Devices is enabling prescription digital therapeutics reimbursement, creating a regulatory channel for seizure detection apps paired with implantable systems.
- Pediatric epilepsy centers:Specialized children's hospitals represent an underpenetrated segment where early responsive neurostimulation intervention may alter neurodevelopmental trajectories.
- Remote patient monitoring convergence:Integration of wearable EEG with cloud-based analytics platforms is enabling home-based seizure forecasting that extends therapeutic monitoring beyond clinic walls.
Industry Challenges
- Electrophysiologist training scarcity:Surgical implantation of intracranial devices requires specialized expertise in stereotactic neurosurgery that remains concentrated at academic medical centers, limiting procedural capacity expansion.
- Legacy EMR integration complexity:Closed-loop neurostimulator data streams require custom interface development with Epic and Cerner systems, fragmenting implementation timelines across hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epilepsy Devices Market |
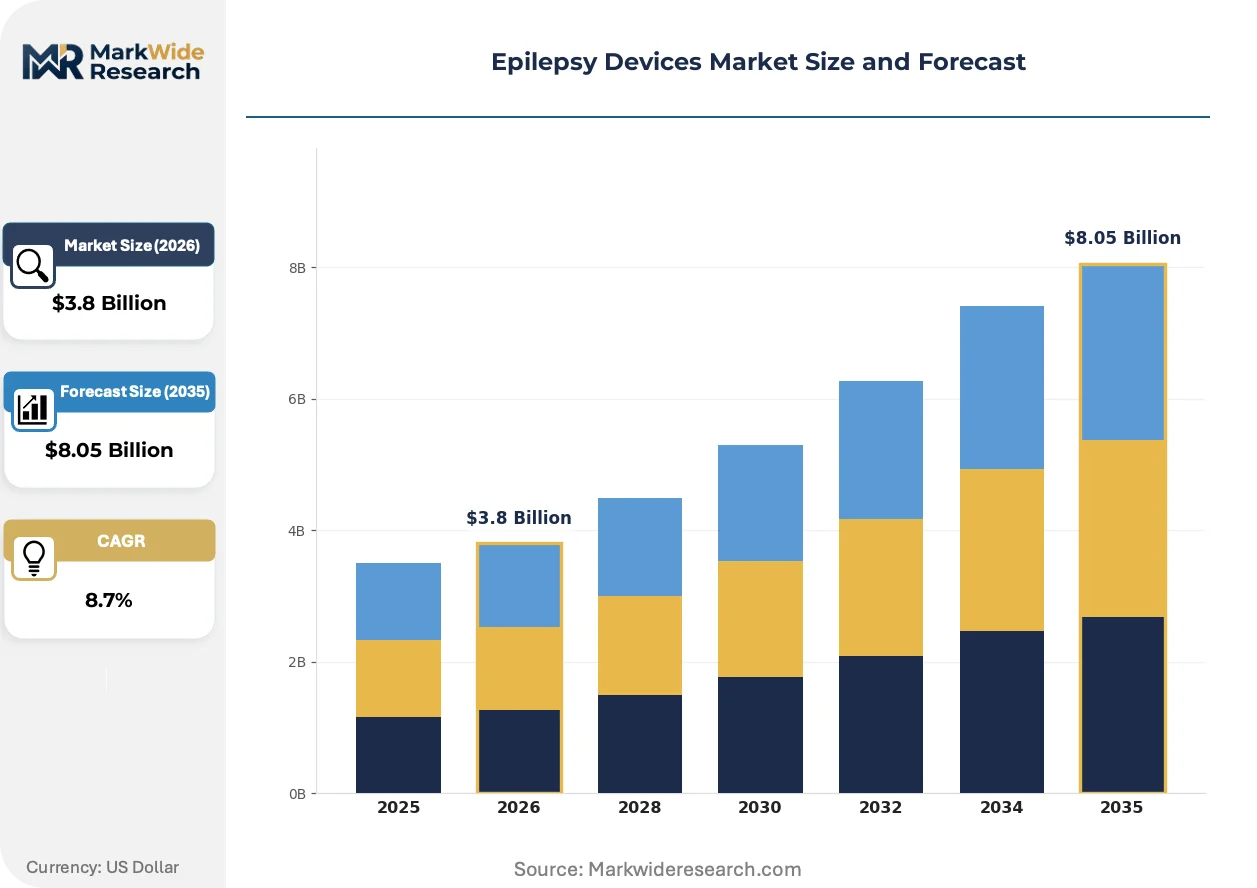
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Vagal Nerve Stimulators, Responsive Neurostimulation Devices, EEG Monitoring Systems, Wearable Devices End User: Hospitals, Neurology Clinics, Home Care, Research Institutions Application: Seizure Management, Diagnostics, Monitoring, Data Management Technology: Closed-Loop Systems, Open-Loop Systems, Implantable Technologies, Mobile Applications |
| Companies Covered | Medtronic, Abbott, Boston Scientific, NeuroPace, LivaNova, Natus Medical, Compumedics, Nihon Kohden, Empatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epilepsy Devices Market Emerging Trajectories
Algorithmic seizure prediction is migrating from research environments into clinically validated platforms, compressing the latency between prodromal detection and therapeutic intervention while reshaping how neurologists manage chronic epilepsy.
Subcutaneous EEG electrodes paired with miniaturized telemetry modules are decentralizing seizure monitoring from hospital epilepsy monitoring units into ambulatory settings. Community neurology practices are adopting these systems to reduce inpatient admission requirements. This technology is decentralizing diagnostic workflows and compressing the interval between symptom onset and surgical candidacy determination.
The FDA is tightening cybersecurity validation requirements for connected implantable devices under its premarket guidance for medical device interoperability. Manufacturers must now submit threat modeling documentation and software bill of materials with 510(k) filings. Implantable neurostimulator portfolios face the most significant compliance burden as wireless telemetry becomes standard functionality.
Epilepsy center purchasing committees are unbundling device procurement from technical support services, negotiating separate contracts for implantation, programming, and long-term device management. Independent neurology groups are aggregating into super-groups to command pricing leverage previously reserved for academic medical centers. This pattern is most pronounced in Texas and Florida where private equity consolidation has concentrated outpatient epilepsy care.
Epilepsy Devices Market Segmentation
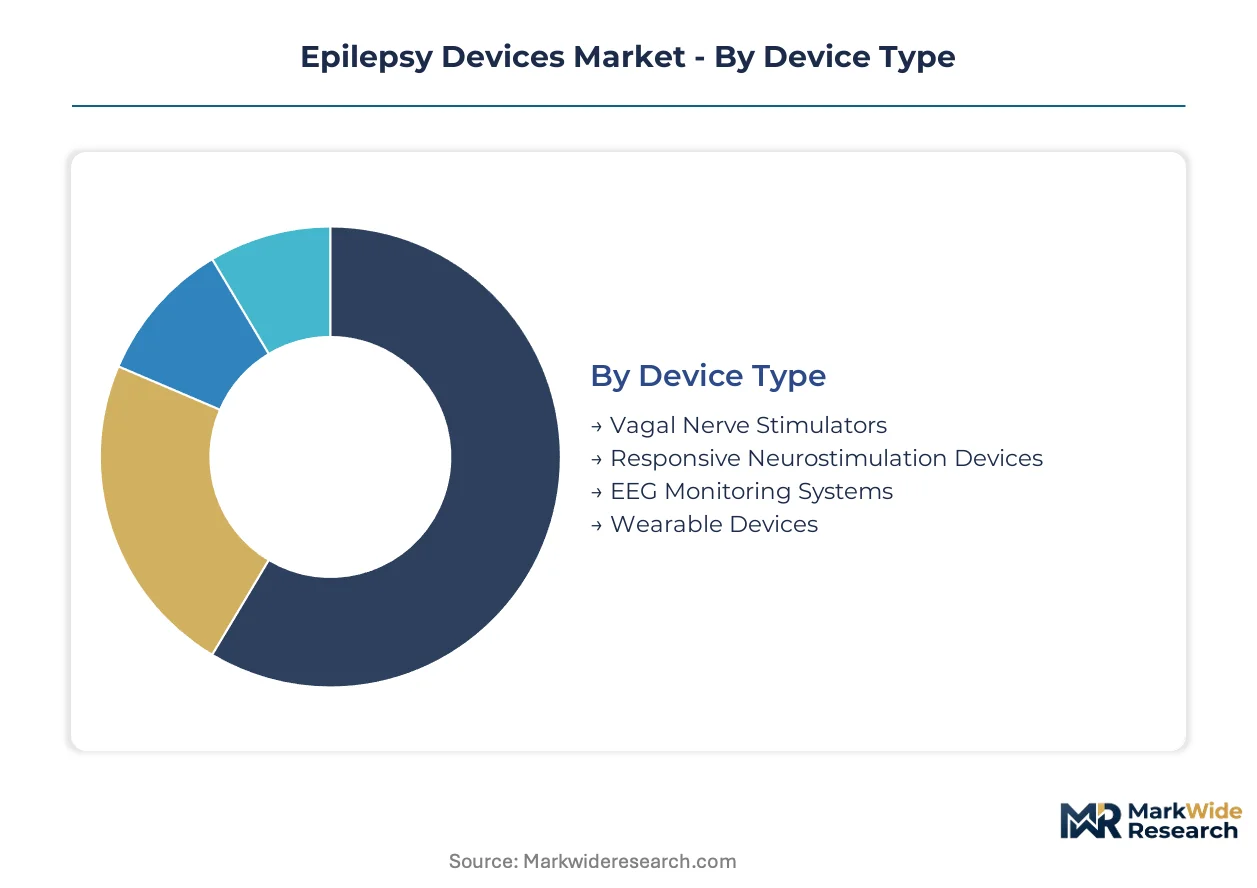
Epilepsy device segmentation reveals divergent margin structures across implantable and external technologies. Procurement patterns vary sharply between acute care settings where capital equipment dominates and ambulatory channels where consumable sensors proliferate.
Device Type:
Volume concentrates in external monitoring hardware while premium margins accrue to implantable neurostimulators requiring surgical placement and long-term management.
- Vagal Nerve Stimulators:These implantable pulse generators deliver intermittent electrical stimulation to the left vagus nerve via a bipolar lead system. Demand clusters at academic medical centers in the United States and Germany where CMS and BfArM reimbursement pathways support surgical candidacy assessments for drug-resistant populations.
- Responsive Neurostimulation Devices:Intracranial systems detect abnormal electrical patterns and deliver targeted counter-stimulation to seizure foci. Epilepsy centers in Japan are expanding implant programs as PMDA accelerates review timelines for aging demographic cohorts with pharmacoresistant epilepsy.
- EEG Monitoring Systems:Multi-channel electrophysiology platforms with 32-256 electrode configurations serve diagnostic workflows in hospital epilepsy monitoring units.
- Wearable Devices:Accelerometer and electrodermal activity sensors enable home-based seizure detection for pediatric and adult ambulatory populations.
Today's leader: Vagal Nerve Stimulators. Tomorrow's challenger: Wearable Devices.
End User:
Customer concentration determines pricing leverage, with consolidated hospital networks extracting service unbundling that fragmented neurology practices cannot replicate.
- Hospitals:Integrated delivery networks centralize procurement for implantable systems through value-analysis committees prioritizing total cost of care metrics over device acquisition price alone.
- Neurology Clinics:Outpatient practices concentrate diagnostic EEG utilization and post-implant programming services, with super-group consolidation in Texas and Florida creating purchasing scale previously reserved for academic centers.
- Home Care:Remote patient monitoring adoption is expanding wearable device deployment beyond clinic walls into residential settings.
- Research Institutions:Academic medical centers generate clinical evidence for FDA premarket approval pathways and EU MDR conformity assessments.
Procurement authority is concentrating fastest among hospital networks, though home care channels are gaining share through remote monitoring reimbursement expansion.
Application:
Clinical utility separates high-value therapeutic intervention from commodity data capture, with closed-loop response systems commanding pricing premiums over passive monitoring.
- Seizure Management:Therapeutic neurostimulation and acute intervention protocols occupy the highest-value tier of epilepsy device applications.
- Diagnostics:Video-EEG correlation and source localization guide surgical candidacy determination for resective procedures.
- Monitoring:Continuous electrophysiological surveillance enables seizure burden quantification and treatment response assessment in ambulatory settings.
- Data Management:Cloud-based analytics platforms aggregate device telemetry and patient-reported outcomes for longitudinal care coordination.
Therapeutic applications currently capture dominant value, yet diagnostic and monitoring segments are climbing fastest as ambulatory care models expand.
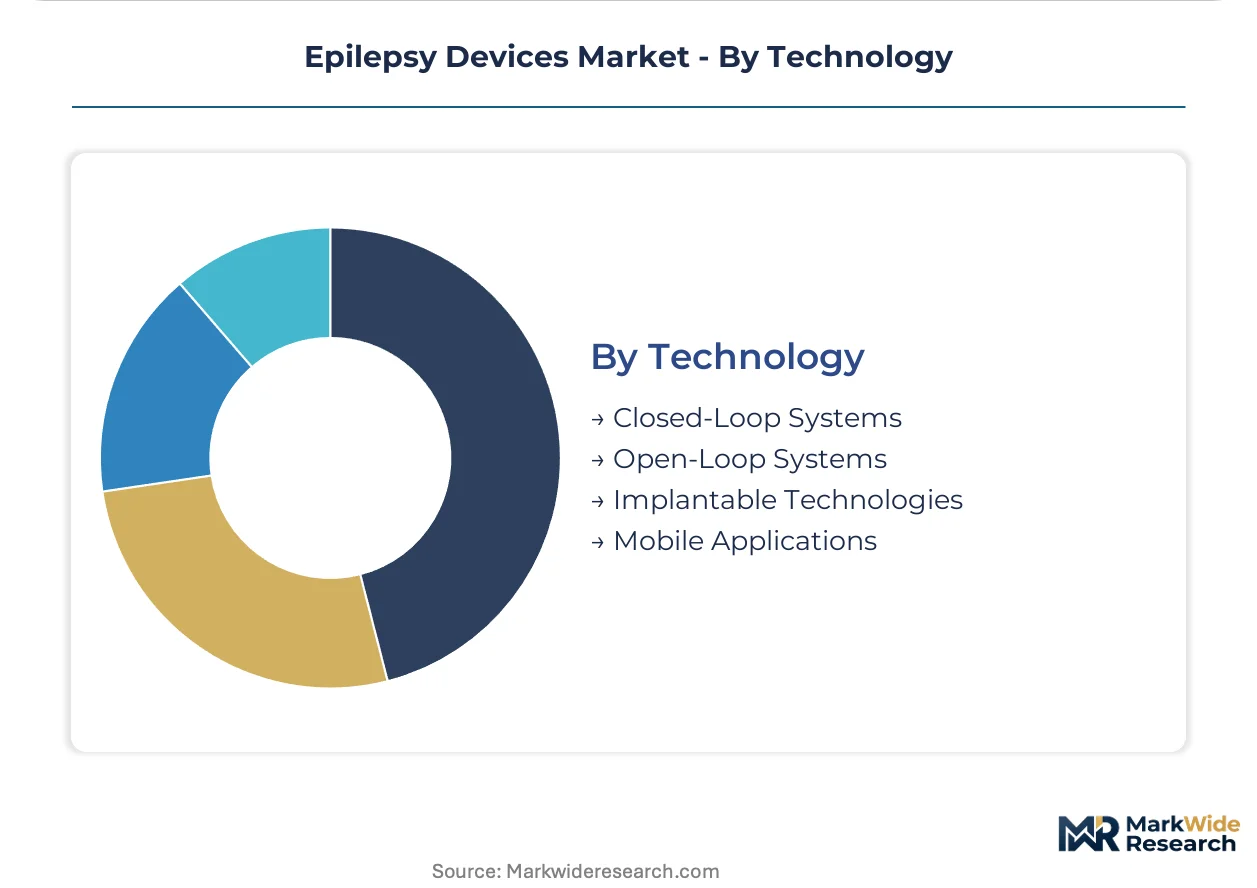
Technology:
Algorithm sophistication creates tiered performance differentiation, with machine learning-enabled prediction separating premium platforms from threshold-based detection systems.
- Closed-Loop Systems:Real-time seizure detection triggers automated therapeutic response without patient or clinician intervention. FDA cybersecurity guidance under medical device interoperability rules imposes threat modeling and software bill of materials requirements on wireless telemetry implementations.
- Open-Loop Systems:Scheduled stimulation protocols deliver therapy at preset intervals without physiological feedback, serving patient populations where detection algorithm complexity exceeds clinical benefit.
- Implantable Technologies:Biocompatible pulse generators with lithium-ion power cells require specialized surgical expertise concentrated at stereotactic neurosurgery centers.
- Mobile Applications:Prescription digital therapeutics paired with implantable systems are accessing Germany's DiGA reimbursement pathway for seizure detection and medication adherence support.
Closed-loop architectures define current premium positioning, while mobile application integration represents the steepest expansion trajectory through regulatory-enabled reimbursement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA accelerates neuromodulation reviews for aging cohorts while Germany's BfArM expands DiGA reimbursement for digital therapeutics, revealing divergent regulatory pathways that reshape commercial timelines across major epilepsy device markets.
United States
CMS reimbursement expansion for responsive neurostimulation therapy drives hospital investment in surgical implant programs across Medicare Advantage networks. FDA premarket approval pathways tighten cybersecurity validation requirements for wireless telemetry in connected implantable devices. The Cleveland Clinic and Mayo Clinic anchor clinical evidence generation for closed-loop systems.
Germany
BfArM reimbursement decisions for vagal nerve stimulation concentrate procurement authority within integrated hospital networks prioritizing total cost of care metrics. The EU Medical Device Regulation mandates extended follow-up periods for active implantable devices, extending manufacturer time-to-market. Berlin and Munich academic medical centers generate conformity assessment data for EU MDR compliance.
Japan
PMDA review timeline acceleration for neuromodulation devices responds to rising epilepsy incidence among patients over 65 years. METI industrial policy supports domestic manufacturing capacity for implantable pulse generator components. Tokyo and Osaka epilepsy centers expand intracranial device implant programs for pharmacoresistant populations.
United Kingdom
NICE technology appraisal processes determine NHS England coverage for closed-loop neurostimulation systems, constraining patient access pending cost-effectiveness validation. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence requirements elevates trial documentation burdens. London and Manchester specialized epilepsy units concentrate surgical candidacy assessments.
Australia
TGA priority review pathways for breakthrough neuromodulation technologies compress regulatory timelines for responsive neurostimulation submissions. Medical Services Advisory Committee reimbursement determinations dictate private hospital procurement of implantable systems. Melbourne and Sydney neurology super-groups aggregate purchasing scale for programming and long-term device management services.
Epilepsy Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the epilepsy devices landscape, creating a tiered structure where scale-driven portfolios clash with indication-specific expertise. Medtronic leverages decades of FDA approval history to sustain institutional relationships, while NeuroPace anchors the responsive neurostimulation segment through specialized clinical focus. Strategic moves concentrate on service unbundling negotiations with integrated hospital networks and algorithm licensing partnerships for machine learning-enabled seizure detection.
Within the diversified medical technology tier, Medtronic and Abbott occupy positions exemplifying breadth-driven competitive advantage, while NeuroPace represents the pure-play specialist archetype. Medtronic's long-standing vagus nerve stimulation approvals anchor its presence at major academic medical centers. Abbott's directional deep brain stimulation portfolio competes across neurological intervention segments. NeuroPace's exclusive focus on responsive neurostimulation systems exemplifies the targeted clinical indication strategy that pure-play specialists employ against conglomerate breadth.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific |
| NeuroPace |
| LivaNova |
| Natus Medical |
| Compumedics |
| Nihon Kohden |
| Empatica |
| Others |
Supply Flow & Price Mechanics
EU MDR clinical evidence requirements gate qualified supply access for implantable neurostimulators while elevating premium-tier pricing for closed-loop systems that demonstrate extended follow-up data. Manufacturers absorbing 18-24 month approval extensions pass compliance costs through to hospital networks, compressing margins for standard-tier devices and widening the pricing spread between certified premium platforms and economy alternatives.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for lithium-ion cells powering implantable pulse generators, yet finished-device pricing stratifies across premium, standard, and economy tiers based on FDA premarket approval status and algorithm sophistication. Price differentiation separates closed-loop responsive neurostimulation systems from open-loop vagal nerve stimulators through cybersecurity validation documentation and machine learning-enabled detection capabilities. Pricing pressure stems from pharmacological substitution as next-generation antiseizure medications capture previously surgical candidates. Hospital value-analysis committees exhibit lowest price sensitivity for integrated care network contracts, while independent neurology super-groups negotiate aggressively on programming service unbundling.
Supply Chain Analysis
Explant and refurbishment flows for pulse generators create secondary supply channels that extend device lifecycle economics and reduce per-patient hardware costs for hospital networks managing long-term implant populations. Component sourcing concentrates among South Korean battery cell manufacturers, Japanese precision electronics suppliers, and German biocompatible materials producers, with raw material dependencies spanning lithium carbonate, platinum-iridium electrodes, and medical-grade silicone encapsulants. Single-source vulnerability in stereotactic neurosurgical instrument supply exposes implant program expansion timelines. Distribution runs through specialized neuromodulation distributors serving academic medical centers and integrated delivery networks with technical support bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epilepsy devices function as a stable compounder anchored by irreversible demographic shifts in aging pharmacoresistant populations across developed healthcare systems. Reimbursement expansion for responsive neurostimulation therapy generates predictable revenue visibility irrespective of near-term competitive dynamics.
For Market Incumbents: Anticipate consolidation pressure from private equity-backed neurology super-groups by securing exclusive multi-year programming contracts with integrated hospital networks. Deepen backward integration into lithium-ion cell qualification to insulate margin structures from East Asian supplier volatility. Prioritize FDA cybersecurity guidance compliance as a competitive moat against emerging entrants lacking threat modeling documentation capabilities.
For New Entrants and Emerging Players: Begin with pediatric epilepsy centers where surgical candidacy determination workflows remain fragmented and academic medical center concentration creates partnership pathways. Target Germany's DiGA reimbursement channel for prescription digital therapeutics paired with wearable seizure detection, leveraging BfArM's accelerated review framework. Deploy cloud-based analytics platforms as the go-to-market wedge to capture ambulatory monitoring data flows before hardware implant decisions.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play algorithm developers without FDA premarket approval history, offering asymmetric upside from regulatory milestone achievement. Five-to-ten-year viability hinges on CMS coverage determination breadth for closed-loop systems across Medicare Advantage networks. Monitor PMDA review timeline compression for neuromodulation devices as the inflection signal for Japanese market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Cybersecurity validation requirements under interoperability guidance impose documentation burdens that favor established manufacturers with regulatory affairs infrastructure. |
| CE Marking Pathway | EU MDR extended follow-up mandates for active implantables extend time-to-market and elevate clinical evidence generation costs for closed-loop systems. |
| Hospital System Partnership | Integrated delivery network value-analysis committees centralize procurement authority and prioritize total cost of care metrics over device acquisition price alone. |
| Software Companion Development | Germany's DiGA reimbursement pathway enables prescription digital therapeutics paired with implantable systems to capture ambulatory seizure monitoring data. |
| Reimbursement Strategy | CMS coverage expansion for responsive neurostimulation therapy across Medicare Advantage networks catalyzes hospital investment in surgical implant programs. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down implantable device production tracking forms the analytical core of this study. Primary interviews with epilepsy center directors, stereotactic neurosurgeons, biomedical engineers, GPO contracts managers, and CMS reimbursement specialists were validated against secondary sources including FDA 510(k) and PMA filings, EU MDR conformity assessment databases, hospital procurement records, and CMS Medicare coverage determinations. Triangulation between demand-side utilization patterns and supply-side manufacturing capacity ensures segmentation integrity across device type and end-user categories.
Input-output matrices mapping lithium-ion cell supply to pulse generator assembly capacity, algorithm development timelines to regulatory submission trajectories, and reimbursement coverage breadth to hospital implant program investment generate volume and value projections across the analysis window. Segmentation dimensions encompass device type, end-user concentration, application tier, and technology architecture. CAGRs derive from fitted growth curves calibrated to historical FDA approval-to-adoption lag patterns and CMS coverage expansion velocities. Forecast inputs include PMDA review timeline acceleration assumptions and EU MDR clinical evidence cost inflation.
Several conditions sit outside the modeled scope, including unforeseen pharmacological breakthroughs eliminating surgical candidacy, lithium supply chain disruptions from geopolitical conflict, and cybersecurity incidents triggering FDA enforcement actions. Forecasts reflect documented assumptions about reimbursement trajectory continuity and regulatory pathway stability. Practitioners should monitor CMS national coverage determination updates, PMDA neuromodulation review queue lengths, and EU MDR notified body capacity constraints for early signals of forecast revision necessity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Struts Implants Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Tissue Embedding Center Market