
 Transcatheter Aortic Valve Implantation (TAVI) Market | 2026-2036
Transcatheter Aortic Valve Implantation (TAVI) Market Size, Share, and Industry Trends Forecast 2026-2036
Transcatheter Aortic Valve Implantation (TAVI) Market Analysis
Hospital-based cardiac surgery centers is unwinding toward ambulatory surgical centers and specialized cardiology clinics as reimbursement shifts reward outpatient structural heart procedures. Edwards Lifesciences Corporation anchors North American TAVI volume through its SAPIEN platform and deep cath-lab relationships. Medtronic plc competes globally with its self-expanding CoreValve system and integrated imaging guidance tools. Abbott Laboratories differentiates via its Navitor valve design and strong interventional cardiology channel control across Europe and Asia-Pacific.
Transcatheter Aortic Valve Implantation deploys a bioprosthetic valve—typically bovine pericardial or porcine tissue mounted on a nitinol or stainless-steel stent frame—through a catheter-based delivery system inserted via the femoral artery or alternative vascular access points, eliminating sternotomy and cardiopulmonary bypass. The procedure restores aortic valve function in patients with severe aortic stenosis who face prohibitive surgical risk. Balloon-expandable valves capture premium positioning in precise annular sizing applications, while transfemoral access dominates procedure volume due to lower complication rates and faster recovery trajectories. Synthetic valve materials represent an emerging R&D frontier as manufacturers seek to eliminate tissue-derived calcification failures and extend valve longevity.
FDA premarket approval and the EU MDR clinical evaluation requirements shape TAVI market access through demanding long-term durability trials and post-market surveillance mandates. Japan's PMDA imposes additional domestic clinical study requirements that delay product entry but ensure rigorous safety validation. Manufacturers must monitor evolving reimbursement decisions by CMS in the United States and national health technology assessment bodies in Europe, as these determinations directly dictate site-level adoption velocity and procedure economics.
Market Dynamics
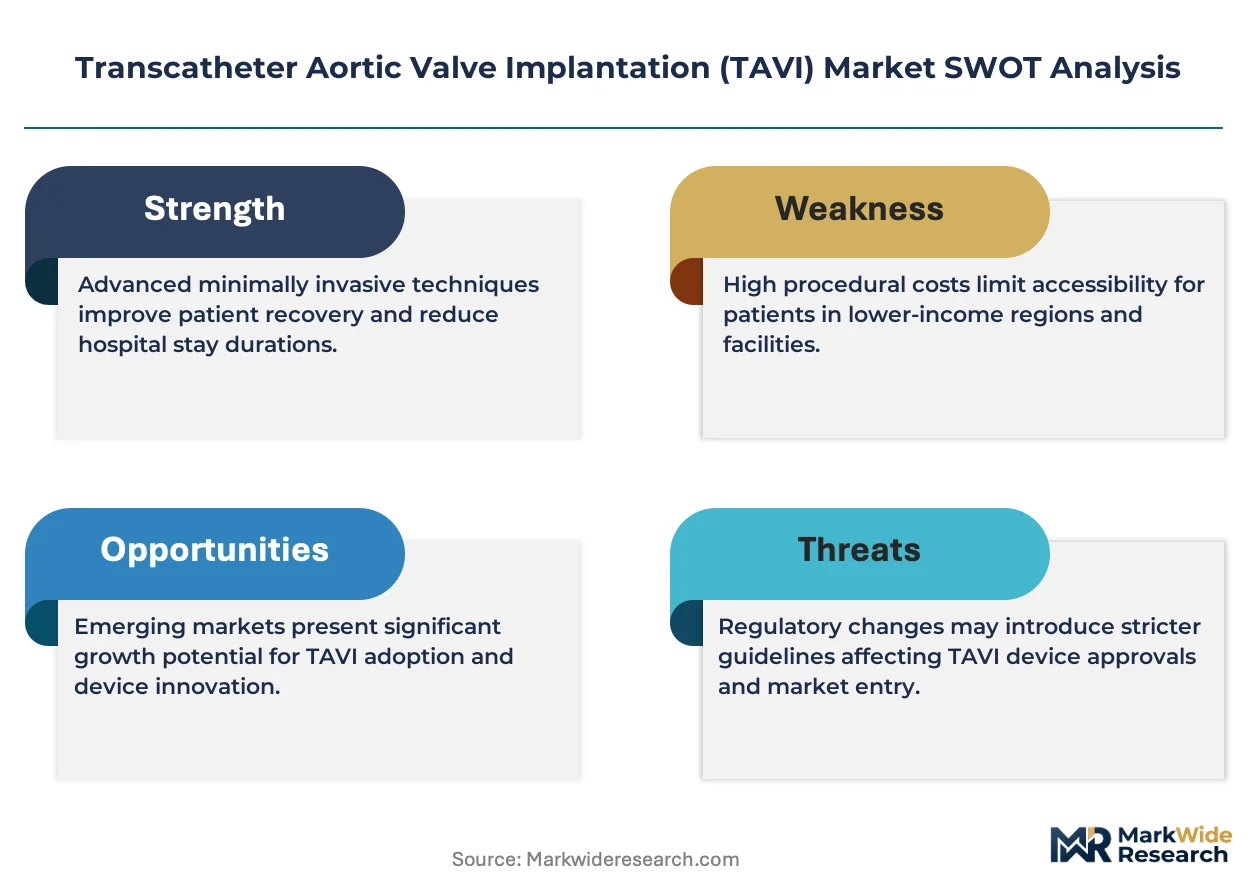
Reimbursement migration from inpatient to outpatient settings is compressing procedure economics and forcing manufacturers to reconfigure site-level support models around ambulatory surgical centers and cardiology clinics.
Growth Catalysts
- CMS outpatient reimbursement expansion:The 2023 addition of TAVI to the Ambulatory Surgical Center Covered Procedures List accelerates site-of-care migration beyond hospital-based cardiac surgery centers.
- Self-expanding valve technology:Nitinol frame designs enable transfemoral delivery in tortuous anatomy previously requiring transapical access, expanding addressable patient populations.
- Germany's structural heart program density:Concentrated cath-lab infrastructure and favorable DRG coding create procedural volume anchors across Baden-Württemberg and Bavaria.
Market Restraints
- Bovine pericardial tissue supply concentration:Reliance on Australian and New Zealand abattoir sourcing creates raw material vulnerability and lot-to-lot variability in tissue thickness.
- EU MDR clinical evaluation requirements:Extended follow-up mandates for valve durability evidence delay CE marking timelines and compress commercialization windows.
- Surgical valve durability benchmarks:Fifteen-year structural valve deterioration data from tissue valves creates expectation gaps against current TAVI longevity evidence.
Strategic Opportunities
- Japan's intermediate-risk indication gap:PMDA approval pathways for expanded indications lag FDA and EMA by 24-36 months, creating first-mover advantage windows for domestic clinical study sponsors.
- Synthetic leaflet materials:Polymer-based valve surfaces eliminate calcification nucleation sites and enable thinner, more durable leaflets without xenograft sourcing constraints.
- Integrated imaging guidance convergence:Fusion of intracardiac echocardiography with fluoroscopy reduces contrast load and radiation exposure, enabling same-day discharge protocols.
Industry Challenges
- Structural heart team skill scarcity:Hybrid training across interventional cardiology and cardiac imaging remains insufficient to match cath-lab expansion velocity.
- Post-market surveillance infrastructure:Longitudinal valve registries require sustained data collection commitments that strain site resources and patient retention rates.
- Legacy electronic health record integration:Procedural data capture for quality reporting and reimbursement justification demands custom interface development with hospital IT systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcatheter Aortic Valve Implantation (TAVI) Market |
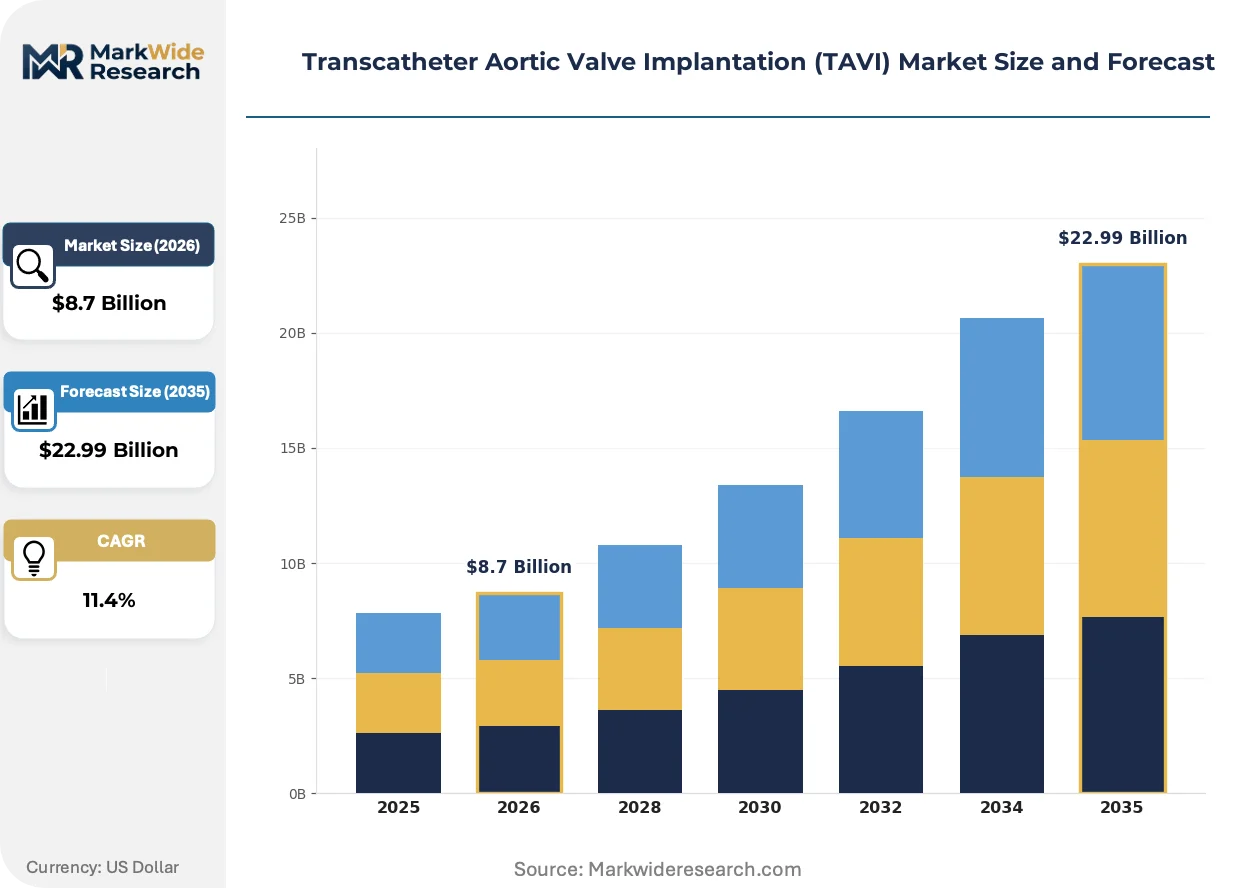
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Bovine Pericardial Valve, Porcine Valve, Synthetic Valve, Balloon-Expandable Valve End User: Cardiology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Procedure Type: Transfemoral, Transapical, Subclavian, Transcarotid Delivery System: Delivery Catheter, Balloon Catheter, Guide Wire, Access Sheath |
| Companies Covered | Boston Scientific Corporation, JenaValve Technology GmbH, Edwards Lifesciences Corporation, Cardiovascular Systems, Inc., Terumo Corporation, Medtronic plc, MicroPort Scientific Corporation, Biotronik SE & Co. KG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcatheter Aortic Valve Implantation (TAVI) Market Emerging Trajectories
Device miniaturization and procedural simplification are compressing the technical barrier to TAVI adoption, enabling volume migration toward lower-acuity settings and earlier disease-stage intervention.
Balloon-expandable valve platforms are fragmenting the precision-sizing segment as manufacturers introduce ultra-low-profile delivery sheaths and pre-sterilized, pre-mounted valve configurations. Community hospitals with limited hybrid OR infrastructure now adopt transfemoral TAVI without on-site surgical backup, enabled by reduced vascular complication rates and simplified post-procedural monitoring protocols. This technology diffusion compresses the historical concentration of TAVI volume within academic medical centers.
CE marking under the EU MDR now demands ten-year follow-up data commitments for bioprosthetic valve approvals, extending clinical trial timelines and elevating post-market surveillance infrastructure requirements. Manufacturers must maintain active implant registries and annual safety reports rather than relying on historical literature reviews. Small and mid-sized valve developers face capital constraints that favor partnership structures with established cardiac surgery distributors.
Hospital purchasing committees now unbundle device procurement from physician preference item status, introducing value-analysis frameworks that weight valve cost against length-of-stay reduction and readmission risk. Integrated delivery networks in the United States consolidate TAVI sourcing decisions at system level rather than permitting individual cath-lab autonomy. This concentration shifts negotiating leverage toward high-volume health systems and compresses manufacturer margin structures.
Transcatheter Aortic Valve Implantation (TAVI) Market Segmentation
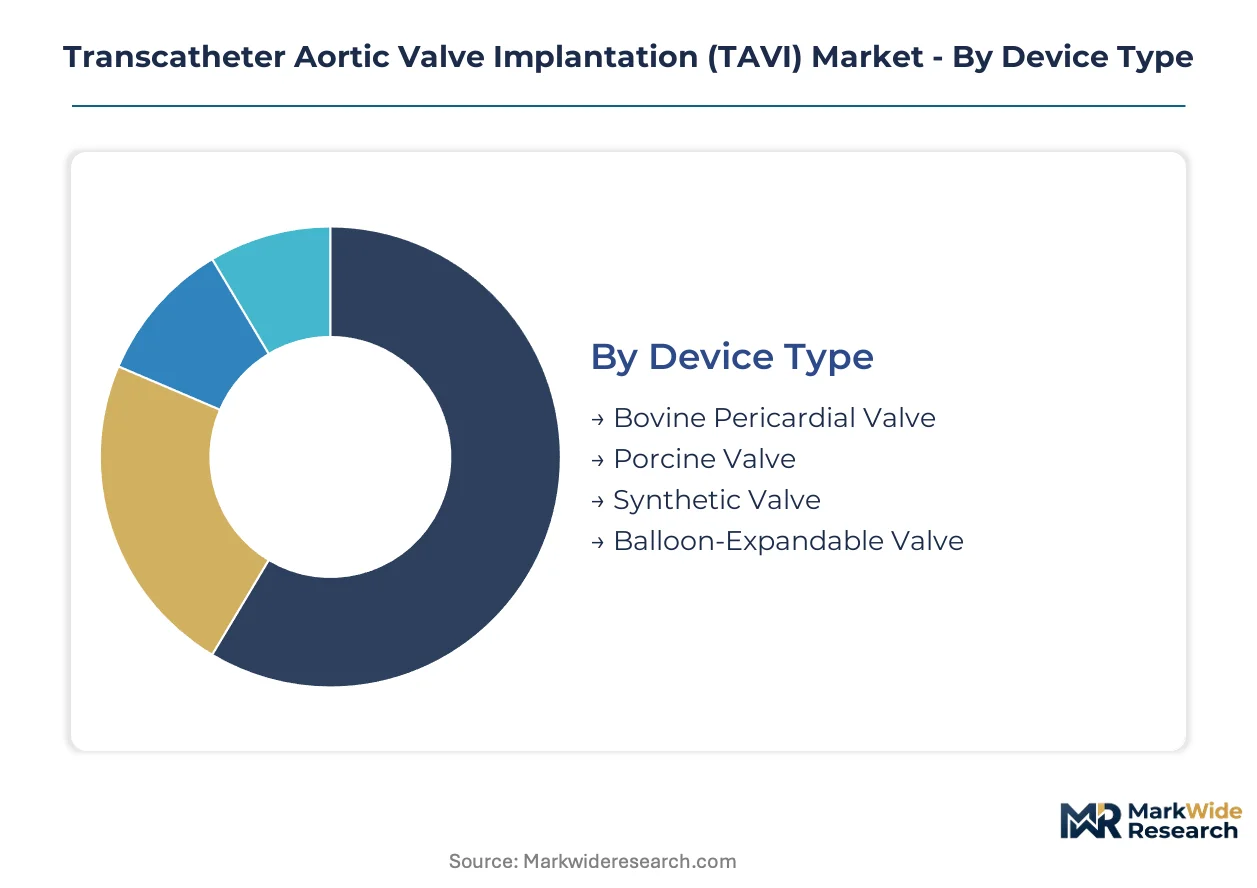
Segmentation in the TAVI market reveals how procedure economics, site-of-care migration, and technology maturation create divergent growth trajectories across device platforms and delivery configurations. Understanding these splits enables manufacturers to align R&D investment with reimbursement pathways and cath-lab infrastructure evolution.
Device Type:
Bovine pericardial valves and balloon-expandable systems dominate hospital-based procurement through established SAPIEN platform relationships, while synthetic materials and self-expanding designs penetrate ambulatory settings seeking durability differentiation.
- Bovine Pericardial Valve:Constructed from chemically fixed bovine pericardium mounted on cobalt-chromium or nitinol frames, this configuration delivers hemodynamic performance matching surgical tissue valves. Demand concentrates in German university hospitals and US academic medical centers where structural heart teams prioritize established durability data over experimental platforms.
- Balloon-Expandable Valve:Stainless-steel or cobalt-chromium stent frames expand via balloon inflation to achieve precise annular apposition, enabling predictable paravalvular leak rates. US cardiology clinics driving outpatient TAVI adoption favor this technology for its reproducible deployment mechanics and lower learning curve.
- Porcine Valve:Porcine aortic root tissue offers alternative xenograft sourcing with distinct calcification resistance profiles compared to bovine alternatives.
- Synthetic Valve:Polymer-based leaflet materials eliminate biological tissue sourcing constraints and target extended valve longevity beyond current tissue valve benchmarks.
By volume, bovine pericardial valves lead. By growth pace, synthetic valve development is ahead.
End User:
Cost tier stratification separates high-acuity hospital procedures from streamlined ambulatory workflows, with reimbursement differentials determining site-level technology adoption patterns.
- Hospitals:Academic medical centers and community hospitals with hybrid OR capabilities manage complex anatomical cases requiring surgical backup. Japanese tertiary centers concentrate volume through PMDA-mandated training requirements that restrict TAVI to designated structural heart programs.
- Cardiology Clinics:Specialized interventional cardiology practices with dedicated cath-labs capture intermediate-risk patients through streamlined pre-procedural screening. Bavarian cardiology networks demonstrate this model's scalability across Germany's dense outpatient infrastructure.
- Ambulatory Surgical Centers:CMS reimbursement expansion enables same-day discharge protocols for select patient populations.
- Research Institutions:Clinical trial sites generate pivotal durability data for regulatory submissions.
Hospital volume still dominates absolute procedure counts. Ambulatory surgical centers are expanding most quickly.
Procedure Type:
Application urgency and anatomical constraints dictate access route selection, with transfemoral penetration reshaping training requirements and device design priorities.
- Transfemoral:Percutaneous femoral artery access enables retrograde aortic valve crossing without thoracotomy, supporting conscious sedation protocols and reduced ICU utilization. US integrated delivery networks prioritize this route for outpatient migration strategies.
- Transapical:Direct left ventricular apex access through mini-thoracotomy serves patients with hostile iliofemoral anatomy. Japanese surgeons retain this capability for elderly patients with severe peripheral vascular disease.
- Subclavian:Axillary or direct subclavian artery access offers alternative vascular entry when femoral vessels prove inadequate.
- Transcarotid:Carotid artery access enables antegrade delivery in selected anatomical configurations.
Transfemoral procedures command the largest share. Transcarotid adoption is climbing the fastest.
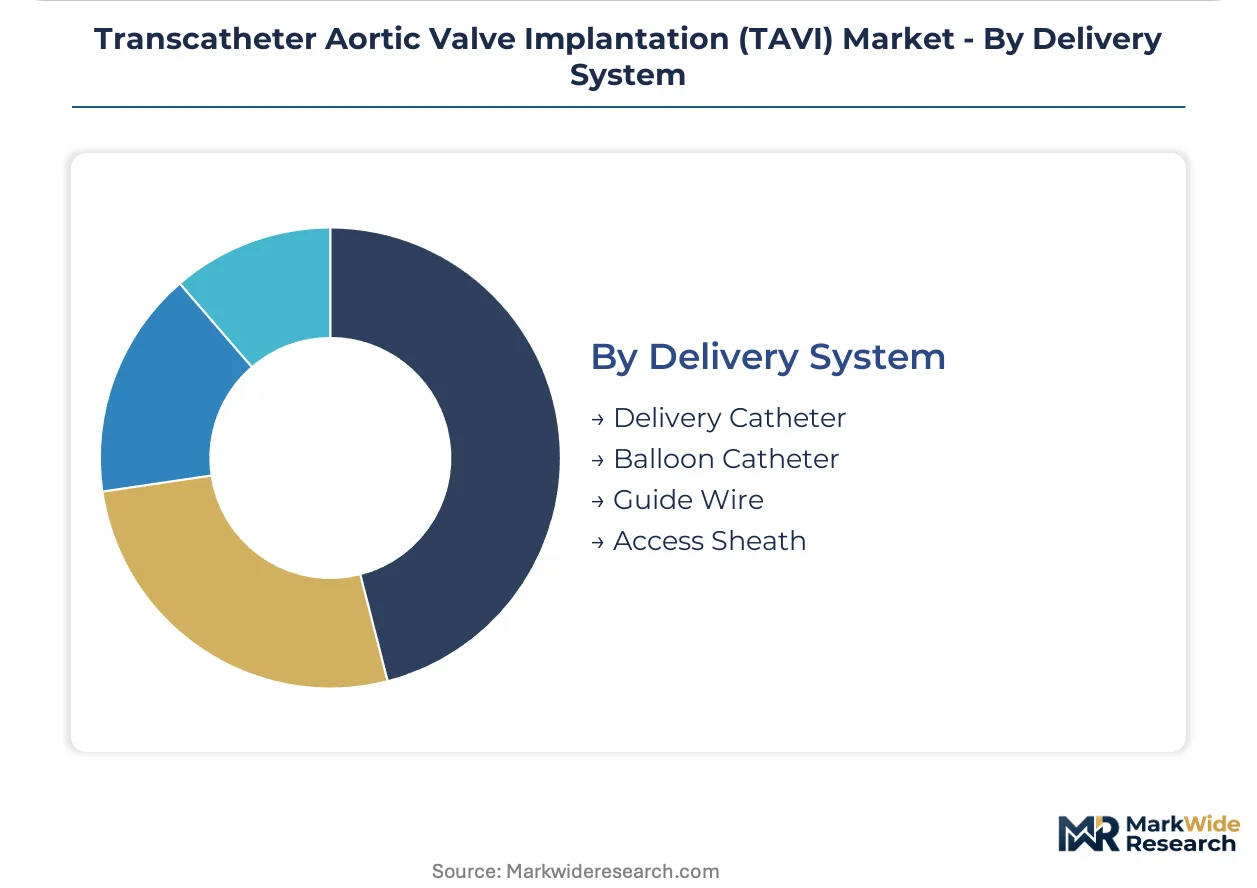
Delivery System:
Supply concentration among specialized catheter manufacturers creates margin pressure points distinct from valve frame and tissue sourcing economics.
- Delivery Catheter:Integrated sheath-valve systems with hydrophilic coatings and torque-responsive shafts enable precise positioning across tortuous vasculature. German catheter producers supply European manufacturers through established medtech clusters in Baden-Württemberg.
- Balloon Catheter:Valvuloplasty and valve deployment balloons require controlled compliance profiles to prevent annular rupture. US suppliers dominate high-pressure balloon sourcing for Edwards Lifesciences SAPIEN deployment.
- Guide Wire:Extra-support wires with atraumatic tips facilitate valve delivery system tracking.
- Access Sheath:Large-bore femoral closure systems manage hemostasis for 14-16F delivery profiles.
Delivery catheters represent the highest volume component. Access sheath innovation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic medical device corridor connecting Boston to Frankfurt anchors TAVI supply chain coordination, with dedicated air freight lanes moving finished valves and delivery systems between manufacturing clusters and cath-lab networks.
United States
CMS outpatient reimbursement expansion and integrated delivery network consolidation drive volume concentration in Texas and Florida health systems. FDA premarket approval pathways demand long-term durability trials that extend commercialization timelines for new entrants. The Minneapolis-St. Paul corridor hosts catheter manufacturing infrastructure serving Edwards Lifesciences and Medtronic distribution networks.
Germany
Baden-Württemberg's dense cath-lab infrastructure and favorable DRG coding sustain procedural volume leadership across Bavaria and the Rhine-Neckar region. EU MDR clinical evaluation requirements under CE marking impose ten-year follow-up mandates that compress development windows for domestic valve startups. Berlin-Brandenburg research hospitals generate pivotal trial data for EMA regulatory submissions.
Japan
PMDA-mandated domestic clinical studies delay product entry by 24-36 months but ensure rigorous safety validation for elderly patient populations. Tokyo and Osaka tertiary centers concentrate volume through designated structural heart program licensing. The Kansai region maintains transapical surgical backup capabilities for patients with hostile iliofemoral anatomy.
China
NMPA regulatory harmonization with international standards accelerates approval timelines for multinational valve manufacturers. Shanghai and Beijing academic medical centers build hybrid OR capacity for complex anatomical cases. The Yangtze River Delta medtech corridor attracts domestic catheter producers seeking integration with global supply chains.
Switzerland
Swissmedic's streamlined approval pathways for breakthrough devices attract early-stage valve developers seeking European market entry. Zurich and Geneva research hospitals participate in multinational durability registries generating EU MDR-compliant evidence. The Basel pharmaceutical cluster extends into structural heart device manufacturing through precision engineering capabilities.
Transcatheter Aortic Valve Implantation (TAVI) Market Vendor Landscape
Concentration sits with diversified cardiovascular conglomerates holding integrated cath-lab relationships and established valve platforms. Three strategic archetypes define competitive positioning: multinational medical device leaders with deep structural heart franchises, specialized transcatheter valve developers with focused R&D pipelines, and Asian-Pacific manufacturers leveraging cost-optimized production for emerging market penetration. Dominant competitive moves include strategic partnerships with imaging guidance technology providers and backward integration into nitinol frame and biological tissue sourcing.
Within the multinational tier, Edwards Lifesciences Corporation, Medtronic plc, and Abbott Laboratories exemplify scale-driven positioning through balloon-expandable and self-expanding platform breadth. Boston Scientific Corporation and Terumo Corporation occupy positions emphasizing geographic diversification and integrated delivery system portfolios. MicroPort Scientific Corporation represents Asia-Pacific manufacturing optimization for cost-sensitive market segments. JenaValve Technology GmbH and Cardiovascular Systems, Inc. sit within the specialized developer archetype targeting indication expansion and anatomical niche applications.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| JenaValve Technology GmbH |
| Edwards Lifesciences Corporation |
| Cardiovascular Systems, Inc. |
| Terumo Corporation |
| Medtronic plc |
| MicroPort Scientific Corporation |
| Biotronik SE & Co. KG |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory buffers for nitinol frame stock and bovine pericardium tissue lots concentrate pricing leverage with Australian and New Zealand abattoir networks, while integrated delivery networks in the United States exploit volume aggregation to compress manufacturer margins across balloon-expandable and self-expanding valve tiers.
Pricing Analysis
Volume-discount tiering structures separate academic medical center contracts from ambulatory surgical center procurement, with three-tier pricing stratification across premium SAPIEN-equivalent platforms, standard CoreValve-tier devices, and economy-positioned Asian-manufactured alternatives. Price differentiation hinges on CE marking tier under EU MDR and FDA premarket approval status, with German hospital purchasing committees exhibiting lowest sensitivity due to favorable DRG coding, while US community hospitals face acute cost compression from CMS outpatient reimbursement migration.
Supply Chain Analysis
Australia and New Zealand anchor bovine pericardial tissue sourcing through geographically concentrated abattoir infrastructure, while Germany and the United States dominate nitinol frame fabrication and catheter manufacturing clusters. Raw material dependencies rest on cobalt-chromium alloy feedstock, hydrophilic coating polymers, and sterilization-grade packaging films. Single-source vulnerability concentrates in tissue lot release testing, with distribution running through dedicated medical device air freight lanes linking Frankfurt, Minneapolis-St. Paul, and Singapore logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TAVI market positioning functions as a defensive-moat story anchored in regulatory entrenchment, where ten-year EU MDR follow-up mandates and PMDA domestic clinical study requirements create insurmountable barriers against rapid competitive replication.
For Market Incumbents: Consolidate cath-lab relationships through backward integration into imaging guidance technology and captive bovine tissue sourcing agreements that neutralize Australian abattoir supply volatility. Expand training infrastructure for structural heart team skill development to match site-of-care migration velocity. Lock in integrated delivery network contracts before ambulatory surgical center purchasing committees achieve full negotiating leverage. For New Entrants and Emerging Players: Differentiate on synthetic leaflet material platforms that eliminate xenograft sourcing constraints and target durability differentiation against tissue valve benchmarks. Penetrate Japan's intermediate-risk indication gap through early PMDA clinical study sponsorship, exploiting the 24-36 month lag against FDA and EMA approvals. Deploy direct-to-hospital sales models bypassing established GPO contracts in fragmented European markets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR compliance costs and registry infrastructure requirements will force specialty valve developers into partnership or acquisition structures with diversified cardiovascular conglomerates. Target acquisition candidates with breakthrough device designations from FDA or Swissmedic and active ten-year follow-up registries. Monitor CMS reimbursement decisions for same-day discharge protocols as the inflection signal for ambulatory surgical center volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Expanded Indication | Premarket approval pathways for intermediate-risk patients unlock US outpatient migration beyond academic medical centers. |
| CE Marking Pathway Under EU MDR | Ten-year durability follow-up commitments under MDR Article 10.4 compress commercialization windows for European market entry. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement decisions and shift negotiating leverage toward high-volume cath-lab operators. |
| Software Companion Development | Integrated imaging guidance convergence with intracardiac echocardiography enables reduced contrast protocols and same-day discharge. |
| Reimbursement Strategy | CMS Ambulatory Surgical Center Covered Procedures List inclusion determines site-of-care economics and manufacturer support model reconfiguration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA premarket approval filings, EMA regulatory submission databases, CMS Medicare reimbursement decisions, and hospital procurement contract disclosures. Interviews with structural heart program directors, cath-lab operations managers, biomedical engineers, and GPO contracts managers informed demand-side validation. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation across balloon-expandable, self-expanding, and emerging synthetic valve platforms.
Segmentation dimensions modeled include device type, end-user facility tier, procedure access route, and delivery system component category across the projection horizon. CAGRs derive from regression analysis of historic procedure volumes against reimbursement policy shifts and cath-lab infrastructure expansion rates. Forecast inputs incorporate PMDA approval timeline lag structures, EU MDR clinical evaluation requirement phase-in schedules, and integrated delivery network consolidation velocity metrics.
Material uncertainties — regulatory timeline delays, tissue supply disruptions, and reimbursement policy reversals — sit outside the modeled envelope. Forecasts reflect assumptions regarding structural heart team training pipeline expansion and synthetic valve durability validation progression. Recalibration cycles align with material shifts in CMS outpatient reimbursement determinations and EU MDR post-market surveillance mandate enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Oral Appliance Market
Medical Devices
Global Electromyography Devices Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
North America Laser Hair Removal Market