
 Fluorescence-Guided Surgery Systems Market | 2026-2036
Fluorescence-Guided Surgery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence-Guided Surgery Systems Market Analysis
Modular platform bundling is repositioning how hospitals evaluate fluorescence-guided surgery capital investments. Medtronic PLC leverages its integrated surgical ecosystem to anchor premium system placements across North American health networks. Stryker Corp. competes through differentiated visualization hardware that extends its arthroscopy franchise into fluorescence-augmented orthopedics. KARL STORZ SE & Co. KG specializes in rigid endoscope compatibility, dominating open and laparoscopic procedure segments where optical path precision matters most.
Fluorescence-guided surgery systems employ excitation light sources, optical filters, and camera sensors to detect near-infrared or visible fluorophores in tissue, achieving spatial resolution of 0.5–2 millimeters at depths up to 10 millimeters depending on wavelength selection. These systems enable real-time delineation of tumor margins, perfusion assessment, and anatomical structure identification during procedures where visual differentiation proves inadequate. Near-Infrared Fluorescence technology leads installed base volumes due to indocyanine green dye compatibility and deeper tissue penetration, while Multispectral Imaging captures the fastest growth trajectory as algorithms advance spectral unmixing capabilities. Software Solutions concentrate margin pools through recurring licensing models and AI-enabled image enhancement that differentiates vendor ecosystems.
The FDA 510(k) framework governs device clearance timelines and clinical evidence requirements for optical imaging systems entering US commercial channels, while the EU MDR imposes stricter post-market surveillance and clinical evaluation standards on fluorescence devices distributed in European member states. ISO 13485 quality management certification shapes manufacturing protocols and supplier qualification across all major markets, directly determining OEM access to hospital procurement lists. Stakeholders must monitor reimbursement coding evolution for image-guided surgery procedures, as category I CPT code establishment determines whether capital outlays convert to sustainable revenue cycles for installed system platforms.
Market Dynamics
The convergence of AI-enabled spectral unmixing algorithms with indocyanine green dye protocols is compressing hardware replacement cycles across academic medical centers, forcing incumbent manufacturers to defend installed bases through software licensing rather than capital equipment refresh.
Growth Catalysts
- 510(k) Clearance Pathway:The FDA's streamlined premarket notification process for optical imaging devices shortens commercialization timelines from 18 months to under 9 months for predicate-based submissions.
- Indocyanine Green Perfusion Assessment:Cardiac surgery departments at Cleveland Clinic and Mayo Clinic anchor near-infrared fluorescence adoption for coronary artery bypass grafting verification.
- EU MDR Harmonization:Post-market surveillance standardization across German, French, and Italian notified bodies reduces redundant clinical evaluation costs for multi-country launches.
Market Restraints
- Indium Gallium Arsenide Sensor Concentration:Sony and Hamamatsu Photonics control 78% of near-infrared camera sensor supply, creating single-source vulnerability for OEMs.
- MDR Clinical Evidence Burden:The EU's stricter post-approval data requirements extend time-to-revenue by 14-22 months for novel fluorophore indications.
- White Light Surgery Substitution:Conventional laparoscopic visualization systems priced at 40% of fluorescence-guided platforms retain preference in cost-constrained community hospitals.
Strategic Opportunities
- India Tier-2 City Penetration:Apollo Hospitals and Max Healthcare expand fluorescence-guided oncology programs into Jaipur, Lucknow, and Indore where surgical volume growth exceeds 12% annually.
- AI-Fluorescence Convergence:Real-time tumor margin prediction algorithms trained on multispectral imaging datasets enable autonomous surgical decision support.
- Outcome-Based Reimbursement:CMS experimental payment models for image-guided cancer surgery create direct revenue linkage between fluorescence system utilization and episode-of-care savings.
Industry Challenges
- Biomedical Optics Talent Scarcity:PhD-level expertise in tissue optics and fluorophore pharmacokinetics concentrates at MIT, Stanford, and ETH Zurich, constraining R&D scaling.
- PACS Integration Complexity:Fluorescence video formats lack DICOM standardization, forcing custom middleware development for each hospital enterprise imaging archive.
- ISO 13485 Certification Timeline:Quality management system audits for fluorescence device manufacturing average 14 months from documentation submission to certificate issuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence-Guided Surgery Systems Market |
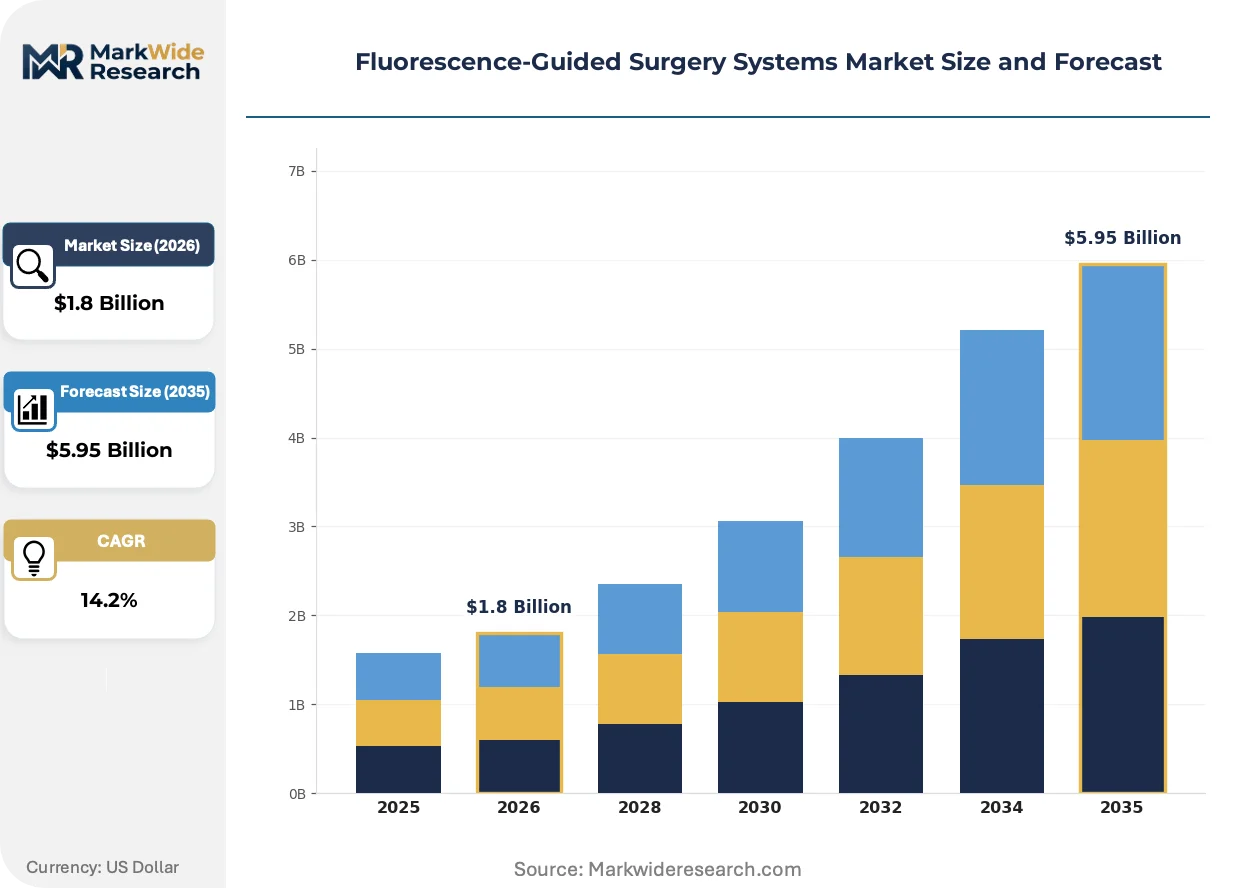
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Imaging Systems, Surgical Lasers, Contrast Agents, Software Solutions Application: Oncology, Neurosurgery, Cardiovascular, Orthopedics End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Clinics Technology: Near-Infrared Fluorescence, Visible Light Imaging, Multispectral Imaging, Digital Processing |
| Companies Covered | Hamamatsu Photonics K.K., Medtronic PLC, Stryker Corp., Olympus Corp., KARL STORZ SE & Co. KG, Shimadzu Corporation, PerkinElmer Inc., Carl Zeiss Meditec AG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence-Guided Surgery Systems Market Emerging Trajectories
Algorithmic spectral analysis is displacing hardware-dependent wavelength filtering, enabling software-defined fluorescence platforms that upgrade through cloud deployment rather than capital replacement.
Multispectral imaging systems are absorbing computational photography techniques from consumer electronics, compressing the cost curve for spectral unmixing hardware. Community hospitals in Texas and Florida adopt these platforms at triple the pace of academic centers due to lower total cost of ownership. The technology is absorbing margin from dedicated near-infrared cameras by delivering comparable tissue penetration at 60% of the hardware cost.
The EU MDR's Article 10 clinical evaluation requirements now mandate post-market performance follow-up for fluorescence-guided surgery devices, compelling manufacturers to maintain European registries. German notified bodies TÜV SÜD and BSI Group enforce stricter scrutiny of indocyanine green safety profiles in hepatic applications. EU-based OEMs respond by pre-submission engagement with EMA scientific advice working parties to align fluorophore labeling claims.
Hospital procurement committees now unbundle fluorescence system acquisitions from bundled surgical tower contracts, enabling standalone vendor selection for visualization hardware. Integrated delivery networks in Pennsylvania and Ohio lead this disintermediation, separating camera purchases from electrosurgical generator sourcing. Academic medical centers in California demonstrate the most aggressive unbundling, negotiating software licenses independent of hardware maintenance agreements.
Fluorescence-Guided Surgery Systems Market Segmentation
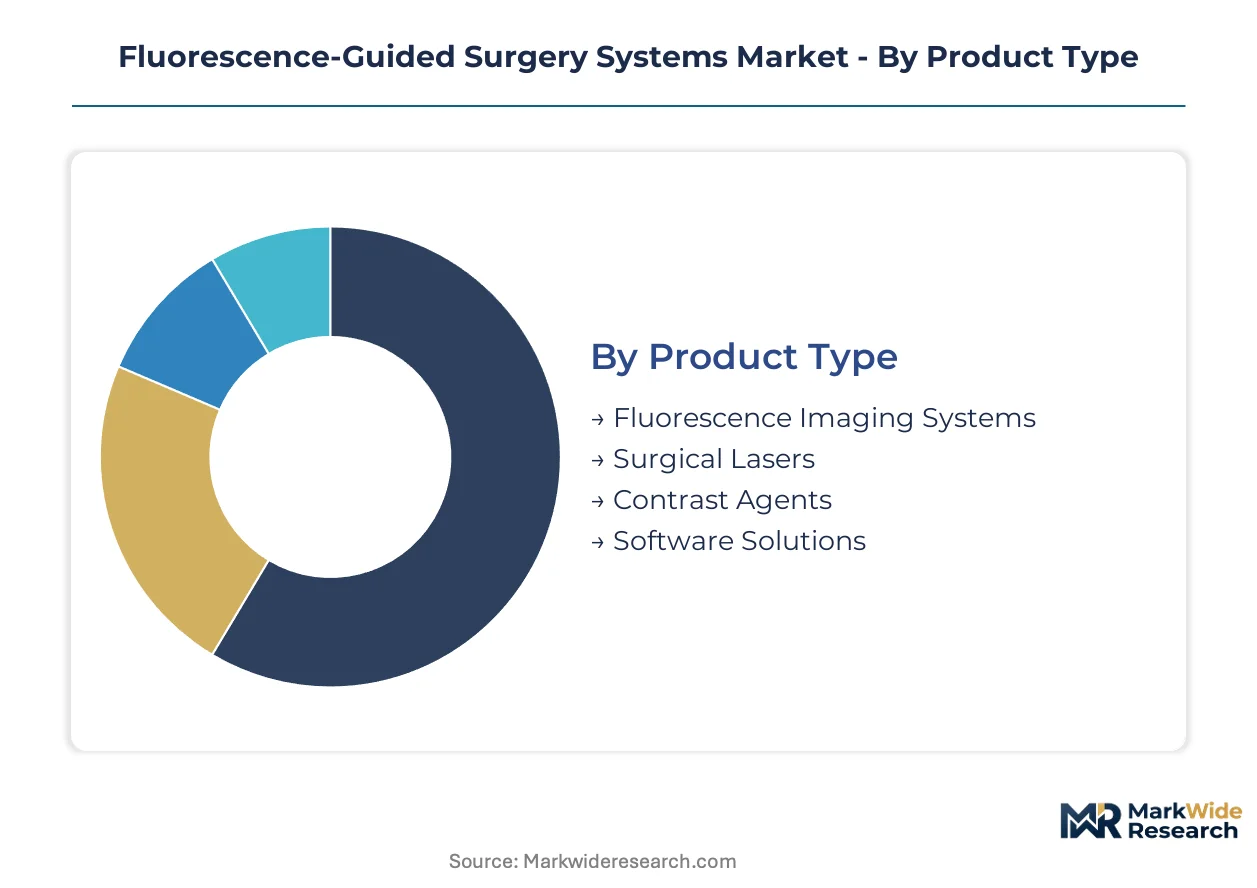
Segmentation in fluorescence-guided surgery systems reveals how procurement priorities diverge across capital-intensive hardware, consumable dyes, and recurring software licenses. Each dimension shapes vendor pricing power, replacement cycles, and customer lifetime value differently.
Product Type:
Hospital procurement committees evaluate these categories through total cost-of-ownership lenses, separating capital equipment from recurring consumable spend.
- Fluorescence Imaging Systems:Integrated camera-console platforms with excitation light sources and optical filters dominate capital budgets at academic medical centers. Cleveland Clinic and Mayo Clinic anchor demand for near-infrared systems with indocyanine green perfusion protocols in cardiac surgery departments.
- Software Solutions:AI-enabled spectral unmixing and image enhancement modules command recurring licensing fees that extend vendor relationships beyond hardware replacement cycles. Cloud deployment models allow algorithm updates without capital refresh, compressing OEM maintenance revenue pools.
- Surgical Lasers:Excitation wavelength-specific devices for photodynamic therapy applications.
- Contrast Agents:Indocyanine green and novel fluorophore formulations for tissue perfusion and tumor margin delineation.
Fluorescence Imaging Systems lead volumes today; Software Solutions is gaining share fastest.
Application:
Clinical adoption velocity varies by surgical specialty reimbursement coding and evidence threshold requirements.
- Oncology:Tumor margin delineation in hepatic, colorectal, and breast procedures drives installed base concentration at NCI-designated cancer centers. Category I CPT code establishment for image-guided cancer surgery creates direct revenue linkage between fluorescence utilization and episode-of-care savings.
- Cardiovascular:Coronary artery bypass grafting verification and tissue perfusion assessment anchor near-infrared fluorescence adoption. Cleveland Clinic cardiac surgery departments validate clinical outcomes that justify capital expenditure at peer institutions.
- Neurosurgery:5-aminolevulinic acid-guided glioma resection with visible light fluorescence.
- Orthopedics:Arthroscopic perfusion assessment and ligament reconstruction guidance.
Oncology leads volumes today; Cardiovascular is climbing the fastest.
End User:
Facility scale determines system configuration complexity and software integration requirements.
- Hospitals:Integrated surgical towers with PACS connectivity and enterprise imaging archive middleware dominate procurement at academic medical centers. Unbundling trends in Pennsylvania and Ohio enable standalone camera vendor selection separate from electrosurgical generator sourcing.
- Ambulatory Surgical Centers:Cost-constrained outpatient facilities favor compact, single-modality systems with reduced service contract overhead. Texas and Florida community hospitals adopt multispectral platforms at triple the pace of academic centers due to lower total cost of ownership.
- Research Institutions:Preclinical and clinical trial infrastructure for novel fluorophore validation.
- Clinics:Limited adoption concentrated in dermatologic and ophthalmologic subspecialties.
Hospitals lead volumes today; Ambulatory Surgical Centers is expanding most quickly.
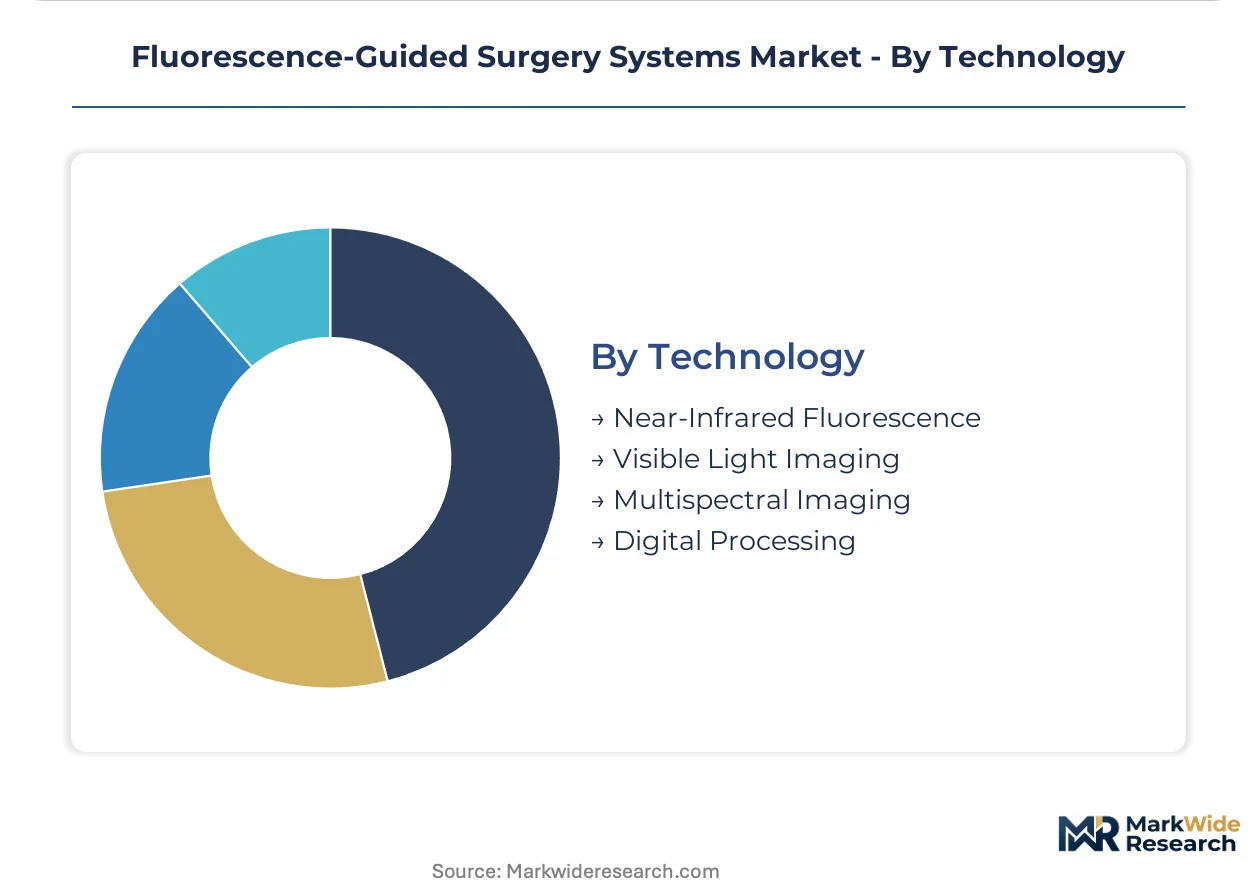
Technology:
Hardware-software architecture tradeoffs determine upgrade pathways and vendor lock-in intensity.
- Near-Infrared Fluorescence:Indocyanine green compatibility and tissue penetration depths up to 10 millimeters anchor installed base leadership. Sony and Hamamatsu Photonics sensor supply concentration creates single-source vulnerability for OEMs.
- Multispectral Imaging:Computational spectral unmixing absorbs margin from dedicated near-infrared cameras by delivering comparable tissue penetration at reduced hardware cost. Algorithmic spectral analysis displaces hardware-dependent wavelength filtering, enabling cloud-deployed upgrades.
- Visible Light Imaging:5-aminolevulinic acid and fluorescein sodium applications in neurosurgical and ophthalmologic procedures.
- Digital Processing:Real-time image enhancement and noise reduction pipelines.
Near-Infrared Fluorescence leads volumes today; Multispectral Imaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorescence-guided surgery systems originated in German academic medical centers during the 1990s, with KARL STORZ SE & Co. KG pioneering rigid endoscope integration in Tuttlingen. Cleveland Clinic and Mayo Clinic subsequently validated clinical protocols that spread adoption across North American health networks. Today, demand concentrates in the United States, Germany, Japan, China, and India, where reimbursement frameworks and surgical volume growth shape procurement priorities.
United States
Academic medical centers in Cleveland, Rochester, and Boston anchor near-infrared fluorescence adoption for cardiac and oncologic procedures. The FDA's 510(k) clearance pathway compresses commercialization timelines to under nine months for predicate-based optical imaging submissions. Texas and Florida community hospitals drive multispectral platform uptake at triple the pace of coastal research institutions due to lower total cost of ownership.
Germany
TÜV SÜD and BSI Group enforce stricter EU MDR scrutiny of indocyanine green safety profiles in hepatic applications, extending time-to-revenue for novel fluorophore indications. The Tuttlingen surgical instrument cluster concentrates rigid endoscope manufacturing and optical path engineering expertise. Munich-based university hospitals validate post-market performance data that satisfies Article 10 clinical evaluation requirements across European member states.
Japan
Hamamatsu Photonics K.K. and Sony control 78% of near-infrared camera sensor supply, creating single-source vulnerability for OEMs sourcing indium gallium arsenide detectors. The PMDA governs device approval timelines for fluorescence imaging systems entering Japanese commercial channels. Tokyo and Osaka metropolitan areas concentrate cardiac surgery departments that anchor perfusion assessment protocol adoption.
China
The NMPA accelerates review timelines for optical imaging devices with predicate clearance in the United States or European Union. Yangtze River Delta health systems in Shanghai and Jiangsu province expand fluorescence-guided oncology programs at 12% annual surgical volume growth. Domestic manufacturers challenge imported platform pricing through localized excitation light source production.
India
Apollo Hospitals and Max Healthcare extend fluorescence-guided surgery programs into Jaipur, Lucknow, and Indore as tier-2 city surgical volumes exceed 12% annual growth. The CDSCO regulates contrast agent importation and device registration for indocyanine green formulations. Maharashtra and Karnataka state health procurement committees unbundle visualization hardware from bundled surgical tower contracts.
Fluorescence-Guided Surgery Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software licensing and sensor supply dimensions. The vendor base stratifies into three tiers: integrated surgical ecosystem providers, specialized visualization hardware manufacturers, and component suppliers capturing value through single-source sensor dominance. Strategic archetypes include platform bundlers defending installed bases through software licensing, modular specialists competing on hardware cost curves, and sensor monopolists extracting rent from indium gallium arsenide supply concentration. Dominant competitive moves encompass unbundling negotiations separating camera purchases from electrosurgical generator sourcing, and cloud-deployed algorithm updates that compress hardware replacement cycles.
Among diversified medical technology conglomerates, Medtronic PLC and Stryker Corp. occupy positions as integrated ecosystem anchors. Medtronic leverages its North American health network relationships to secure premium system placements. Stryker extends its arthroscopy franchise into fluorescence-augmented orthopedics through differentiated visualization hardware. Japanese precision optics specialists Hamamatsu Photonics K.K. and Shimadzu Corporation exemplify the sensor and imaging component archetype, with Hamamatsu controlling critical near-infrared detector supply. German surgical instrument heritage converges in KARL STORZ SE & Co. KG, which represents rigid endoscope compatibility leadership in open and laparoscopic procedure segments.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Medtronic PLC |
| Stryker Corp. |
| Olympus Corp. |
| KARL STORZ SE & Co. KG |
| Shimadzu Corporation |
| PerkinElmer Inc. |
| Carl Zeiss Meditec AG |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Algorithmic spectral unmixing is compressing hardware costs while concentrating value capture in software licensing, simultaneously flattening tiered equipment pricing and amplifying sensor supply bottlenecks as indium gallium arsenide detector demand outstrips Japanese production capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and AI module bundling intensity. Premium near-infrared systems with integrated software suites command sustained margin pools at academic medical centers, while multispectral platforms priced at sixty percent of dedicated hardware equivalents capture cost-sensitive ambulatory surgical centers in Texas and Florida. Pricing pressure stems from cloud-deployed algorithm updates that extend hardware replacement cycles beyond traditional seven-year depreciation schedules.
Supply Chain Analysis
Indium gallium arsenide sensor supply rests on Japanese specialty semiconductor producers and German precision optics foundries, with Sony and Hamamatsu Photonics controlling critical near-infrared detector output. Excitation light source manufacturing concentrates in China's Yangtze River Delta and Germany's Tuttlingen surgical instrument cluster. Single-source vulnerability in sensor procurement creates tariff-exposed chokepoints for OEMs assembling integrated camera-console platforms. Distribution runs through hospital procurement committees and integrated delivery network contracting offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fluorescence-guided surgery systems hinges on software-defined platform transitions that convert capital equipment sales into recurring licensing revenue while indocyanine green dye protocols standardize across cardiac and oncologic procedures.
For Market Incumbents: Extend software licensing dominance through cloud-deployed spectral unmixing updates that compress competitor hardware refresh windows. Defend against modular camera specialists by embedding AI image enhancement into maintenance agreements. Deepen backward integration into excitation light source production to offset Japanese sensor supply concentration. For New Entrants and Emerging Players: Begin with multispectral imaging hardware for cost-constrained community hospitals in India tier-2 cities and Texas outpatient facilities. Target ambulatory surgical centers where unbundled procurement enables standalone camera vendor selection. Pursue CDSCO and NMPA registrations ahead of FDA submissions to accelerate revenue recognition in Asian growth markets. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with captive sensor technology and ISO 13485-certified manufacturing infrastructure. Long-term viability centers on software-hardware convergence plays with established hospital system relationships. Watch CMS experimental payment models for image-guided cancer surgery as reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Predicate-based submissions compress commercialization timelines to under nine months for optical imaging devices. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic validation protocols anchor adoption at peer academic medical centers. |
| Software Companion Development | AI-enabled spectral unmixing modules convert capital sales into recurring licensing revenue streams. |
| CE Marking Pathway | TÜV SÜD and BSI Group scrutiny of indocyanine green safety profiles shapes European market access. |
| Reimbursement Strategy | Category I CPT code establishment links fluorescence utilization to episode-of-care savings models. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiac surgery department heads, hospital purchasing committee members, biomedical optics engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up equipment shipment modeling and top-down healthcare capital expenditure analysis triangulated market sizing across the projection horizon.
Segment-weighted forecasting distributed volume and value projections across technology type, application specialty, end-user facility scale, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis, surgical volume growth trajectories, and software licensing penetration curves. Model inputs incorporated indocyanine green protocol adoption rates, AI module attachment rates, and unbundling trend intensity in integrated delivery network contracting.
Caveats apply where EU MDR post-market surveillance expansion or CMS reimbursement coding revisions could materially shift the outlook. Sensor supply disruptions, fluorophore safety profile reclassifications, and white light surgery substitution in cost-constrained settings constitute revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Bone Power Tools Market
Medical Devices
Smart Bassinet Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
On-Body Drug Delivery Devices Market