
 Spinal Fusion Market | 2026-2036
Spinal Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Fusion Market Outlook
Ambulatory surgical centers is bifurcating from traditional hospital inpatient settings as the dominant buyer archetype for spinal fusion procedures. Medtronic leverages its integrated spine and biologics portfolio to serve both settings with differentiated device platforms. Stryker anchors its competitive position through proprietary navigation and imaging ecosystems that reduce operative time. Zimmer Biomet competes by specializing in expandable interbody devices that address minimally invasive access constraints.
Spinal fusion denotes a surgical procedure that permanently connects two or more vertebrae using bone graft material, interbody cages, and pedicle screw fixation systems to eliminate motion at a painful spinal segment, typically requiring titanium or polyetheretherketone constructs with defined load-bearing thresholds. The procedure primarily treats degenerative pathologies, deformities, and instability where conservative management has failed. Fixation devices represent the most mature revenue pool with established pricing and hospital contracts, while biologics captures expanding margins as synthetic bone substitutes displace autograft harvesting. Minimally invasive techniques command premium positioning due to reduced blood loss and shorter recovery profiles that align with ambulatory migration.
FDA 510(k) and PMA pathways govern device commercialization in the United States, while EMA MDR requirements and CE marking obligations structure European market access with escalating clinical evidence demands. Japan's PMDA and METI coordinate reimbursement listing with technical standards through the Chuikyo process, creating a dual hurdle for foreign entrants. Stakeholders must monitor how robotic surgery integration alters capital deployment decisions and whether real-world evidence requirements expand beyond current pilot programs.
Market Dynamics
Migration toward ambulatory surgical centers is compressing inpatient procedure volumes and forcing device manufacturers to reconfigure implant portfolios for same-day discharge protocols. This structural shift demands smaller incision footprints, reduced operative time, and streamlined instrumentation kits.
Growth Catalysts
- Aging demographics in Germany, Japan, and the United States:Expanding Medicare-eligible populations and statutory health insurance systems sustain procedure demand for degenerative disc disease and spinal stenosis interventions.
- FDA 510(k) clearance streamlining:Predicate device pathways accelerate commercialization timelines for titanium interbody cages and pedicle screw systems compared with PMA requirements.
- Minimally invasive access techniques:Tubular retractor systems and percutaneous screw placement reduce blood loss and enable ambulatory eligibility, expanding addressable procedure volumes.
Market Restraints
- Titanium powder supply concentration:Additive manufacturing feedstock for patient-specific interbody devices depends on limited North American and European suppliers, creating input cost volatility.
- EMA MDR clinical evidence escalation:European notified body requirements for biologics and Class III implants extend certification timelines and inflate regulatory expenditure.
- Non-operative spine care substitution:Advanced physiotherapy protocols and neuromodulation devices capture early-stage degenerative cases before surgical thresholds.
Strategic Opportunities
- Japan's Chuikyo reimbursement acceleration:PMDA-METI coordination enables faster device listing for robotic-assisted fusion systems in tertiary hospitals.
- Synthetic bone graft convergence with 3D printing:Beta-tricalcium phosphate scaffolds integrated with additive manufacturing enable patient-matched osteoconductive matrices.
- Ambulatory surgery center direct contracting:Bypassing hospital purchasing committees through physician-owned facility partnerships captures margin compression from consolidated health systems.
Industry Challenges
- Robotic surgery system integration complexity:Capital-intensive navigation platforms require retraining surgical staff and reconfiguring OR workflows, delaying utilization ramp.
- Surgeon certification bottlenecks:Minimally invasive lateral and oblique approaches demand specialized cadaveric training programs that limit adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Fusion Market |
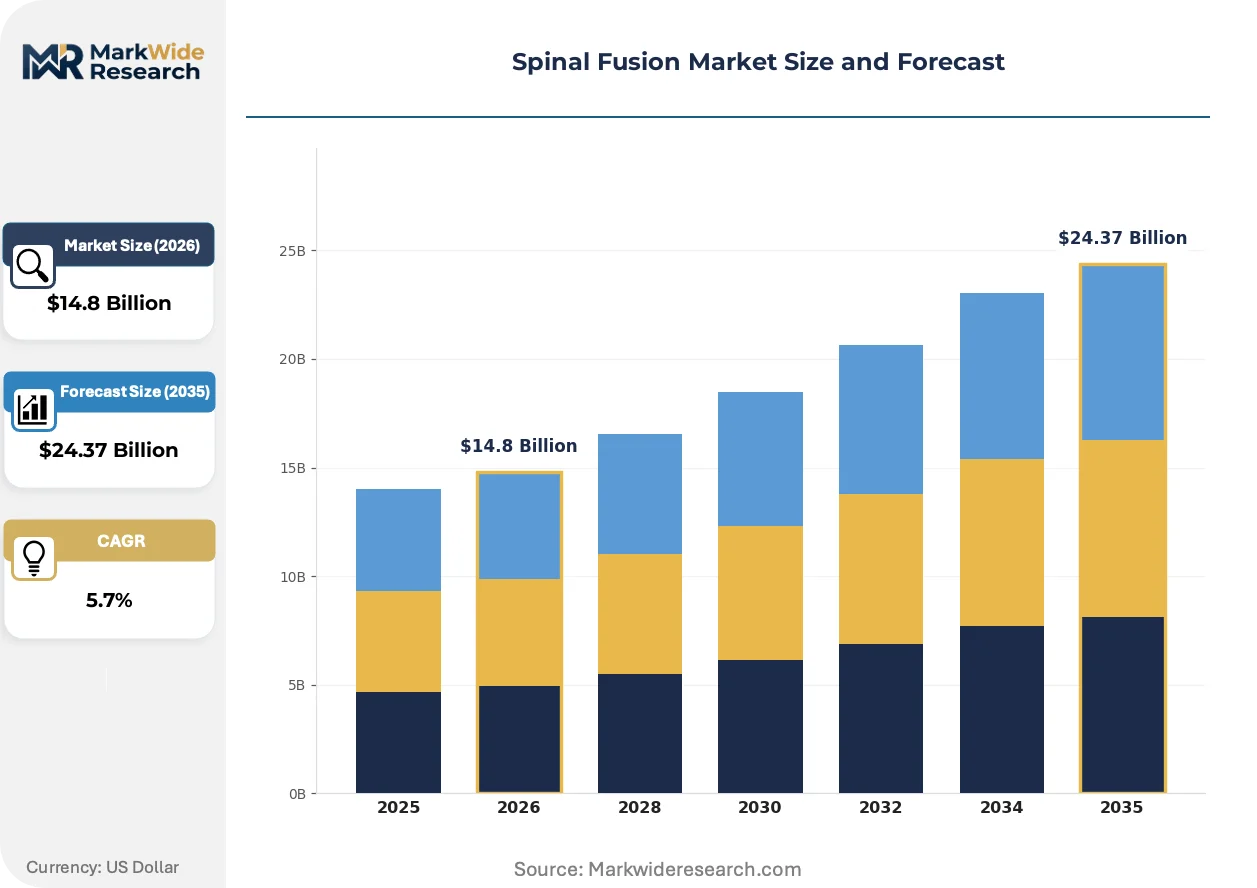
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Fusion Devices, Fixation Devices, Biologics End User: Hospitals, Orthopedic Clinics, Spine Centers, Rehabilitation Facilities Technology: Traditional Techniques, Minimally Invasive Techniques, Robotic Surgery, Imaging Systems Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, Globus Medical, NuVasive, B. Braun, Orthofix Medical, SeaSpine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Fusion Market Strategic Shifts
Device miniaturization and bioresorbable materials are redefining implant lifecycle economics while navigation-assisted placement reduces revision rates. These developments compress traditional hardware margins while opening service-based revenue streams.
Polyetheretherketone interbody cages with embedded titanium markers are displacing pure titanium constructs in lumbar fusion procedures. Ambulatory surgical centers in the United States prioritize radiolucent PEEK for postoperative imaging clarity and reduced subsidence rates. This material transition is displacing conventional machined titanium revenue pools and forcing suppliers to dual-source polymer injection molding capacity.
Japan's PMDA has tightened post-market surveillance requirements for spinal biologics under revised ministerial ordinances. Manufacturers must now submit annual safety reports and real-world usage data for demineralized bone matrix products. Synthetic bone substitute developers are responding by pre-positioning clinical registries to demonstrate non-inferiority against autograft controls.
Hospital procurement committees are unbundling implant pricing from instrumentation and biologics, forcing separate line-item negotiations. This disaggregation enables ambulatory surgery centers to source interbody devices from secondary suppliers while retaining primary vendor navigation systems. The pattern is most visible in United States Medicare Advantage networks where site-of-service differentials drive cost accounting transparency.
Spinal Fusion Market Segmentation
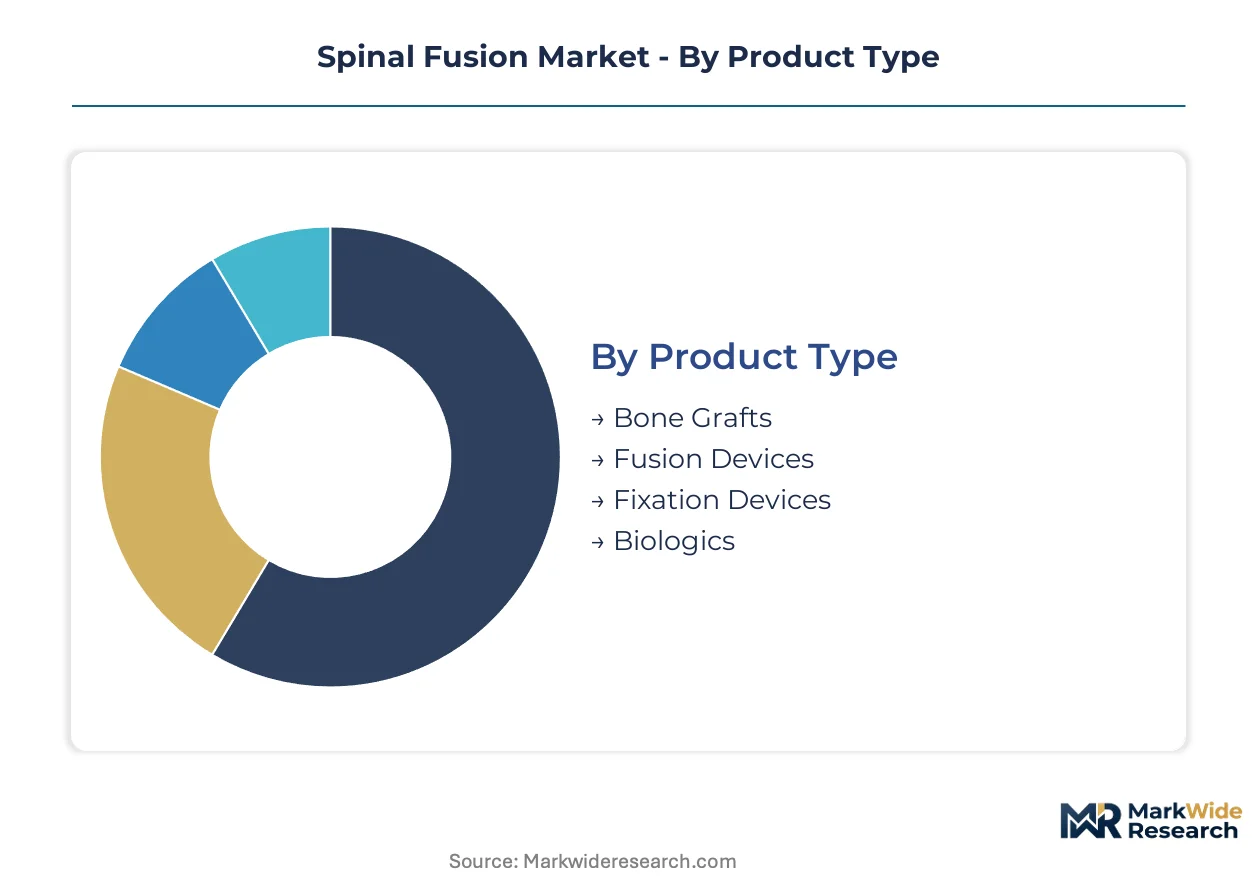
Spinal fusion device manufacturers must align product portfolios with divergent reimbursement pathways and site-of-service economics. Each segment category carries distinct regulatory burdens and margin profiles that shape competitive positioning across hospital and ambulatory settings.
Product Type:
FDA 510(k) clearance timelines vary substantially across implant categories, with Class III biologics facing PMA-equivalent scrutiny while metallic fixation devices navigate streamlined predicate pathways.
- Fixation Devices:Pedicle screw systems and rod constructs fabricated from titanium alloys or cobalt-chrome alloys provide mechanical stabilization across multiple vertebral levels. United States hospital purchasing committees negotiate multi-year contracts for these mature products, with Medicare Severity Diagnosis-Related Group reimbursement rates cementing volume concentration in tertiary centers.
- Biologics:Demineralized bone matrix and synthetic bone substitutes including beta-tricalcium phosphate scaffolds promote osteoinduction and osteoconduction. Japan's PMDA post-market surveillance requirements for these products are accelerating clinical registry investments by manufacturers seeking Chuikyo reimbursement listing.
- Fusion Devices:Interbody cages manufactured from polyetheretherketone or titanium facilitate disc space restoration and arthrodesis.
- Bone Grafts:Autograft harvested from iliac crest and allograft from tissue banks serve as biological substrate for vertebral fusion.
Established volume favors fixation devices; emerging adoption favors biologics.
End User:
Site-of-service economics are fragmenting procurement authority across consolidated health systems and physician-owned facilities.
- Hospitals:Tertiary academic medical centers and community hospitals perform complex multi-level fusions requiring extended inpatient stays. Germany's statutory health insurance system reimburses these procedures through diagnosis-related group classifications that sustain high implant utilization.
- Spine Centers:Dedicated orthopedic and neurosurgical facilities concentrate specialized surgical expertise and navigation equipment. These centers in the United States are capturing migration from hospital outpatient departments through direct-to-employer contracting and bundled payment arrangements.
- Orthopedic Clinics:Office-based practices provide preoperative evaluation and postoperative rehabilitation coordination.
- Rehabilitation Facilities:Post-acute care settings manage functional recovery following fusion surgery.
Procurement consolidation favors hospitals; margin expansion favors spine centers.
Technology:
Capital intensity and training requirements are creating adoption gradients across surgical approaches.
- Minimally Invasive Techniques:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption and blood loss. Ambulatory surgical centers in the United States are prioritizing these approaches to qualify patients for same-day discharge under Medicare's comprehensive ambulatory payment classification.
- Robotic Surgery:Navigation platforms integrate preoperative imaging with intraoperative guidance for screw trajectory planning. Japan's METI reimbursement acceleration for robotic-assisted systems is concentrating capital deployment in tertiary hospitals with high procedural volumes.
- Traditional Techniques:Open posterior approaches with direct visualization remain standard for deformity correction.
- Imaging Systems:Intraoperative CT and fluoroscopy provide real-time anatomical verification during implant placement.
Clinical volume concentrates in traditional techniques; steepest expansion trajectory belongs to minimally invasive approaches.
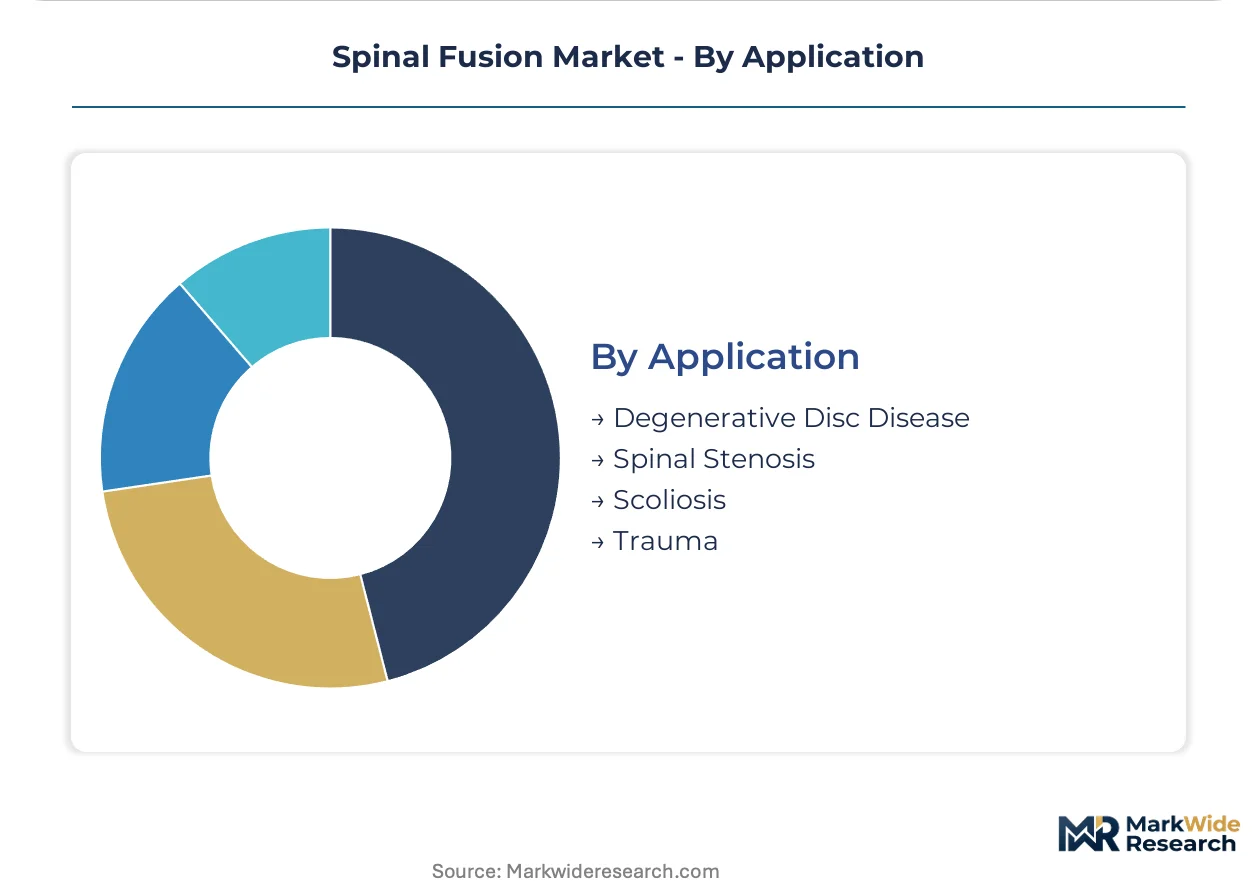
Application:
Pathology-specific reimbursement codes and clinical evidence requirements are segmenting addressable procedure volumes.
- Degenerative Disc Disease:Intervertebral disc space collapse with mechanical back pain represents the predominant surgical indication. United States Medicare coverage determinations for lumbar fusion in this indication require documented failure of six months conservative management, concentrating volume in established surgical cohorts.
- Spinal Stenosis:Central canal and foraminal narrowing with neurogenic claudication drives decompression with fusion procedures. Germany's aging demographic profile is expanding statutory health insurance expenditure for these interventions in patients over sixty-five.
- Scoliosis:Coronal and sagittal plane deformities require multi-level instrumented correction.
- Trauma:Vertebral fractures and dislocations necessitate stabilization for neural protection.
Reimbursement stability favors degenerative indications; procedure growth favors spinal stenosis interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium powder feedstock for additive-manufactured interbody devices concentrates among North American and European suppliers, while finished implant demand distributes across aging population centers with favorable reimbursement infrastructure.
United States
Medicare Advantage networks and site-of-service differentials accelerate ambulatory surgical center migration for single-level lumbar fusions. FDA 510(k) predicate pathways enable faster commercialization timelines for titanium interbody cages compared with PMA-equivalent biologics. Minneapolis and Memphis host concentrated orthopedic device manufacturing clusters serving both hospital and ASC procurement channels.
Germany
Statutory health insurance diagnosis-related group classifications sustain inpatient volume for complex multi-level procedures in patients over sixty-five. EMA MDR requirements and notified body obligations extend certification timelines for Class III spinal implants and biologics. The Rhine-Ruhr and Bavarian medical technology corridors concentrate European headquarters for major device manufacturers.
Japan
Aging demographic profiles and expanding tertiary hospital capacity drive demand for robotic-assisted fusion systems. PMDA-METI coordination through the Chuikyo process creates dual regulatory-reimbursement hurdles for foreign device entrants. Tokyo and Osaka metropolitan areas concentrate high-volume spine centers with navigation platform deployment.
United Kingdom
NHS England specialized commissioning frameworks restrict complex spinal fusion procedures to designated tertiary centers, concentrating surgical expertise. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards while streamlining national access pathways. The Oxford-Cambridge-London golden triangle anchors academic medical center research collaborations with device manufacturers.
Australia
Private health insurance penetration supports elective fusion procedures in dedicated orthopedic hospitals alongside public hospital throughput. TGA conformity assessment requirements for Class III active implantable devices mandate Australian sponsor representation for market entry. Sydney and Melbourne metropolitan regions concentrate both surgical volume and medical device distribution infrastructure.
Spinal Fusion Market Competitive Environment
Concentration sits with diversified orthopedic conglomerates that integrate fixation hardware, biologics, and navigation platforms under unified commercial organizations. Three to five integrated players command hospital purchasing committee relationships through multi-year contract structures, while mid-tier specialists compete on minimally invasive access technologies or regional ASC direct contracting. Tiered competitive dynamics separate scale-driven full-portfolio suppliers from focused interbody cage innovators and robotic navigation pure-plays. Dominant competitive moves include strategic partnerships with ambulatory surgery center management companies and technology licensing arrangements for patient-specific additive manufacturing.
Among integrated spine-biologics conglomerates, Medtronic and Stryker exemplify archetype positioning through diversified implant portfolios and proprietary navigation ecosystems. Zimmer Biomet occupies a position within the expandable interbody device specialization tier, addressing minimally invasive access constraints. These three entities anchor competitive reference points without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet |
| Globus Medical |
| NuVasive |
| B. Braun |
| Orthofix Medical |
| SeaSpine |
| Others |
Value Chain & Pricing Dynamics
PEEK polymer substitution for titanium interbody cages is redrawing raw material sourcing maps toward European polymer compounders while compressing per-unit implant economics for ambulatory surgical center buyers. This material transition simultaneously elevates radiolucency premiums and exposes manufacturers to polyetheretherketone resin price volatility from limited specialty chemical suppliers.
Pricing Analysis
Volume-discount tiering structures separate hospital system GPO contracts from ambulatory surgery center spot purchasing, with the former commanding 15-25 point spreads based on annual implant commitment thresholds. Price differentiation hinges on FDA 510(k) predicate lineage and navigation system bundling, where integrated platform vendors extract premium positioning. Cost compression in standard fixation devices is intensifying because hospital procurement committees are unbundling biologics from hardware line items. Ambulatory surgery centers exhibit highest price sensitivity due to direct-to-employer contracting pressures, while tertiary academic centers maintain lowest sensitivity through diagnosis-related group reimbursement buffers.
Supply Chain Analysis
Titanium powder feedstock chokepoints from North American additive manufacturing suppliers tether patient-specific interbody production to limited electron beam melting capacity in Ohio and Pennsylvania. Raw material dependencies span titanium sponge from Ukrainian and Russian sources, PEEK resin from Solvay and Victrex European facilities, and demineralized bone matrix from US tissue bank networks. Single-source vulnerability concentrates in beta-tricalcium phosphate ceramic precursors from Japanese chemical processors. Distribution runs through hospital purchasing committees for tertiary centers and direct physician-owned facility contracting for ambulatory migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) predicate libraries and Chuikyo reimbursement listing creates substantial switching costs for hospital procurement committees.
For Market Incumbents: Fortify hospital GPO relationships by embedding navigation software licenses within multi-year implant contracts, while deepening backward integration into titanium powder atomization to offset feedstock volatility from Eastern European supply disruptions. Prioritize PEEK injection molding capacity expansion in Germany to serve EMA MDR-compliant manufacturing requirements. For New Entrants and Emerging Players: Differentiate on patient-matched additive manufacturing for complex deformity cases where established predicate pathways offer limited anatomical fit, targeting Japan's Chuikyo reimbursement acceleration for robotic-assisted systems as the most penetrable regulatory entry point. Pursue direct ASC management company partnerships bypassing hospital purchasing committee gatekeeping. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated spine-biologics-platform conglomerates over single-product specialists. Long-term viability centers on acquiring robotic navigation pure-plays with installed base momentum in high-volume US metropolitan markets. Watch FDA real-world evidence pilot program expansion as the inflection signal for biologics regulatory pathway disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year GPO contracts with embedded navigation licensing across Medicare Advantage networks. |
| FDA 510(k) Predicate Expansion | Accelerates titanium interbody cage commercialization timelines versus PMA-equivalent biologics scrutiny. |
| Reimbursement Strategy | Positions robotic-assisted systems for Chuikyo listing in Japan's tertiary hospital expansion. |
| Software Companion Development | Integrates preoperative planning tools with intraoperative navigation to reduce screw revision rates. |
| CE Marking Pathway | Navigates EMA MDR clinical evidence escalation for Class III spinal implants in German statutory systems. |
Study Parameters
Cross-validation between primary interviews with spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, and EMA MDR notified body guidance anchors the qualitative findings. Secondary sources include hospital procurement databases, Chuikyo reimbursement listing records, and orthopedic device trade customs data. Bottom-up procedure volume modeling triangulates against top-down manufacturer revenue segmentation.
Sensitivity analysis around ambulatory surgical center migration velocity and titanium powder feedstock cost trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user site-of-service, surgical technology approach, and pathology indication. CAGRs derive from procedure volume elasticities to aging demographic penetration and reimbursement policy shifts. Forecast inputs incorporate PMDA-METI coordination timelines and EMA MDR notified body capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage site-of-service differentials or prolonged titanium supply disruption would require recalibration. Forecasts reflect assumptions regarding regulatory pathway stability and ASC capital deployment continuity. Revision becomes warranted when robotic surgery utilization rates cross tertiary hospital adoption thresholds or when EMA MDR clinical evidence demands exceed current notified body capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Pectus Bar System Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
TMJ Implants Market
Medical Devices
Gamma Knife Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
High Frequency Ventilators Market