
 India Crop Protection Chemicals Market | 2026-2036
India Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Crop Protection Chemicals Market Foresight
Aftermarket technical advisory revenue is reconfiguring margin pools away from pure product sales toward bundled agronomy services. UPL Limited leverages its deep distribution network across rural India to sustain farmer loyalty programs. BASF SE anchors premium fungicide positioning through proprietary strobilurin chemistry. PI Industries differentiates via backward integration into active ingredient synthesis, controlling cost structures that competitors cannot match.
Crop protection chemicals comprise synthetic and biological formulations designed to control pests, diseases, and weeds through active ingredients such as glyphosate, imidacloprid, or mancozeb, typically applied at grams-per-hectare dosages via foliar spray, soil drench, or seed treatment to safeguard yield volume and quality in commercial agriculture. Herbicides command the largest product type share as mechanization spreads and manual weeding costs escalate, while fungicides represent the fastest-expanding category driven by intensified horticulture cultivation and climate-induced disease pressure. Liquid formulations dominate volume due to ease of tank-mixing and spray application, though granular formats retain strong penetration in rice paddy systems where standing water complicates foliar delivery.
The Central Insecticides Board under the Ministry of Agriculture regulates registration, manufacturing, and residue limits under the Insecticides Act, while FSSAI monitors pesticide residues in food commodities, jointly elevating compliance costs for new molecule introduction. BIS certification requirements for formulated products further constrain import pathways and favor domestic production scale. Stakeholders must monitor evolving MRL harmonization with Codex Alimentarius standards and the PLI scheme's potential extension to agrochemical intermediates as signals for capital allocation timing.
Market Dynamics
The Central Insecticides Board's tightening of MRL norms under the Insecticides Act is compressing product lifecycles and forcing formulators toward novel molecule development. This regulatory pressure is reshaping competitive economics away from generic off-patent chemistry toward proprietary active ingredient synthesis.
Growth Catalysts
- PLI Scheme Extension:The Production Linked Incentive scheme's anticipated coverage of agrochemical intermediates is accelerating domestic manufacturing scale in Gujarat and Maharashtra.
- Labor Cost Escalation:Rice and wheat farmers in Punjab and Haryana are expanding herbicide applications as manual weeding costs rise beyond economic viability.
- Climate-Induced Disease Pressure:Erratic monsoon patterns are intensifying fungal outbreaks in Maharashtra's grape and pomegranate belts, driving fungicide consumption.
Market Restraints
- Import Dependency on Technicals:China supplies over 60% of India's active ingredient intermediates, creating supply concentration risk during geopolitical friction.
- FSSAI Residue Monitoring:The Food Safety and Standards Authority of India's expanded testing protocols for pesticide residues in food commodities are elevating compliance costs for exporters.
- Generic Chemistry Saturation:Glyphosate and mancozeb commoditization is compressing margins for formulators lacking backward integration into synthesis.
Strategic Opportunities
- Karnataka Horticulture Belt:Underpenetrated coffee and spice cultivation regions present white space for specialty fungicide and insecticide portfolios.
- Biopesticide Convergence:Integration of microbial formulations with synthetic chemistry is opening registration pathways under streamlined BIS certification frameworks.
- Drone Application Channels:Agricultural unmanned aerial vehicle spraying services are creating direct-to-farmer distribution bypassing traditional dealer networks.
Industry Challenges
- Registration Timeline Compression:The Central Insecticides Board's 36-48 month novel molecule approval cycle is delaying product launches against faster Asian competitors.
- Formulation Chemist Scarcity:Limited domestic talent pools in active ingredient synthesis are constraining R&D scale-up for indigenous molecule development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Crop Protection Chemicals Market |
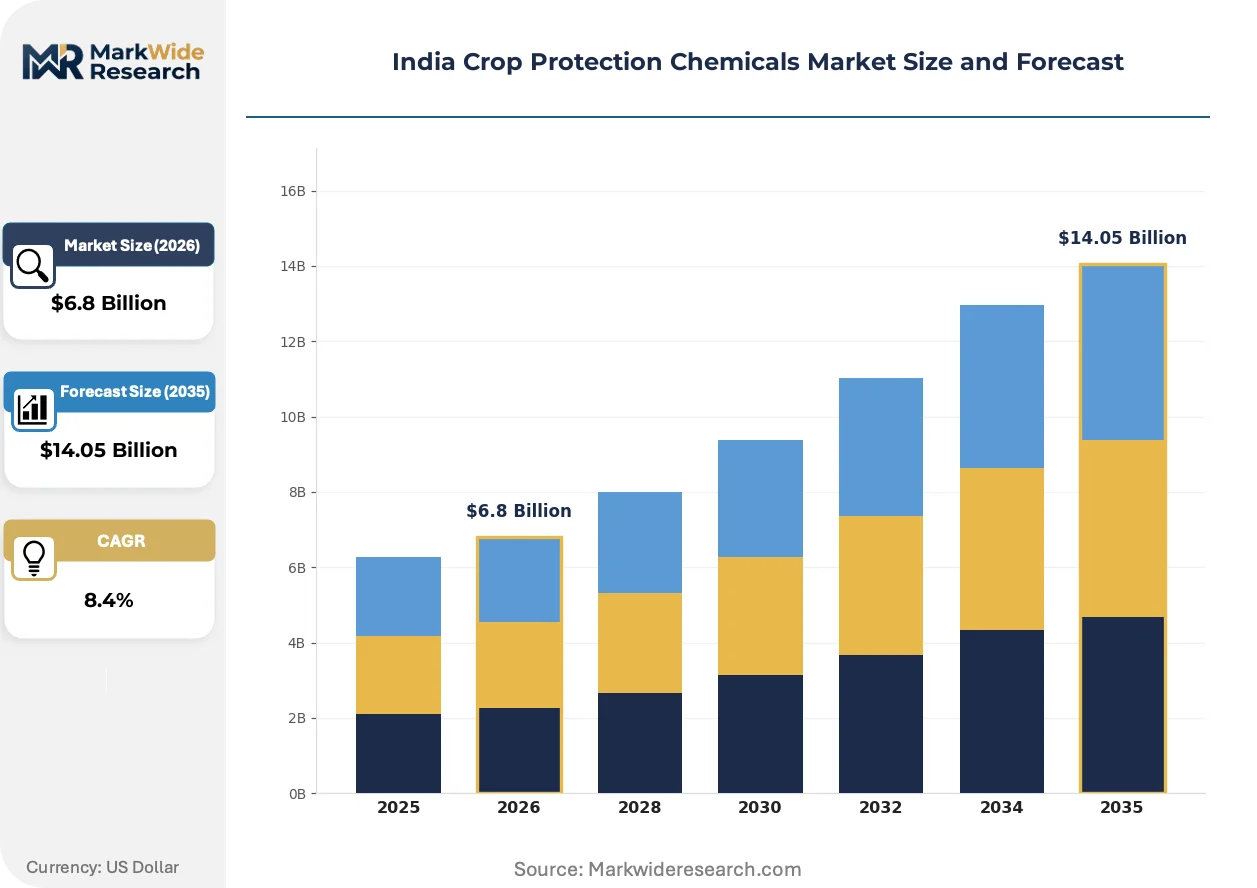
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural Fields, Greenhouses, Turf, Residential Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate End Use Industry: Crops, Horticulture, Forestry, Others |
| Companies Covered | Syngenta Group, BASF SE, UPL Limited, Indofil Industries Limited, Rallis India Limited, PI Industries, Corteva Agriscience, Crystal Crop Protection, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Crop Protection Chemicals Market Shifts & Advancements
Novel delivery mechanisms and regulatory harmonization are compressing traditional formulation advantages while opening premium positioning for integrated agronomy services. The market is witnessing active migration from commodity chemistry toward value-added bundled offerings.
Nano-emulsion and micro-encapsulation technologies are improving active ingredient stability and targeted release in foliar applications. Grape growers in Nashik and Sangli districts are adopting these formats for reduced phytotoxicity and extended residual control. The technology is migrating from specialty horticulture toward broad-acre cereal applications as cost structures normalize.
The Central Insecticides Board's MRL harmonization with Codex Alimentarius standards is elevating residue testing protocols for export-oriented commodities. This regulatory alignment is disqualifying legacy molecules from EU-bound basmati and grape shipments. Formulators serving Punjab's rice belt and Maharashtra's export horticulture clusters are prioritizing re-registration investments for Codex-compliant alternatives.
Farmer buying patterns are fragmenting across digital platforms and cooperative procurement collectives. Dealer networks in Madhya Pradesh's soybean belt are losing share to app-based aggregator models bundling credit, weather data, and input delivery. This channel disintermediation is most pronounced among younger growers in Telangana's chili cultivation zones, where smartphone penetration exceeds traditional extension service reach.
India Crop Protection Chemicals Market Segmentation
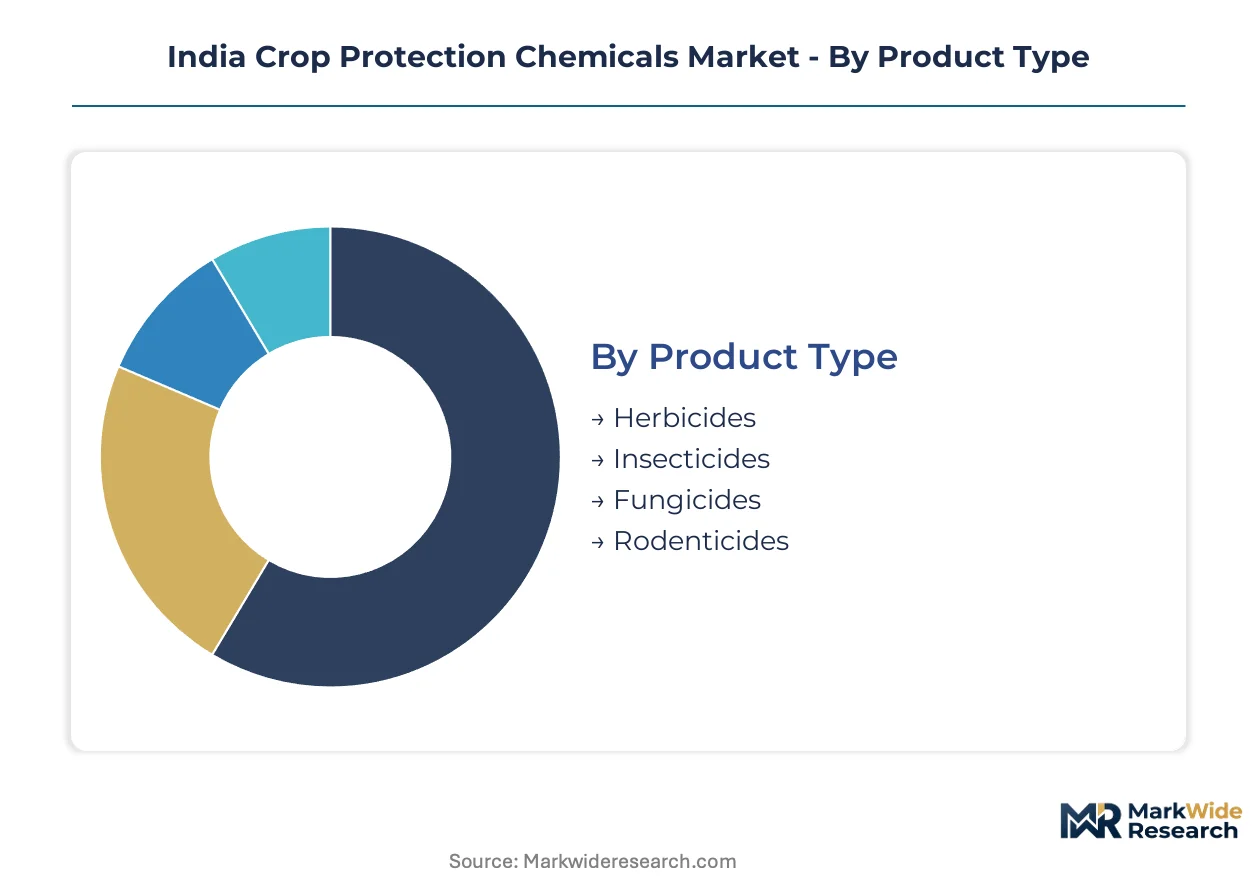
Segmentation in India's crop protection market reveals how regulatory pressure and agronomic specialization are fragmenting demand across distinct technical specifications and application contexts. Each dimension carries different margin profiles and compliance burdens that shape capital allocation priorities for formulators.
Product Type:
Herbicides turn over fastest as resistance management protocols force rotation cycles, while rodenticides exhibit the longest replacement intervals due to stable actives and limited regulatory churn.
- Herbicides:Synthetic formulations containing glyphosate, pendimethalin, or 2,4-D that disrupt plant metabolic pathways through foliar or soil application. Punjab and Haryana's rice-wheat systems are absorbing volume as labor costs for manual weeding exceed chemical intervention economics.
- Fungicides:Protectant and systemic formulations targeting oomycete and ascomycete pathogens via strobilurin, triazole, or dithiocarbamate chemistry. Maharashtra's grape and pomegranate belts are intensifying consumption as erratic monsoon patterns elevate disease pressure.
- Insecticides:Neurotoxic actives including neonicotinoids and pyrethroids targeting sucking and chewing pests across broad-acre and horticulture systems.
- Rodenticides:Anticoagulant and acute toxic baits for stored grain protection and field perimeter control, facing tightening FSSAI residue scrutiny.
Herbicides anchors the volume base while fungicides gains share at the steepest rate.
Application:
Cost tiering separates capital-intensive protected cultivation from open-field systems, with greenhouse applications commanding premium formulation grades and technical advisory bundling.
- Agricultural Fields:Broad-acre open-field deployment across cereal, oilseed, and pulse cultivation dominating tonnage consumption. Madhya Pradesh's soybean belt and Telangana's chili zones are consolidating procurement through cooperative aggregator platforms.
- Greenhouses:Controlled-environment protected cultivation requiring precision dosing and reduced phytotoxicity specifications. Karnataka's expanding polyhouse infrastructure for vegetables and flowers is absorbing specialty fungicide and insecticide portfolios.
- Turf:Golf course, sports field, and landscaping maintenance applications with aesthetic performance thresholds.
- Residential:Home garden and small-plot consumer formulations distributed through retail agri-input channels.
Agricultural Fields generates the deepest volume while Greenhouses delivers the highest margin per hectare treated.
Formulation:
Application mechanics dictate format selection, with liquid systems enabling tank-mix flexibility and granular formats solving standing-water delivery constraints in paddy systems.
- Liquid:Solution, suspension, and emulsion formats facilitating spray application and compatibility with macro- and micronutrient tank mixes. Maharashtra's horticulture clusters prefer liquid fungicides for precision disease management.
- Granular:Slow-release matrix formulations for soil incorporation or standing-water application in rice systems. Punjab's paddy belt retains strong granular herbicide penetration where foliar spray is impractical.
- Powder:Wettable powder and dust formulations for seed treatment and specialized foliar applications.
- Emulsifiable Concentrate:Oil-based carrier systems with surfactant packages for improved leaf surface adhesion and rainfastness.
Liquid dominates formulation volume while nano-emulsion and micro-encapsulation variants within liquid formats are climbing the fastest.
End Use Industry:
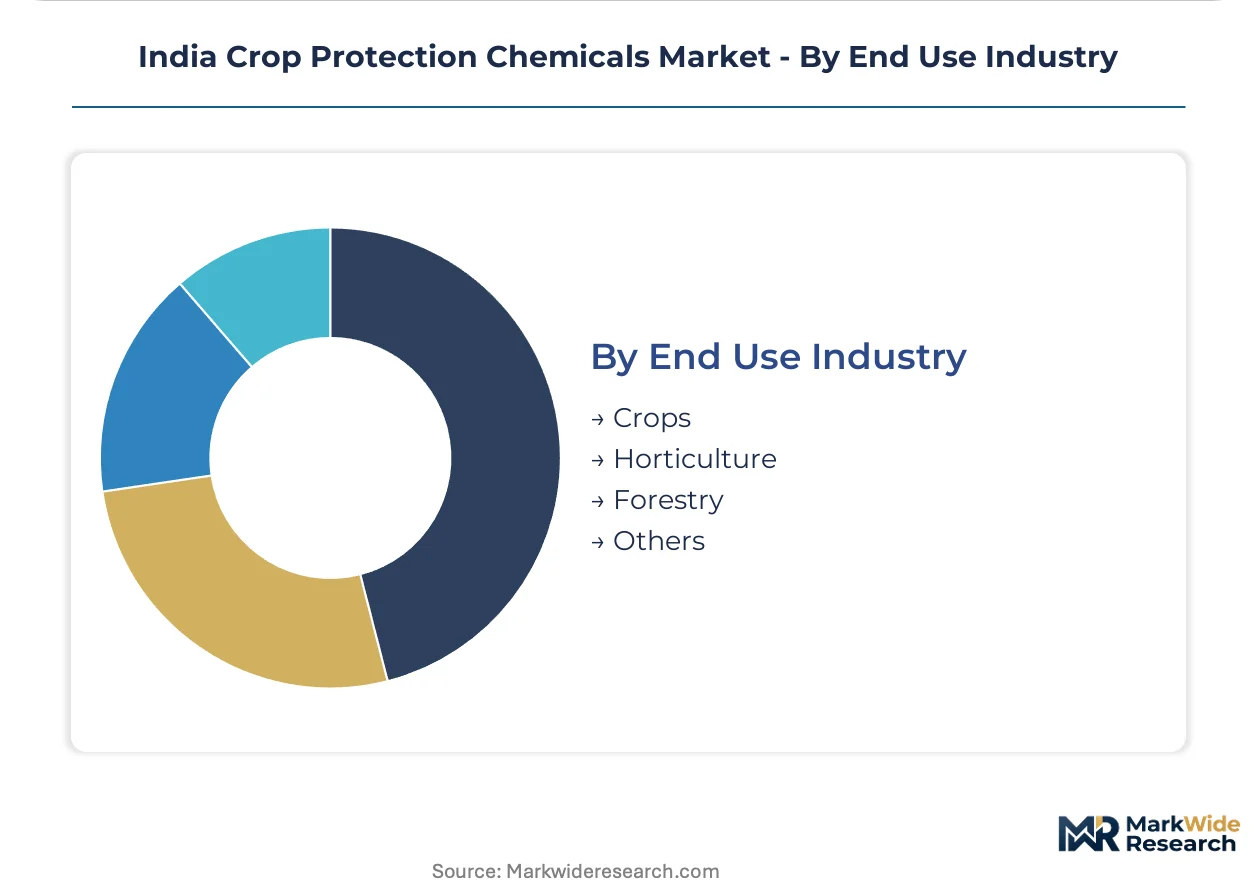
Customer maturity varies sharply, with export-oriented horticulture demanding Codex-aligned residue compliance and cereals tolerating broader MRL flexibility.
- Crops:Cereal, oilseed, and fiber cultivation representing the foundational consumption base across India's agrarian economy. Punjab's basmati rice exporters are prioritizing re-registration investments for EU-compliant molecule alternatives.
- Horticulture:Fruit, vegetable, and flower cultivation with quality-sensitive output markets and intensified pest pressure. Maharashtra's Nashik-Sangli grape corridor is driving premium fungicide adoption for export certification.
- Forestry:Plantation and natural forest protection applications with extended treatment cycles and bulk procurement patterns.
- Others:Aquatic weed control, vector management, and non-agricultural specialty applications.
Crops sustains the volume foundation while Horticulture commands the steepest expansion trajectory as export orientation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states, with Punjab and Haryana's mechanized cereal farmers accepting premium herbicide pricing while Karnataka's smallholder horticulture operators remain acutely price-sensitive.
Maharashtra
Grape and pomegranate cultivation in Nashik and Sangli districts is absorbing premium fungicide volumes as export certification requirements intensify. The state's agricultural marketing board enforces residue testing protocols aligned with EU import standards. Pune-based formulator networks are consolidating procurement for the western Maharashtra horticulture belt.
Gujarat
Cotton and groundnut cultivation in Saurashtra and Kutch regions is driving insecticide consumption amid whitefly and jassid pressure. The state's industrial policy extends PLI scheme benefits to agrochemical intermediate manufacturing. Anand and Vadodara industrial corridors are attracting technical-grade synthesis capacity from domestic formulators.
Punjab
Basmati rice exporters in Amritsar and Gurdaspur districts are prioritizing re-registration investments for EU-compliant molecule alternatives. The Central Insecticides Board's tightening MRL norms is disqualifying legacy actives from export-bound shipments. Ludhiana-based distribution cooperatives are consolidating herbicide procurement for the rice-wheat rotation system.
Karnataka
Coffee and spice cultivation in Kodagu and Chikmagalur districts presents underpenetrated white space for specialty fungicide portfolios. The state's horticulture department promotes precision spraying adoption through subsidized equipment programs. Bengaluru's agri-tech startup ecosystem is piloting drone-based application services for plantation crops.
Telangana
Chili cultivation in Warangal and Khammam districts is shifting procurement toward app-based aggregator platforms bundling credit and input delivery. The state's Rythu Bandhu income support program stabilizes farmer liquidity for input purchases. Hyderabad's digital infrastructure supports cooperative procurement collectives bypassing traditional dealer networks.
India Crop Protection Chemicals Market Competitive Landscape
Integrated multinationals and domestic synthesis specialists split the market between premium proprietary chemistry and cost-optimized generic formulations. The vendor base concentrates around three strategic archetypes: global innovators with patented active ingredient pipelines, backward-integrated Indian formulators controlling technical-grade production, and regional distributors bundling agronomy services. Competitive intensity is accelerating through M&A consolidation of dealer networks and capacity expansion in Gujarat's intermediate manufacturing corridor.
Among global innovators, Syngenta Group and BASF SE exemplify the premium-tier positioning built on proprietary strobilurin and novel mode-of-action chemistry. UPL Limited anchors the scale-driven domestic tier with extensive rural distribution infrastructure. PI Industries represents the backward-integrated specialist archetype, with in-house active ingredient synthesis capabilities that competitors relying on Chinese technical imports cannot replicate. Corteva Agriscience and Bayer AG occupy positions between these poles, balancing global R&D access with localized formulation adaptation for Indian agronomic conditions.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| UPL Limited |
| Indofil Industries Limited |
| Rallis India Limited |
| PI Industries |
| Corteva Agriscience |
| Crystal Crop Protection |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Gujarat's industrial corridor along the Anand-Vadodara belt anchors domestic technical-grade synthesis capacity, and its PLI-backed expansion is compressing import dependency premiums while elevating pricing power for backward-integrated formulators. This geographic concentration shapes downstream margin pools as Chinese intermediate costs fluctuate against rupee-denominated domestic production.
Pricing Analysis
Aftermarket agronomy services and bundled technical advisory contracts drive lifetime value beyond pure product transactions. Three-tier pricing structure across premium proprietary chemistry, standard generic formulations, and economy bulk commodities segments the market by certification grade and residue compliance level. Cost compression in generic glyphosate and mancozeb formulations is intensifying because Chinese technical import costs and rupee volatility squeeze formulator margins. Smallholder cereal farmers in Madhya Pradesh and Telangana exhibit acute price sensitivity, while export-oriented grape growers in Maharashtra accept premium fungicide pricing for EU MRL compliance.
Supply Chain Analysis
Extended payment terms from domestic formulators to dealer networks and supply-chain finance facilities for input procurement stabilize working capital across the distribution tier. Active ingredient intermediates draw from China, India, and limited European specialty chemical sources, with technical-grade synthesis feeding from aniline, chlorine, and phosphorus-based precursor chemicals. Single-source vulnerability through China's 60%-plus share of technical imports creates structural exposure during geopolitical friction or port congestion. Distribution runs through state-level dealer networks consolidating into cooperative procurement platforms and emerging drone-based direct-to-farmer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as drone application services and biopesticide convergence create novel distribution and registration pathways ahead of widespread adoption. Horticulture intensification and export certification requirements provide the underlying penetration tailwind.
For Market Incumbents: Harden proprietary molecule pipelines against generic commoditization by accelerating novel active ingredient registration with the Central Insecticides Board. Deepen captive supply of technical-grade intermediates through Gujarat capacity expansion to offset Chinese import concentration risk. Consolidate dealer network loyalty through bundled agronomy advisory services that embed switching costs beyond product transactions.
For New Entrants and Emerging Players: Karnataka's underpenetrated coffee and spice cultivation belts in Kodagu and Chikmagalur districts represent the most penetrable entry point for specialty fungicide portfolios. Drone-based application services in Telangana and Karnataka offer direct-to-farmer distribution bypassing entrenched dealer networks. Pursue streamlined BIS certification for microbial-synthetic hybrid formulations to exploit regulatory convergence opportunities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated domestic formulators with in-house synthesis capabilities and established Central Insecticides Board registration track records. Long-term viability across a 5-10 year window rests on defensible technical-grade production and novel molecule pipelines rather than pure distribution scale. Monitor PLI scheme extension announcements for agrochemical intermediates as the critical inflection signal for domestic manufacturing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical Synthesis | Gujarat-based captive production of active ingredient intermediates reduces Chinese import dependency and stabilizes margin structures. |
| Novel Molecule Registration Investment | Central Insecticides Board approval for proprietary chemistry defends against MRL-driven generic disqualification in export markets. |
| Drone Application Channel Development | Direct-to-farmer aerial spraying services in Telangana and Karnataka bypass traditional dealer network consolidation. |
| Biopesticide-Synthetic Hybrid Portfolio | Streamlined BIS certification pathways for microbial formulations open premium positioning in residue-sensitive horticulture. |
| Dealer Network Consolidation | Cooperative procurement platforms in Madhya Pradesh and Telangana aggregate smallholder demand and embed loyalty through credit bundling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Central Insecticides Board registration databases, FSSAI residue testing protocols, and PLI scheme policy documentation. Primary interviews engaged technical R&D directors at domestic formulators, procurement leads at Maharashtra grape export cooperatives, distribution channel partners in Punjab's rice belt, and regulatory affairs specialists navigating MRL harmonization. Secondary validation drew from customs import data for technical-grade intermediates, BIS certification filings, and state agricultural department input subsidy records. Bottom-up volume estimates from state-level cultivation patterns triangulate against top-down value projections from manufacturer revenue disclosures.
Forecast inputs incorporate product type segmentation by herbicide, fungicide, insecticide, and rodenticide chemistry; application context across agricultural fields, greenhouses, and protected cultivation; formulation format including liquid, granular, and nano-emulsion variants; and end-use intensity by cereal, horticulture, and export-oriented crop systems. CAGRs derive from regression analysis of historical input adoption curves against labor cost escalation, climate-induced disease pressure indices, and regulatory approval timelines. Industry-specific forecast inputs include Central Insecticides Board novel molecule approval cycle durations and FSSAI-EU MRL convergence trajectories for export commodities.
Practitioners should monitor regulatory revision triggers including PLI scheme extension coverage, Codex Alimentarius MRL harmonization pace, and Chinese technical export policy shifts for early signals of forecast deviation. Forecasts reflect assumptions regarding stable monsoon patterns, continued labor cost escalation in cereal belts, and gradual drone application adoption rates. Macroeconomic rupee volatility, geopolitical disruption of Chinese intermediate flows, or accelerated FSSAI residue enforcement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
North America Acaricides Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Iprodione Market
Crop Protection
North America Nematicides Market
Crop Protection
Europe Fungicide Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Global Termite Control Market
Crop Protection
IPM Pheromones Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Dicamba Market
Crop Protection
Germany Crop Protection Chemicals Market