
 Seed Treatment Materials Market | 2026-2036
Seed Treatment Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Treatment Materials Market Analytics
Agrichemical distribution through farm cooperatives and independent retailers is fragmenting as biological seed treatments gain shelf space alongside conventional chemistry. Bayer AG leverages its crop science pipeline to sustain integrated seed-and-trait bundling across North America. Syngenta AG anchors its position through proprietary coating technologies that improve active ingredient adhesion. BASF SE competes via microbial inoculant platforms targeting nitrogen fixation in soybeans.
Seed treatment materials encompass formulated pesticides, fertilizers, biological agents, and polymer coatings applied to seeds before planting to protect germinating embryos and enhance early vigor; active ingredient loadings typically range from grams to kilograms per metric ton of seed depending on crop value and pest pressure. Biological agents represent the fastest-expanding product type as bacterial and fungal inoculants displace synthetic chemistry in specialty and organic systems. Liquid formulations dominate volume due to compatibility with high-speed treaters, while powder carriers retain share in smallholder markets where equipment sophistication lags.
The EPA governs pesticide seed treatment registration under FIFRA, requiring efficacy and environmental fate data that lengthens development timelines for novel actives. The EU's REACH framework and MDR-linked biocidal product regulations restrict certain neonicotinoid seed treatments, redirecting R&D investment toward microbial alternatives. Brazil's ANVISA and the national environmental regulator oversee residue thresholds for exported commodities, shaping formulation choices for multinational suppliers. Stakeholders must monitor evolving pollinator risk assessments and carbon accounting methodologies that could recalibrate which treatment platforms command premium positioning.
Market Dynamics
Biological seed treatment platforms are compressing development timelines as Brazil's ANVISA and the EU's ECHA simultaneously tighten residue thresholds for synthetic actives, forcing multinational suppliers to rebuild formulation pipelines around microbial inoculants and RNA-interference technologies.
Growth Catalysts
- EU F-Gas Regulation:Mandates phase-down of fluorinated greenhouse gases used in seed coating polymers, accelerating investment in biodegradable film-forming alternatives across German and French supply chains.
- Brazilian soybean expansion:Double-cropping intensity in Mato Grosso and Goiás drives repeat treatment cycles per growing season, concentrating demand for high-load fungicide formulations.
- RNAi seed treatments:Novel mode-of-action platforms targeting corn rootworm and soybean cyst nematode are virtualizing resistance management protocols previously dependent on pyramided Bt traits.
Market Restraints
- Active ingredient concentration:Neonicotinoid load restrictions under EU REACH and parallel EPA pollinator risk assessments eliminate high-margin chemistry from multiple crop segments.
- Polymer supply concentration:Four Asian manufacturers control over 75 percent of water-soluble coating polymer capacity, exposing treaters to freight volatility and tariff exposure.
- Biological shelf stability:Microbial inoculants require cold-chain logistics and limited post-treatment storage windows, constraining distributor inventory flexibility.
Strategic Opportunities
- India's rabi-wheat belt:Subsidy reform and cooperative consolidation create entry points for premium treatment services in Punjab and Haryana, where farmer-paid input penetration remains below 15 percent.
- Carbon credit protocols:Nitrogen-fixing inoculants qualify for verified emission reduction credits under developing soil carbon methodologies, enabling price premiums in voluntary offset markets.
- Drone-based spot treatment:Convergence of precision application hardware and real-time soil sensing allows retreatment of underperforming seed lots post-planting, extending service revenue windows.
Industry Challenges
- Formulation chemist scarcity:Expertise in biological-compatible adjuvant systems lags behind microbial strain development, bottlenecking product registration pipelines.
- Treat-to-seed calibration complexity:High-speed treaters require real-time viscosity and flow-rate adjustments across heterogeneous seed lots, demanding capital upgrades at independent retail facilities.
- Cross-border residue harmonization:Divergent maximum residue limits between ANVISA, EPA, and EFSA force suppliers to maintain parallel formulation portfolios for export commodities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Treatment Materials Market |
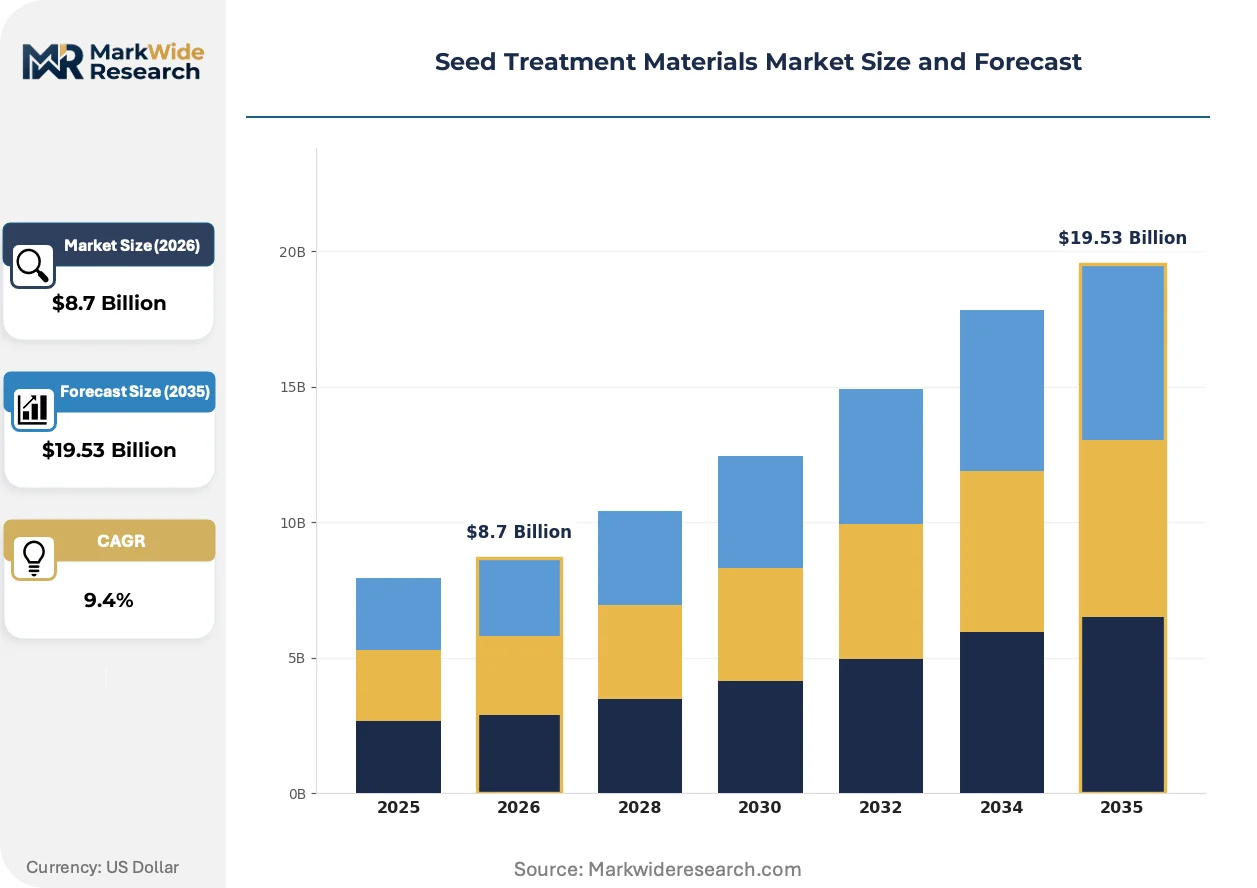
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fertilizers, Biological Agents, Coatings Form: Liquid, Granule, Powder, Gel Application Method: Drenching, Coating, Seed Immersion, Soil Injection End Use Industry: Agriculture, Horticulture, Turf Management, Others |
| Companies Covered | Syngenta AG, BASF SE, Bayer AG, Corteva Agriscience, UPL Limited, Nufarm Limited, FMC Corporation, Sumitomo Chemical, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Treatment Materials Market Evolving Landscape
Digital coating control systems and biological stabilization chemistries are converging to extend treatment efficacy windows, while regulatory pressure on conventional actives accelerates platform substitution across major agricultural economies.
Encapsulation technologies using layered lipid matrices are virtualizing the release kinetics of rhizobia inoculants, enabling single-application treatments that previously required separate priming and coating steps. Large-scale soybean processors in Iowa and Illinois have adopted these systems for identity-preserved contract production. The technology is virtualizing inventory management by compressing treatment-to-planting lead times from 72 hours to under 24 hours.
REACH authorization requirements for microplastic-containing seed coatings are forcing European suppliers to reformulate with polysaccharide-based film formers by 2027. Industrial consequence includes 18-24 month registration delays as new polymers undergo ecotoxicology review. Specialty vegetable seed producers in the Netherlands and Spain are most affected, accelerating partnerships with biopolymer developers to secure pipeline continuity.
Farmer procurement of seed treatment services is fragmenting as cooperative treaters lose exclusivity contracts to independent retailers offering biological-only portfolios. The channel disruption is most visible in Brazil's Mato Grosso do Sul, where 40 percent of soybean hectares now bypass traditional cooperative infrastructure. Input distributors are responding by acquiring microbial fermentation capacity to capture margin previously retained by multinational suppliers.
Seed Treatment Materials Market Segmentation
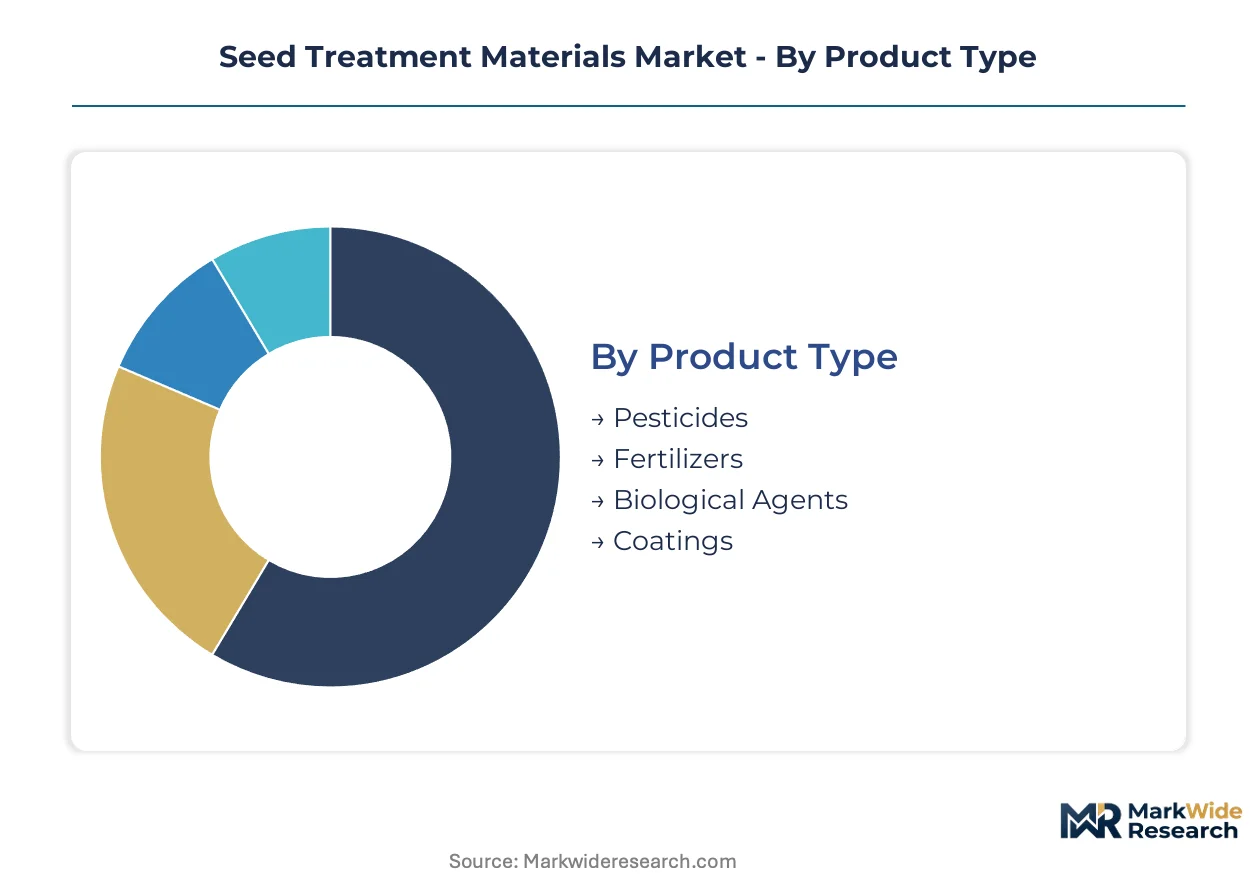
Seed treatment materials fragment across functional chemistry, physical state, application technology, and end-use intensity. Each dimension shapes procurement patterns, formulation R&D priorities, and channel economics differently across row-crop and specialty agriculture.
Product Type:
Cost tier stratification separates commodity chemistry from premium biological platforms and functional coatings.
- Pesticides:Synthetic fungicides and insecticides dominate volume in high-value row crops, with neonicotinoid reformulation pressure redirecting investment toward novel modes of action in Brazil and the US Corn Belt.
- Fertilizers:Micronutrient coatings and starter fertilizers concentrate demand in precision agriculture systems where early root vigor determines yield trajectories; double-cropping intensity in Mato Grosso drives repeat application cycles.
- Biological Agents:Bacterial and fungal inoculants are climbing the fastest as regulatory pressure on synthetic actives accelerates microbial platform adoption in specialty and organic systems.
- Coatings:Polymer and polysaccharide film formers protect active ingredient adhesion; EU REACH microplastic restrictions are forcing polysaccharide substitution by 2027.
Pesticides hold installed capacity. Biological agents are rotating up the share rankings.
Form:
Application equipment sophistication and seed lot heterogeneity determine physical state selection across treater tiers.
- Liquid:Dominates commercial volume due to compatibility with high-speed continuous treaters; viscosity calibration enables real-time flow-rate adjustments across heterogeneous seed lots in Iowa and Illinois processing facilities.
- Granule:Retains share in smallholder markets where equipment sophistication lags; carrier matrices enable delayed nutrient release in rabi-wheat systems of Punjab and Haryana.
- Powder:Compact description with at least ONE named entity.
- Gel:Compact description with at least ONE named entity.
Liquid holds installed capacity. Gel is rotating up the share rankings.
Application Method:
Volume throughput and treatment uniformity requirements separate industrial-scale coating from precision drenching and spot retreatment.
- Coating:Industrial standard for high-volume row crops; Bayer and Syngenta proprietary adhesion technologies command premium positioning in identity-preserved soybean contracts.
- Drenching:Compact description with at least ONE named entity.
- Seed Immersion:Compact description with at least ONE named entity.
- Soil Injection:Compact description with at least ONE named entity.
Coating holds installed capacity. Soil injection is rotating up the share rankings.
End Use Industry:
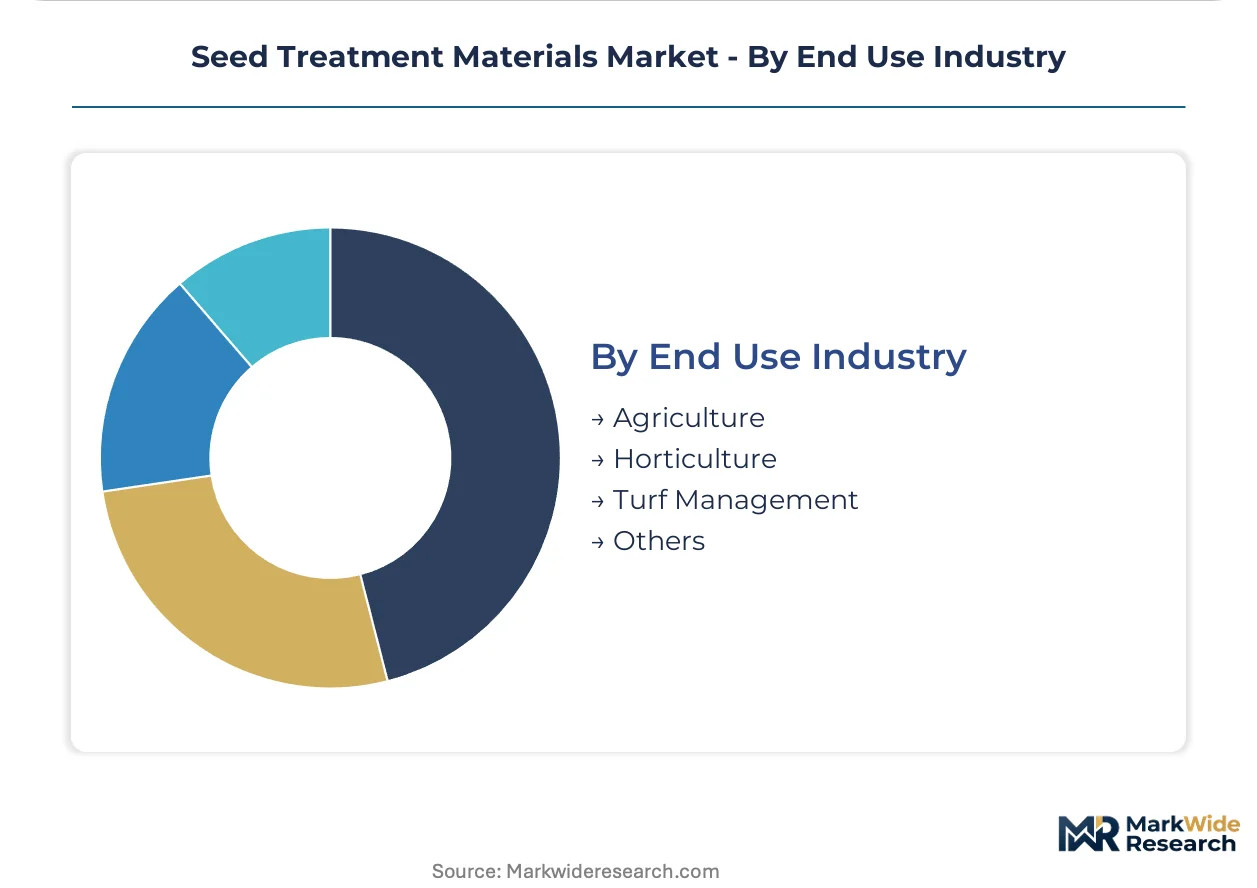
Customer type intensity and input cost recovery potential segment demand across production agriculture and managed landscapes.
- Agriculture:Row-crop production absorbs the majority of treatment volume; yield protection economics justify premium loading rates in corn-soy rotations across the US Midwest and Brazilian Cerrado.
- Horticulture:High-value vegetable and fruit propagation demands precision dosing; specialty seed producers in the Netherlands and Spain lead polysaccharide coating adoption ahead of REACH deadlines.
- Turf Management:Compact description with at least ONE named entity.
- Others:Compact description with at least ONE named entity.
Agriculture holds installed capacity. Horticulture is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium biological seed treatments command 40% higher pricing in Germany and France than equivalent formulations in India, reflecting regulatory stringency and farmer-paid input penetration gaps. This asymmetry shapes multinational supplier portfolio allocation and local manufacturing investment decisions across the forecast window.
United States
Corn-soy rotation intensity across Iowa and Illinois drives fungicide loading rates above global averages, with identity-preserved contract production demanding precision coating uniformity. The EPA's pollinator risk assessments under FIFRA are eliminating neonicotinoid seed treatments from multiple crop segments, redirecting R&D toward RNA-interference platforms. Large-scale processors in the US Corn Belt have adopted encapsulated rhizobia systems that compress treatment-to-planting lead times to under 24 hours.
Brazil
Double-cropping expansion in Mato Grosso and Goiás generates repeat treatment cycles per growing season, concentrating demand for high-load fungicide formulations on soybean seed. ANVISA residue thresholds for exported commodities force multinational suppliers to maintain parallel formulation portfolios, with the national environmental regulator tightening ecotoxicology review timelines. Independent retailers in Mato Grosso do Sul now capture 40% of soybean hectares that previously flowed through cooperative infrastructure.
Germany
The EU F-Gas Regulation mandates phase-down of fluorinated greenhouse gases in seed coating polymers, accelerating biodegradable film-forming alternative investment across German supply chains. ECHA's REACH framework restricts microplastic-containing coatings, forcing polysaccharide-based reformulation by 2027 with 18-24 month registration delays. Specialty vegetable seed producers in Bavaria and Lower Saxony lead biopolymer adoption ahead of compliance deadlines.
India
Subsidy reform and cooperative consolidation in Punjab and Haryana create entry points for premium treatment services, where farmer-paid input penetration remains below 15%. The FSSAI and central agricultural regulator oversee residue thresholds for domestic consumption and export commodities, shaping formulation choices for multinational entrants. Granule carrier matrices retain share in the rabi-wheat belt where equipment sophistication lags behind commercial processing standards.
China
Domestic soybean production expansion in Heilongjiang and Jilin provinces drives biological inoculant demand as growers seek nitrogen fixation alternatives to imported fertilizer. The Ministry of Agriculture and Rural Affairs and national standardization bodies are tightening residue monitoring for export-oriented production. Yangtze River Delta seed processors are adopting liquid formulation systems compatible with high-speed continuous treaters.
Seed Treatment Materials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying active ingredients, coating polymers, and application equipment. The supplier base concentrates around crop science conglomerates with integrated seed-and-trait pipelines, while mid-tier microbial fermentation specialists fragment the biological agent segment. Three archetypes dominate: multinational agrochemical platforms with proprietary adhesion technologies, regional treater networks acquiring fermentation capacity, and biopolymer developers securing REACH-compliant film-former supply. Competitive moves center on backward integration into microbial production and strategic partnerships with precision application hardware vendors.
Within the platform integrator tier, Syngenta AG, BASF SE, and Bayer AG exemplify contrasting strategic positions. Syngenta anchors its standing through proprietary coating technologies that improve active ingredient adhesion in high-speed processing environments. BASF competes via microbial inoculant platforms targeting nitrogen fixation in soybean systems, representing the biological pivot away from synthetic chemistry. Bayer leverages its crop science pipeline to sustain integrated seed-and-trait bundling across North American production agriculture, occupying a position that ties treatment services to germplasm licensing.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| UPL Limited |
| Nufarm Limited |
| FMC Corporation |
| Sumitomo Chemical |
| Croda International Plc |
| Others |
Value Network & Pricing Analysis
Tariff exposure between China and the United States on water-soluble coating polymers determines both three-tier pricing spreads across premium biological platforms, standard synthetic formulations, and economy generic chemistry, and the geographic reshaping of supplier manufacturing footprints toward Vietnam and Indonesia.
Pricing Analysis
Configured-to-order pricing for identity-preserved soybean contracts commands spreads of 35-50% above standard bulk treatment services. Premium-mid-economy pricing differentiation rests on certification grade under EU REACH and volume scale through cooperative procurement. Cost compression in economy synthetic tiers is intensifying because Brazilian independent retailers are bypassing traditional distribution markups. Smallholder markets in India's rabi-wheat belt exhibit highest price sensitivity, while identity-preserved contract growers in Iowa and Illinois demonstrate lowest sensitivity due to yield-linked payment structures.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for coating polymer inputs. Manufacturing concentrates in China, Germany, and Brazil, with active ingredient synthesis drawing from Indian and Chinese chemical intermediates. Raw material dependencies center on fluorinated polymer precursors, microbial fermentation substrates, and lipid encapsulation matrices. Single-source vulnerability persists for water-soluble film formers where four Asian manufacturers control dominant capacity. Distribution runs through farm cooperative treaters and independent retail networks, with channel fragmentation accelerating in Brazil's Mato Grosso do Sul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed treatment materials are entering a cyclical recovery phase as Brazilian double-cropping intensity and EU regulatory substitution mandates rebuild demand momentum for biological platforms.
For Market Incumbents: Insulate formulation pipelines from neonicotinoid load restrictions by accelerating backward integration into microbial fermentation capacity in Mato Grosso and Goiás. Secure captive supply of polysaccharide film formers ahead of EU REACH compliance deadlines to defend margin position against biopolymer developers. Channel control through exclusive treater contracts is eroding; redirect investment toward precision application hardware partnerships that extend service revenue windows. For New Entrants and Emerging Players: Establish a beachhead in India's rabi-wheat belt where farmer-paid input penetration remains below 15% and cooperative consolidation creates procurement entry points. Target carbon credit qualification services for nitrogen-fixing inoculants as the most penetrable white-space, leveraging developing soil carbon methodologies in voluntary offset markets. Pursue drone-based spot retreatment technology as the go-to-market angle, converging precision hardware with real-time soil sensing to capture post-planting service revenue. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward biopolymer developers with REACH-compliant film-former pipelines. Long-term viability across the analysis window favors platform integrators with integrated seed-and-trait bundling capabilities over standalone active ingredient suppliers. Acquisition target archetype: regional treater networks acquiring microbial fermentation capacity to capture margin previously retained by multinational suppliers. The signal to watch is ANVISA residue threshold harmonization with EPA and EFSA standards, which would force portfolio consolidation among suppliers maintaining parallel formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captures margin from multinational suppliers as Brazilian independent retailers consolidate. |
| Biopolymer Film-Former Development | Secures pipeline continuity ahead of EU REACH microplastic restrictions in German and French supply chains. |
| Precision Application Hardware Partnership | Extends service revenue windows through drone-based spot retreatment in Iowa and Illinois processing facilities. |
| Carbon Credit Protocol Qualification | Enables price premiums for nitrogen-fixing inoculants under developing soil carbon methodologies. |
| Cooperative Treater Network Acquisition | Consolidates fragmented distribution channels in India's Punjab and Haryana rabi-wheat belt. |
Research Methodology
Desk research of regulatory filings with EPA, ECHA, and ANVISA, trade customs data, and SEC disclosures from crop science conglomerates preceded structured interviews with seed treatment formulation chemists, cooperative procurement managers, independent retail distributors, and precision agriculture hardware engineers. Primary intelligence combined with secondary validation across patent databases, biocidal product registration records, and agricultural input customs classifications. Bottom-up treatment volume estimates triangulated against top-down crop acreage projections and input intensity benchmarks.
Assumptions held fixed include EU REACH microplastic restriction timelines and Brazilian double-cropping expansion rates, while variables tested included ANVISA-EPA residue harmonization speed and biological shelf stability improvements. Segmentation modeling spanned functional chemistry, physical state, application technology, and end-use intensity across the projection horizon. CAGRs derived from S-curve adoption patterns for biological platforms and replacement cycle analysis for synthetic chemistry. Industry-specific inputs incorporated pollinator risk assessment trajectories under FIFRA and carbon credit methodology development for soil carbon protocols.
Stress conditions across tariff exposure on Chinese polymer inputs, cold-chain logistics failure rates for microbial inoculants, and cooperative contract cancellation velocity in Brazil were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation schedules and technology adoption curves. Specific risks that could revise projections include accelerated neonicotinoid bans, breakthroughs in RNA-interference delivery systems, and abrupt shifts in farmer procurement channel preferences. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Iprodione Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
South America Acaricides Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Global Turf Protection Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
United States Nematicides Market
Crop Protection
Soil Fumigant Market
Crop Protection
North America Acaricides Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Indoor Vertical Farm Safe Crop Protection Chemistry Market