
 Mexico Vegetable Seed Market | 2026-2036
Mexico Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Vegetable Seed Market Foresight
Specialized plant breeding talent is unwinding constraints across Mexico's vegetable seed value chain. Bayer AG leverages its vegetable seed R&D station in Culiacán to develop heat-tolerant pepper varieties for Sinaloa's summer cycle. Syngenta Group anchors its commercial position through direct supply contracts with large-scale tomato producers in San Quintín Valley. Groupe Limagrain competes via its proprietary brassica germplasm portfolio tailored to central Mexico's altitude gradients.
Vegetable seed comprises genetically stabilized or hybridized ovules and embryos capable of germinating into edible plant species, with germination rates, pathogen load thresholds, and genetic purity percentages defining commercial grade. Hybrid seed dominates Mexico's commercial farm segment due to yield consistency and disease-stacking traits, while open-pollinated varieties sustain smallholder and home gardener niches where seed-saving remains economically rational. Organic seed occupies a narrow but expanding margin pool as SADER-aligned export operations pursue EU-equivalent certification for European retail channels.
SADER phytosanitary protocols and Mexico's Federal Law on Plant Health shape import flows and domestic multiplication requirements, forcing foreign suppliers to establish local breeding stations or partnership networks. BIS-equivalent seed quality benchmarks under the national seed certification system (SNICS) govern varietal registration and commercial release timelines. Stakeholders must monitor evolving biosafety deliberations around gene-edited vegetables, as regulatory clarity will determine whether CRISPR-derived traits enter Mexico's seed pipeline ahead of conventional transgenic approval pathways.
Market Dynamics
SADER's tightened phytosanitary certification for imported germplasm is forcing foreign seed suppliers to relocate breeding operations into Mexico or partner with domestic research stations, fundamentally restructuring competitive entry barriers.
Growth Catalysts
- Protected Agriculture Expansion:The greenhouse corridor around Querétaro is pulling hybrid tomato and pepper seed demand as commercial farms convert from open-field to controlled-environment production for year-round export cycles.
- SNICS Certification Alignment:Mexico's national seed certification system is streamlining varietal registration timelines for domestic breeders, accelerating commercial release of heat-tolerant germplasm adapted to Sinaloa's summer growing conditions.
- EU-Equivalent Organic Certification:SADER-aligned export operations pursuing European retail channel access are expanding procurement of certified organic vegetable seed, creating premium margin pools for compliant suppliers.
Market Restraints
- Import Germplasm Dependency:Mexico's vegetable seed value chain remains structurally reliant on foreign genetic material for hybrid brassica and solanaceae lines, exposing domestic multiplication networks to SADER phytosanitary clearance volatility.
- Specialized Breeding Talent Scarcity:The concentration of plant breeding expertise in Jalisco and Sinaloa research stations limits national capacity for in-house trait development, constraining domestic varietal pipeline velocity.
- Conventional Transgenic Approval Pathways:Mexico's Federal Law on Plant Health maintains restrictive frameworks for genetically modified vegetable seed, delaying market entry of yield-optimized germplasm relative to competitor export origins.
Strategic Opportunities
- Gene-Edited Vegetable Germplasm:Regulatory clarity around CRISPR-derived traits under SADER biosafety deliberations would open Mexico's seed pipeline ahead of conventional transgenic timelines, rewarding early-positioned breeding stations.
- Altitude-Graded Brassica Portfolios:Central Mexico's elevation diversity from Guanajuato to Mexico City creates demand for germplasm tailored to specific thermal zones, supporting proprietary variety development.
- Direct Supply Contracting:Large-scale tomato producers in Baja California's San Quintín Valley are consolidating procurement through exclusive breeding agreements, bypassing traditional distributor markups.
Industry Challenges
- Phytosanitary Compliance Timeline Compression:SADER's evolving import certification requirements are extending germplasm quarantine periods, forcing seed companies to maintain larger safety stocks and working capital buffers.
- Genetic Purity Verification Costs:SNICS-mandated germination rate and pathogen load testing for commercial seed release is concentrating compliance capabilities among capital-intensive laboratories in Culiacán and Guadalajara.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Vegetable Seed Market |
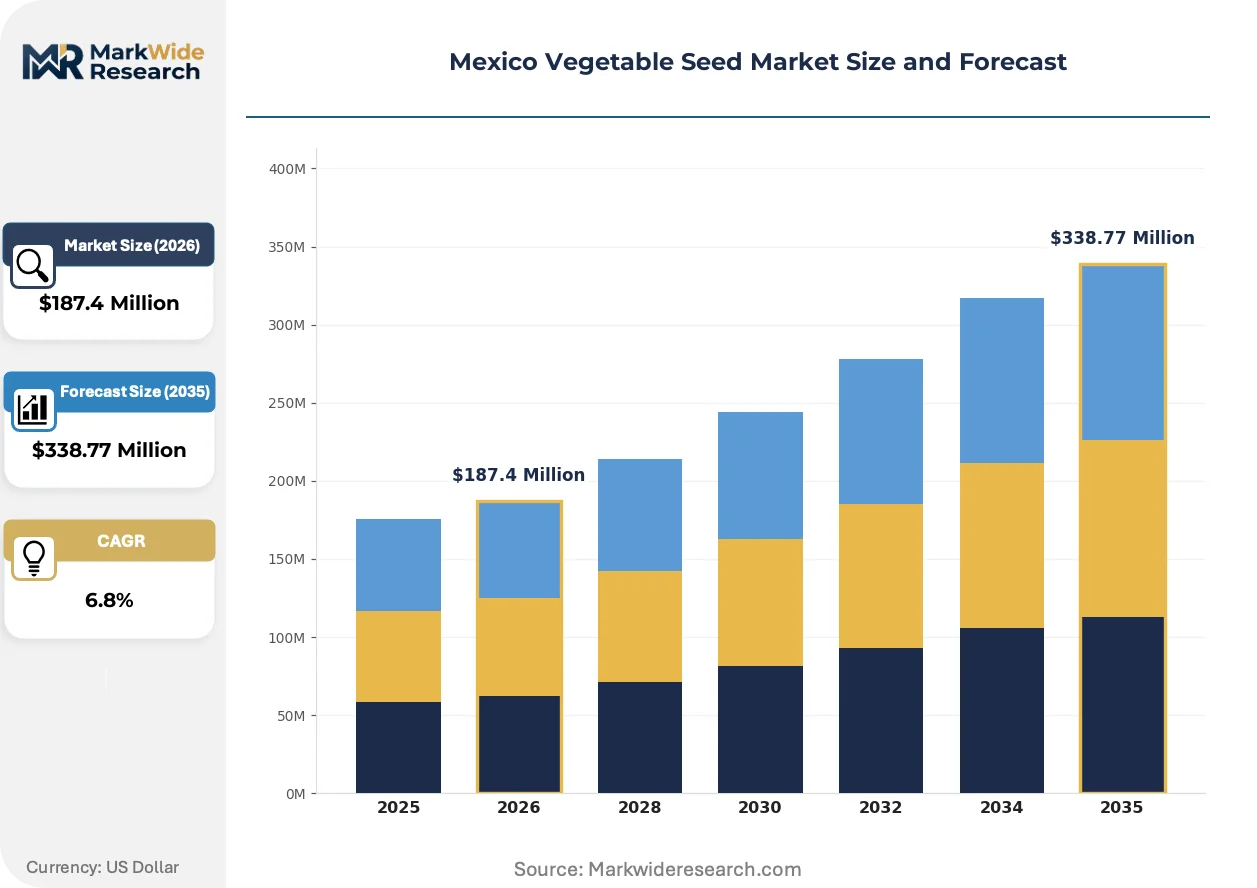
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Open-Pollinated, GMO, Organic Crop Category: Leafy Greens, Root Vegetables, Fruit Vegetables, Legumes Distribution Channel: Retail, Wholesale, Direct Supply, Online End User: Commercial Farms, Home Gardeners, Research Institutions, Agricultural Cooperatives |
| Companies Covered | Syngenta Group, Bayer AG, Groupe Limagrain, Rijk Zwaan Zaadteelt en Zaadhandel BV, Bejo Zaden BV, East-West Seed Group, Takii and Co., Ltd., Sakata Seed Corporation, Enza Zaden Beheer B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Vegetable Seed Market Shifts & Advancements
Biotechnology adoption and regulatory recalibration are splitting Mexico's vegetable seed market into parallel development tracks, with gene-edited germplasm racing against conventional breeding for commercial positioning.
Gene-editing platforms are bifurcating competitive strategy across Mexico's vegetable seed sector. CRISPR-based trait development enables precise heat-tolerance stacking in pepper lines without transgenic regulatory classification. Bayer AG's Culiacán research station and domestic breeders at INIFAP are diverging R&D budgets between gene-edited and conventional hybrid pipelines. This technological split is compressing varietal development timelines for export-oriented producers while leaving smallholder segments dependent on slower open-pollinated releases.
SADER's alignment with OECD seed certification standards is reshaping import documentation requirements for foreign germplasm suppliers. The regulatory convergence mandates third-party genetic purity verification and extended quarantine protocols for hybrid tomato and brassica seed entering through Manzanillo and Lázaro Cárdenas ports. Large-scale protected agriculture operators in Querétaro are responding by pre-positioning multiplication stock with domestic breeding partners to circumvent clearance delays.
Consolidated procurement through direct breeding contracts is displacing traditional distributor networks for commercial tomato and pepper seed in Mexico's major vegetable belts. Large-scale greenhouse operators in San Quintín Valley and open-field producers across Sinaloa are negotiating exclusive supply agreements with Syngenta Group and Groupe Limagrain research stations. This channel compression is most visible in Jalisco's commercial farm segment, where volume commitments now precede varietal development rather than following certification release.
Mexico Vegetable Seed Market Segmentation
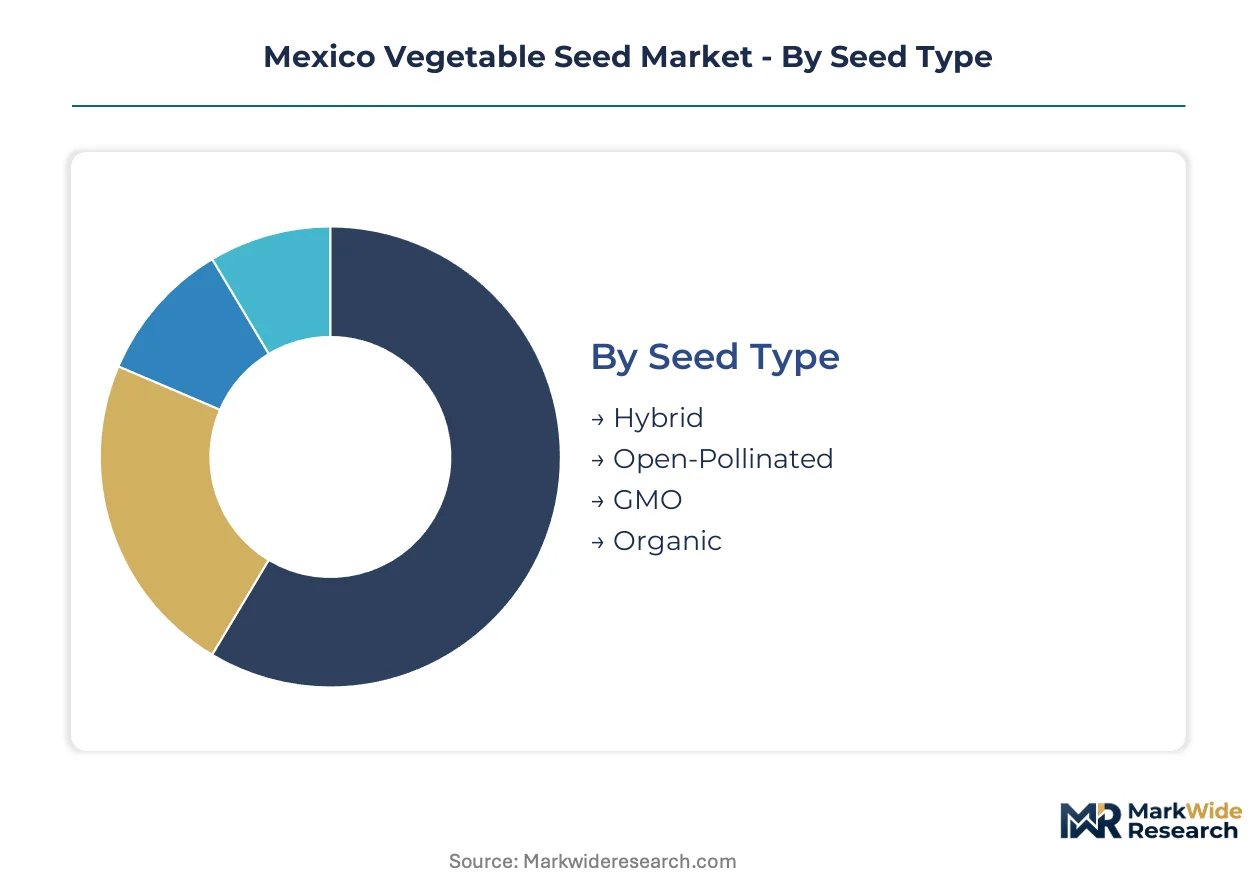
Segmentation in Mexico's vegetable seed market reveals how SADER phytosanitary pressures and protected agriculture expansion are fragmenting procurement patterns across seed types, crop categories, and distribution channels. Understanding these divides exposes where substitution threats and margin compression concentrate.
Seed Type:
Substitution pressure runs strongest against open-pollinated varieties as hybrid seed delivers yield consistency that protected agriculture operators in Querétaro now treat as non-negotiable.
- Hybrid:Genetically stabilized crosses combining two inbred parent lines deliver uniform germination rates and stacked disease resistance. Demand concentrates among commercial greenhouse operators in San Quintín Valley who require predictable harvest cycles for year-round export commitments to US retail chains.
- Open-Pollinated:Self-fertilizing varieties maintain genetic stability across generations without controlled crossing. Smallholder networks in Guanajuato's open-field belt sustain demand where seed-saving economics outweigh hybrid premium costs, though acreage is contracting.
- GMO:Transgenic germplasm incorporating engineered traits faces restrictive approval pathways under Mexico's Federal Law on Plant Health. Regulatory delays limit commercial penetration despite yield optimization potential.
- Organic:Certified organic seed meets SNICS-equivalent standards for EU-aligned export operations. SADER-certified producers in Jalisco are expanding procurement as European retail channel access commands premium pricing.
Hybrid seed anchors the volume base while organic gains share at the steepest rate.
Crop Category:
Cost tier stratification separates commodity brassica production from premium solanaceae cultivation, with margin structure dictating seed investment intensity across Mexico's vegetable belts.
- Fruit Vegetables:Solanaceae and cucurbit lines including tomato, pepper, and melon dominate commercial farm procurement. Protected agriculture corridors around Querétaro and Baja California are pulling hybrid tomato seed volumes as controlled-environment production expands.
- Leafy Greens:Brassica and lettuce germplasm spans open-field and greenhouse systems. Central Mexico's altitude gradients from Guanajuato to Mexico City create demand for thermally adapted varieties.
- Root Vegetables:Carrot, beet, and radish seed serves processing and fresh market channels. Sinaloa's commercial farms are consolidating carrot seed procurement through direct breeding contracts.
- Legumes:Bean and pea germplasm sustains smallholder and subsistence segments. Seed-saving practices limit commercial seed penetration in traditional cultivation zones.
Fruit vegetables command the revenue concentration while leafy greens are climbing the fastest on protected agriculture conversion.
Distribution Channel:
Customer type fragmentation splits procurement between consolidated commercial farms seeking volume terms and dispersed smallholders dependent on retail access.
- Direct Supply:Exclusive breeding agreements between seed developers and large-scale producers. San Quintín Valley tomato operators are bypassing distributor markups through direct contracts with Syngenta and Limagrain research stations.
- Wholesale:Bulk seed distribution through agricultural cooperatives and regional distributors. Sinaloa's commercial farm networks rely on Culiacán-based wholesalers for hybrid pepper seed.
- Retail:Packaged seed sales through agricultural supply stores and garden centers. Home gardener demand in Mexico City and Guadalajara metropolitan areas sustains open-pollinated variety availability.
- Online:E-commerce platforms for specialized and organic seed procurement. Emerging channel serving research institutions and niche organic producers seeking SNICS-certified germplasm.
Direct supply captures the margin expansion while online is expanding most quickly on procurement digitization.
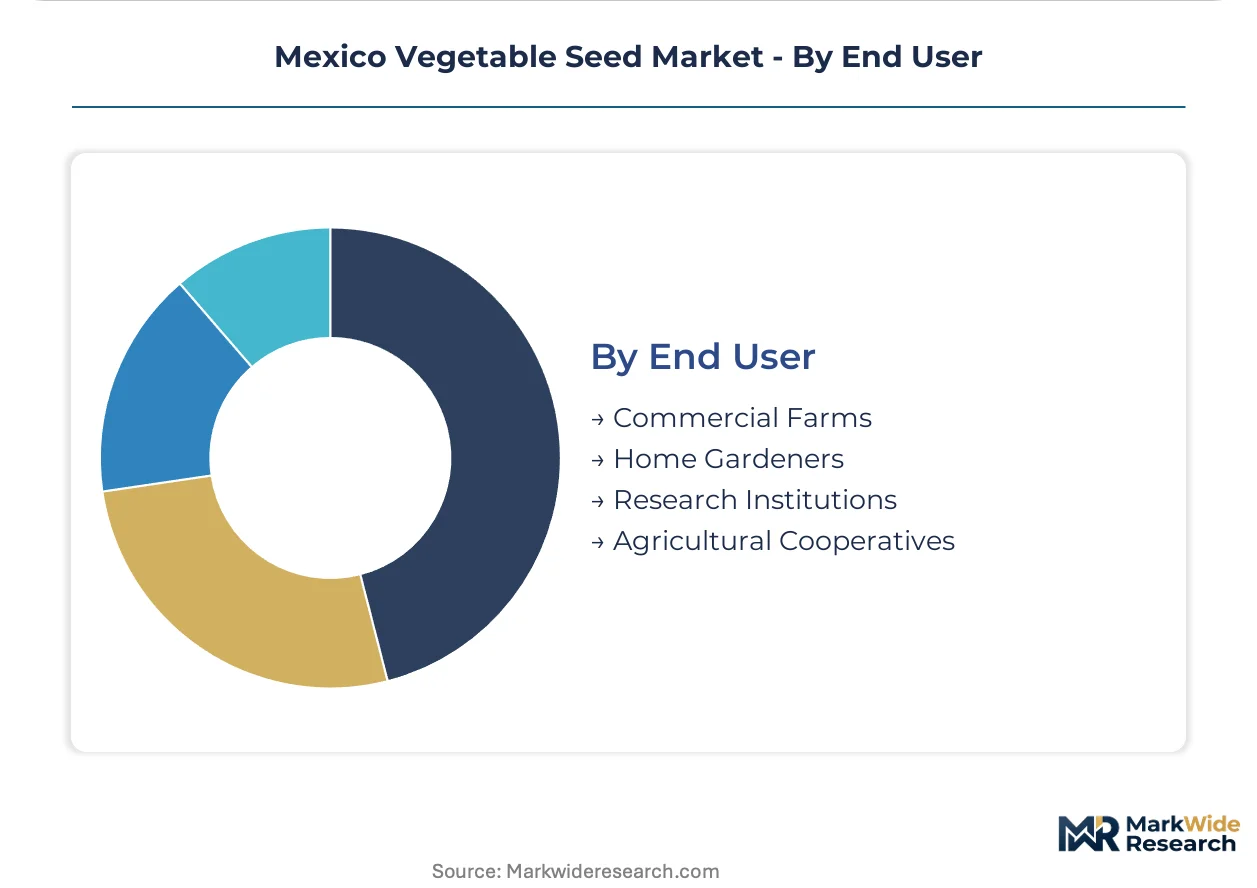
End User:
Application maturity separates established commercial farm segments from emerging research partnerships driving next-generation trait development.
- Commercial Farms:Large-scale protected and open-field operations generating export volumes. Jalisco, Sinaloa, and Baja California operations account for concentrated hybrid seed demand.
- Agricultural Cooperatives:Collective procurement entities aggregating smallholder demand. Guanajuato cooperatives are negotiating volume terms for brassica seed.
- Research Institutions:INIFAP and university breeding stations developing domestically adapted germplasm. SADER phytosanitary pressures are expanding public R&D budgets for in-house trait development.
- Home Gardeners:Residential and small-scale cultivation sustaining open-pollinated and heirloom variety demand. Urban gardening trends in Monterrey and Puebla support retail seed sales.
Commercial farms anchor the volume base while research institutions are gaining influence fastest on domestic breeding capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SADER phytosanitary protocols anchor Mexico's vegetable seed geography, concentrating breeding infrastructure and commercial multiplication networks across distinct agricultural corridors that each face specialized germplasm requirements.
Jalisco
Commercial farms across Jalisco's coastal plains are expanding hybrid tomato seed procurement for export-oriented production. SADER's tightened import certification timelines are pushing domestic breeders toward in-house trait development at INIFAP research stations. The Guadalajara metropolitan corridor hosts concentrated seed quality testing laboratories serving SNICS compliance requirements.
Sinaloa
Sinaloa's summer growing cycle generates specialized demand for heat-tolerant pepper germplasm that withstands extreme thermal stress. Bayer AG operates a dedicated vegetable seed R&D station in Culiacán to develop regionally adapted varieties. Commercial pepper producers across the Culiacán Valley are consolidating procurement through direct breeding contracts rather than traditional wholesale channels.
Baja California
Large-scale tomato producers in San Quintín Valley are converting open-field acreage to controlled-environment systems requiring hybrid seed with predictable germination uniformity. Syngenta Group anchors its commercial position through exclusive supply contracts with greenhouse operators serving US retail chains. The coastal corridor's year-round production cycles demand continuous seed availability that bypasses import quarantine volatility.
Guanajuato
Guanajuato's open-field vegetable belt sustains demand for brassica germplasm adapted to central Mexico's altitude gradients. Agricultural cooperatives are negotiating volume terms for thermally diversified cabbage and cauliflower seed portfolios. The León-Irapuato corridor maintains Mexico's highest concentration of smallholder networks where seed-saving economics still outweigh hybrid premiums.
Querétaro
Querétaro anchors Mexico's protected agriculture greenhouse corridor where hybrid tomato and pepper seed demand concentrates among export-oriented operations. SADER-aligned producers pursuing EU-equivalent organic certification are expanding procurement of certified organic vegetable seed. The El Marqués industrial zone hosts multiplication facilities that pre-position stock to circumvent Manzanillo port clearance delays.
Mexico Vegetable Seed Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Mexico's vegetable seed market, with the upper tier commanding direct supply relationships with large-scale commercial farms while specialists occupy niche germplasm segments. The structure reflects SADER phytosanitary pressures that reward local breeding infrastructure over import-dependent models. Three archetypes dominate: integrated multinational breeders with Mexican R&D stations, regional specialists with proprietary germplasm portfolios, and domestic research institutions expanding commercial multiplication capacity. Competitive positioning hinges on exclusive breeding contracts with protected agriculture operators and SNICS certification alignment for accelerated varietal release.
Among integrated multinational breeders, Syngenta Group, Bayer AG, and Groupe Limagrain occupy positions exemplifying the direct-contracting archetype. Syngenta Group represents the scale-driven approach through its commercial anchoring in Baja California's San Quintín Valley. Bayer AG exemplifies R&D-forward positioning with its Culiacán research station developing heat-tolerant germplasm. Groupe Limagrain occupies the specialty portfolio tier through its proprietary brassica germplasm adapted to central Mexico's altitude diversity. These three companies collectively illustrate how foreign suppliers are restructuring Mexican operations around local breeding capacity to satisfy SADER phytosanitary requirements.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| Groupe Limagrain |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Bejo Zaden BV |
| East-West Seed Group |
| Takii and Co., Ltd. |
| Sakata Seed Corporation |
| Enza Zaden Beheer B.V. |
| Others |
Supply & Pricing Matrix
Hybrid seed displacement of open-pollinated varieties across Jalisco and Sinaloa commercial farms simultaneously concentrates supply geography around Culiacán and Guadalajara breeding stations and compresses pricing economics for uncertified germplasm. This substitution dynamic tightens margin structures for distributors while rewarding vertically integrated breeders with SNICS-aligned multiplication capacity.
Pricing Analysis
Price spreads between Sinaloa's heat-tolerant pepper seed and standard brassica lines in Guanajuato reflect contract-based long-term offtake structures that lock in volume commitments ahead of varietal release. Price differentiation hinges on SNICS certification grade and greenhouse operator scale, with protected agriculture buyers in Querétaro showing least sensitivity due to export contract premiums. Pricing pressure runs downward for open-pollinated retail seed as hybrid penetration accelerates in commercial segments.
Supply Chain Analysis
Manzanillo port clearance bottlenecks tether germplasm flows to extended quarantine protocols that strain working capital buffers across import-dependent distributors. Supply concentration rests on the Netherlands, Israel, and domestic multiplication networks in Culiacán for hybrid tomato and pepper parent lines. Raw material dependencies include proprietary inbred parent stock, SNICS-certified organic foundation seed, and CRISPR-edited trait packages. Tariff exposure compounds single-source vulnerability for brassica germplasm. Distribution runs through exclusive breeding contracts with San Quintín Valley operators and Culiacán-based wholesale cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's vegetable seed market represents early-cycle expansion driven by protected agriculture conversion in Querétaro and Baja California, where greenhouse infrastructure buildout pulls hybrid germplasm demand ahead of domestic breeding capacity maturation.
For Market Incumbents: Shield proprietary germplasm positions through backward integration into multiplication facilities near El Marqués and Culiacán, capturing margin otherwise lost to import quarantine delays. Deepen SNICS certification pipelines to accelerate varietal release timelines against gene-editing entrants. Secure exclusive supply contracts with consolidating San Quintín Valley tomato operators before channel compression completes.
For New Entrants and Emerging Players: Organic certification service gaps among SADER-aligned export operations in Jalisco create white-space entry points for SNICS-accredited germplasm specialists. Target altitude-graded brassica portfolios for Guanajuato cooperatives underserved by multinational heat-tolerance programs. Pursue direct online procurement platforms for research institutions seeking CRISPR-edited trait packages outside conventional distributor markups.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors domestic breeding stations with established SADER phytosanitary compliance infrastructure. Long-term viability over a 5-10 year horizon rests on regulatory clarity for gene-edited vegetables and protected agriculture acreage expansion rates. Watch SADER biosafety deliberations on CRISPR classification as the critical inflection signal determining whether gene-edited pipelines outpace conventional hybrid development timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| SNICS Certification Investment | Accelerates varietal registration timelines for domestic breeders competing against import-dependent rivals. |
| Backward Integration into Multiplication | Captures margin compression from quarantine delays at Manzanillo and Lázaro Cárdenas ports. |
| Direct Supply Contracting | Bypasses distributor networks consolidating around San Quintín Valley greenhouse operators. |
| Gene-Edited Germplasm Pipeline | Positions ahead of SADER regulatory clarity on CRISPR-derived trait classification. |
| Altitude-Graded Portfolio Development | Addresses thermal zone diversity across Guanajuato-to-Mexico City elevation gradients. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with vegetable seed breeding directors, SADER regulatory affairs officers, protected agriculture operations managers, and agricultural cooperative procurement leads; and secondary validation through SNICS varietal registration databases, SADER phytosanitary clearance records, OECD seed certification standards, and customs germplasm import documentation. Bottom-up acreage and seeding rate estimates from Jalisco, Sinaloa, and Baja California production zones were triangulated against top-down breeder shipment data.
Across the analysis window, the forecasting framework modeled volume and value trajectories by seed type, crop category, distribution channel, and end-user segment, with additional granularity for altitude-adapted germplasm requirements. CAGRs were derived from trend extrapolation of protected agriculture conversion rates, SNICS certification velocity, and SADER import policy evolution. Industry-specific inputs included greenhouse operator expansion plans, INIFAP breeding pipeline disclosures, and EU-equivalent organic certification adoption curves.
Forecasts assume regulatory continuity in SADER phytosanitary protocols and Federal Law on Plant Health enforcement; material policy shifts on gene-edited vegetable classification or import germplasm restrictions would require re-modeling. Practitioners should keep alternative scenarios live as biosafety deliberation timelines and protected agriculture investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South Africa Forage Seed Market
Seeds
Spain Forage Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
India Vegetable Seed Market
Seeds
North America Seeds Market
Seeds
India Seed Market
Seeds
Brazil Forage Seed Market
Seeds
Mustard Seeds Market
Seeds
Pigeon Pea Market
Seeds
Africa Grain Seed Market
Seeds
Myanmar Rice Seed Market
Seeds
Carrot Seed Oil Market
Seeds
Fruit Seed Waste Market
Seeds
Philippines Rice Seed Market
Seeds
Myanmar Maize Seed Market